
 Smart Gas Market | 2026-2036
Smart Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Gas Market Outlook
Subscription-based meter-data-management software is shifting how vendors monetize smart gas infrastructure. Itron leverages its SaaS platform to lock in recurring revenue from North American utilities. Honeywell International Inc. anchors its position through deep manufacturing scale across electromechanical and digital metering portfolios. Landis+Gyr competes by specializing in dual-fuel AMI architectures that bridge gas and electric networks.
Smart gas systems combine advanced metering infrastructure, leak detection sensors, and cloud-native analytics platforms to monitor pipeline integrity, consumption patterns, and safety thresholds in real time; these systems typically operate across sub-GHz wireless meshes or cellular LPWAN protocols with pressure ratings up to 100 bar for transmission-grade deployments. The utilities end-user segment dominates installed base economics due to regulatory-driven replacement cycles, while IoT-enabled leak detection represents the fastest-growing product category as methane-emission accountability tightens across industrial corridors. Cloud computing infrastructure underpins margin expansion by reducing on-premise hardware dependency and enabling remote firmware updates across dispersed meter populations.
The EPA enforces methane performance standards for oil and gas facilities, compelling operators to deploy continuous emissions monitoring tied to smart sensor networks. EU F-Gas Regulation and national methane action plans across member states mandate granular leakage reporting that directly drives AMI procurement specifications. Stakeholders must weigh interoperability standards against vendor lock-in risks as utility procurement shifts toward outcome-based service contracts rather than capital-hardware purchases.
Market Dynamics
AMI deployment cycles are compressing as utilities face overlapping mandates from the EPA's methane performance standards and the EU F-Gas Regulation, forcing simultaneous infrastructure replacement and emissions accountability investments.
Growth Catalysts
- EU methane action plans:Member states now mandate granular leakage reporting that directly specifies AMI procurement requirements, accelerating meter replacement timelines across Germany, France, and Italy.
- Cloud-native analytics platforms:These systems enable remote firmware management and predictive maintenance, reducing field service costs for utilities managing dispersed meter populations.
- Industrial corridor monitoring:Refineries and chemical clusters in Texas, Louisiana, and Rotterdam are deploying continuous emissions monitoring tied to smart sensor networks under tightening accountability frameworks.
Market Restraints
- Sub-GHz wireless spectrum congestion:Dense urban deployments in Tokyo and Seoul face interference constraints that limit mesh network scalability.
- Cellular LPWAN module supply concentration:Narrowband-IoT chip fabrication concentrates among three East Asian foundries, exposing procurement timelines to geopolitical disruption.
- Legacy electromechanical meter residual value:Utilities in Poland and Hungary face stranded asset calculations that delay full AMI conversion despite regulatory deadlines.
Strategic Opportunities
- Hydrogen blend compatibility:Germany's H2-readiness mandates for distribution networks create demand for next-generation meters capable of handling variable gas compositions.
- Dual-fuel AMI architectures:Convergence of gas and electric metering on unified communication backbones opens cross-utility procurement consolidation in deregulated markets like the United Kingdom.
- Subscription-based meter-data-management:SaaS platforms shift vendor economics from hardware margins to recurring revenue streams, penetrating mid-sized municipal utilities previously priced out of capital-intensive deployments.
Industry Challenges
- Cybersecurity certification timelines:IEC 62351 compliance for utility-grade communication protocols adds 8-14 months to product launch schedules.
- Interoperability testing fragmentation:Divergent national standards between France's Linky specification and Italy's Open Meter create redundant engineering burdens for multi-country vendors.
- Field technician skill gaps:Electromechanical meter repair expertise dominates utility workforces, creating retraining bottlenecks for digital-first AMI maintenance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Gas Market |
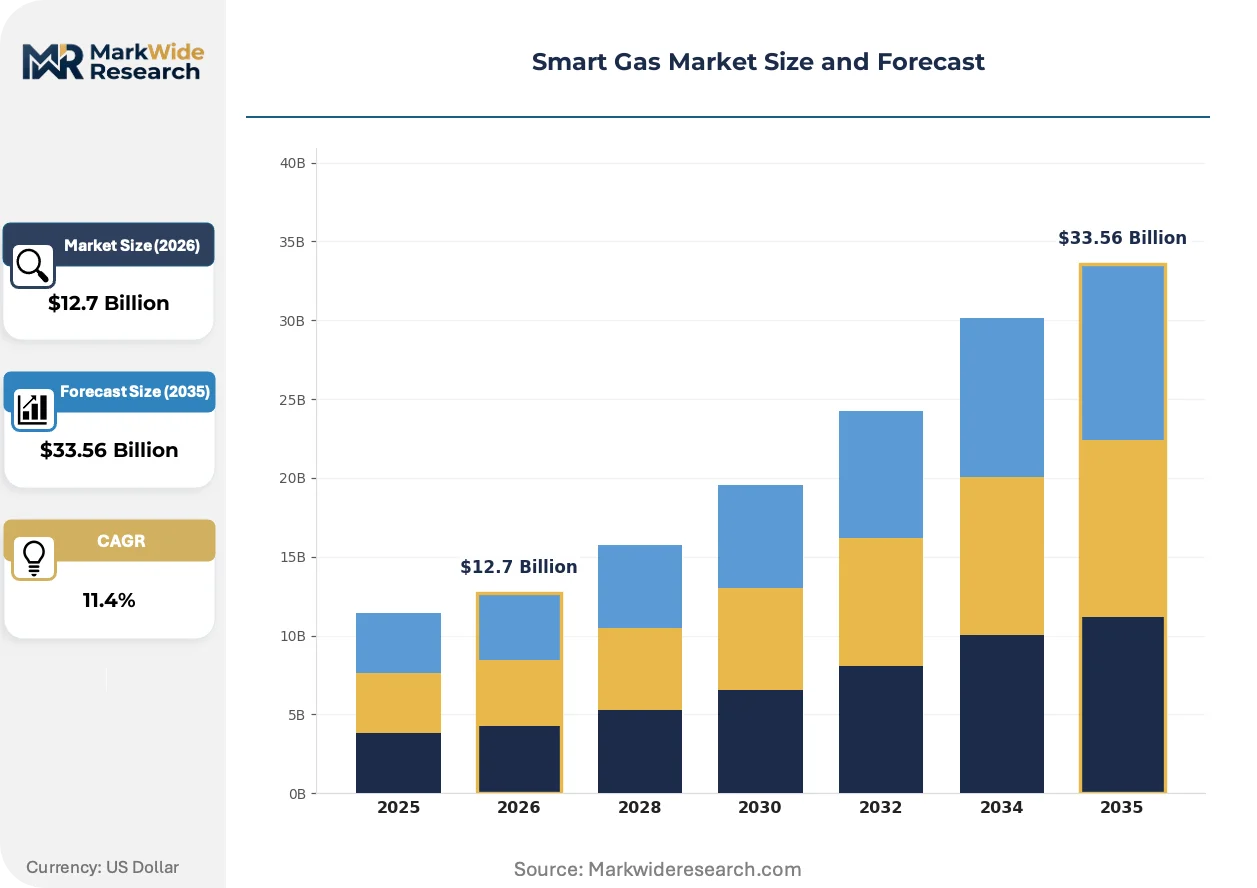
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Leak Detectors, Flow Sensors, Pressure Sensors Technology: IoT, Wireless Communication, Cloud Computing, Data Analytics End User: Utilities, Industrial, Commercial, Residential Installation: Onshore, Offshore, Retrofit, New Build |
| Companies Covered | Itron, Diehl Stiftung & Co. KG, Honeywell International Inc., ABB Group, Landis+Gyr, Apator S.A., General Electric Company, Elster Group SE, Aclara Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Gas Market Strategic Shifts
Edge computing migration is redistributing analytics workloads from centralized clouds to meter-level processors, enabling real-time leak detection without backhaul latency. This architectural shift is compressing response times for safety-critical applications.
Ultrasonic metering technology is modularizing gas measurement systems into standardized subassemblies. Distribution utilities in Japan and South Korea are adopting these platforms for accelerated field deployment. The technology is modularizing supply chains by decoupling sensor manufacturing from communication module integration.
The EPA's methane performance standards now require quarterly optical gas imaging surveys supplemented by continuous monitoring systems. Oil and gas facility operators must integrate smart sensor networks with emissions reporting infrastructure. Midstream pipeline operators in the Permian Basin and Appalachian shale regions are prioritizing procurement of certified monitoring equipment to avoid penalty structures.
Utility procurement departments are consolidating vendor relationships under outcome-based service contracts that tie payments to meter uptime and data accuracy metrics. Hardware suppliers face margin compression as buyers shift risk to vendors through performance guarantees. This contractual evolution is most advanced in the United Kingdom and Netherlands where regulatory frameworks explicitly favor service-based utility models.
Smart Gas Market Segmentation
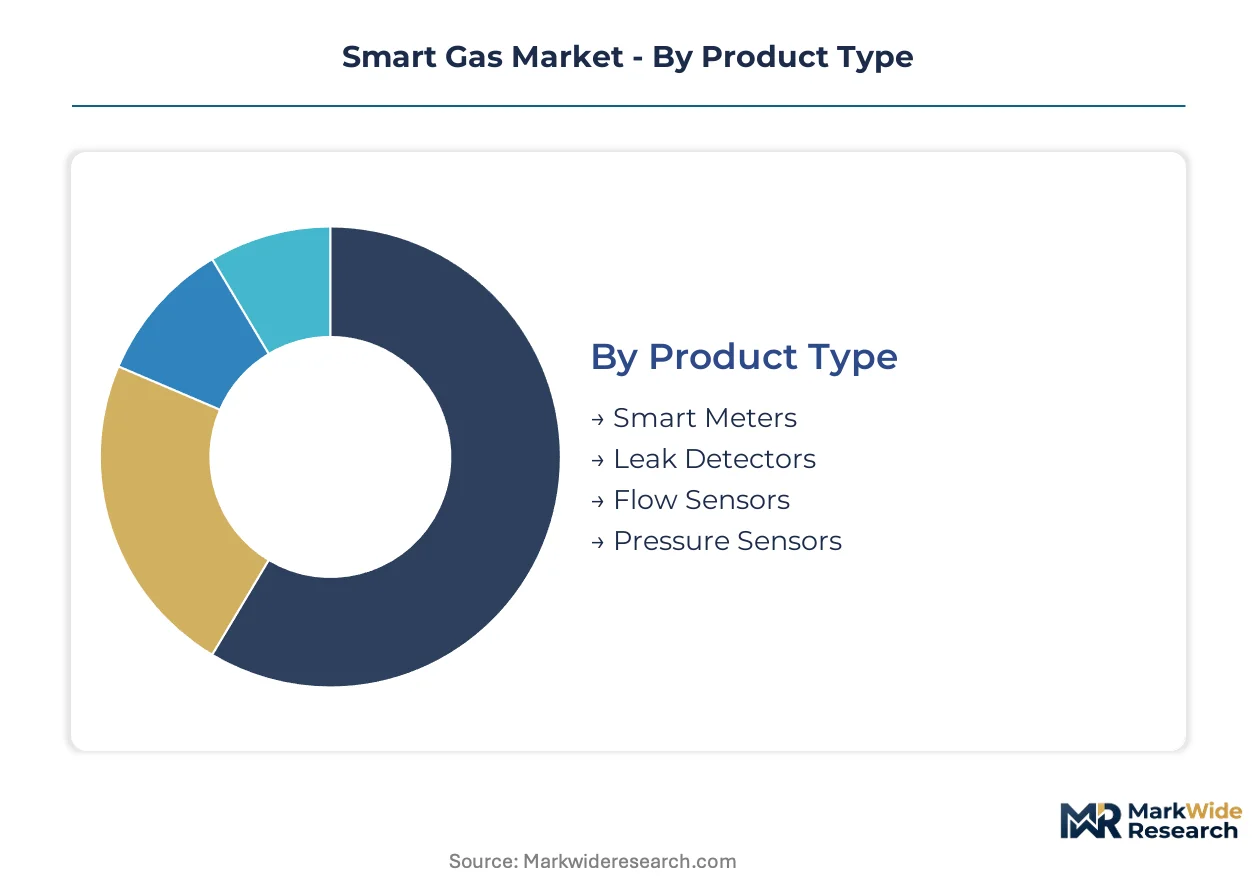
Smart gas infrastructure procurement varies sharply by deployment context, with regulatory mandates dictating certification requirements and technology choices across meter types, communication protocols, and installation environments. Understanding these segment boundaries enables vendors to align R&D investment with the compliance burdens and performance specifications that dominate customer decision criteria.
Product Type:
IEC 62351 cybersecurity certification applies universally to communication-enabled devices, while ATEX/IECEx explosion protection ratings separate hazardous-zone equipment from standard commercial meters. Pressure-rated enclosures for transmission-grade deployments carry additional ASME certification requirements.
- Smart Meters:Advanced metering infrastructure devices integrate metrology, wireless communication modules, and edge processors in sealed housings rated for 100 bar pressure in transmission networks. Utilities in Germany and the United States dominate procurement volumes under EU methane action plans and EPA methane performance standards that mandate granular consumption reporting and remote disconnect capability.
- Leak Detectors:Optical gas imaging and semiconductor-based sensors provide continuous emissions monitoring with detection thresholds measured in parts per million. Industrial corridor operators in Texas, Louisiana, and Rotterdam deploy these systems to satisfy tightening accountability frameworks for methane emissions from refineries and chemical clusters.
- Flow Sensors:Ultrasonic and thermal mass flow measurement devices for custody transfer applications.
- Pressure Sensors:Piezoelectric and strain-gauge transducers monitoring pipeline integrity in distribution networks.
Leading the category by volume: Smart Meters. Growing fastest: Leak Detectors.
Technology:
Cost tiers separate capital-intensive hardware deployments from recurring SaaS expenditures, with cloud-native platforms commanding premium pricing against on-premise legacy systems.
- IoT:Sensor networks combining sub-GHz wireless meshes and cellular LPWAN protocols enable real-time data transmission from dispersed meter populations. Narrowband-IoT module supply concentrates among East Asian foundries, exposing procurement timelines to geopolitical disruption risks.
- Wireless Communication:Mesh network architectures face spectrum congestion constraints in dense urban deployments across Tokyo and Seoul.
- Cloud Computing:Remote firmware management and predictive maintenance platforms reduce field service costs for utilities managing geographically dispersed infrastructure.
- Data Analytics:Consumption pattern analysis and anomaly detection algorithms supporting demand forecasting and theft identification.
Most mature deployment: Wireless Communication. Steepest expansion trajectory: Cloud Computing.
End User:
Application requirements diverge between regulated utilities with mandated replacement cycles and industrial operators pursuing voluntary emissions reductions.
- Utilities:Regulated distribution companies operating under state-level decarbonization mandates and federal methane performance standards. AMI procurement specifications in North America and Europe explicitly require interoperability with existing billing systems and outage management platforms.
- Industrial:Refineries, chemical plants, and midstream pipeline operators deploying continuous emissions monitoring to avoid penalty structures under tightening accountability frameworks.
- Commercial:Multi-building property managers and district heating operators seeking submetering granularity for tenant billing.
- Residential:Single-family homeowners and small multi-unit buildings with basic consumption monitoring requirements.
Dominant procurement volume: Utilities. Climbing the fastest: Industrial.
Installation:
Customer type segmentation reveals divergent risk appetites, with municipal utilities favoring proven retrofit solutions while private infrastructure investors speculatively deploy new-build hydrogen-ready systems.
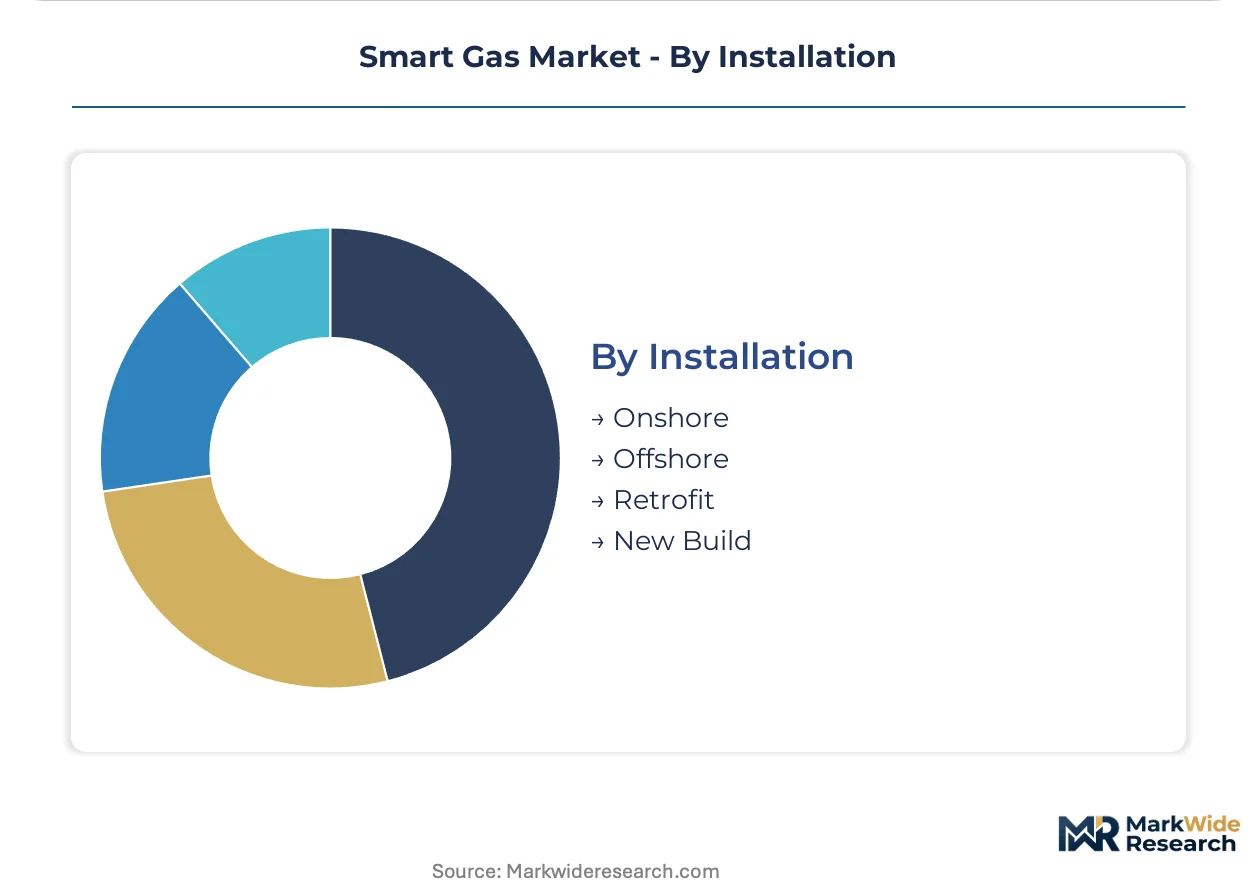
- Onshore:Pipeline and distribution network deployments across terrestrial infrastructure in Germany, the United States, and Japan. Modernization budgets in these markets favor phased retrofit programs that minimize service disruption.
- Offshore:Platform and subsea pipeline monitoring systems for oil and gas production facilities.
- Retrofit:Replacement of legacy electromechanical meters with AMI-capable digital units. Utilities in Poland and Hungary face stranded asset calculations that delay full conversion despite regulatory deadlines.
- New Build:Greenfield installations incorporating hydrogen blend compatibility and unified communication backbones for dual-fuel architectures.
Highest volume segment: Retrofit. Gaining share fastest: New Build.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's chemical corridor drives European smart gas deployment through continuous emissions monitoring mandates at refineries and storage terminals. Industrial clusters in this region anchor procurement volumes for leak detection systems and AMI infrastructure under tightening methane accountability frameworks.
United States
Texas and Louisiana refineries deploy continuous monitoring networks under EPA methane performance standards that mandate quarterly optical gas imaging surveys. The Permian Basin and Appalachian shale regions prioritize certified equipment procurement to avoid federal penalty structures. Midstream operators in Houston anchor demand for pressure-rated transmission-grade metering systems.
Germany
Ruhr industrial complexes and Bavarian distribution utilities accelerate AMI replacement under EU methane action plans requiring granular leakage reporting. The country's national regulator specifies interoperability standards that shape procurement specifications for dual-fuel architectures. Hydrogen blend compatibility mandates in North Rhine-Westphalia drive next-generation meter development.
Japan
Tokyo Gas and Osaka metropolitan utilities face sub-GHz wireless spectrum congestion that constrains dense urban mesh network scalability. METI efficiency standards push ultrasonic metering adoption for accelerated field deployment. The Kanto region's pipeline modernization budgets favor modular subassembly platforms that decouple sensor manufacturing from communication integration.
United Kingdom
Distribution network operators consolidate vendor relationships under outcome-based service contracts tied to meter uptime metrics. The national regulatory framework explicitly favors service-based utility models over capital-hardware purchases. Deregulated market structures enable cross-utility procurement consolidation for unified communication backbones spanning gas and electric networks.
Netherlands
Port of Rotterdam chemical clusters deploy smart sensor networks to satisfy EU F-Gas Regulation accountability requirements for refineries and storage terminals. The national gas grid operator specifies cloud-native analytics platforms that enable remote firmware management across dispersed infrastructure. Amsterdam's municipal utility pilots hydrogen-ready new-build installations with dual-fuel AMI architectures.
Smart Gas Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the smart gas value chain, creating a tiered structure where electromechanical manufacturers face margin pressure from software-centric entrants. The market consolidates around three strategic archetypes: diversified industrial conglomerates with deep manufacturing scale, specialized metering pure-plays with dual-fuel expertise, and SaaS-platform vendors capturing recurring revenue from data management services. Dominant competitive moves include strategic partnerships between meter manufacturers and cloud infrastructure providers, plus portfolio diversification into hydrogen-compatible next-generation systems.
Within the diversified industrial tier, Honeywell International Inc. and ABB Group occupy positions anchored by electromechanical legacy and digital transformation capabilities. Landis+Gyr exemplifies the specialized metering archetype through its focus on unified communication backbones. Itron represents the SaaS-platform vector, shifting vendor economics toward subscription-based meter-data-management revenue streams that penetrate mid-sized municipal utilities previously priced out of capital-intensive deployments.
| Leading Market Players |
|---|
| Itron |
| Diehl Stiftung & Co. KG |
| Honeywell International Inc. |
| ABB Group |
| Landis+Gyr |
| Apator S.A. |
| General Electric Company |
| Elster Group SE |
| Aclara Technologies LLC |
| Others |
Value Chain & Pricing Dynamics
Backward integration into narrowband-IoT chip fabrication anchors supply positions for East Asian foundries while simultaneously compressing hardware margins for Western meter vendors competing on recurring SaaS revenue streams. This integration choice concentrates pricing power among semiconductor suppliers and forces meter manufacturers toward subscription-based monetization to defend profitability.
Pricing Analysis
Margin tightening in hardware tiers reflects the shift from capital-intensive AMI deployments to outcome-based service contracts that transfer uptime risk to vendors. Three-tier pricing structure across premium-certified, standard-compliant, and economy retrofit levels separates IEC 62351-validated units from basic commercial meters. Cost-down pressure on transmission-grade enclosures accelerates because ASME certification requirements add fixed compliance burdens regardless of production scale. Municipal utilities exhibit highest price sensitivity due to constrained capital budgets, while midstream operators in shale corridors demonstrate lowest sensitivity given penalty avoidance incentives.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for pressure-rated meter assemblies and leak detection sensors. Component manufacturing concentrates in Germany, Japan, and South Korea for ultrasonic metrology subassemblies. Raw material dependencies span piezoelectric ceramics, strain-gauge alloys, and explosion-proof enclosure polymers. Single-source vulnerability concentrates in narrowband-IoT module fabrication. Distribution runs through utility-direct procurement channels and specialized energy infrastructure distributors serving industrial corridor operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart gas infrastructure is transitioning from electromechanical metering to cloud-native AMI platforms with edge-computing capabilities, compressing replacement cycles and reshaping vendor economics across the value chain.
For Market Incumbents: Deepen SaaS platform penetration among mid-sized municipal utilities previously priced out of capital-intensive deployments to offset hardware margin compression. Accelerate IEC 62351 certification pipelines to reduce the 8-14 month compliance delays that cede first-mover advantage to specialized metering pure-plays. Prioritize hydrogen blend compatibility R&D to capture Germany's H2-readiness procurement mandates before regulatory specifications harden.
For New Entrants and Emerging Players: Enter via leak detection sensor networks for industrial corridor operators in Texas, Louisiana, and Rotterdam where tightening methane accountability frameworks create procurement urgency absent incumbent relationships. Target midstream pipeline operators in the Permian Basin and Appalachian shale regions with continuous emissions monitoring solutions that satisfy EPA quarterly optical gas imaging supplement requirements. Deploy cloud-native analytics platforms through outcome-based service contracts that bypass capital-budget constraints.
For Investors and Strategic Acquirers: Exit pathways concentrate in SaaS-platform acquisitions by diversified industrial conglomerates seeking recurring revenue streams and dual-fuel AMI expertise. Long-term viability favors vendors with unified communication backbone capabilities spanning gas and electric networks. Acquisition target archetype: specialized metering pure-plays with hydrogen-compatible product pipelines and established utility procurement relationships. Watch for inflection when EU member states publish granular methane leakage reporting specifications that trigger accelerated AMI replacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies gas and electric metering on single communication backbone for UK deregulated markets. |
| Strategic Partnership | Cloud infrastructure alliances enable remote firmware management across dispersed meter populations. |
| Acquisition of Specialist Firm | Leak detection sensor expertise addresses fastest-growing product category under tightening methane regulations. |
| Geographic Expansion | Hydrogen-ready meter deployment captures Germany's North Rhine-Westphalia blend compatibility mandates. |
| Product Launch | Ultrasonic modular subassemblies accelerate field deployment for Tokyo Gas and Osaka metropolitan utilities. |
Study Parameters
Independent corroboration across utility planning officers, AMI procurement managers, and industrial emissions compliance leads underwrites the qualitative findings. Primary interviews with distribution network operators, midstream pipeline engineers, and smart meter R&D directors combined with secondary validation from EIA data, EPA methane performance standard filings, EU F-Gas Regulation implementation reports, and IEA energy infrastructure databases. Bottom-up meter deployment tracking and top-down regulatory mandate analysis triangulate market sizing.
Comparable-period anchoring to historical AMI replacement cycles and industrial emissions monitoring adoption patterns structures the forecast window. Segmentation dimensions span product type, communication protocol, end-user category, and installation environment across the projection horizon. CAGRs derive from utility capital expenditure trajectories, regulatory compliance deadlines, and technology substitution rates. Forecast inputs include narrowband-IoT module supply constraints and hydrogen infrastructure rollout timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption to East Asian semiconductor fabrication and accelerated EU methane action plan implementation. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and utility procurement cycle timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Storage Tank Market
Fuels
LPG Gas Cylinder Market
Fuels
LPG Vaporizer Market
Fuels
Chafing Fuel Market
Fuels
Oil Dispensing Stations Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Hybrid Propellants Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Canada Coal Market
Fuels
South America Aviation Fuel Market
Fuels
Bituminous Coal Market
Fuels
Global Wood Gas Generator Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Canada Bunker Fuel Market
Fuels
Pyrolysis Gas Market
Fuels
Brazil Bunker Fuel Market