
 Asia-Pacific Weight Management Supplement Market | 2026-2036
Asia-Pacific Weight Management Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Weight Management Supplement Market Outlook
Chinese contract manufacturers is pivoting toward cGMP-certified facilities to serve both domestic brands and export orders across Southeast Asia. Amway Corp leverages its direct-selling infrastructure to sustain penetration in tier-two Chinese cities. Glanbia PLC anchors its position through specialized dairy-protein formulations tailored to Asian digestive tolerances. Herbalife Nutrition Ltd. competes via nutrition-club distribution models that control last-mile engagement in India and Indonesia.
Asia-Pacific weight management supplements encompass orally administered formulations containing thermogenic compounds, soluble fibers, or macro-nutrient isolates designed to modulate energy expenditure, satiety signaling, or substrate metabolism. Manufacturing employs spray-drying for protein encapsulation and cold-pressing for herbal extract preservation to maintain bioactive stability through shelf life. Pills and powders occupy the largest volume share due to dose precision and stackability with existing fitness regimens, while gels are gaining fastest among convenience-seeking urban commuters. Online retail channels capture expanding margin pools as live-stream commerce and subscription models displace traditional pharmacy distribution across China and South Korea.
FSSAI in India mandates stringent label disclosures for ayurvedic-herbal weight-loss claims, while TGA-equivalent frameworks in Australia enforce batch-testing for stimulant adulterants. China's SAMR requires blue-hat registration for all functional weight-management products, creating a two-tier market of compliant premium brands and unregistered gray-market imports. Stakeholders must monitor evolving ASEAN harmonization talks on supplement GMP standards, as regulatory misalignment currently fragments cross-border e-commerce fulfillment.
Market Dynamics
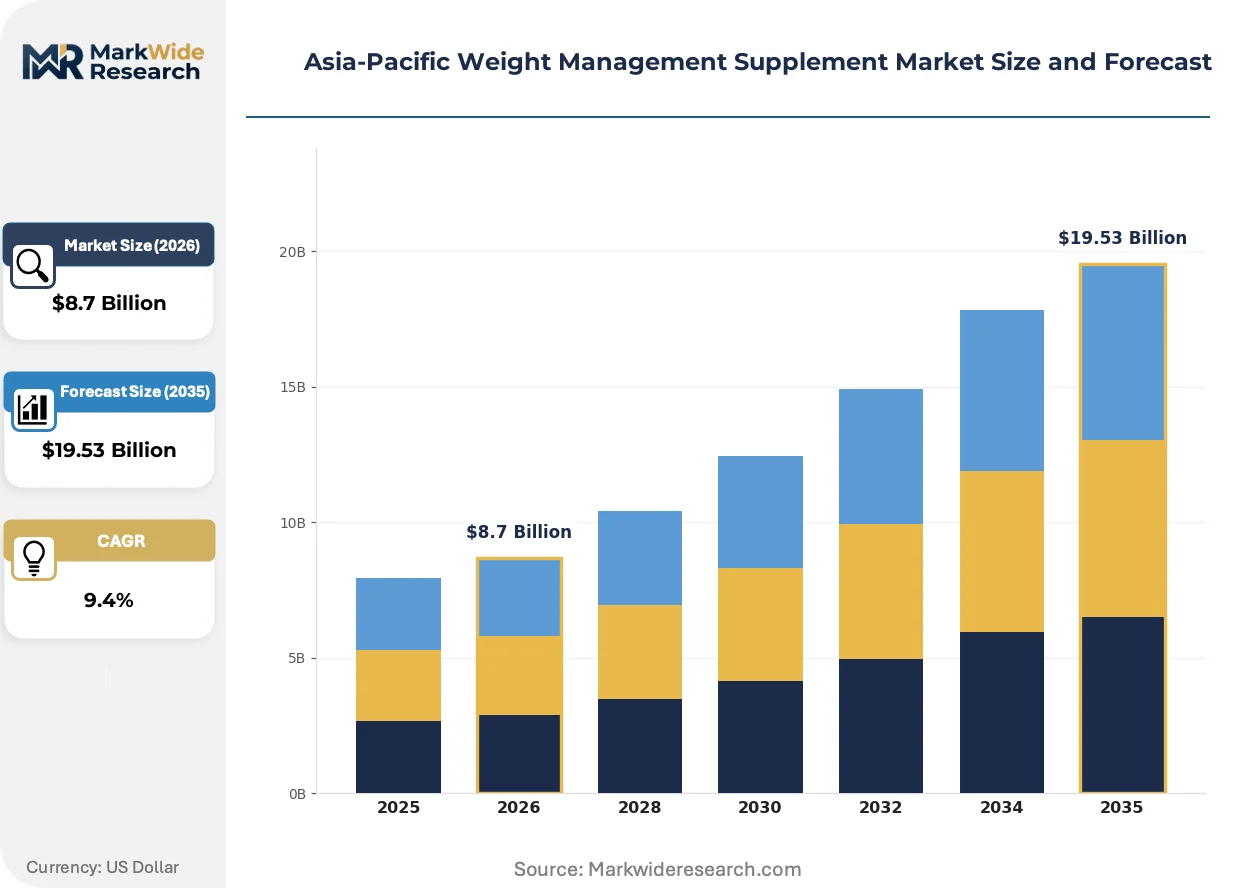
China's SAMR blue-hat registration mandate is bifurcating the Asia-Pacific weight management supplement market into compliant premium tiers and unregistered gray-market channels, forcing manufacturers to rebuild supply chains around certified cGMP infrastructure.
Growth Catalysts
- Live-stream commerce penetration:Chinese and South Korean platforms now convert fitness influencers directly into distribution nodes, collapsing traditional pharmacy margins and accelerating subscriber acquisition in tier-two urban clusters.
- FSSAI disclosure standardization:India's tightening label requirements for ayurvedic-herbal claims are professionalizing domestic manufacturing, pushing organized players toward export-grade documentation that unlocks Southeast Asian cross-border sales.
- Gym culture densification:Urban fitness center expansion across Jakarta, Bangkok, and Ho Chi Minh City is creating captive consumption environments where stackable powder formats dominate pre-workout and meal-replacement occasions.
Market Restraints
- Whey protein import dependency:Southeast Asian brands remain tethered to Australian and New Zealand dairy protein supply, exposing margin structures to ocean freight volatility and currency fluctuation.
- SAMR registration backlog:China's functional food approval queue now stretches 18-24 months for novel weight-management ingredients, freezing innovation pipelines for domestic startups without existing blue-hat portfolios.
- Stimulant adulterant detection:TGA-equivalent batch-testing protocols in Australia and emerging ASEAN harmonization talks are raising QC costs for thermogenic formulations containing caffeine analogs or herbal alkaloids.
Strategic Opportunities
- Vietnam e-commerce infrastructure:Underdeveloped last-mile fulfillment in secondary Vietnamese cities creates first-mover advantage for brands building localized warehousing ahead of regional GMP standardization.
- Subscription model automation:AI-driven replenishment algorithms tied to wearable biometric data are emerging in South Korea, enabling brands to capture recurring revenue through personalized dosing protocols.
- PLI scheme alignment:India's production-linked incentive frameworks for pharmaceutical and nutraceutical manufacturing offer capital subsidy pathways for domestic contract manufacturers scaling cGMP tablet and capsule lines.
Industry Challenges
- Dual-formulation talent scarcity:The intersection of traditional Chinese medicine extraction science and Western clinical trial design lacks trained formulators, slowing hybrid product development for brands targeting both regulatory pathways.
- Cold-chain gel preservation:Convenience-format hydrocolloid gels require refrigerated distribution infrastructure that remains fragmented across Indonesian archipelago logistics, limiting shelf-stable formulation innovation.
- Cross-border customs harmonization:Divergent ASEAN member state classifications for weight-management supplements versus functional foods create clearance delays and duty uncertainty for centralized fulfillment hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Weight Management Supplement Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Powders, Gels, Chewables Ingredient Type: Herbal Extracts, Protein, Fiber, Vitamins Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores Customer Type: Fitness Enthusiasts, Weight Watchers, Health-Conscious Consumers, Athletes |
| Companies Covered | Amway Corp, NU SKIN, Abbott Laboratories, Pfizer Inc., Bayer AG, Herbalife Nutrition Ltd., Glanbia PLC, Archer Daniels Midland, Nestlé SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Weight Management Supplement Market Strategic Shifts
Spray-drying and microencapsulation advances are reshaping bioactive stability standards, while regulatory digitization and direct-to-consumer channel migration are compressing traditional wholesale hierarchies across the region.
Microencapsulation technology using lipid-shell matrices is unifying thermogenic compound delivery with taste-masking functionality, enabling bitter alkaloid inclusion in ready-to-mix beverages. Premium Chinese fitness brands are adopting these systems at scale to differentiate from commodity powder competitors. The technology is unifying formerly separate processing steps—stabilization, flavor engineering, and controlled release—into single-unit operations that reduce CoGS for mid-tier manufacturers.
China's evolving GB standards for functional food claims are tightening evidentiary requirements for weight-management efficacy assertions, forcing reformulation toward ingredients with existing clinical dossiers. Domestic brands now prioritize whey protein isolates and soluble fibers over novel botanical extracts to secure faster SAMR approvals. The policy shift most impacts entrepreneurial entrants lacking legacy registration portfolios, who are pivoting toward contract manufacturing partnerships with established blue-hat holders.
Biometric-integrated purchasing is displacing static subscription models as South Korean consumers link wearable devices to auto-replenishment platforms. Fitness apps now trigger supplement reorders based on actual caloric expenditure and body-composition trends rather than fixed calendar cycles. This behavioral shift concentrates highest adoption in Seoul and Busan metropolitan corridors where smart-device penetration intersects with boutique studio membership density.
Asia-Pacific Weight Management Supplement Market Segmentation
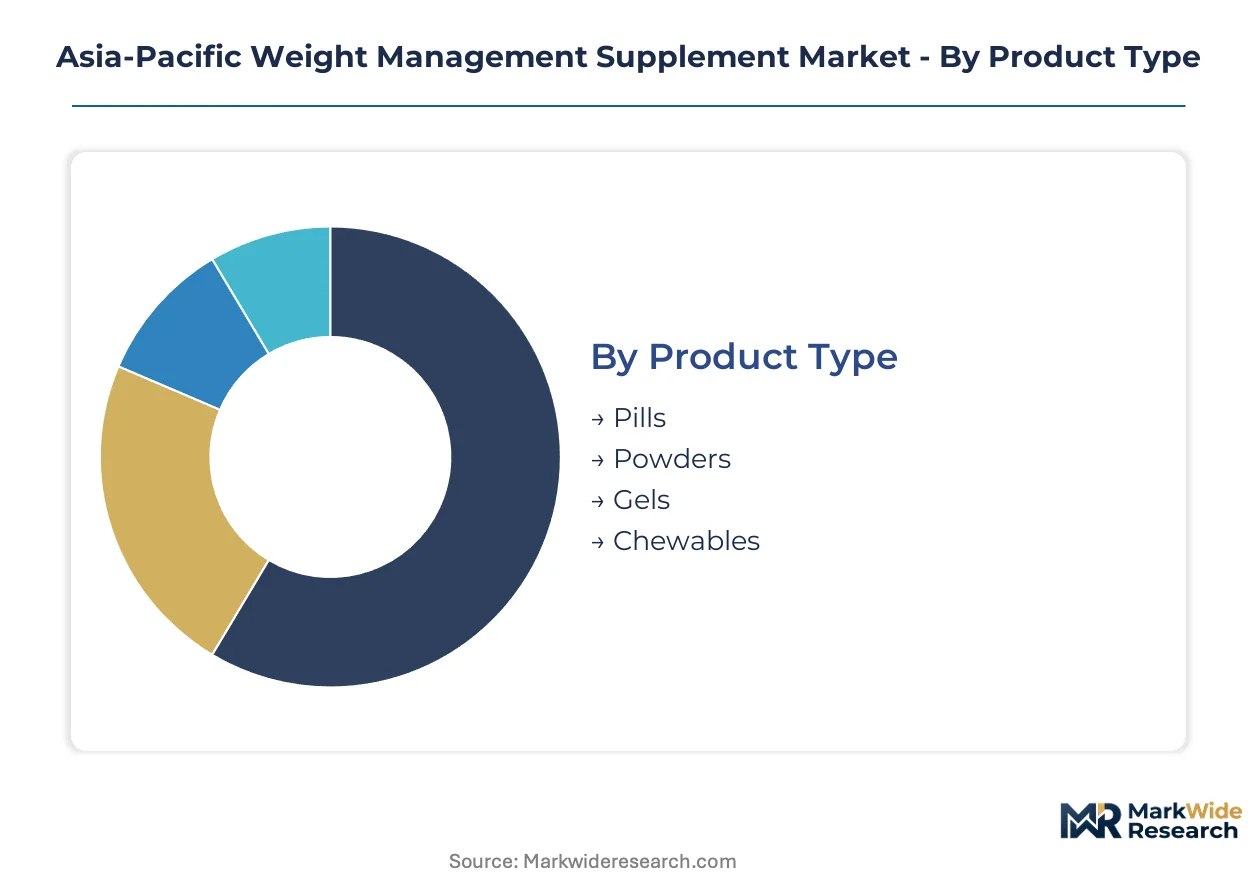
Product formats and distribution pathways in Asia-Pacific weight management supplements reflect divergent consumer integration behaviors. Some segments function as standalone purchase decisions while others embed within broader fitness or dietary routines.
Product Type:
Standalone formats dominate direct-to-consumer channels, while embedded systems integrate with gym protocols or meal-planning apps.
- Pills:Compressed tablet formulations deliver precise dosing of thermogenic compounds and soluble fibers. Demand concentrates in China's tier-one cities where SAMR blue-hat registration signals quality assurance to skeptical urban professionals. The format suits commuters seeking portable, no-preparation consumption.
- Powders:Macro-nutrient isolates and protein blends require reconstitution but enable stackable dosing with pre-workout regimens. Gym culture densification across Jakarta, Bangkok, and Ho Chi Minh City drives bulk purchasing through fitness center retail nodes. Spray-dried encapsulation preserves bioactive stability through humid supply chains.
- Gels:Hydrocolloid matrices offer convenience without water requirements, though cold-chain preservation limits Indonesian archipelago penetration.
- Chewables:Palatable formats target entry-level consumers transitioning from confectionery habits to functional nutrition.
Powders lead volumes today; gels are gaining share fastest.
Ingredient Type:
Cost tiers separate premium clinically-validated inputs from commodity botanical sourcing.
- Protein:Whey isolates and plant-based alternatives anchor meal-replacement formulations. Southeast Asian brands remain import-dependent on Australian and New Zealand dairy protein, exposing margins to freight volatility and currency fluctuation.
- Herbal Extracts:Traditional Chinese medicine-derived thermogenics face tightening evidentiary requirements under evolving GB standards. Domestic Chinese brands now prioritize extracts with existing clinical dossiers to secure faster SAMR approvals.
- Fiber:Soluble variants modulate satiety signaling with lower regulatory burden than stimulant compounds.
- Vitamins:Micronutrient fortification addresses deficiency-correction positioning in India's FSSAI-regulated market.
Protein commands the premium tier; fiber is expanding most quickly among cost-sensitive segments.
Distribution Channel:
Channel selection determines margin capture versus reach trade-offs across urban density gradients.
- Online Retail:Live-stream commerce platforms in China and South Korea convert fitness influencers into distribution nodes, collapsing traditional pharmacy margins. Subscription algorithms tied to wearable biometric data now automate replenishment in Seoul and Busan.
- Supermarkets:Mass-market penetration depends on shelf-stable formulations with extended humidity tolerance for tropical storage conditions.
- Pharmacies:Professional recommendation channels retain importance for first-time purchasers seeking clinical credibility.
- Health Stores:Specialty retail captures enthusiast segments willing to pay premium for stackable, full-spectrum formulations.
Online retail leads transaction volume; health stores show the steepest expansion trajectory.
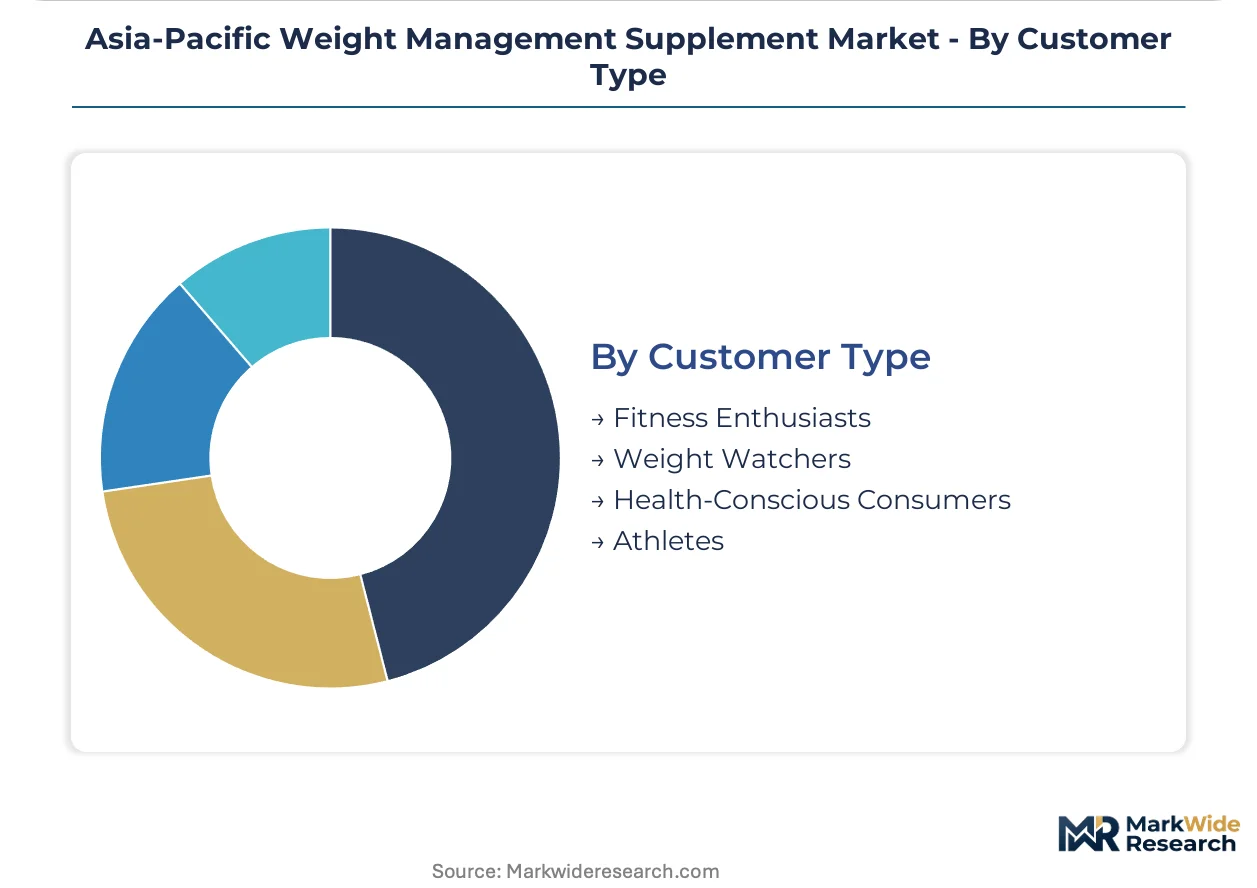
Customer Type:
Application intensity separates casual lifestyle adopters from performance-optimized protocols.
- Fitness Enthusiasts:Stackable powder consumers drive pre-workout and meal-replacement occasions through gym-affiliated purchasing. This cohort shows highest subscription conversion rates and lowest price elasticity.
- Athletes:Competition-tested formulations require batch-certified purity under TGA-equivalent protocols, constraining supplier eligibility.
- Weight Watchers:Satiety-focused fiber and protein demand concentrates among urban professionals in India's metropolitan corridors.
- Health-Conscious Consumers:Preventive positioning attracts ayurvedic-herbal interest under FSSAI disclosure mandates.
Fitness enthusiasts dominate current revenue; athletes represent the fastest-climbing segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's regulatory infrastructure demands blue-hat registration for functional weight-management claims, while India relies on FSSAI disclosure mandates that professionalize ayurvedic-herbal manufacturing. Both markets anchor Asia-Pacific demand concentration, though divergent compliance pathways create asymmetric competitive entry costs.
China
Fitness enthusiasts in tier-one cities drive premium powder consumption through gym-affiliated retail nodes. SAMR blue-hat registration requirements bifurcate the market into compliant premium tiers and gray-market channels, forcing supply chain rebuilding around cGMP-certified facilities. Yangtze River Delta manufacturers pivot toward export-grade infrastructure to serve Southeast Asian orders.
India
Urban professionals in metropolitan corridors concentrate demand for satiety-focused fiber and protein formulations. FSSAI tightening of ayurvedic-herbal label disclosures pushes organized players toward export-grade documentation standards. Maharashtra and Gujarat contract manufacturers align with PLI scheme subsidies to scale tablet and capsule production lines.
South Korea
Biometric-integrated purchasing displaces static subscription models in Seoul and Busan metropolitan corridors. MFDS-equivalent frameworks govern functional food claims while wearable device penetration enables AI-driven replenishment algorithms. Domestic brands capture recurring revenue through personalized dosing protocols tied to actual caloric expenditure data.
Vietnam
Underdeveloped last-mile fulfillment in secondary cities creates first-mover advantage for localized warehousing investments. Gym culture densification across Ho Chi Minh City drives pre-workout powder consumption through fitness center retail. Brands building captive distribution infrastructure ahead of ASEAN GMP harmonization secure structural positioning advantages.
Australia
TGA-equivalent batch-testing protocols enforce stimulant adulterant detection for thermogenic formulations. Import dependency on whey protein isolates exposes margin structures to ocean freight volatility and currency fluctuation. Sydney and Melbourne health stores capture enthusiast segments willing to pay premium for stackable, competition-tested formulations.
Asia-Pacific Weight Management Supplement Market Competitive Environment
Chinese producers anchor one tier; European and North American multinationals hold premium positioning through direct-selling infrastructure. The market structures around three archetypes: cGMP-certified contract manufacturers serving dual domestic-export markets, direct-selling operators controlling last-mile engagement in tier-two urban clusters, and dairy-protein specialists leveraging digestive-tolerance formulations. Dominant competitive moves include registration portfolio accumulation to secure SAMR approval pathways and live-stream commerce platform partnerships that collapse traditional pharmacy margins.
Among direct-selling specialists, Amway Corp and Herbalife Nutrition Ltd. exemplify channel-control archetypes that convert fitness influencers into distribution nodes across tier-two Chinese cities and Indonesian nutrition-club networks. Glanbia PLC occupies a position within the dairy-protein formulation tier, anchoring supply relationships through specialized isolates tailored to Asian digestive tolerances. These three entities represent distinct competitive vectors: infrastructure-heavy direct engagement, localized last-mile penetration, and upstream ingredient specialization.
| Leading Market Players |
|---|
| Amway Corp |
| NU SKIN |
| Abbott Laboratories |
| Pfizer Inc. |
| Bayer AG |
| Herbalife Nutrition Ltd. |
| Glanbia PLC |
| Archer Daniels Midland |
| Nestlé SA |
| Others |
Value Chain & Pricing Dynamics
Spray-drying and microencapsulation technology adoption across Yangtze River Delta contract manufacturers is compressing unit economics for mid-tier powder producers while simultaneously concentrating production capacity among cGMP-certified facilities. This dual effect elevates price floors for compliant premium tiers and widens spreads against gray-market imports.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for whey protein isolates as domestic spray-drying infrastructure reduces import dependency. Three-tier pricing structure across blue-hat certified premium, export-grade standard, and unregistered economy levels reflects SAMR registration status and batch-testing documentation. Pricing pressure stems from live-stream commerce commission structures that squeeze brand margins. Fitness enthusiasts show lowest price sensitivity due to subscription lock-in, while casual weight watchers drive volume in discount channels.
Supply Chain Analysis
Ocean freight rate volatility between Australia, New Zealand, and Southeast Asian ports is destabilizing landed costs for dairy protein inputs. Raw material sourcing draws from Australian whey concentrate, New Zealand isolate, and domestic Chinese soy protein. Single-source vulnerability concentrates in Tasman Sea shipping lanes and Port of Melbourne processing hubs. Distribution runs through fitness center retail nodes in Jakarta, Bangkok, and Ho Chi Minh City, with e-commerce fulfillment centers displacing traditional pharmacy wholesalers across China and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
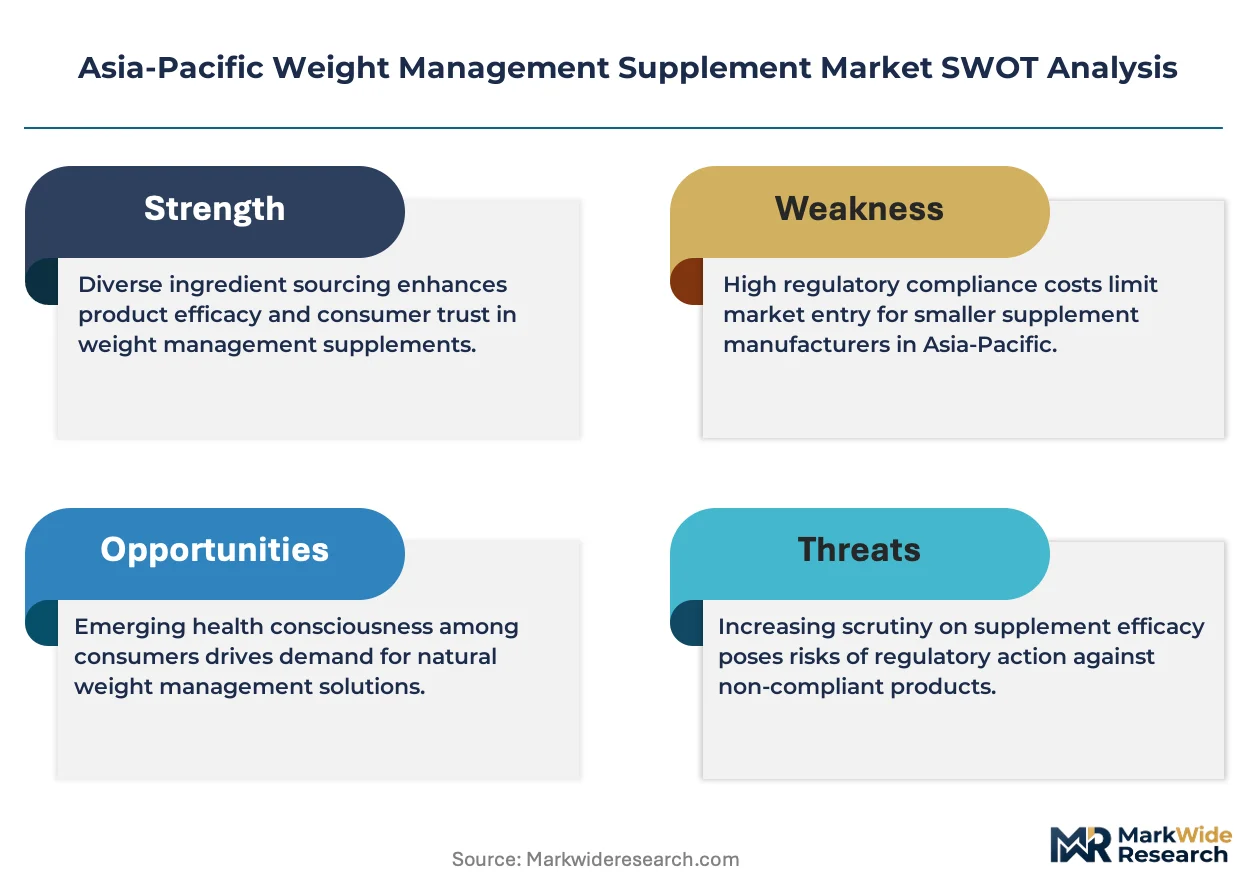
The Asia-Pacific weight management supplement market reads as a late-cycle quality story as urban consumers shift toward clinically-validated, registration-compliant formulations over commodity botanical extracts.
For Market Incumbents: To counter gray-market price erosion from unregistered imports, deepen cGMP certification coverage across Southeast Asian contract manufacturing partnerships and accumulate SAMR blue-hat registration portfolios to freeze out entrepreneurial entrants lacking approval pathways. For New Entrants and Emerging Players: Launch via live-stream commerce partnerships targeting tier-two Chinese cities and Vietnamese secondary urban clusters where localized warehousing investments precede ASEAN GMP harmonization. White-space concentration sits in biometric-integrated subscription models for South Korean fitness apps and ayurvedic-herbal formats under FSSAI disclosure mandates for Indian export documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Chinese contract manufacturers with dual domestic-export cGMP infrastructure but limited brand equity. Long-term viability favors acquisition targets with established SAMR registration pipelines and spray-drying capacity expansion. The signal to watch is MFDS-equivalent framework adoption timelines across ASEAN member states as harmonization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Certification Expansion | Blue-hat registration unlocks premium tier access in China's SAMR-regulated channels. |
| Live-Stream Commerce Partnership | Fitness influencer networks collapse traditional pharmacy margins in tier-two Chinese cities. |
| Biometric Subscription Integration | Wearable data linkage automates replenishment for Seoul and Busan metropolitan consumers. |
| ASEAN Localized Warehousing | Captive distribution infrastructure secures positioning ahead of regional GMP standardization. |
| PLI Scheme Alignment | India's production-linked incentives subsidize tablet and capsule line scaling in Maharashtra. |
Study Parameters
Coverage spans China, India, South Korea, Vietnam, and Australia, with primary inputs from each market combining interviews with contract manufacturing executives, regulatory affairs specialists at SAMR and FSSAI, fitness center procurement managers, and e-commerce platform operators. Secondary validation draws from SAMR registration databases, FSSAI disclosure filings, ASEAN trade statistics, and customs import records for whey protein isolates. Bottom-up segment sizing triangulates against top-down macroeconomic consumption indicators.
Rate-of-change decomposition separates volume growth from value expansion across product format, ingredient type, distribution channel, and customer application intensity dimensions throughout the forecast period. CAGRs derive from regression analysis against gym membership density, live-stream commerce penetration rates, and regulatory approval queue durations. Industry-specific inputs include SAMR blue-hat registration timelines and FSSAI ayurvedic-herbal disclosure compliance costs.
Several conditions sit outside the modeled scope, including abrupt SAMR regulatory reversals, ocean freight rate shocks, and ASEAN GMP harmonization delays. Forecasts reflect assumptions about continued urban fitness center expansion and wearable device adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
United States Sports Nutrition Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
China Sports Drink Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
Asia-Pacific Sports Drink Market