
 Asia-Pacific Sports Nutrition Market | 2026-2036
Asia-Pacific Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sports Nutrition Market Outlook
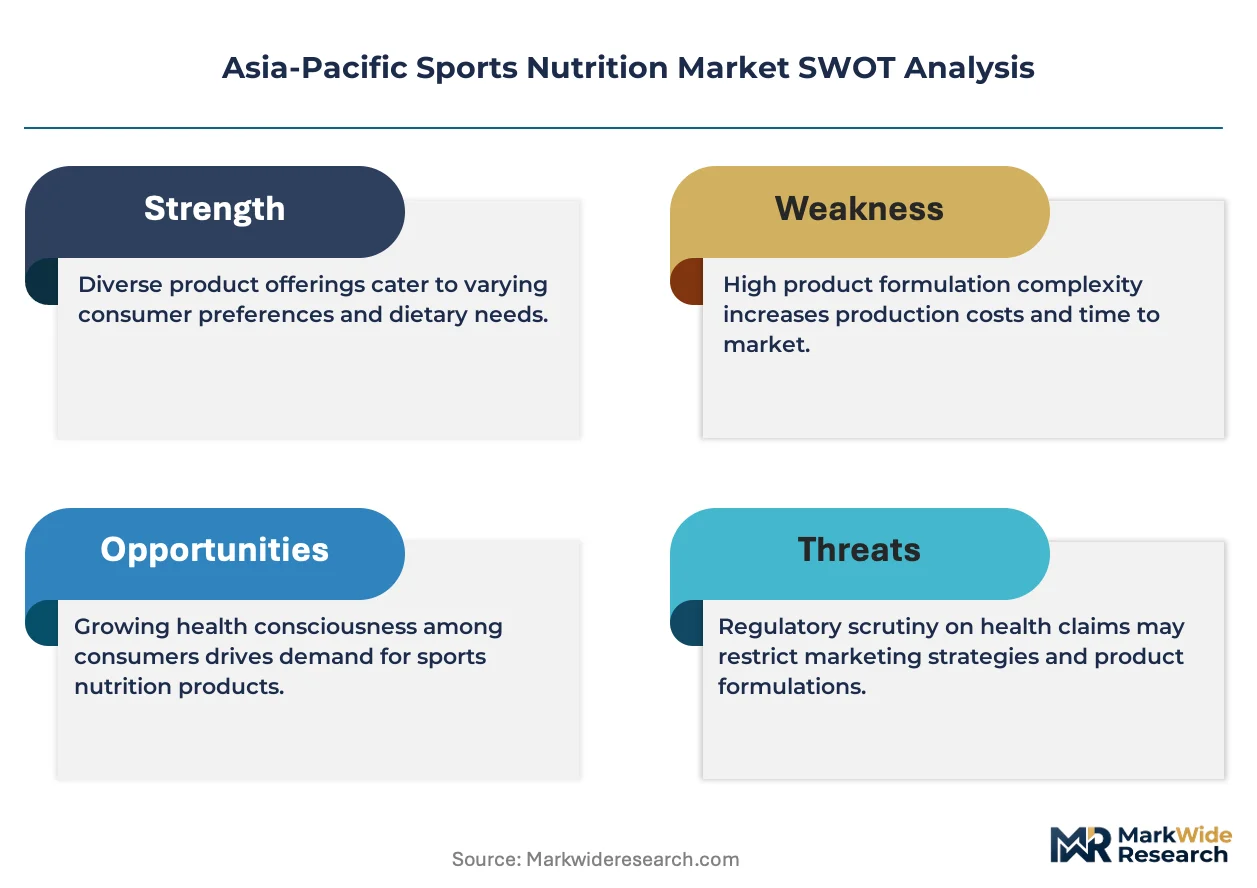
Precision fermentation and enzymatic protein processing is tilting formulation economics toward cleaner-label products with higher bioavailability. Abbott Laboratories leverages its clinical nutrition heritage to anchor premium positioning in medical-adjacent sports segments. MuscleBlaze competes aggressively on domestic sourcing and flavor localization for Indian bodybuilders. Otsuka Pharmaceutical Co. Ltd. sustains its foothold in East Asian markets through science-backed electrolyte and amino acid portfolios.
Asia-Pacific sports nutrition encompasses engineered consumables delivering macronutrients, micronutrients, and ergogenic compounds to support athletic performance, recovery, and body composition goals. These products typically feature protein concentrations ranging from 15 grams to 30 grams per serving, with formulations incorporating branched-chain amino acids, creatine monohydrate, or caffeine matrices processed through spray-drying or cold-pressed bar manufacturing. Protein Supplements dominate value pools due to repeat-purchase frequency and subscription channel penetration, while Energy Gels represent the fastest-growing product type among endurance athletes seeking portable, rapid-absorption fuel. The End User base fragments across Athletes demanding batch-tested certification and Recreational Users prioritizing taste and convenience over performance claims.
Japan's Consumer Affairs Agency enforces strict health food labeling under the Foods with Function Claims system, compelling brands to substantiate efficacy with clinical evidence. Australia's Therapeutic Goods Administration and Food Standards Australia New Zealand jointly oversee borderline sports supplements, creating compliance complexity for imported powders and capsules. India's FSSAI mandates licensing under the Food Safety and Standards Act for all protein and pre-workout products sold domestically. Stakeholders must monitor evolving cross-border e-commerce regulations, as direct-to-consumer import channels face tightening customs scrutiny across Southeast Asian markets.
Market Dynamics
Precision fermentation and enzymatic protein processing are compressing formulation costs for cleaner-label sports nutrition products across Asia-Pacific manufacturing hubs. China's updated GB standards for health food ingredient disclosure are forcing reformulation investments that reshape competitive economics for domestic and imported brands alike.
Growth Catalysts
- Professional athlete segment expansion:Competitive sports teams and elite athletes in Australia, Japan, and India are driving batch-tested certification demand that pulls premium product development.
- FSSAI licensing standardization:India's consolidated Food Safety and Standards Act oversight for protein and pre-workout products is formalizing domestic market access and reducing informal channel competition.
- Precision fermentation scale-up:Enzymatic processing advances in Singapore and South Korean biotech clusters are lowering input costs for high-bioavailability protein isolates.
Market Restraints
- Whey protein import dependency:Asia-Pacific manufacturers rely on concentrated whey supply from Oceania dairy processors, exposing margins to commodity volatility and currency fluctuation.
- Japan's FFC clinical evidence requirements:The Consumer Affairs Agency's Foods with Function Claims system demands substantiation investments that freeze smaller competitors out of functional positioning.
- Plant protein taste-performance gap:Pea and rice protein isolates still underperform on flavor masking versus dairy alternatives, limiting mainstream recreational user adoption.
Strategic Opportunities
- Vietnam and Indonesia gym corridor penetration:Metro fitness infrastructure in Ho Chi Minh City, Jakarta, and Surabaya remains underdeveloped relative to protein awareness growth.
- Direct-to-consumer subscription channel:E-commerce platforms bypassing traditional pharmacy and specialty retail are capturing repeat-purchase economics previously lost to intermediaries.
- TGA-FSANZ harmonization potential:Closer alignment between Australia's Therapeutic Goods Administration and Food Standards Australia New Zealand could streamline cross-border powder and capsule compliance.
Industry Challenges
- Cross-border e-commerce customs friction:Southeast Asian markets are tightening direct-to-consumer import scrutiny, forcing inventory localization and distributor relationship investments.
- Flavor localization complexity:India's MuscleBlaze and similar domestic players have raised consumer expectation for region-specific taste profiles that multinational brands struggle to replicate at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sports Nutrition Market |
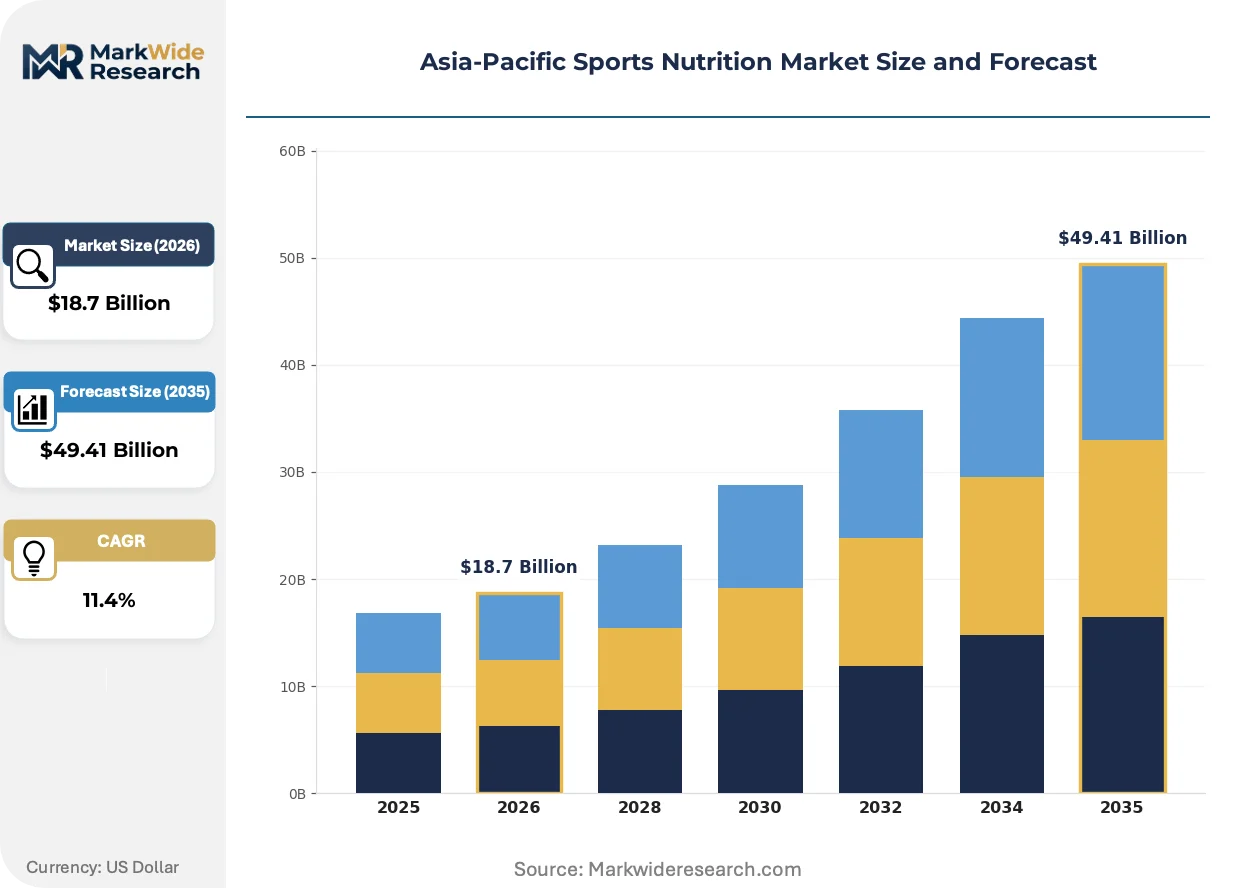
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Energy Gels, Meal Replacements, Pre-Workout Formulas End User: Athletes, Fitness Enthusiasts, Bodybuilders, Recreational Users Distribution Channel: Online Retail, Supermarkets, Fitness Centers, Health Stores Form: Powder, Bar, Liquid, Capsule |
| Companies Covered | Herbalife International of America Inc., Abbott Laboratories, The Coca-Cola Company, Reliance Consumer Products Limited, General Nutrition Centers Inc., PepsiCo Inc., Otsuka Pharmaceutical Co. Ltd., MuscleBlaze, Glanbia plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sports Nutrition Market Strategic Shifts
Digital twin formulation platforms and AI-driven protein structure prediction are compressing R&D cycles for Asia-Pacific sports nutrition developers. These technologies enable rapid iteration on bioavailability and sensory profiles without extensive physical prototyping.
Digital twin simulation is virtualizing the traditional wet-lab formulation process for protein bar and powder development. Mid-tier manufacturers in South Korea and Australia are adopting cloud-based molecular modeling to reduce trial batches by half. This compression is virtualizing competitive advantage toward firms with stronger computational chemistry capabilities rather than legacy manufacturing scale.
China's SAMR enforcement of updated GB standards for health food labeling is tightening ingredient disclosure and prohibited substance thresholds. Domestic brands must now submit comprehensive supply chain documentation that previously sufficed with self-certification. Imported products face extended registration timelines, advantaging established players with dedicated regulatory affairs teams in Shanghai and Beijing.
Subscription-driven replenishment models are displacing traditional retail replenishment cycles across India's metropolitan fitness corridors. Recreational users in Mumbai, Delhi, and Bangalore now expect personalized flavor rotation and auto-delivery cadences managed through mobile apps. This behavioral shift concentrates lifetime value capture with brands that own direct customer relationships rather than pharmacy or gym counter intermediaries.
Asia-Pacific Sports Nutrition Market Segmentation
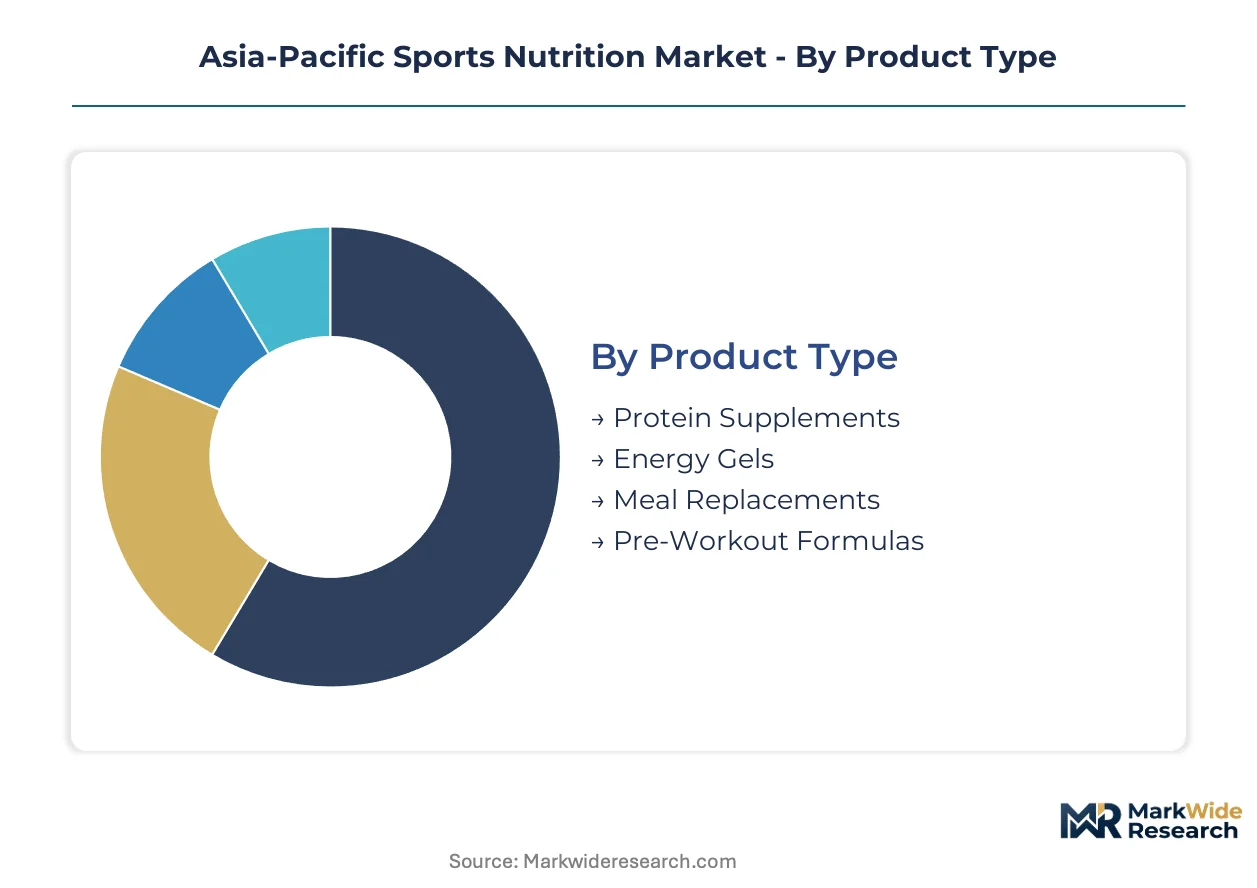
Segmentation in Asia-Pacific sports nutrition reveals divergent margin structures and channel economics. Product form and end-user sophistication drive formulation investment, while distribution access determines geographic penetration speed.
Product Type:
Cost tier differentiation separates commodity protein from premium functional formats.
- Protein Supplements:Concentrates and isolates delivering 15-30 grams per serving dominate replenishment economics through subscription channels. Australia's competitive sports teams and India's metropolitan bodybuilders anchor volume concentration, though whey import dependency from Oceania squeezes margin stability.
- Energy Gels:Rapid-absorption carbohydrate matrices packaged for endurance portability are climbing fastest among marathon and triathlon participants. Japanese and Australian endurance athletes pull portable fuel demand, with Ho Chi Minh City and Jakarta gym corridors emerging as new consumption nodes.
- Meal Replacements:Macro-balanced formulations targeting body composition goals serve time-constrained professionals in India's tech corridors.
- Pre-Workout Formulas:Caffeine and creatine matrices with stimulant timing optimization capture committed training segments across South Korean fitness centers.
Protein Supplements command the established base. The steepest expansion runs through Energy Gels.
End User:
Customer type stratification maps directly to certification requirements and price elasticity.
- Athletes:Competitive sports teams and individual competitors demand batch-tested certification under Australia's TGA and Japan's Consumer Affairs Agency frameworks. This segment absorbs premium pricing for contaminant-free guarantees, with India's professional cricket and kabaddi leagues driving formalized procurement.
- Fitness Enthusiasts:Regular gym attendees with structured training programs prioritize bioavailability metrics and flavor rotation. Mumbai, Delhi, and Bangalore's subscription app users concentrate lifetime value capture with direct-to-consumer brands.
- Bodybuilders:India's domestic sourcing preferences and localized taste profiles create defensive moats for regional formulators.
- Recreational Users:Convenience-oriented consumers with sporadic gym attendance favor ready-to-drink liquids and impulse bar purchases.
Athletes anchor premium revenue pools. Fitness Enthusiasts are expanding most quickly through digital channel migration.
Distribution Channel:
Channel configuration determines inventory localization requirements and customs exposure.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators bypass traditional pharmacy intermediaries. India's mobile-first subscription models and Australia's specialty protein sites concentrate repeat-purchase economics, though Southeast Asian customs tightening forces bonded warehouse investments.
- Supermarkets:Mass-market powder and bar placement reaches recreational users with lower education thresholds. Shelf-space competition favors established FMCG portfolios with existing retail relationships.
- Fitness Centers:Gym counter and vending presence captures impulse replenishment immediately post-workout.
- Health Stores:Pharmacy-adjacent specialty retailers serve advisory-seeking consumers with clinical nutrition questions.
Online Retail leads volume growth trajectory. Supermarkets retain the broadest reach base.
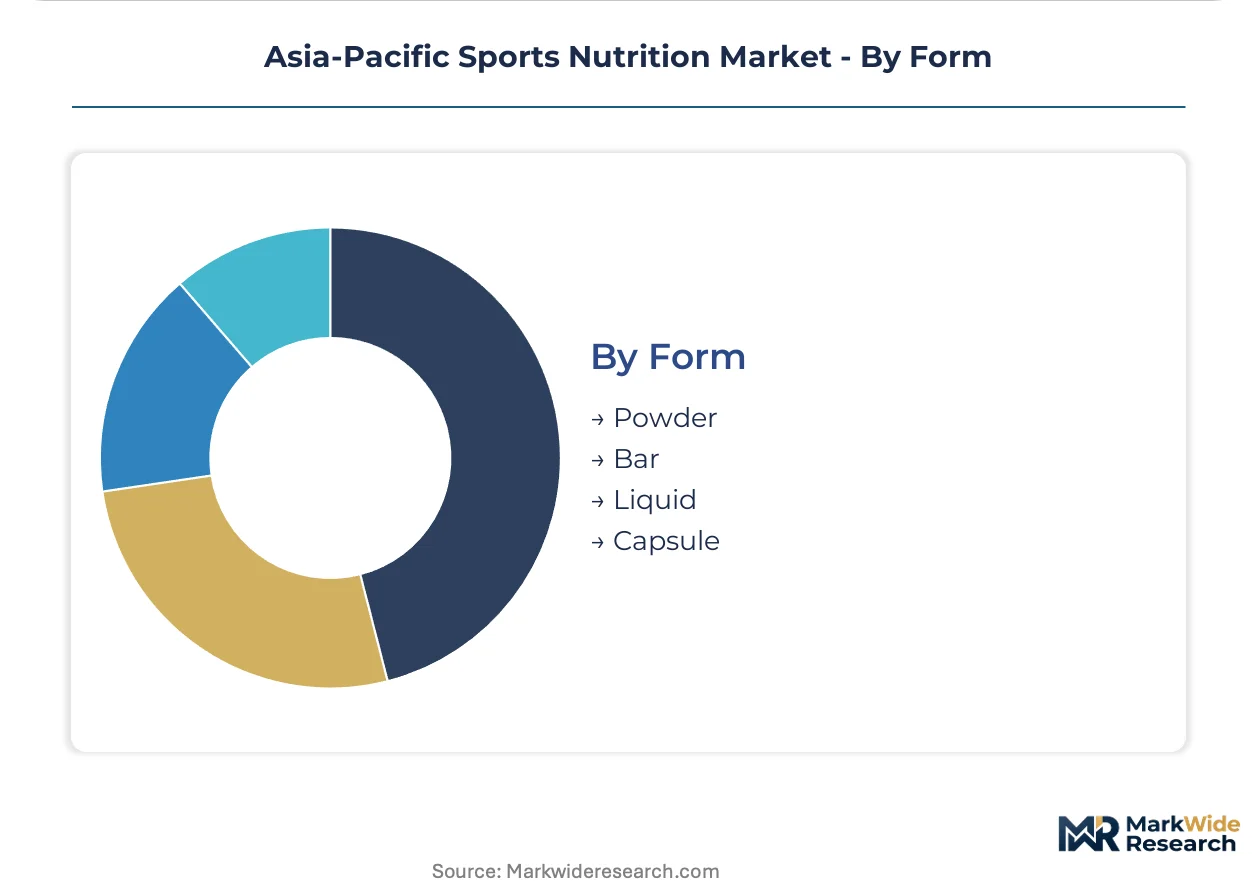
Form:
Manufacturing process and supply chain shape competitive positioning across physical formats.
- Powder:Spray-dried isolates and concentrates dominate bulk purchasing economics. Singapore and South Korean precision fermentation scale-up is compressing input costs for cleaner-label protein isolates.
- Bar:Cold-pressed and extruded formats with flavor masking complexity command manufacturing specialization.
- Liquid:Ready-to-drink convenience carries shelf-stability and logistics cost premiums.
- Capsule:Branched-chain amino acid and creatine monohydrate delivery suits precision dosing requirements.
Powder commands the volume base. Bar formats are gaining share fastest through portability demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional athletes and competitive sports teams concentrate demand across Australia's TGA-regulated leagues, India's FSSAI-licensed corridors, and Japan's Consumer Affairs Agency frameworks. Fitness enthusiasts in metropolitan gym clusters pull differentiated product requirements that reshape regional formulation priorities.
China
Updated GB standards for health food ingredient disclosure force comprehensive supply chain documentation from domestic brands and extended registration timelines for imports. SAMR enforcement advantages established players with dedicated regulatory affairs teams in Shanghai and Beijing. Precision fermentation scale-up in Yangtze River Delta biotech clusters compresses input costs for high-bioavailability protein isolates.
Japan
Endurance athletes in marathon and triathlon segments pull portable fuel demand for rapid-absorption carbohydrate matrices. The Consumer Affairs Agency's Foods with Function Claims system demands clinical evidence investments that freeze smaller competitors out of functional positioning. Tokyo and Osaka metropolitan fitness corridors anchor premium product consumption with batch-tested certification requirements.
India
FSSAI licensing standardization under the Food Safety and Standards Act formalizes domestic market access for protein and pre-workout products while reducing informal channel competition. Mumbai, Delhi, and Bangalore subscription app users concentrate lifetime value capture with direct-to-consumer brands. Domestic sourcing preferences and localized taste profiles create defensive moats for regional formulators serving bodybuilder segments.
Australia
Competitive sports teams and elite athletes drive batch-tested certification demand that pulls premium product development under TGA frameworks. The Therapeutic Goods Administration and Food Standards Australia New Zealand jointly oversee borderline sports supplements, creating compliance complexity for imported powders and capsules. Sydney and Melbourne specialty protein sites concentrate repeat-purchase economics through online retail channels.
South Korea
Caffeine and creatine matrices with stimulant timing optimization capture committed training segments across Seoul Capital Area fitness centers. MFDS oversight structures import registration requirements for functional health foods. Precision fermentation advances in Busan-Ulsan biotech clusters enable enzymatic processing cost compression for cleaner-label formulations.
Asia-Pacific Sports Nutrition Market Competitive Environment
Channel-controlling players compete with product-specialist players across subscription platforms, gym counters, and pharmacy-adjacent specialty retail. The market structure tiers between multinational FMCG portfolios with existing retail relationships and domestic formulators with flavor localization capabilities. Three strategic archetypes dominate: clinical nutrition heritage players anchoring medical-adjacent segments, domestic sourcing specialists capturing regional taste preferences, and precision fermentation scale-ups compressing cleaner-label economics. Competitive moves concentrate on direct-to-consumer platform development and regulatory affairs team localization in priority markets.
Within the clinical heritage tier, Abbott Laboratories exemplifies premium positioning anchored in medical-adjacent sports segments. Among domestic formulators, MuscleBlaze occupies a position representing aggressive competition on sourcing and flavor localization for bodybuilders. At the East Asian functional positioning vector, Otsuka Pharmaceutical Co. Ltd. represents science-backed electrolyte and amino acid portfolio concentration.
| Leading Market Players |
|---|
| Herbalife International of America Inc. |
| Abbott Laboratories |
| The Coca-Cola Company |
| Reliance Consumer Products Limited |
| General Nutrition Centers Inc. |
| PepsiCo Inc. |
| Otsuka Pharmaceutical Co. Ltd. |
| MuscleBlaze |
| Glanbia plc |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Oceania dairy processing facilities drives whey protein concentrate premiums and forces Asia-Pacific formulators toward alternative sourcing strategies. This utilization squeeze compresses margin structures for mid-tier brands while rewarding incumbents with locked-in supply contracts.
Pricing Analysis
Cost-plus contracts indexed to Fonterra Global Dairy Trade auction prices dominate whey protein procurement. Three-tier pricing structure across premium batch-tested, standard certified, and economy unbranded tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from FSSAI licensing compliance costs in India, which squeeze smaller domestic competitors. Recreational users in Southeast Asian markets exhibit highest price sensitivity, while Australian TGA-certified athletes absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Export-control scrutiny on precision fermentation technology limits bioreactor equipment flows into Chinese and South Korean manufacturing hubs. Supply concentrates in New Zealand dairy cooperatives, Singapore biotech clusters, and Indian domestic sourcing networks for regional brands. Raw material dependencies span whey protein isolate, pea protein concentrate, and enzymatic processing catalysts. Single-source vulnerability runs through Oceania dairy processor consolidation. Distribution runs through direct-to-consumer platforms in India and Australia, with bonded warehouse localization forced by Southeast Asian customs tightening.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up constitutes a technological inflection reshaping formulation economics and competitive moats across the region. China's SAMR enforcement of GB standards simultaneously accelerates regulatory consolidation.
For Market Incumbents: Build regulatory affairs moats through Shanghai and Beijing team localization to capture extended import registration timelines. Deepen backward integration into precision fermentation capacity in Singapore and South Korean biotech corridors. Anchor premium positioning through TGA and FFC certification investments that freeze smaller competitors out of functional claims. Threat vector: domestic formulators with flavor localization capabilities in India. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia gym corridors where metro fitness infrastructure lags protein awareness growth. Target Ho Chi Minh City and Jakarta subscription app users with localized flavor profiles and mobile-first replenishment models. Penetrate through direct-to-consumer platforms bypassing pharmacy intermediaries facing customs friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with owned customer relationships in India's metropolitan fitness corridors. Long-term viability favors precision fermentation scale-ups with enzymatic processing capabilities and cleaner-label positioning. Acquisition target archetype: domestic formulators with regional taste localization and FSSAI licensing compliance. Signal to watch: TGA-FSANZ harmonization progress as cross-border compliance streamlining indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enzymatic processing advances in Singapore and Busan-Ulsan clusters compress cleaner-label protein economics. |
| Regulatory Affairs Localization | Dedicated Shanghai and Beijing teams capture extended SAMR registration timeline advantages for imported brands. |
| Direct-to-Consumer Platform Development | Mobile-first subscription models in Mumbai and Bangalore concentrate lifetime value capture with owned relationships. |
| Flavor Localization Investment | Region-specific taste profiles defend against MuscleBlaze and domestic Indian formulator competition. |
| Batch-Tested Certification Acquisition | TGA and FFC compliance investments anchor premium positioning in Australian and Japanese athlete segments. |
Study Parameters
The analysis maps protein supplement, energy gel, pre-workout formula, and meal replacement sub-sectors, each validated through formulation scientists, regulatory affairs directors, gym chain procurement managers, and e-commerce platform operators. Primary interviews triangulate with secondary validation from FSSAI licensing databases, TGA product registration listings, SAMR GB standard documentation, and customs trade flow records. Bottom-up segment sizing and top-down macro anchoring converge through iterative reconciliation.
Assumption sets held regulatory enforcement intensity and precision fermentation scale-up rates fixed while varying gym penetration speed and cross-border e-commerce policy trajectories. Segmentation dimensions span product type, end user sophistication tier, distribution channel configuration, and regional regulatory cluster. CAGRs derive from installed base growth rates and per-user consumption trajectory modeling. Industry-specific forecast inputs include FSSAI licensing penetration curves and TGA batch-testing certification adoption patterns.
Macroeconomic conditions sit as an overlay; deviation in currency volatility affecting Oceania dairy imports or commodity protein price spikes would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and biotech cluster investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Medicated Fitness Supplements Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
United States Weight Management Market