
 Brazil Sports Nutrition Market | 2026-2036
Brazil Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Sports Nutrition Market Intelligence
Certified sports nutritionists and exercise physiologists is reorganizing how Brazilian consumers evaluate supplement efficacy and safety. Glanbia leverages its whey protein sourcing infrastructure to anchor premium positioning in southern Brazil. Max Titanium competes through flavor localization and regional gym partnerships. Integralmedica Suplementos Nutricionais dominates pharmacy and drugstore channels with broad retail coverage.
Sports nutrition encompasses formulated consumables designed to enhance athletic performance, recovery, or body composition, typically specifying macronutrient ratios, bioactive compound concentrations, and dissolution profiles for rapid gastric emptying. Protein Supplements occupy the largest value share due to entrenched gym culture and established consumption rituals among resistance-trained populations. Pre-Workout formulations represent the fastest-growing product type as younger consumers seek ergogenic aids with transparent ingredient panels. The End User base fragments across Athletes requiring batch-tested certifications and Casual Users prioritizing convenience and taste over performance metrics.
ANVISA governs product registration, health claim substantiation, and Good Manufacturing Practice compliance for all domestically manufactured and imported sports nutrition items. The Ministry of Agriculture, Livestock, and Supply oversees ingredient traceability for collagen, amino acid, and animal-derived inputs entering the supply chain. Stakeholders must monitor pending ANVISA consultations on novel ingredient approvals and adapt formulation pipelines accordingly.
Market Dynamics
ANVISA's updated nutritional supplement labeling requirements are compressing product development cycles and forcing reformulation investments across Brazilian manufacturers. This regulatory pressure sits alongside a demand pivot where amateur athletes and weekend warriors now match bodybuilders as category drivers.
Growth Catalysts
- Metropolitan Fitness Density:São Paulo's metropolitan corridor and Rio de Janeiro's coastal zones concentrate gym memberships and supplement consumption rituals. These urban clusters generate disproportionate per-capita spending on protein and pre-workout formulations.
- ANVISA Registration Pathways:Streamlined product registration processes for established ingredient categories reduce time-to-market for compliant domestic manufacturers. This regulatory clarity accelerates pipeline commercialization relative to imported alternatives facing full novel-substance review.
- Plant Protein Processing:Advances in pea and rice protein isolation technology improve amino acid completeness and dissolution profiles. Brazilian ingredient suppliers leverage domestic agricultural capacity to serve growing vegan and flexitarian athlete segments.
Market Restraints
- Whey Concentrate Import Dependency:Premium whey protein isolate relies on concentrated import flows from Ireland and US dairy processing regions. Currency volatility against the dollar directly compresses gross margins for mid-tier domestic brands.
- ANVISA Novel Ingredient Backlog:Pending consultations on adaptogens, nootropics, and exotic stimulants create formulation uncertainty. Manufacturers delay R&D investments until regulatory clarity emerges on substance-by-substance approvals.
- Pharmacy Channel Concentration:Integralmedica's entrenched drugstore relationships limit shelf access for challenger brands. This distribution bottleneck forces competitors toward higher-cost direct-to-consumer logistics.
Strategic Opportunities
- Northeast Urban Expansion:Salvador, Recife, and Fortaleza exhibit rising gym penetration with underdeveloped sports nutrition retail infrastructure. Early entrants capture consumer habit formation before national brands establish local presence.
- Clean Label Pre-Workout:Transparent ingredient panels with disclosed stimulant stacks and no proprietary blends attract younger consumers. Brands leading this disclosure standard capture trust premiums before regulatory mandates force universal compliance.
- Telehealth Integration:Sports nutritionists and exercise physiologists prescribing supplementation through digital health platforms create new prescription-adjacent channels. This convergence merges clinical credibility with e-commerce convenience.
Industry Challenges
- Exercise Physiologist Talent Scarcity:Certified professionals capable of translating biometric data into personalized supplementation protocols remain concentrated in southern state capitals. National brands struggle to staff credible educational field teams.
- Batch Testing Certification Timelines:Third-party testing for banned substances and label claim verification extends lead times by eight to fourteen weeks. Athletes requiring competition-safe certifications face inventory gaps during peak demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Sports Nutrition Market |
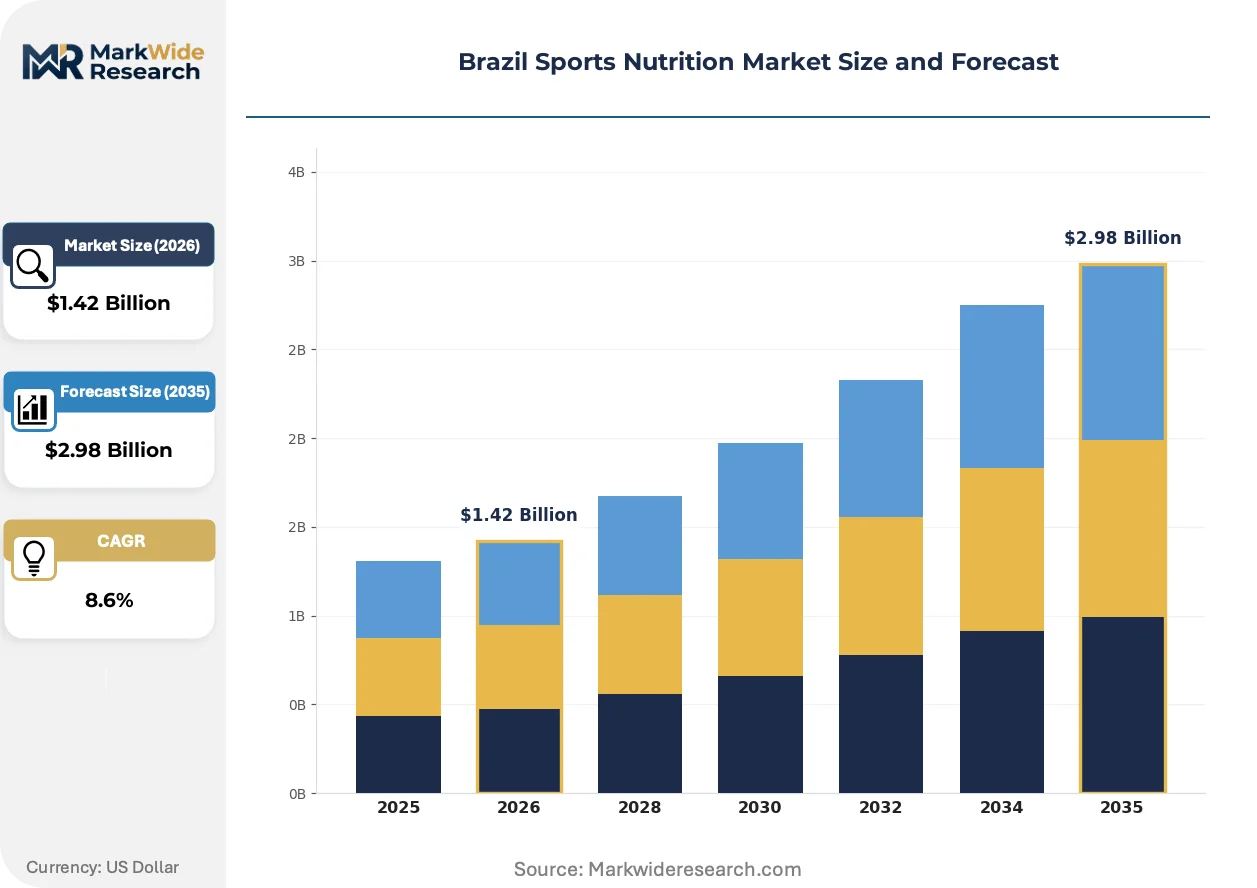
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Energy Bars, Pre-Workout, Post-Workout End User: Athletes, Fitness Enthusiasts, Bodybuilders, Casual Users Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Gyms Form: Powder, Liquid, Bar, Capsule |
| Companies Covered | PepsiCo, The Coca-Cola Company, Abbott Laboratories, Glanbia, Nestlé, Integralmedica Suplementos Nutricionais, Max Titanium, MusclePharm, Optimum Nutrition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Sports Nutrition Market Strategic Shifts & Innovations
Formulation transparency and digital distribution are reshaping how Brazilian consumers discover, evaluate, and purchase sports nutrition products. These shifts compress traditional brand loyalty cycles while elevating clinical credibility as a purchase filter.
Protein sourcing technology is bifurcating the market into animal-derived precision isolates and plant-based complete amino acid profiles. Younger consumers in São Paulo and Curitiba adopt hybrid consumption patterns, alternating whey and pea blends based on training modality. This dual-track adoption is bifurcating manufacturing investments, with facilities retooling for flexible production lines rather than single-source dominance.
ANVISA's pending consultation on novel ingredient approvals is forcing brands to pre-position compliant formulations before substance-specific rulings. Manufacturers are submitting grandfathered applications for established compounds while shelving experimental adaptogen stacks. Pre-workout and nootropic-adjacent categories face the highest uncertainty, with several brands pivoting to caffeine-theanine core formulations as regulatory safe harbors.
Certified sports nutritionists now influence purchase decisions through social proof and direct consultation, displacing pure marketing-driven selection. Gym chains in Rio de Janeiro and Belo Horizonte integrate registered professionals into membership packages, creating bundled supplement recommendations. This channel shift concentrates authority with credentialed individuals rather than retail shelf placement, rewarding brands that invest in practitioner education programs.
Brazil Sports Nutrition Market Segmentation
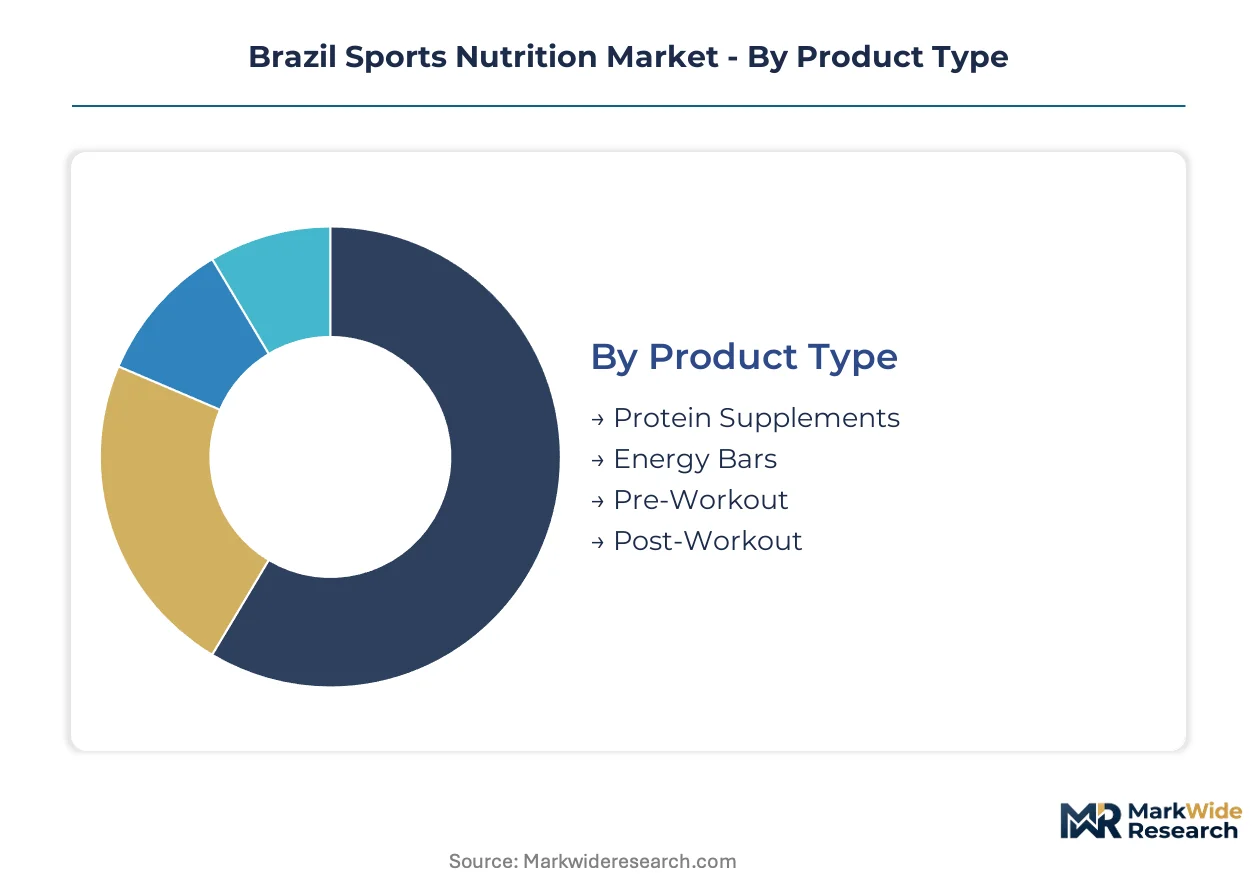
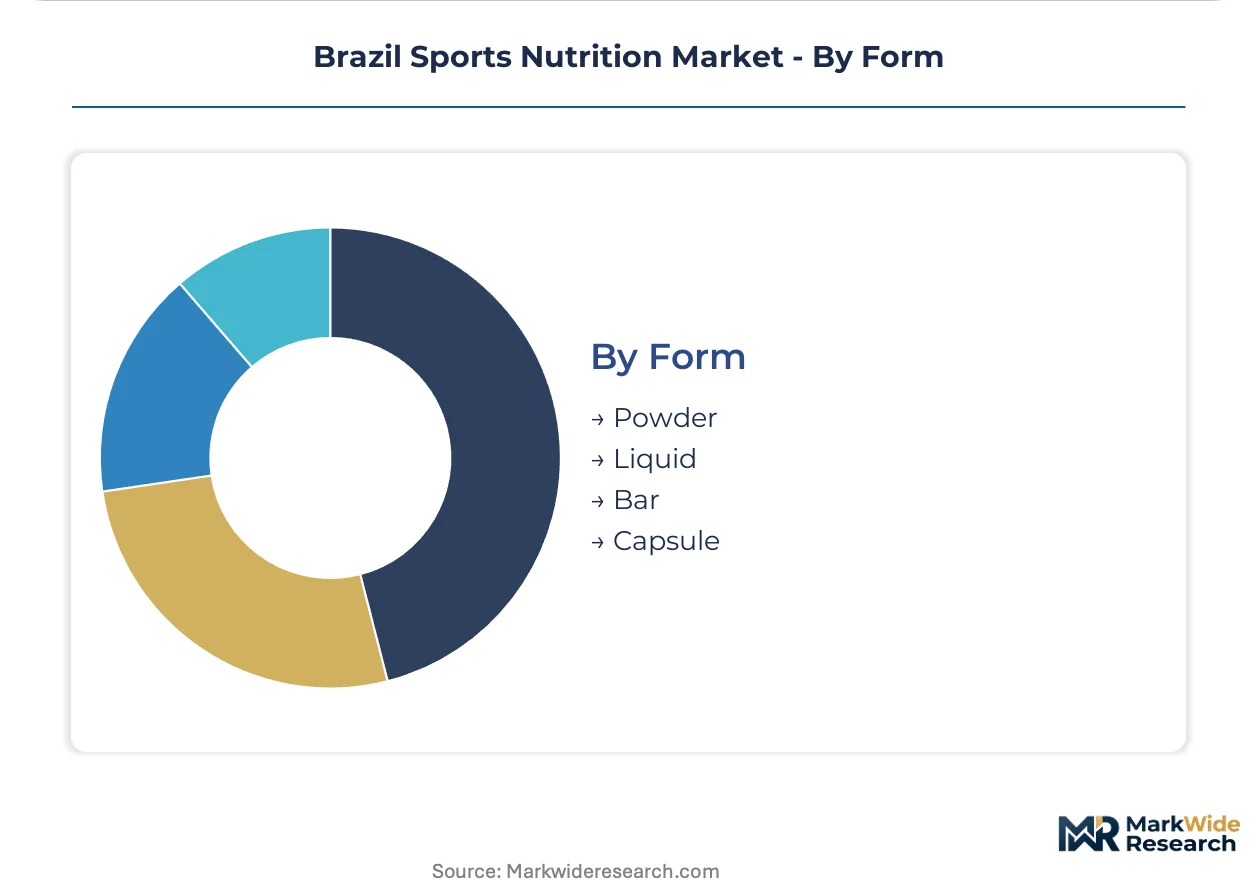
Brazil's sports nutrition market fragments across four dimensions that determine pricing power and channel access. Product type and end-user profiles concentrate margin pools in distinct consumption rituals, while distribution channel and form factor dictate manufacturing flexibility requirements.
Product Type:
Margin pools concentrate in formulations with established consumption rituals and premium positioning potential.
- Protein Supplements:Whey isolates, concentrates, and plant-based blends deliver standardized amino acid profiles with dissolution specifications for rapid gastric emptying. Resistance-trained populations in São Paulo's metropolitan corridor sustain entrenched daily consumption habits that stabilize volume forecasts. ANVISA registration pathways for established protein categories reduce compliance friction relative to novel formulations.
- Pre-Workout:Ergogenic blends specifying caffeine, beta-alanine, and citrulline concentrations target acute performance enhancement with transparent stimulant disclosure. Younger consumers in Rio de Janeiro's fitness-dense coastal zones drive demand for clean-label formulations without proprietary blends. Pending ANVISA consultations on exotic stimulants compress R&D timelines and force grandfathered ingredient strategies.
- Energy Bars:Macronutrient-balanced portable nutrition with specified protein-carbohydrate ratios for intra-workout or meal-replacement scenarios.
- Post-Workout:Recovery-focused formulations emphasizing carbohydrate replenishment and leucine-triggered muscle protein synthesis.
The dominant share belongs to Protein Supplements, while Pre-Workout is closing the gap fastest.
End User:
Customer archetypes split between performance-verified demand and convenience-driven consumption.
- Bodybuilders:Rigorous macronutrient tracking and batch-tested certification requirements define purchase criteria. Competition-tested athletes face eight-to-fourteen-week third-party verification timelines that strain inventory planning during peak demand windows.
- Casual Users:Taste preference and retail accessibility override performance metrics in purchase decisions. Pharmacy channel concentration in southeastern state capitals limits brand discovery for challenger products.
- Athletes:Competition-safe certifications and banned-substance testing protocols govern selection.
- Fitness Enthusiasts:Hybrid consumption patterns alternating between training-focused and lifestyle-oriented products.
Bodybuilders anchor volume stability, though Casual Users are expanding most quickly as gym penetration broadens beyond traditional strength sports.
Distribution Channel:
Channel economics determine margin retention and consumer education investment requirements.
- Specialty Stores:Staff expertise and sampling programs justify premium pricing for complex formulations. Southern Brazil's concentrated gym culture supports dedicated retail footprints with higher per-square-meter supplement sales.
- Online Retail:Direct-to-consumer logistics bypass pharmacy channel bottlenecks but absorb last-mile costs in northeast urban expansion markets. Subscription models capture recurring revenue from established consumption rituals.
- Supermarkets:Mass-market accessibility with limited SKU depth and minimal staff guidance.
- Gyms:Bundled membership offerings integrating certified sports nutritionist consultations.
Specialty Stores command margin premiums, while Online Retail is gaining share fastest through telehealth integration and subscription mechanics.
Form:
Manufacturing flexibility requirements vary with dissolution specifications and shelf stability demands.
- Powder:Bulk packaging economics and flavor localization capabilities support regional brand differentiation. Pea and rice protein isolation advances enable complete amino acid profiles from domestic agricultural inputs.
- Bar:Texture engineering and moisture barrier specifications determine production line capital requirements.
- Liquid:Ready-to-drink convenience with sterilization and packaging constraints.
- Capsule:Precise dosing for stimulant and nootropic-adjacent categories facing regulatory uncertainty.
Powder dominates production volume, though Bar formats are climbing fastest as on-the-go consumption expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's regulatory framework anchors the southeastern corridor where gym density and supplement consumption concentrate most heavily. State-level agricultural policies and metropolitan fitness infrastructure create distinct sub-regional competitive dynamics across Brazil's federated structure.
São Paulo
São Paulo's metropolitan corridor generates the highest per-capita spending on protein and pre-workout formulations, driven by entrenched gym culture and resistance-trained populations. The state agricultural secretariat supports dairy processing infrastructure that supplies whey protein inputs to domestic manufacturers. Campinas and Sorocaba host concentrated flavor localization facilities serving national distribution networks.
Rio de Janeiro
Rio de Janeiro's coastal zones exhibit fitness-dense consumption patterns where younger demographics drive clean-label pre-workout demand. ANVISA's streamlined registration pathways benefit established manufacturers headquartered in the state capital. Niterói and Barra da Tijuca cluster premium specialty retail and certified sports nutritionist consultation services.
Minas Gerais
Minas Gerais leverages its dairy production base to anchor whey protein concentrate supply for southeastern formulators. State-level quality certification programs for agricultural inputs align with ANVISA's traceability requirements for animal-derived supplements. Belo Horizonte's expanding gym penetration supports rising consumption among amateur athletes and casual users.
Rio Grande do Sul
Rio Grande do Sul concentrates exercise physiologist talent and sports science education infrastructure that shapes consumer evaluation of supplement efficacy. The state university system feeds credentialed professionals into practitioner-influenced distribution channels. Porto Alegre's specialty retail ecosystem commands margin premiums through staff expertise and sampling programs.
Bahia
Bahia represents an emerging expansion frontier where rising gym penetration meets underdeveloped sports nutrition retail infrastructure. Salvador's metropolitan growth outpaces national supplement category penetration rates, creating first-mover opportunities. Local agricultural capacity in pea and rice protein inputs supports domestic plant-based formulation investments.
Brazil Sports Nutrition Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Multinational nutrition conglomerates leverage R&D infrastructure and global sourcing networks, while domestic specialists compete through flavor localization and regional gym partnerships. Three archetypes dominate: premium ingredient innovators, mass-market distribution consolidators, and agile regional challengers. Capacity expansion and portfolio diversification constitute the dominant competitive moves, with players extending from core protein into adjacent functional nutrition categories.
Among multinational nutrition conglomerates, Glanbia and Abbott Laboratories occupy positions exemplifying premium ingredient sourcing and clinical credibility archetypes. PepsiCo and Nestlé represent mass-market distribution consolidators leveraging beverage and packaged food infrastructure into sports nutrition adjacencies. Domestic specialists Max Titanium and Integralmedica Suplementos Nutricionais anchor the regional challenger tier, with the former exemplifying flavor-led gym partnership strategies and the latter representing pharmacy channel concentration models.
| Leading Market Players |
|---|
| PepsiCo |
| The Coca-Cola Company |
| Abbott Laboratories |
| Glanbia |
| Nestlé |
| Integralmedica Suplementos Nutricionais |
| Max Titanium |
| MusclePharm |
| Optimum Nutrition |
| Others |
Cost & Logistics Intelligence
ANVISA's Good Manufacturing Practice certification gates both supply qualification and price differentiation simultaneously, separating registered domestic manufacturers from import-dependent competitors facing currency-adjusted cost structures. This regulatory threshold compresses margins for mid-tier brands while rewarding compliant incumbents with pharmacy channel access and premium positioning.
Pricing Analysis
São Paulo's metropolitan corridor commands price premiums of 15-20% above Salvador and Recife for equivalent whey isolate formulations, reflecting logistics density and retail competition concentration. Pricing stratifies across batch-tested premium tiers, standard ANVISA-registered mid-market SKUs, and economy concentrates with simplified amino acid disclosure. Price differentiation hinges on certification grade and import dependency, with dollar-exposed whey isolate brands experiencing margin compression against domestic dairy-sourced competitors. Casual users in pharmacy channels exhibit highest price sensitivity, while competitive bodybuilders absorb premiums for third-party verified competition-safe certifications.
Supply Chain Analysis
Ireland and the United States anchor premium whey protein isolate supply for Brazilian formulators, while domestic Minas Gerais and Rio Grande do Sul dairy processing regions feed concentrate and hydrolysate tiers. Raw material dependencies center on filtered whey permeate, microfiltration membranes, and flavor masking systems for plant protein blends. Supply chain risk concentrates in single-source import vulnerability for ion-exchange resins and specialized packaging films. Distribution runs through pharmacy channel consolidators in southeastern state capitals, with direct-to-consumer logistics expanding fastest in underserved northeast urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's sports nutrition sector tracks gym membership cyclicality, with amateur athlete enrollment recovering from pandemic disruption and driving category volume expansion ahead of historical bodybuilder-dominant baselines.
For Market Incumbents: Compound defensive positioning through backward integration into domestic dairy processing capacity in Minas Gerais, securing captive whey concentrate supply against currency volatility. Lock in exclusive certified sports nutritionist partnerships with expanding gym chains before challenger brands replicate the practitioner-influenced distribution model. Prioritize ANVISA pre-registration for grandfathered ingredient formulations ahead of pending novel substance rulings.
For New Entrants and Emerging Players: Differentiate on clean-label pre-workout transparency with disclosed stimulant stacks, capturing younger consumer trust before regulatory mandates force universal compliance. Target Salvador, Recife, and Fortaleza gym penetration growth with direct-to-consumer subscription models, bypassing Integralmedica's pharmacy channel concentration. Deploy telehealth-integrated sports nutritionist consultations as the primary go-to-market wedge against established retail-dependent competitors.
For Investors and Strategic Acquirers: ANVISA's pending novel ingredient consultation reshapes the acquisition landscape toward compliant formulation pipelines and established registration portfolios. Long-term viability favors targets with flexible production lines accommodating both animal-derived isolates and plant-based complete amino acid profiles. Watch batch testing certification backlog resolution as the signal for competitive inventory positioning and working capital efficiency inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Flavor Localization Investment | Campinas and Sorocaba facilities enable regional taste differentiation against standardized multinational SKUs. |
| Plant Protein Processing Scale-Up | Domestic pea and rice isolation capacity captures vegan athlete segments with agricultural input traceability. |
| Telehealth Platform Integration | Digital sports nutritionist prescriptions merge clinical credibility with e-commerce recurring revenue mechanics. |
| ANVISA Registration Portfolio Expansion | Grandfathered ingredient filings ahead of novel substance rulings secure pipeline commercialization timelines. |
| Northeast Urban Distribution Buildout | Salvador and Recife logistics infrastructure captures consumer habit formation before national brand establishment. |
Research Approach
Cross-validation between primary interviews with sports nutrition manufacturers, gym chain procurement directors, and certified exercise physiologists anchors the qualitative findings against secondary validation. The research program combined structured conversations with ANVISA regulatory affairs specialists, pharmacy category buyers at drugstore consolidators, and flavor localization facility managers in Campinas with customs import data, ANVISA registration databases, and gym membership penetration statistics from metropolitan statistical agencies. Bottom-up SKU-level demand modeling triangulated against top-down category spending estimates across the analysis window.
Sensitivity analysis tested volume and value outputs against varying assumptions for gym penetration rates, currency volatility bands, and ANVISA consultation timeline scenarios throughout the forecast period. The analytical framework segmented demand across product type, end user archetype, distribution channel, and form factor, with additional modeling for regional consumption intensity within state-level metropolitan corridors. CAGRs derived from fitted growth curves incorporating historical category evolution patterns and projected amateur athlete enrollment trajectories, with specific inputs for whey protein import dependency ratios and plant protein processing capacity expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained gym membership recovery, ANVISA regulatory clarity, and stable dairy input pricing would require recalibration. Forecasts reflect documented assumptions regarding consumer habit formation rates and practitioner influence adoption curves. Specific risks that could revise projections include extended novel ingredient approval delays, acute currency devaluation against the dollar, and pharmacy channel consolidation beyond current concentration levels. Recalibration cycles align with material shifts in ANVISA regulatory posture, gym penetration statistics, and import cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
Brazil Sports Drinks Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Asia-Pacific Weight Management Supplement Market
Sports Nutrition
Creatine Supplements Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Medicated Fitness Supplements Market