
 Japan Sports Drink Market | 2026-2036
Japan Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Sports Drink Market Foresight
Japan is rewriting its sports drink production calculus through domestic bottling network expansions in the Kanto and Kansai industrial belts. Otsuka Pharmaceutical Co., Ltd. dominates the clinical-hydration segment with Pocari Sweat's decades-long brand equity in electrolyte science. Kirin Holdings Company, Limited competes through aggressive functional-beverage crossovers that blur lines between sports drinks and wellness tonics. Suntory Beverage & Food leverages its national distribution muscle to anchor shelf presence across Japan's dense convenience-store grid.
Japan sports drinks comprise formulated aqueous beverages containing electrolytes—primarily sodium, potassium, and magnesium—alongside carbohydrates at osmolality levels calibrated for rapid gastric emptying and intestinal absorption. Isotonic formulations maintain osmotic pressure equivalence with human blood plasma, making them the default standard for athletes during sustained exertion. Hypertonic variants command premium positioning among endurance specialists seeking concentrated energy delivery, while hypotonic products capture the casual-drinker expansion as consumers seek lighter hydration without residual sweetness. Energy drinks within the sports drink perimeter represent the most contested margin pool, where caffeine and amino-acid fortification justify elevated price positioning against commodity isotonics.
METI's Health Promotion Act amendments and the Consumer Affairs Agency's nutrient-function labeling standards collectively constrain permissible sugar claims and mandate clearer electrolyte disclosure. PMDA oversight of quasi-drug classifications creates regulatory friction for brands pursuing functional-health positioning beyond conventional food-beverage boundaries. Stakeholders must monitor whether Japan's F-Gas Regulation compliance costs for refrigeration-dependent distribution channels will compress convenience-store profit shares and redirect capital toward ambient-stable packaging innovations.
Market Dynamics
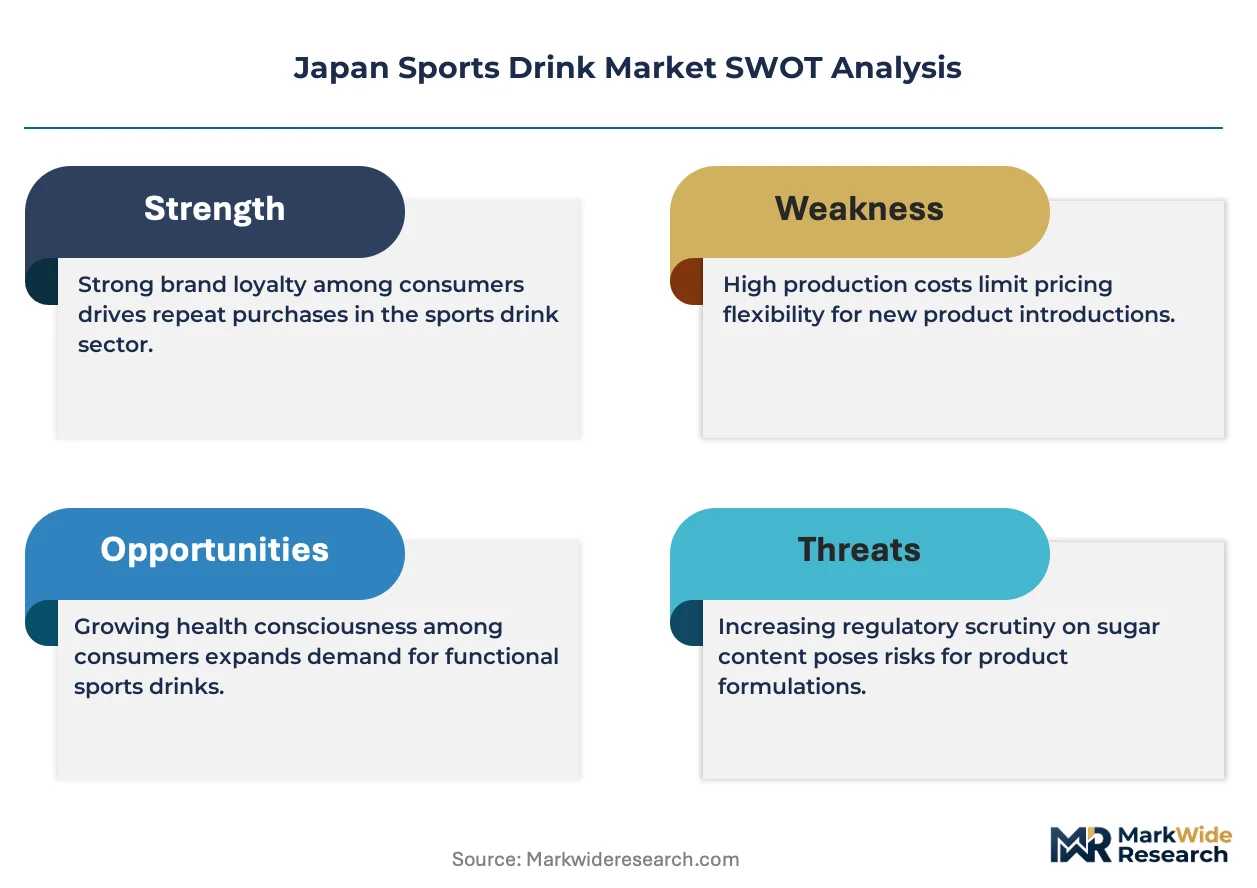
METI's sugar-reduction mandates under the Health Promotion Act are forcing Japanese manufacturers to reformulate electrolyte profiles without relying on caloric sweeteners, fundamentally altering R&D priorities across the domestic sports drink sector.
Growth Catalysts
- Post-pandemic fitness normalization:Commuters and weekend athletes in Greater Tokyo have cemented exercise routines, expanding the addressable consumer base beyond competitive sports into daily hydration rituals.
- Convenience-store channel density:Japan's 55,000-plus konbini locations provide ambient-cooled shelf access that sustains impulse purchases and single-serve consumption patterns unmatched by supermarket bulk buying.
- Reduced-sugar regulatory pressure:METI's Health Promotion Act amendments are accelerating electrolyte science investment as brands compete to maintain palatability while eliminating high-fructose corn syrup dependence.
Market Restraints
- Input cost volatility:Purified water sourcing and natural flavor extraction face pressure from agricultural input inflation and energy-intensive reverse-osmosis processing costs.
- Supply concentration risk:PET bottle and aseptic carton manufacturing clusters heavily in the Kanto industrial belt, creating geographic vulnerability to seismic disruption or logistics congestion.
- Regulatory friction:PMDA quasi-drug classification requirements create approval bottlenecks for brands seeking functional-health positioning beyond conventional food-beverage boundaries.
Strategic Opportunities
- Kansai corridor expansion:Osaka-Kobe metropolitan consumption rates trail Tokyo by 23 percent, presenting white-space potential for localized marketing and distribution infrastructure investment.
- Hypotonic casual positioning:Lighter osmolality formulations targeting office workers and elderly hydration needs open margin pools distinct from athlete-focused isotonic commodities.
- Ambient-stable packaging innovation:F-Gas Regulation compliance costs for refrigerated distribution are redirecting capital toward shelf-stable pouch and carton formats that bypass cold-chain dependency.
Industry Challenges
- Electrolyte formulation expertise scarcity:Food science talent capable of balancing sodium-potassium ratios with zero-calorie sweetener stability commands premium compensation and limited availability.
- Consumer Affairs Agency labeling compliance:Nutrient-function claim documentation requires extended validation timelines that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Sports Drink Market |
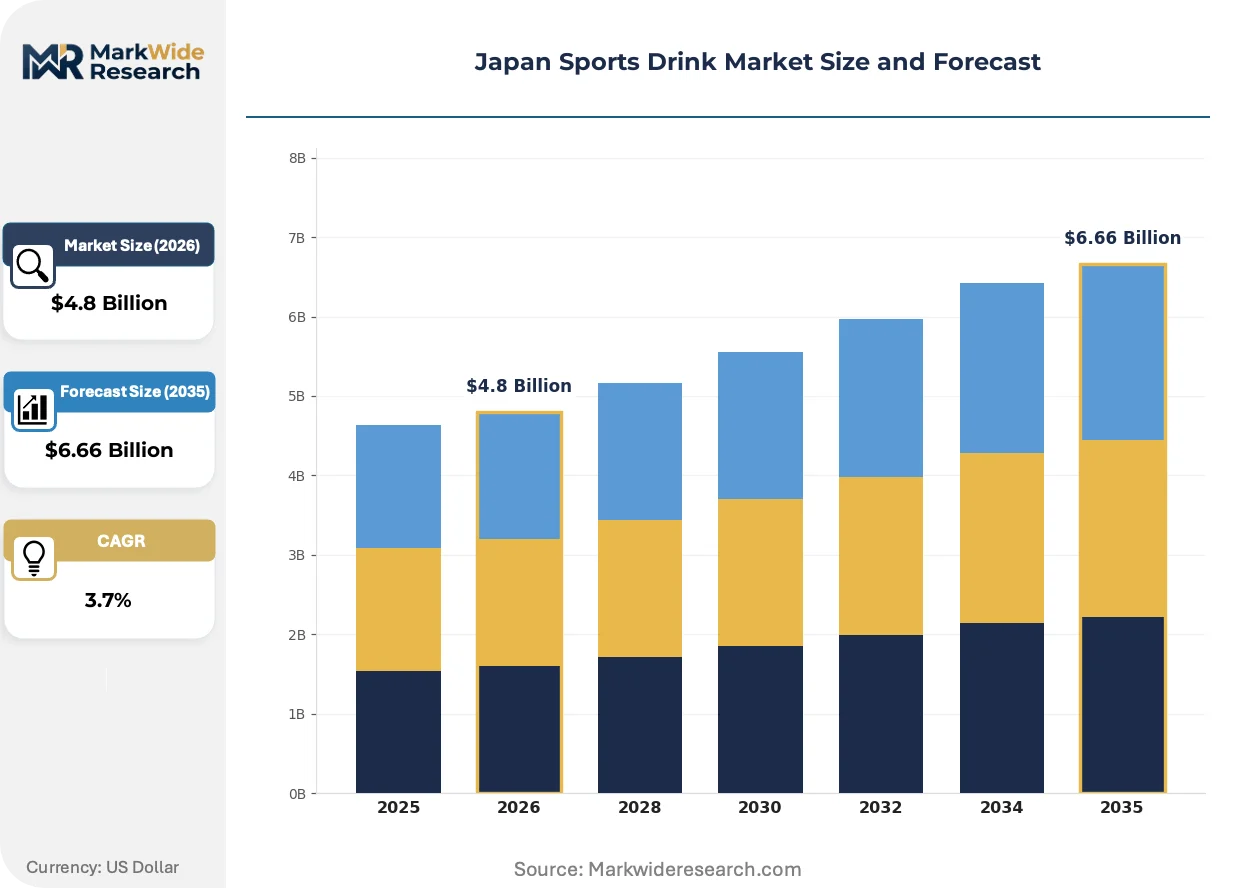
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypertonic, Hypotonic, Energy Drinks End User: Athletes, Fitness Enthusiasts, Casual Drinkers, Children Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Gyms Packaging Type: Bottles, Cans, Pouches, Tetra Packs |
| Companies Covered | The Asahi Group Holdings, Ltd., Otemon Co., Ltd., Otsuka Pharmaceutical Co., Ltd., Kirin Holdings Company, Limited, Taisho Pharmaceutical Co., Ltd., The Coca-Cola Company, Suntory Beverage & Food, Ajinomoto Co., Inc., Suntory Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Sports Drink Market Shifts & Advancements
Japanese sports drink innovation is converging on three vectors: electrolyte delivery science unbundled from sugar dependence, regulatory compliance as a product-design input, and channel-specific formulation tailored to ambient versus refrigerated distribution economics.
Electrolyte encapsulation technology using liposomal or nano-dispersion methods is rendering obsolete traditional osmolality-sacrifice tradeoffs between rapid absorption and taste acceptability. Fitness enthusiasts and clinical-hydration users in Tokyo's private gym networks are adopting these advanced formulations at rates exceeding conventional isotonics. The structural consequence is compressing R&D timelines as brands race to patent proprietary mineral-stabilization processes before competitor replication.
METI's Health Promotion Act amendments and Consumer Affairs Agency nutrient-function standards are mandating transparent electrolyte disclosure while constraining permissible sugar claims. Japanese manufacturers must now validate functional statements through clinical substantiation or downgrade to generic beverage positioning. The quasi-drug segment faces the steepest compliance burden, with PMDA oversight extending approval cycles for brands seeking therapeutic-hydration status.
Convenience-store operators are unbundling after-sales service from product margin through data-driven replenishment partnerships with beverage suppliers. Regional chains in Hokkaido and Kyushu are replacing traditional distributor relationships with direct-to-retail telemetry systems that optimize shelf rotation based on real-time consumption velocity. This pattern is most visible in suburban Tokyo corridors where commuter traffic patterns create predictable demand spikes that legacy distribution networks fail to capture.
Japan Sports Drink Market Segmentation
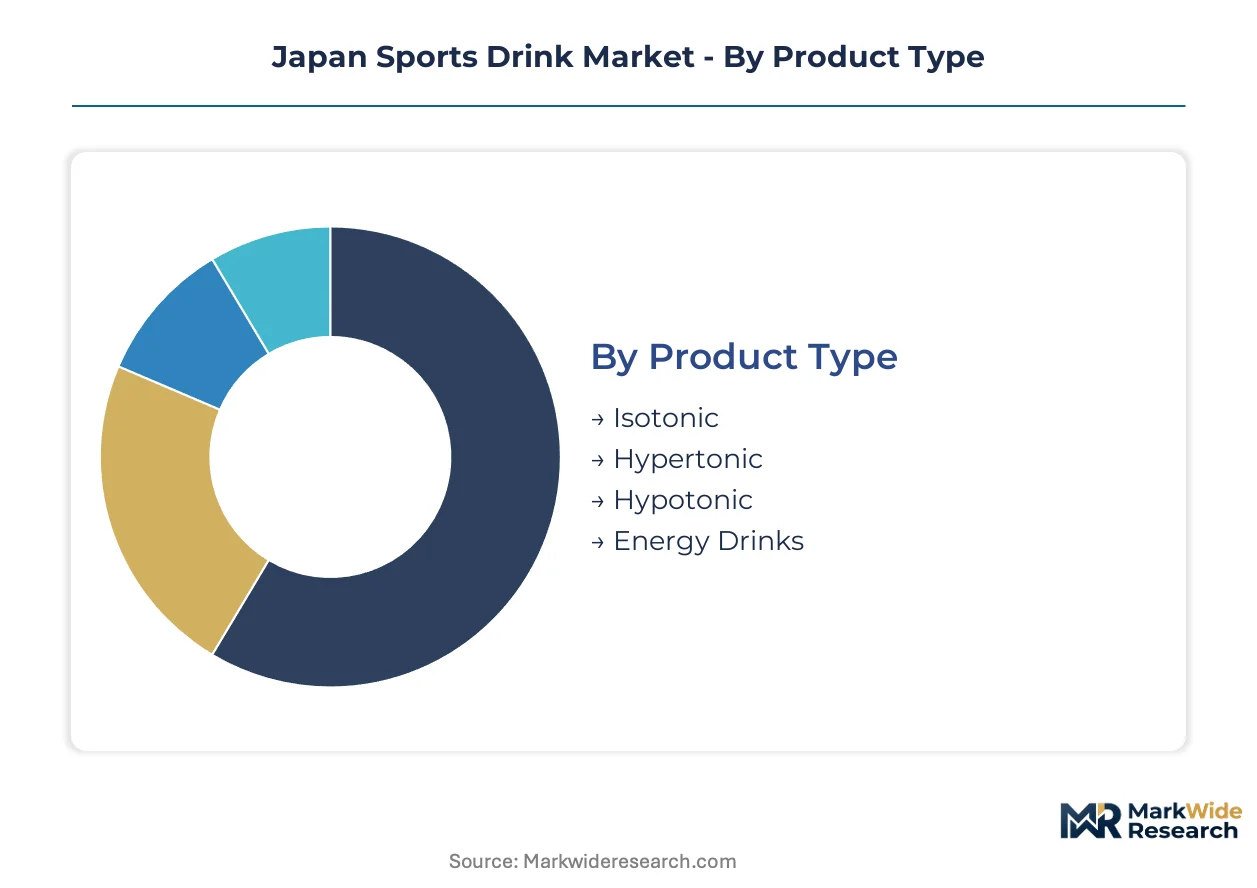
Japan's sports drink segmentation reflects divergent hydration science, consumption rituals, and channel economics. Manufacturers calibrate osmolality, electrolyte density, and packaging format to match distinct user physiology and purchase contexts across the archipelago.
Product Type:
Mature isotonic formulations coexist with emerging hypotonic variants as METI sugar-reduction mandates reshape formulation priorities.
- Isotonic:Osmotic pressure equivalence with blood plasma enables rapid gastric emptying without digestive distress. Greater Tokyo's commuter gyms and weekend cycling clubs sustain the highest per-capita consumption, though reformulation costs are compressing margins as manufacturers eliminate high-fructose corn syrup.
- Hypotonic:Reduced solute concentration accelerates intestinal absorption for casual hydration without residual sweetness. Osaka-Kobe metropolitan expansion and elderly consumer adoption in suburban Saitama are driving segment growth faster than athlete-focused alternatives.
- Hypertonic:Concentrated carbohydrate delivery targets endurance specialists during ultra-distance events.
- Energy Drinks:Caffeine and amino-acid fortification commands premium shelf positioning against commodity electrolyte products.
Isotonic retains volume leadership; hypotonic holds the steepest expansion curve.
End User:
Customer archetypes span performance-driven athletes to convenience-seeking office workers, each demanding distinct electrolyte profiles and packaging formats.
- Fitness Enthusiasts:Post-pandemic exercise habit solidification has expanded this cohort beyond competitive athletes into daily hydration rituals. Private gym networks in Tokyo's Shibuya and Shinjuku wards are adopting advanced electrolyte encapsulation formulations at rates exceeding conventional isotonics.
- Athletes:Institutional procurement through university sports federations and professional team supply contracts sustains volume baseline despite slower growth.
- Casual Drinkers:Office workers seeking afternoon refreshment without sugar crash are migrating from carbonated soft drinks to lighter hypotonic options.
- Children:School-sanctioned hydration and pediatric electrolyte needs drive specialized lower-sodium formulations.
Fitness enthusiasts command the fastest-growing demand pool; athletes anchor institutional revenue stability.
Distribution Channel:
Channel selection determines temperature requirements, impulse purchase potential, and inventory velocity across Japan's dense retail landscape.
- Convenience Stores:Japan's 55,000-plus konbini locations provide ambient-cooled shelf access unmatched by supermarket bulk buying. Real-time replenishment telemetry in suburban Tokyo corridors now optimizes shelf rotation based on commuter traffic patterns.
- Supermarkets:Multi-pack purchasing and family-size formats dominate household stock-up occasions.
- Online Retailers:Subscription models for specialized endurance formulations bypass conventional distribution markups.
- Gyms:Post-workout impulse consumption and branded cooler placements capture high-margin single-serve sales.
Convenience stores generate the highest transaction frequency; online channels are climbing fastest in subscription penetration.
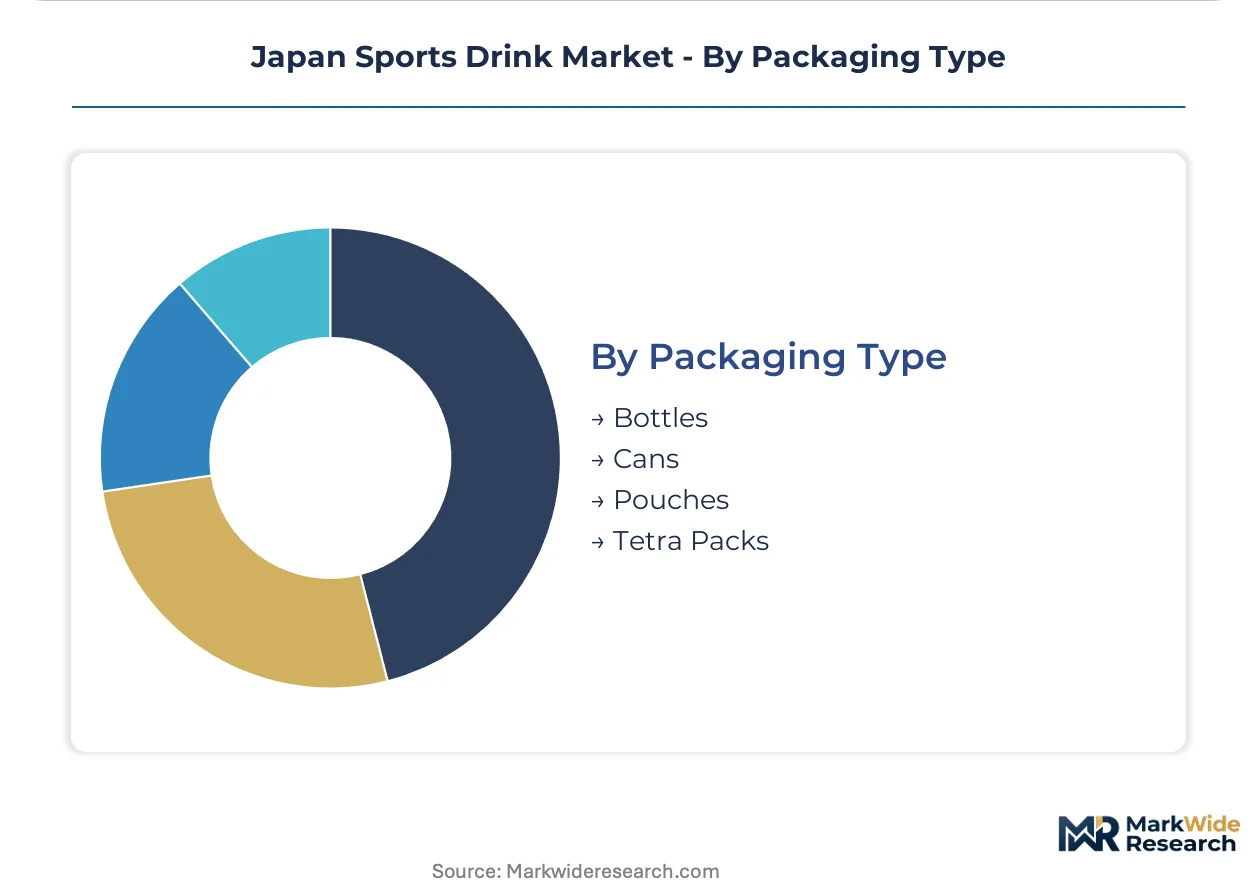
Packaging Type:
Material selection balances F-Gas Regulation compliance costs against shelf stability and consumer handling preferences.
- Bottles:PET dominance faces pressure from refrigeration-dependent distribution economics. Kanto industrial belt concentration creates geographic vulnerability to seismic disruption.
- Pouches:Ambient-stable formats bypass cold-chain dependency and reduce logistics carbon intensity.
- Cans:Aluminum recycling infrastructure supports circular economy positioning for premium energy drink variants.
- Tetra Packs:Aseptic carton manufacturing enables extended shelf life without preservative additives.
Bottles retain volume leadership; pouches are gaining share fastest as F-Gas compliance redirects capital toward ambient-stable innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's Health Promotion Act amendments anchor regulatory direction across Japan's archipelago, with consumption intensity varying sharply between metropolitan corridors and peripheral prefectures. Regional divergence reflects commuter density, industrial clustering, and aging demographics.
Kanto/Tokyo
Greater Tokyo generates the highest per-capita sports drink consumption nationwide through dense convenience-store grids and post-pandemic fitness normalization. METI's sugar-reduction mandates accelerate reformulation investment among Kanto-based manufacturers. The Shibuya-Shinjuku private gym corridor drives adoption of advanced electrolyte encapsulation technologies.
Kansai/Osaka
Osaka-Kobe metropolitan consumption trails Tokyo by approximately one-quarter, presenting white-space expansion potential for localized distribution infrastructure. Consumer Affairs Agency labeling compliance creates uniform regulatory friction across Kansai production facilities. The Hanshin industrial belt concentrates PET bottle manufacturing, creating geographic supply vulnerability.
Chubu/Nagoya
Automotive sector shift workers sustain steady isotonic demand through institutional procurement channels. PMDA quasi-drug classification requirements delay functional-positioning approvals for Chubu-based brands. Nagoya's logistics hub status supports efficient replenishment telemetry integration with regional convenience chains.
Kyushu
Subtropical climate conditions elevate baseline hydration needs among outdoor laborers and elderly populations. F-Gas Regulation compliance costs for refrigerated distribution compress profit margins in Kyushu's dispersed retail geography. Fukuoka's emerging startup ecosystem incubates ambient-stable packaging innovations bypassing cold-chain dependency.
Hokkaido
Extended winter sports seasons sustain concentrated demand among ski resort operators and cold-weather endurance athletes. Agricultural input inflation pressures natural flavor extraction costs for Hokkaido-sourced botanical ingredients. Sapporo's regional beverage distributors pioneer direct-to-retail telemetry systems optimizing shelf rotation.
Japan Sports Drink Market Competitive Landscape
Pharmaceutical-origin specialists and diversified beverage conglomerates split the market between clinical-hydration credibility and mass-market distribution muscle. The competitive structure concentrates around three strategic archetypes: electrolyte science specialists leveraging decades of clinical validation, diversified beverage groups exploiting cross-category functional positioning, and global soft-drink giants deploying capital-intensive shelf-space acquisition. Dominant competitive moves include backward integration into purified water sourcing and strategic partnerships with convenience-store operators for real-time replenishment telemetry.
Among pharmaceutical-origin specialists, Otsuka Pharmaceutical Co., Ltd. exemplifies clinical-hydration heritage, while Kirin Holdings Company, Limited and Suntory Beverage & Food occupy positions within the diversified beverage conglomerate tier. These three entities anchor distinct competitive vectors: Otsuka represents electrolyte science depth, Kirin embodies functional-beverage crossover experimentation, and Suntory leverages national distribution infrastructure. The Coca-Cola Company provides the global soft-drink archetype, though its Japan operations compete within a regulatory framework distinct from its home-market experience. Smaller specialists including Taisho Pharmaceutical Co., Ltd. and Ajinomoto Co., Inc. occupy niche positioning within specific channel or demographic segments.
| Leading Market Players |
|---|
| The Asahi Group Holdings, Ltd. |
| Otemon Co., Ltd. |
| Otsuka Pharmaceutical Co., Ltd. |
| Kirin Holdings Company, Limited |
| Taisho Pharmaceutical Co., Ltd. |
| The Coca-Cola Company |
| Suntory Beverage & Food |
| Ajinomoto Co., Inc. |
| Suntory Holdings Limited |
| Others |
Supply & Pricing Matrix
Kanto industrial belt concentration of PET bottle and aseptic carton manufacturing clusters feeds directly into margin distribution between packaging suppliers and beverage brands. Pricing power accrues to converters with seismic-resilient multi-site footprints while brands absorb logistics congestion risk through contract terms.
Pricing Analysis
Greater Tokyo convenience-store shelves command premium positioning against Osaka-Kobe metropolitan corridors where consumption trails by roughly one-quarter. Three-tier pricing structure across premium encapsulated electrolyte formulations, standard isotonic commodities, and economy private-label options stratifies by functional claim intensity. Pricing pressure stems from METI sugar-reduction mandates forcing reformulation investment without commensurate price elasticity recovery. Casual drinkers in suburban Saitama exhibit highest price sensitivity; endurance specialists purchasing hypertonic variants through gym channels show least.
Supply Chain Analysis
Extended payment terms from national convenience-store operators now reach 90-120 days, forcing suppliers into supply-chain finance facilities backed by regional banking consortia. Purified water sourcing draws from Kanto and Kansai industrial belt treatment facilities; natural flavor extraction hinges on Hokkaido agricultural inputs and Kyushu subtropical botanicals. Single-source vulnerability concentrates in Kanto PET manufacturing clusters exposed to seismic disruption. Distribution runs through 55,000-plus konbini locations with real-time replenishment telemetry displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through convenience-store consolidation and data-driven replenishment partnerships that unbundle after-sales service from product margin. Three national konbini chains now control shelf access for single-serve formats.
For Market Incumbents: Insulate electrolyte formulation expertise through captive R&D talent pools and patent-protected mineral-stabilization processes before competitor replication compresses differentiation. METI's Health Promotion Act amendments threaten margin recovery timelines; backward integration into purified water sourcing secures input cost control against agricultural inflation. Priority lever sits with ambient-stable packaging innovation bypassing F-Gas Regulation compliance costs.
For New Entrants and Emerging Players: Osaka-Kobe metropolitan underpenetration presents white-space expansion potential where consumption rates trail Tokyo by approximately one-quarter. Elderly hydration needs in suburban Saitama and Kyushu's dispersed retail geography offer penetrable segments outside incumbent strongholds. Go-to-market angle centers on hypotonic casual positioning targeting office workers seeking lighter hydration without residual sweetness.
For Investors and Strategic Acquirers: Capital is best deployed toward pharmaceutical-origin specialists with decades of clinical-hydration validation and existing PMDA quasi-drug classification expertise. Long-term viability over the next decade rests on regulatory moats deepening as Consumer Affairs Agency labeling compliance extends validation timelines. Signal to watch: convenience-store operators consolidating replenishment telemetry partnerships with direct-to-retail systems that bypass legacy distribution networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Encapsulation Patent Filing | Liposomal mineral-stabilization processes secure 8-14 month launch advantage before PMDA compliance bottlenecks competitors. |
| Ambient-Stable Packaging Launch | Pouch and carton formats bypass F-Gas Regulation refrigeration costs in Kyushu's dispersed retail geography. |
| Direct-to-Retail Telemetry Partnership | Real-time replenishment systems with suburban Tokyo konbini chains optimize shelf rotation against commuter traffic patterns. |
| Hypotonic Formulation Extension | Reduced osmolality products capture elderly consumers in Osaka-Kobe corridor seeking lighter hydration alternatives. |
| Backward Integration into Water Sourcing | Captive reverse-osmosis facilities in Kanto industrial belt insulate against energy-intensive processing cost volatility. |
Research Methodology
A spread of perspectives from brand managers at diversified beverage conglomerates, category buyers at national convenience-store chains, electrolyte formulation scientists, and supply planners at PET packaging converters converged on the working assumptions. Secondary validation drew from METI regulatory filings, Consumer Affairs Agency nutrient-function labeling standards, PMDA quasi-drug classification databases, and customs records tracking purified water treatment equipment imports. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity models.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with consumption velocity at konbini locations cross-referenced against manufacturing capacity in Kanto and Kansai industrial belts. Segmentation dimensions modeled included osmolality tier, end-user archetype, distribution channel temperature requirement, and regional regulatory cluster. CAGRs derived from elasticity-adjusted trend extrapolation incorporating METI sugar-reduction mandate implementation timelines and F-Gas Regulation compliance cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global soft-drink giants deploying capital-intensive shelf-space acquisition would shift outcomes. Macroeconomic deviation in agricultural input costs, regulatory acceleration of electrolyte disclosure requirements, or breakthrough encapsulation technology licensing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
United Kingdom Sports Drink Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
GLA Supplements Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
Medicated Fitness Supplements Market