
 Dimethicone Market | 2026-2036
Dimethicone Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethicone Market Analysis
Pharmaceutical-grade specification upgrades is rotating demand toward higher-purity dimethicone across medical and cosmetic applications. Dow Chemical Company leverages backward integration into silicone feedstock to sustain cost discipline at scale. Wacker Chemie AG anchors European supply through specialized silicone oil production in Germany. Shin-Etsu Chemical Co., Ltd. dominates ultra-high-purity grades for semiconductor-adjacent personal care markets in Asia.
Dimethicone is a polydimethylsiloxane silicone polymer with viscosity ranging from 0.65 to 100,000 centistokes, manufactured through hydrolysis and polymerization of dimethyldichlorosilane. It functions primarily as a skin protectant, emollient, and conditioning agent across topical formulations and industrial coatings. Silicone oil leads product type revenue due to its versatility in hair care and skin care formulations, while emulsion grades capture expanding pharmaceutical demand for water-dispersible delivery systems. Hair care and skin care applications concentrate margin pools through premium positioning in professional salon and dermatological channels.
FDA monograph requirements for skin protectant drug products and REACH registration obligations for silicone substances in Europe constrain market entry for sub-scale producers. China's NMPA and GB standards for cosmetic raw materials impose additional testing protocols on imported dimethicone. India's CDSCO and BIS certification pathways for pharmaceutical-grade silicones create compliance layering for multinational suppliers. Stakeholders must monitor regulatory divergence between cosmetic and pharmaceutical classification regimes to anticipate reformulation costs and sourcing shifts.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing the supplier base as REACH and FDA specifications tighten concurrently, forcing reformulation investments across cosmetic and medical channels.
Growth Catalysts
- Wound care protocols:Hospital systems in Germany and the United States are expanding silicone-based occlusive dressing use for burn and surgical wound management, pulling higher-viscosity dimethicone grades into institutional procurement.
- REACH registration deadlines:ECHA's 2023-2027 substance evaluation cycles are accelerating substitution away from cyclic silicones toward linear dimethicone polymers in European personal care manufacturing.
- China's NMPA cosmetic raw material reforms:Domestic formulators in Shanghai and Guangzhou are qualifying local dimethicone supply chains to reduce import dependency for mass-market skin care brands.
Market Restraints
- Siloxane feedstock concentration:Methyl chloride and silicon metal supply clusters in China's Xinjiang and Yunnan provinces create geographic vulnerability for non-integrated formulators.
- Technical substitution limits:Natural emollients and hydrocarbon alternatives fail to replicate dimethicone's spreadability and volatility profile in high-performance hair serums.
- Regulatory friction from dual classification:Products crossing cosmetic and medical device boundaries face divergent FDA monograph and EU MDR compliance pathways, extending time-to-market.
Strategic Opportunities
- India's CDSCO pharmaceutical-grade pathway:Multinational suppliers can capture generic topical drug formulation demand as domestic production scales under PLI scheme incentives.
- Water-dispersible emulsion innovation:Silicone-in-water systems enable clean-label positioning in Southeast Asian skin care markets where rinse-off applications dominate.
- ISO 10993 biocompatibility convergence:Harmonized testing standards for medical device silicones reduce redundant certification costs across US and EU markets.
Industry Challenges
- Specialized polymerization expertise scarcity:Hydrolysis process optimization for ultra-low residual siloxane grades requires chemists with organosilicon synthesis experience concentrated at legacy production sites.
- Multi-jurisdiction certification timelines:Parallel FDA drug master file and REACH dossier preparation stretches regulatory affairs capacity for mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethicone Market |
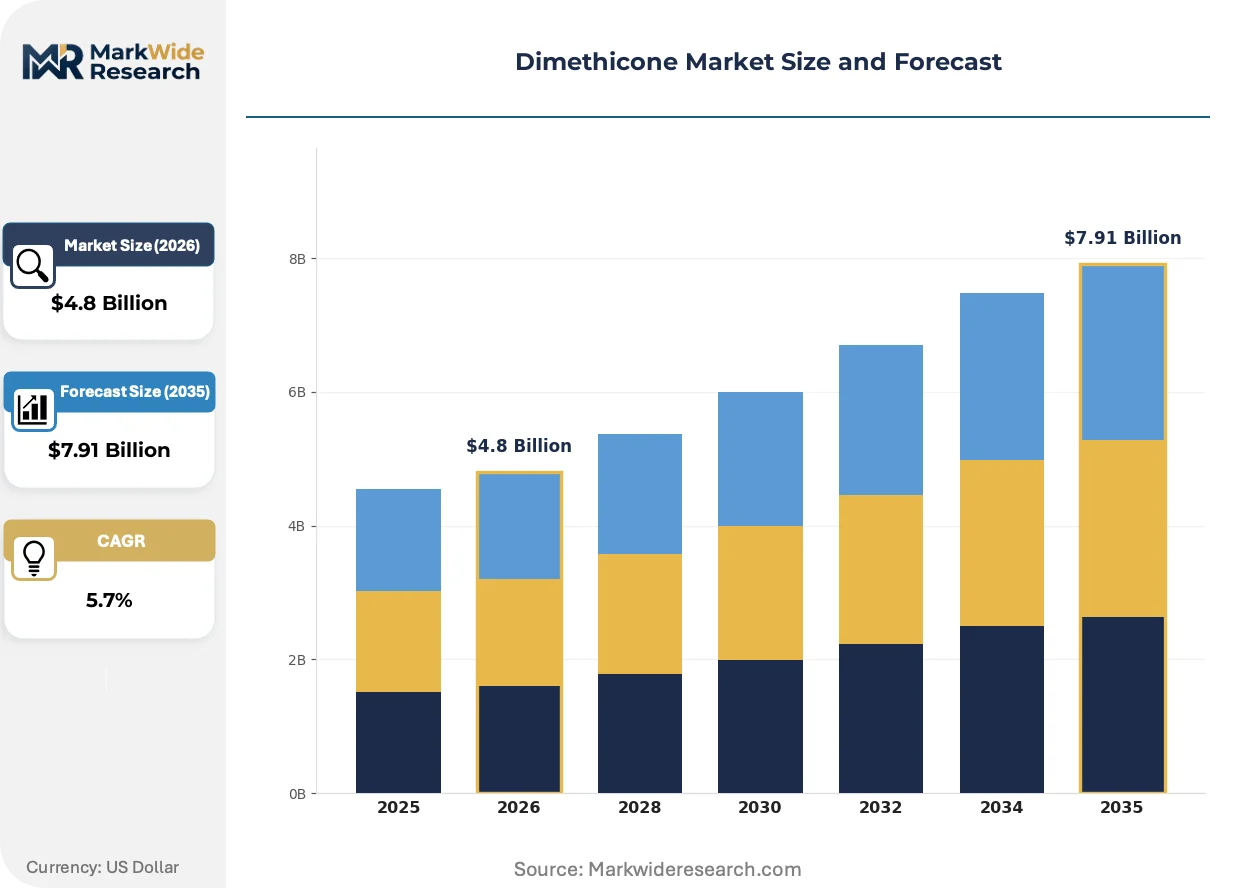
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Oil, Emulsion, Foam, Gel End Use Industry: Personal Care, Pharmaceuticals, Automotive, Construction Form: Liquid, Cream, Powder, Paste Application: Hair Care, Skin Care, Antifogging Agent, Surface Coating |
| Companies Covered | Evonik Industries AG, Elkem Silicones, Dow Chemical Company, ADEKA Corporation, TORAY SILICONES, Wacker Chemie AG, Momentive Performance Materials Inc., KCC Corporation, Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethicone Market Emerging Trajectories
Dimethicone functionality is fragmenting across performance tiers as cosmetic chemists and pharmaceutical formulators diverge in purity requirements and delivery system preferences.
Silicone elastomer gel technology is bifurcating the texture modifier segment. Cross-linked dimethicone networks deliver cushion and optical blurring in color cosmetics. Premium Korean and Japanese brands are adopting these at accelerated rates. The technology is compressing conventional silicone fluid volumes in prestige foundation and primer categories.
REACH restriction proposals for low molecular weight siloxanes are tightening supply chain documentation obligations. Downstream personal care manufacturers must now certify dimethicone feedstock molecular weight distributions. German and French formulators are consolidating supplier relationships to reduce audit burden.
Clean beauty procurement criteria are displacing traditional specification-based purchasing. Retailers in California and New York now mandate full siloxane chain transparency. Indie brands are switching to fermentation-derived alternatives where performance thresholds permit, though dimethicone retains formulation share in professional salon channels.
Dimethicone Market Segmentation
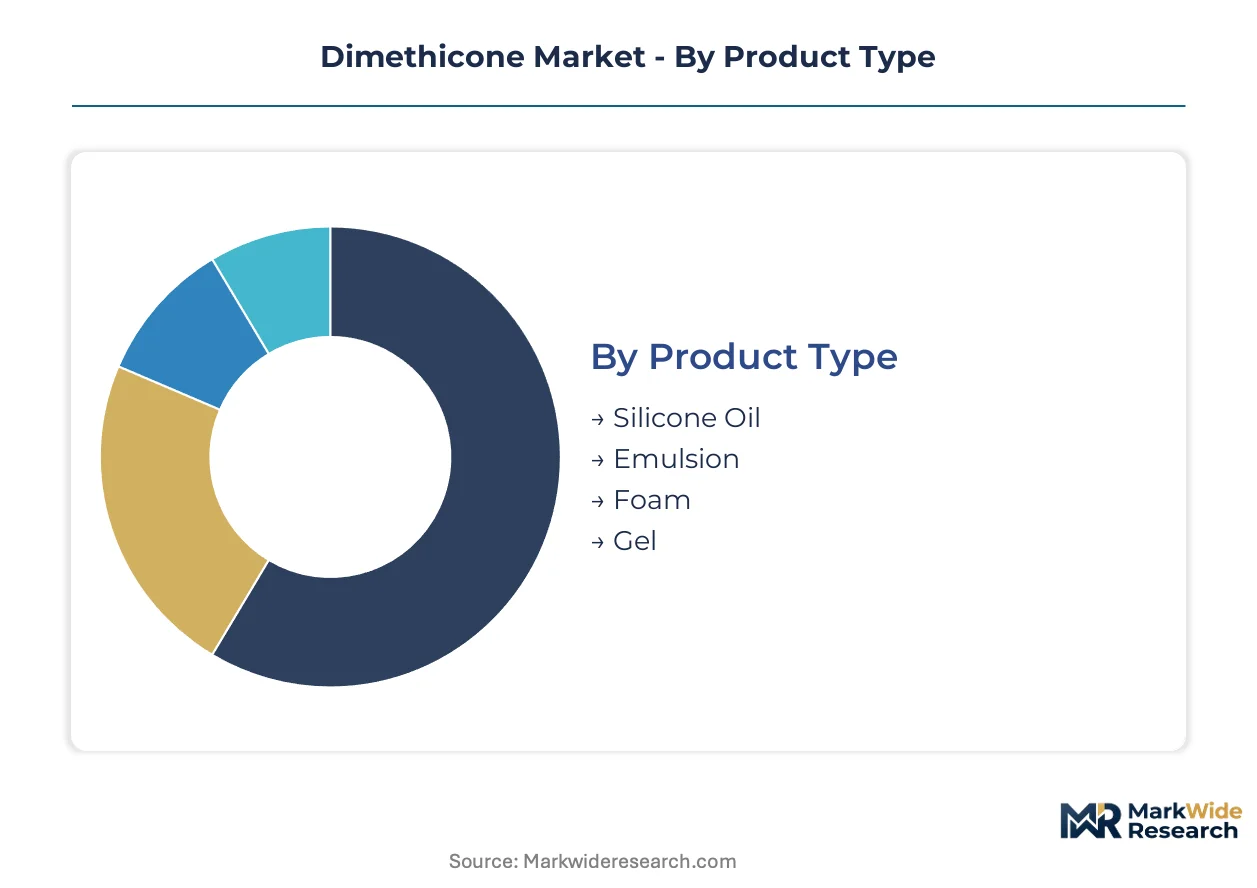
Dimethicone's functional versatility across viscosity grades and delivery formats creates distinct competitive arenas where substitution economics vary sharply. Formulators select product types and physical forms based on regulatory classification thresholds and end-use performance requirements rather than commodity pricing alone.
Product Type:
Silicone oil faces the most intense substitution pressure from bio-based emollients in mass-market personal care, while specialized formats maintain defensive positions through technical performance barriers.
- Silicone Oil:Linear polydimethylsiloxane polymers span 0.65 to 100,000 centistokes viscosity, serving as the foundational conditioning agent in hair serums and skin moisturizers. Demand concentrates in professional salon channels across the United States and Germany where spreadability and dry-down speed command formulation loyalty despite clean beauty pressures.
- Emulsion:Silicone-in-water or water-in-silicone systems enable pharmaceutical-grade wound care applications and rinse-off skin cleansers. China's NMPA cosmetic raw material reforms are accelerating domestic qualification of emulsion-grade supply chains for mass-market brands in Shanghai and Guangzhou.
- Foam:Aerosolized dimethicone delivery systems for topical medical devices and barrier sprays. FDA monograph compliance requirements constrain supplier participation in institutional procurement.
- Gel:Cross-linked elastomer networks providing optical blurring and cushion in color cosmetics. Korean and Japanese prestige brands are expanding adoption in foundation and primer categories.
Silicone oil retains volume leadership; emulsion holds the steepest expansion curve.
End Use Industry:
Margin structures diverge sharply between regulated medical channels and discretionary consumer segments, with automotive and construction applications commanding distinct specification tiers.
- Personal Care:Hair care and skin care formulations concentrate revenue through premium positioning in professional salon and dermatological channels. REACH registration deadlines are accelerating substitution away from cyclic silicones toward linear dimethicone polymers in European manufacturing.
- Pharmaceuticals:Wound care protocols in German and United States hospital systems are expanding silicone-based occlusive dressing use for burn and surgical wound management, pulling higher-viscosity grades into institutional procurement. CDSCO pharmaceutical-grade pathways in India and FDA drug master file requirements create compliance layering for multinational suppliers.
- Automotive:Lubricant and sealant applications requiring thermal stability across temperature extremes. Hydrocarbon alternatives compete on cost in non-critical assemblies.
- Construction:Waterproofing and sealant formulations where durability requirements limit substitution. GB standards in China impose additional testing protocols on imported material.
Personal care dominates value capture; pharmaceuticals is climbing the fastest.
Form:
Physical state determines handling infrastructure requirements and directly shapes distribution economics from production through compounding.
- Liquid:Standard viscosity silicone oils and low-viscosity fluids for bulk tanker delivery to personal care formulators. Tank farm infrastructure requirements favor established supply relationships.
- Cream:Pre-dispersed emulsion concentrates reducing manufacturing complexity for mid-scale cosmetic producers. Water-dispersible systems enable clean-label positioning in Southeast Asian rinse-off markets.
- Powder:Spray-dried dimethicone for dry shampoo and anhydrous color cosmetic applications. Particle size distribution controls sensory performance in finished goods.
- Paste:High-viscosity or filled systems for industrial sealant and adhesive compounding. Specialized mixing equipment requirements limit customer switching.
Liquid commands shipment volumes; cream formats are expanding most quickly.
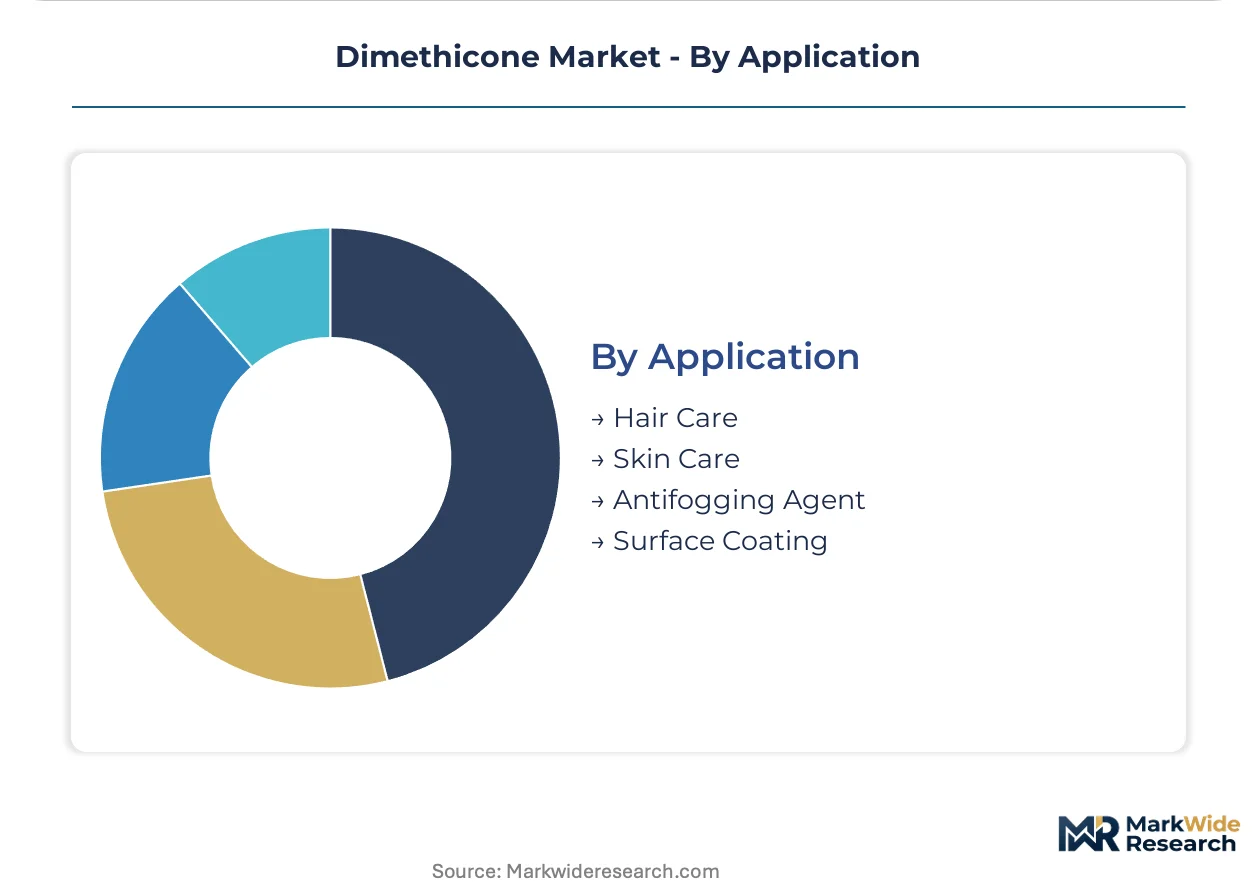
Application:
Performance requirements in functional applications create stickier demand than aesthetic categories where sensory substitution is technically feasible.
- Hair Care:Conditioning agents and heat protectants in shampoos, conditioners, and styling products. Professional salon channels in the United States and Germany maintain formulation loyalty based on stylist training and performance consistency.
- Skin Care:Emollients and occlusive agents in moisturizers, sunscreens, and topical pharmaceuticals. India's CDSCO pharmaceutical-grade pathway is attracting multinational suppliers to generic topical drug formulation demand.
- Antifogging Agent:Surface treatment for optical lenses, food packaging films, and safety equipment. ISO 10993 biocompatibility convergence reduces redundant certification costs across US and EU medical device markets.
- Surface Coating:Release coatings and protective films in industrial and consumer applications. Siloxane feedstock concentration in China's Xinjiang and Yunnan provinces creates geographic vulnerability for non-integrated formulators.
Hair care holds volume leadership; antifogging applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Siloxane feedstock clusters in China's Xinjiang and Yunnan provinces concentrate upstream supply, while downstream formulation demand fragments across pharmaceutical hubs in Germany, personal care corridors in the United States, and emerging generic drug manufacturing zones in India.
United States
Hospital systems in Texas and California are expanding silicone-based occlusive dressing procurement for burn and surgical wound management. FDA monograph requirements for skin protectant drug products constrain supplier participation in institutional channels. New Jersey and Pennsylvania host the densest concentrations of pharmaceutical formulation contractors qualifying dimethicone supply chains.
Germany
ECHA's 2023-2027 substance evaluation cycles are accelerating substitution away from cyclic silicones toward linear dimethicone polymers in European personal care manufacturing. REACH registration obligations for silicone substances impose documentation burdens on downstream formulators. The Cologne-Düsseldorf corridor anchors specialized silicone oil production for medical device and cosmetic applications.
China
NMPA cosmetic raw material reforms are accelerating domestic qualification of dimethicone supply chains for mass-market skin care brands in Shanghai and Guangzhou. GB standards for cosmetic raw materials impose additional testing protocols on imported material. The Yangtze River Delta concentrates domestic silicone production capacity expansion as local personal care brands scale formulation capabilities.
India
CDSCO pharmaceutical-grade pathways are attracting multinational suppliers to generic topical drug formulation demand as domestic production scales under PLI scheme incentives. BIS certification requirements for silicone substances create compliance layering for imported material. Maharashtra and Gujarat host the fastest-expanding contract manufacturing clusters for dermatological and wound care formulations.
Japan
PMDA pharmaceutical-grade specifications for medical device silicones drive demand for ultra-high-purity grades in semiconductor-adjacent personal care markets. METI industrial policy supports domestic silicone polymerization expertise retention. The Kansai region around Osaka maintains specialized production of low-residual siloxane grades for premium cosmetic applications.
Dimethicone Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the dimethicone market. The supplier base consolidates around integrated chemical conglomerates with captive siloxane feedstock, while specialized silicone divisions of larger materials groups occupy mid-tier positions. Two strategic archetypes dominate: backward-integrated petrochemical majors with in-house silicon metal and methyl chloride production, and technology-focused specialists with proprietary polymerization expertise. Capacity expansion in China's Xinjiang province and strategic partnerships for pharmaceutical-grade certification represent the dominant competitive vectors.
Among Germany-based chemical groups, Wacker Chemie AG exemplifies the European technology-specialist archetype with concentrated silicone oil production capabilities. Dow Chemical Company represents the integrated petrochemical major model with upstream control over silicone feedstock chains. Shin-Etsu Chemical Co., Ltd. anchors the ultra-high-purity specialist position for semiconductor-adjacent and medical-grade applications in Asia. These three companies illustrate the geographic and technological segmentation that structures competitive positioning across pharmaceutical, cosmetic, and industrial end-use segments.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Elkem Silicones |
| Dow Chemical Company |
| ADEKA Corporation |
| TORAY SILICONES |
| Wacker Chemie AG |
| Momentive Performance Materials Inc. |
| KCC Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Siloxane production scale economies in China's Xinjiang and Yunnan provinces compress unit costs for integrated manufacturers while establishing price floors that non-integrated formulators struggle to match, concentrating margin capture among backward-integrated petrochemical majors and forcing mid-tier suppliers toward specialty grade differentiation.
Pricing Analysis
REACH registration obligations and FDA drug master file requirements dictate the pricing tier structure across pharmaceutical, cosmetic, and industrial grades. Three-tier pricing structure across premium, standard, and economy levels separates ultra-high-purity medical device grades from cosmetic-grade emulsions and industrial sealant volumes. Cost compression in standard-grade silicone oil is intensifying because China's domestic capacity expansion enables local brands to negotiate volume contracts with qualified suppliers. Mass-market personal care formulators exhibit the highest price sensitivity, while hospital procurement systems for wound care applications prioritize biocompatibility certification over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg elevate inbound logistics costs for European formulators sourcing from Chinese siloxane clusters. Production gravity centers on China, Germany, and Japan, with methyl chloride and silicon metal feedstock drawing from coal-chemical complexes in Xinjiang and metallurgical-grade silicon in Yunnan. Supply chain risk stems from single-source vulnerability in high-purity polymerization expertise concentrated at legacy Japanese and German production sites. Distribution runs through bulk tanker networks for liquid grades and specialized cold-chain logistics for emulsion concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between cosmetic and pharmaceutical classification regimes fragments competitive terrain, creating specialized service and certification niches that favor focused players over diversified conglomerates.
For Market Incumbents: Consolidate supplier relationships with NMPA-qualified Chinese producers to secure cost-competitive emulsion grades for mass-market skin care brands. Deepen backward integration into silicon metal production to defend margin position against Xinjiang-based capacity expansions. Prioritize ISO 10993 biocompatibility certification investments to capture institutional wound care procurement in German and United States hospital systems.
For New Entrants and Emerging Players: Pharmaceutical-grade emulsion technical service gaps in India's Maharashtra and Gujarat contract manufacturing clusters offer immediate white-space opportunity. Target CDSCO certification support services for multinational suppliers navigating India's PLI scheme incentives. Pursue clean-label silicone-in-water system development for Southeast Asian rinse-off markets as the most penetrable application segment.
For Investors and Strategic Acquirers: Regional silicone oil specialists with captive pharmaceutical-grade certification pathways represent the most attractive acquisition target archetype for portfolio exposure to medical device and dermatological formulation growth. Long-term viability hinges on regulatory compliance capacity rather than commodity scale. Watch for ECHA restriction proposals on low molecular weight siloxanes as the critical inflection signal for substitution-driven demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Xinjiang coal-chemical complexes offer captive methyl chloride and metallurgical silicon cost advantages. |
| Pharmaceutical-Grade Certification Investment | CDSCO and FDA drug master file pathways unlock institutional wound care procurement in India and the United States. |
| Water-Dispersible Emulsion Development | Silicone-in-water systems enable clean-label positioning in Southeast Asian rinse-off skin care markets. |
| Regional Supply Chain Qualification | NMPA cosmetic raw material reforms reward domestic Chinese dimethicone sourcing for Shanghai and Guangzhou formulators. |
| Specialized Polymerization Expertise Retention | Hydrolysis process optimization for ultra-low residual siloxane grades concentrates at legacy German and Japanese production sites. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA registration dossiers, FDA drug master file submissions, and SEC 10-K filings from silicone producers. Primary interviews engaged plant managers at siloxane production facilities, procurement leads at personal care OEMs, regulatory affairs directors navigating REACH and NMPA compliance, and technical R&D directors optimizing polymerization processes. Bottom-up demand modeling triangulates against top-down supply capacity assessments across the analysis window.
Segmentation dimensions modeled include viscosity grade tier, end-use industry classification, physical form factor, and regional regulatory cluster. CAGRs derive from production capacity expansion timelines, formulation substitution elasticities, and certification pathway completion rates. Forecast inputs incorporate ECHA substance evaluation cycle timing, China's NMPA cosmetic raw material reform implementation pace, and India's PLI scheme incentive disbursement patterns.
Forecasts assume regulatory continuity in REACH, FDA, and NMPA regimes; material policy shifts would require re-modeling. Specific risks include ECHA restriction proposals on cyclic siloxanes, NMPA import testing protocol tightening, and CDSCO pharmaceutical-grade pathway delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Phosphonate Market