
 Phosgene Market | 2026-2036
Phosgene Market Size, Share, and Industry Trends Forecast 2026-2036
Phosgene Market Intelligence
New capacity additions in China for integrated isocyanate production is tilting the supply landscape towards Asia, creating regional supply-demand imbalances. Wanhua Chemical Group Co., Ltd. leverages its significant scale and captive supply of feedstocks to control costs in this region. In contrast, Covestro AG sustains its global position through advanced process technology and a focus on high-purity grades for specialty chemical applications. BASF SE operates with a balanced geographic footprint, serving both bulk and niche segments.
Phosgene is a highly reactive chemical intermediate, COCl2, produced by reacting carbon monoxide and chlorine gas over a porous activated carbon catalyst. Its industrial function is as a reagent for synthesizing organic compounds, especially isocyanates and polycarbonates. Demand from isocyanates production for the polyurethane industry represents the dominant application segment. The choice between product forms like gaseous or liquid phosgene often depends on scale, with large-scale users preferring on-site generation to improve safety.
The market operates under stringent oversight due to phosgene's acute toxicity, governed by the US EPA's hazardous substance rules and the EU's REACH framework. International controls under the Chemical Weapons Convention (CWC) also apply, restricting trade and mandating reporting. These regulations dictate containment protocols, directly influencing plant design and operational costs. The development of phosgene-free synthesis routes for isocyanates remains a critical technology trend to watch.
Market Dynamics
The market's central dynamic is the tension between the geographic concentration of production capacity in Asia and the intensifying global regulatory pressure for inherently safer processes. This conflict shapes investment in on-site generation versus large-scale merchant supply chains.
Growth Catalysts
- Polyurethane Demand:Sustained consumption of isocyanates for polyurethane foams in the global automotive and construction industries provides foundational demand, particularly for MDI and TDI production.
- Integrated Production Hubs:The development of large-scale, integrated chemical parks in China allows for efficient, captive supply of phosgene, lowering feedstock costs for co-located isocyanate and polycarbonate plants.
- On-Site Generation Technology:Advances in modular, small-scale phosgene generators improve safety by minimizing storage and transport, enabling its use in specialty chemical applications that were previously inaccessible due to risk.
Market Restraints
- International Treaty Obligations:The Chemical Weapons Convention (CWC) classifies phosgene as a Schedule 3 substance, imposing strict declaration, verification, and trade restriction protocols that increase compliance costs.
- Phosgene-Free Synthesis Routes:The development and industrialization of alternative, non-phosgenation pathways to produce isocyanates present a long-term substitution threat, driven by environmental and safety concerns.
- High Containment Costs:Stringent regulations from bodies like the US EPA and EU's ECHA mandate extensive capital investment in advanced containment systems, leak detection, and emergency response infrastructure.
Strategic Opportunities
- High-Purity Grades:Expanding applications for high-purity phosgene derivatives in the pharmaceutical and agrochemical sectors offer avenues for value-added product differentiation beyond bulk isocyanates.
- Microreactor Technology:The convergence of microfluidics with continuous flow chemistry enables the creation of highly controlled, small-footprint phosgene production systems, opening new possibilities for point-of-use synthesis.
- Emerging Chemical Sectors:Building out domestic chemical value chains in regions like Southeast Asia and India creates opportunities to supply technology and establish production for nascent polyurethane industries.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of chemical engineers and plant operators with the specific training and experience required to safely manage highly toxic chemical processes and associated control systems.
- Legacy Asset Modernization:The significant capital expenditure required to retrofit older production facilities to meet evolving ISO safety standards and local environmental, health, and safety (EHS) mandates.
- Complex Compliance Verification:Navigating the intricate and time-consuming process of auditing, documenting, and reporting production and consumption data to national authorities under the CWC framework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosgene Market |
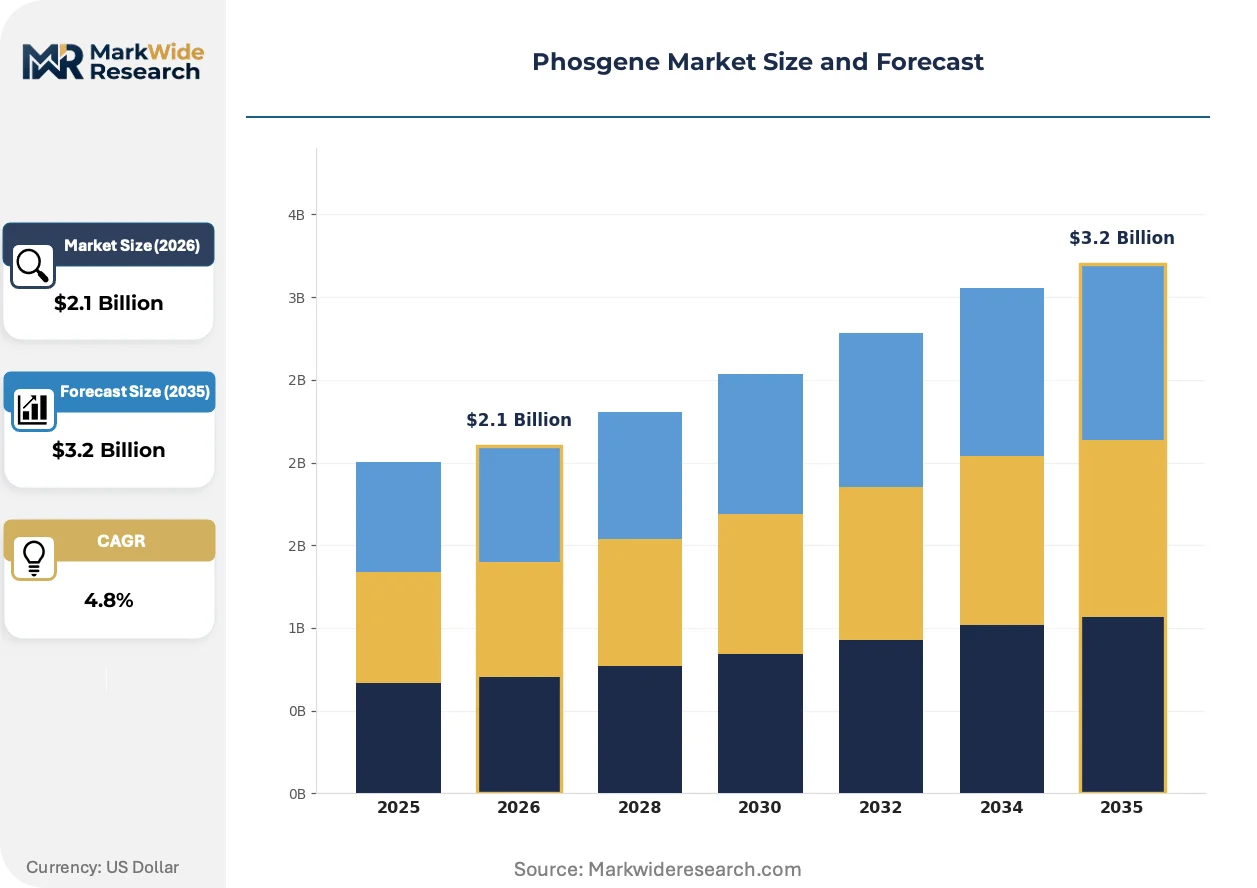
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Phosgene, Gaseous Phosgene, Solution Form, Stabilized Phosgene Application: Isocyanates Production, Agrochemicals Synthesis, Pharmaceuticals Manufacturing, Dye Intermediates, Pesticide Formulation End User Industry: Chemical Manufacturing, Specialty Chemicals, Crop Protection, Fine Chemicals, Laboratory Research Packaging Type: Steel Cylinders, High-Pressure Tanks, ISO Containers, Cryogenic Vessels |
| Companies Covered | Huntsman Corporation, VanDeMark Chemical Inc., BASF SE, Paushak Ltd., Altivia, Covestro AG, Wanhua Chemical Group Co., Ltd., Synthesia a.s., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosgene Market Strategic Shifts & Innovations
Technological innovation and regulatory pressures are compelling a fundamental re-evaluation of how phosgene is produced, handled, and used. The industry is moving towards systems that minimize human exposure and reduce the consequence of potential release events through process intensification and digitalization.
Advanced process simulation and digital twin technology provide a virtual model of phosgenation reactors and containment systems. Large-scale chemical manufacturers in Germany, Japan, and the United States adopt these tools for initial plant design, operator training, and stress-testing safety protocols. The use of these sophisticated models is virtualizing physical commissioning steps, significantly reducing risks associated with plant startups and process modifications.
The European Union's REACH framework continues to exert pressure on chemical supply chains by scrutinizing substances of very high concern. This regulation imposes a significant burden for data generation and risk assessment on both phosgene producers and their customers operating within the EU. The polycarbonate and specialty isocyanate segments are most affected, accelerating research into non-phosgene synthesis routes to align with long-term substitution objectives.
A shift from transactional purchasing to long-term "tolling" agreements for phosgene supply is becoming more prevalent among major chemical producers. Under this model, an isocyanate manufacturer provides feedstock to a co-located phosgene specialist, paying a fee for the chemical conversion service rather than purchasing the phosgene itself. This trend is most advanced in integrated chemical parks along the US Gulf Coast and in China.
Phosgene Market Segmentation
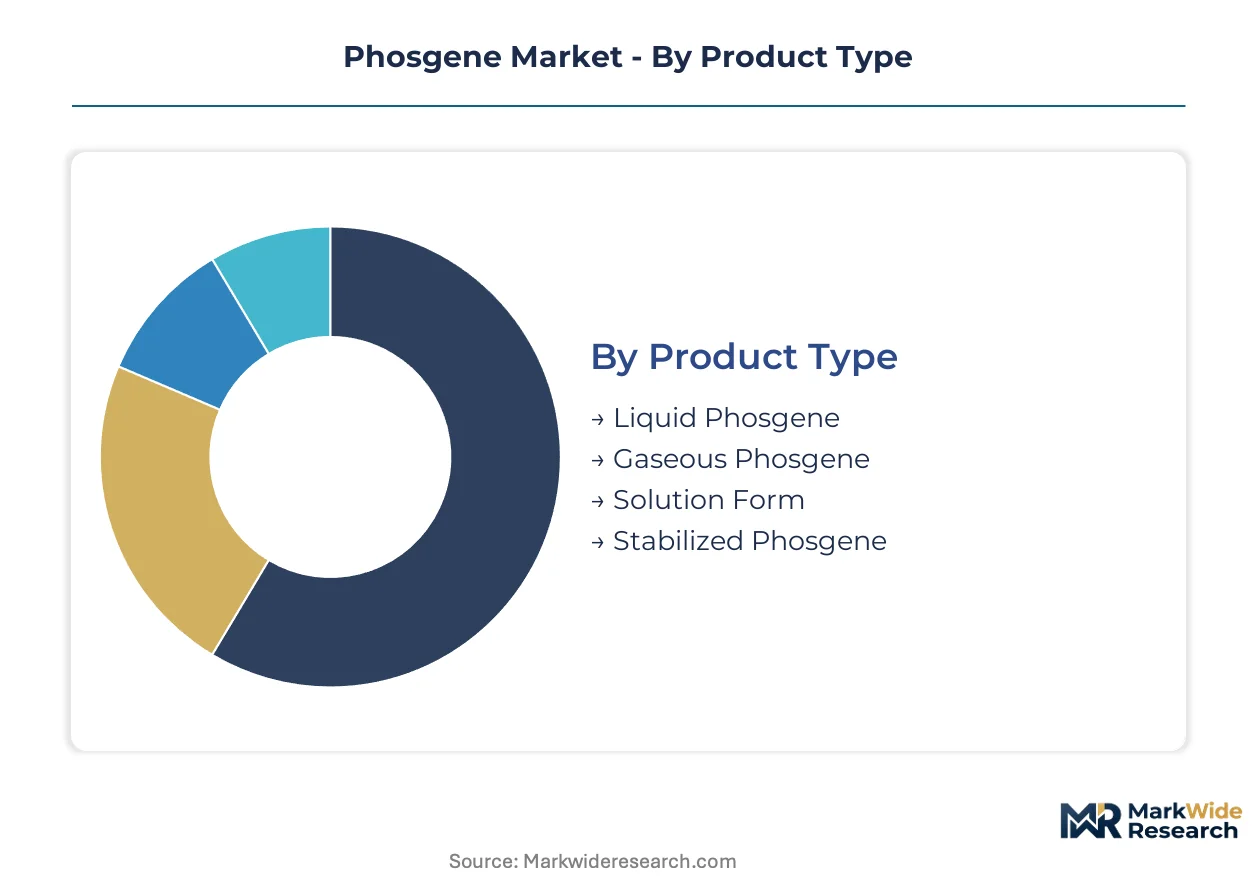
The Phosgene Market segmentation reveals the diverse forms and applications driving its industrial use. This analysis highlights how different product types and end-user industries influence supply chain dynamics and regulatory compliance. Understanding these segments is crucial for navigating the market's complex operational landscape.
Product Type:
The various phosgene product forms exhibit distinct production and consumption cycle times, reflecting their stability and handling requirements.
- Gaseous Phosgene:This highly reactive form is typically generated on-site at chemical facilities, minimizing transport and storage risks. Its rapid consumption in integrated isocyanate production lines in China drives immediate demand, reflecting a fast inventory turnover.
- Liquid Phosgene:Stored under pressure, this form facilitates transport to off-site users for various synthesis reactions. Demand for liquid phosgene supports smaller-scale specialty chemical manufacturing in Europe, where on-site generation is less prevalent.
- Solution Form:Phosgene dissolved in inert solvents offers improved handling safety for specific batch reactions in pharmaceutical synthesis.
- Stabilized Phosgene:Additives enhance the shelf life of this phosgene variant, primarily for laboratory research and niche fine chemical applications.
Gaseous phosgene dominates the installed production base for large-scale operations. Liquid phosgene is where expansion concentrates for merchant supply to diverse end-users.
Application:
Phosgene's utility spans multiple chemical synthesis pathways, with each application segment demanding specific purity levels and handling protocols.
- Isocyanates Production:This segment represents the largest consumption of phosgene, serving as a key intermediate for MDI and TDI in polyurethane manufacturing. Large integrated chemical complexes in China drive this demand, benefiting from captive phosgene supply.
- Pharmaceuticals Manufacturing:Phosgene acts as a crucial reagent for synthesizing a wide array of active pharmaceutical ingredients and intermediates. Strict purity requirements and batch-specific production characterize demand from specialized facilities in Germany.
- Agrochemicals Synthesis:Phosgene derivatives are essential for creating various herbicides, insecticides, and fungicides in the crop protection industry.
- Dye Intermediates:This segment utilizes phosgene for manufacturing precursors to industrial dyes, serving textiles and other coloring applications.
- Pesticide Formulation:Phosgene is used in the chemical processes to formulate specific pesticide compounds for agricultural pest control.
Isocyanates production drives the highest volume demand, while pharmaceutical manufacturing provides premium margin opportunities due to stringent quality needs.
End User Industry:
End-user industries vary significantly in their scale of phosgene consumption and the complexity of their regulatory compliance frameworks.
- Chemical Manufacturing:This segment encompasses large-scale producers of isocyanates and polycarbonates, often with integrated phosgene production facilities. Companies like Wanhua Chemical Group in China exemplify this model, achieving cost efficiencies through scale.
- Specialty Chemicals:Manufacturers in this sector require phosgene for complex synthesis routes to high-value products like advanced polymers and performance additives. European specialty chemical firms often rely on external phosgene suppliers or smaller on-site units.
- Crop Protection:This industry uses phosgene derivatives to produce agricultural chemicals that safeguard crops from pests and diseases.
- Fine Chemicals:Producers of fine chemicals utilize phosgene for highly specific, often multi-step, synthesis reactions for diverse applications.
- Laboratory Research:Academic and industrial laboratories consume small quantities of phosgene for experimental synthesis and material science studies.
Chemical manufacturing remains the volume backbone, while the specialty chemicals sector is expanding most quickly due to new product development.
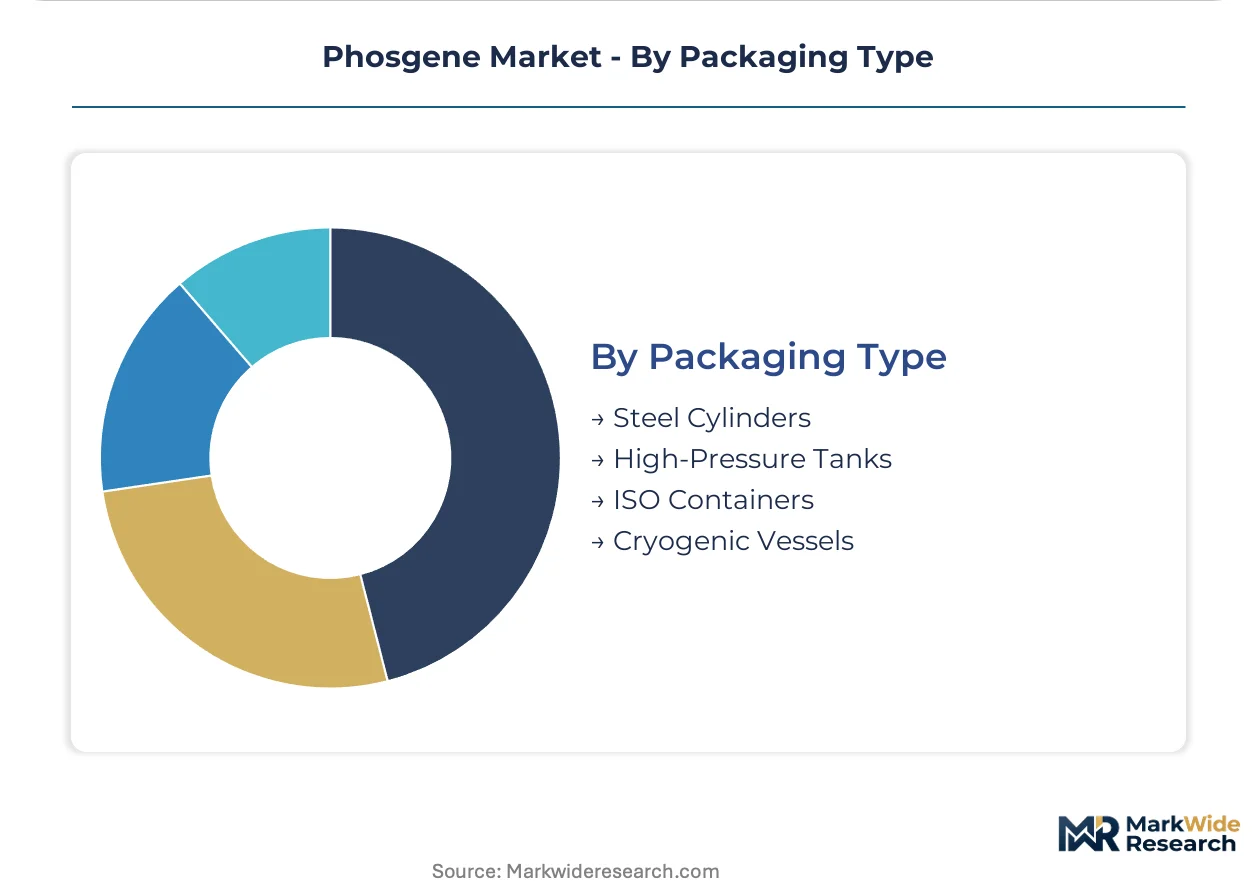
Packaging Type:
The choice of phosgene packaging directly impacts transportation logistics, safety protocols, and the scale of delivery to end-users.
- ISO Containers:These multimodal tanks enable efficient international transport of phosgene, particularly for merchant supply between continents. Stringent international regulations under the CWC govern the movement and declaration of these containers.
- High-Pressure Tanks:Used for bulk storage and transport within a region, these tanks serve large industrial consumers of phosgene. Facilities on the US Gulf Coast employ these tanks for delivering phosgene to integrated chemical parks.
- Steel Cylinders:Smaller volumes of phosgene are transported in steel cylinders, catering to laboratory and niche specialty chemical requirements.
- Cryogenic Vessels:These specialized containers maintain phosgene at very low temperatures for specific applications requiring high purity or large-scale storage.
ISO containers offer critical efficiency for international trade, while high-pressure tanks optimize regional bulk distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Phosgene market leverages extensive chemical logistics networks, including specialized pipelines and port infrastructure, to facilitate the movement of critical intermediates. This infrastructure supports large-scale industrial complexes and integrated production hubs worldwide. These facilities ensure a steady supply for diverse downstream applications.
China
China's vast chemical manufacturing base drives significant demand for phosgene in isocyanates production for its polyurethane industry. The Ministry of Ecology and Environment (MEE) enforces stringent environmental protection standards for chemical plants. Integrated chemical parks in the Yangtze River Delta region enable efficient, captive phosgene supply for co-located facilities.
United States
The United States market sees robust demand for phosgene, particularly for MDI and TDI production supporting automotive and construction sectors. The US EPA rigorously enforces hazardous substance rules, dictating containment protocols for phosgene handling. Chemical manufacturing hubs along the US Gulf Coast benefit from integrated production and tolling agreements for phosgene supply.
Germany
Germany's advanced chemical industry utilizes phosgene for high-purity grades in specialty chemicals and pharmaceutical synthesis. The EU REACH framework imposes strict data generation and risk assessment requirements on phosgene producers and users. Industrial clusters in the Rhine-Ruhr region focus on process technology and high-value phosgene derivatives for niche applications.
India
India is developing its domestic chemical value chains, creating new demand for phosgene in the nascent polyurethane and agrochemical industries. The Bureau of Indian Standards (BIS) establishes safety norms for chemical production and handling. Chemical industrial zones in Gujarat are attracting investment for new production capacities and technology transfer.
Phosgene Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical chemical intermediates. The Phosgene market exhibits a tiered structure, with large multinational chemical manufacturers dominating bulk production. Strategic archetypes include integrated producers focused on captive supply and specialty chemical firms requiring high-purity grades. Capacity expansion in Asia and technology licensing for on-site generation are prominent competitive moves.
Within the integrated production archetype, Wanhua Chemical Group Co., Ltd., a China-based entity, leverages its scale for cost control in isocyanates. Covestro AG, a German multinational, occupies a position as a global leader through advanced process technology and high-purity grades. BASF SE, also a German chemical company, exemplifies a balanced geographic footprint, serving both bulk and niche segments across various regions.
| Leading Market Players |
|---|
| Huntsman Corporation |
| VanDeMark Chemical Inc. |
| BASF SE |
| Paushak Ltd. |
| Altivia |
| Covestro AG |
| Wanhua Chemical Group Co., Ltd. |
| Synthesia a.s. |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly those from the Chemical Weapons Convention, directly influence phosgene pricing tier spreads and global supply chain shape. These stringent controls dictate production costs and limit merchant supply flexibility.
Pricing Analysis
Volume-based discount tiering structures define phosgene pricing, with significant differentiation across bulk commodity grades and high-purity specialty variants. Geographic delivery costs and the scale of off-take agreements also influence final prices. Pricing pressure stems from escalating regulatory compliance and containment infrastructure investments. Specialty chemical manufacturers relying on merchant supply exhibit higher price sensitivity compared to integrated producers with captive phosgene.
Supply Chain Analysis
Dedicated phosgene specialists and integrated chemical giants like Wanhua Chemical Group Co., Ltd. and Covestro AG hold significant production capacity. Geographic supply concentrates in China, the US Gulf Coast, and the Rhine-Ruhr region of Germany. The supply chain draws from carbon monoxide, chlorine gas, and specialized activated carbon catalysts. Regulatory restrictions, particularly those under the Chemical Weapons Convention, pose a structural supply chain risk, impacting distribution via integrated pipelines, high-pressure tanks, and ISO containers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phosgene market currently presents a buyer-power-shift story, driven by the consolidation of large-scale integrated chemical manufacturers. These dominant buyers, particularly in Asia, leverage captive supply to control costs and reduce reliance on merchant suppliers.
For Market Incumbents: Harden existing positions by investing in advanced process technology for high-purity phosgene grades, particularly for pharmaceutical and agrochemical applications. Expand on-site generation capacity in strategic growth regions like India and Southeast Asia to counter emerging phosgene-free synthesis routes. Pursue certification investments to meet evolving ISO safety standards, mitigating regulatory shifts. Deepen captive supply chains to reduce exposure to external market volatility and maintain cost control.
For New Entrants and Emerging Players: Modular, small-scale phosgene generators for specialty chemical applications in Europe represent a penetrable entry point. Target nascent polyurethane industries in India and Southeast Asia by offering technology licensing for advanced on-site generation systems. Focus on high-purity solution forms for pharmaceutical synthesis, leveraging improved handling safety. A go-to-market angle involves providing integrated technology and operational support for point-of-use synthesis.
For Investors and Strategic Acquirers: The market sits at a mature yet evolving phase that favors integrated producers with advanced safety technologies. Long-term viability over the next 5-10 years remains strong due to polyurethane demand, but substitution risks persist. Acquisition targets should focus on niche technology providers specializing in microreactor systems or advanced containment solutions. A critical signal to watch as an inflection indicator is the widespread industrialization of non-phosgene isocyanate synthesis routes.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Build new integrated phosgene production facilities in China to support growing MDI and TDI demand. |
| Backward Integration | Secure captive supply of carbon monoxide and chlorine to control feedstock costs for phosgene manufacturing. |
| Green Manufacturing Transition | Invest in R&D for phosgene-free synthesis routes to align with EU REACH long-term substitution objectives. |
| Long-term Supply Agreement | Establish tolling agreements with isocyanate manufacturers on the US Gulf Coast to ensure stable demand. |
| Joint Venture | Partner with specialty chemical firms in Germany to develop high-purity phosgene derivatives for pharmaceutical applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Stakeholders included plant managers, procurement leads at downstream isocyanate OEMs, R&D directors, and EHS compliance officers. Secondary data sources comprised customs and trade statistics, ACC/Cefic industry reports, US EPA filings, and EU REACH dossiers. This approach facilitated robust bottom-up and top-down market triangulation.
Forecasts were calibrated against historical market performance and future growth drivers across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, packaging format, and regional production hub. Compound Annual Growth Rates were derived from multi-factor regression analysis. Key industry-specific forecast inputs included global polyurethane production forecasts and projected regulatory compliance costs.
Stress conditions across feedstock price volatility and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements in phosgene-free synthesis routes. Quarterly review of CWC declarations and capacity additions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Dimethyldichlorosilane Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Caustic Soda Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Global Lactate Salts Market
Chemicals
India Methanol Market
Chemicals
Global Amines Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Valeronitrile Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Fluorochemicals Market
Chemicals
Calcium Hydroxide Market
Chemicals
Sodium Methoxide Market