
 Sodium Hyaluronate Market | 2026-2036
Sodium Hyaluronate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Hyaluronate Market Analytics
Hospital procurement committees is unwinding legacy purchasing patterns toward single-source injectable contracts for ophthalmology suites. Lifecore Biomedical anchors its position through captive fermentation capacity in Minnesota, while Bloomage Bio-Technology Corporation dominates pharmaceutical-grade output from Shandong Province. Galderma competes across European aesthetic channels with differentiated cross-linked gel formulations.
Sodium hyaluronate is a non-sulfated glycosaminoglycan composed of repeating disaccharide units of D-glucuronic acid and N-acetyl-D-glucosamine, typically produced via microbial fermentation or avian extraction for medical and cosmetic applications. Injectable formulations command the deepest margin pools due to sterility validation burdens and clinical trial requirements, whereas topical products occupy broader volume channels through pharmacy and direct-to-consumer access. Dermal fillers within aesthetic medicine represent the fastest-expanding application segment as outpatient clinic chains standardize hyaluronic acid-based facial rejuvenation protocols.
FDA enforces injectable purity standards under biologics licensing pathways, while EMA's MDR framework reclassifies high-viscosity dermal fillers as Class III devices with strengthened post-market surveillance obligations. China's NMPA imposes dual carbon goals on fermentation facilities, constraining energy-intensive sodium hyaluronate production in Shandong and Jiangsu provinces. Stakeholders must monitor regulatory divergence between US biologics pathways and EU device reclassification to anticipate compliance cost allocation across their manufacturing footprints.
Market Dynamics
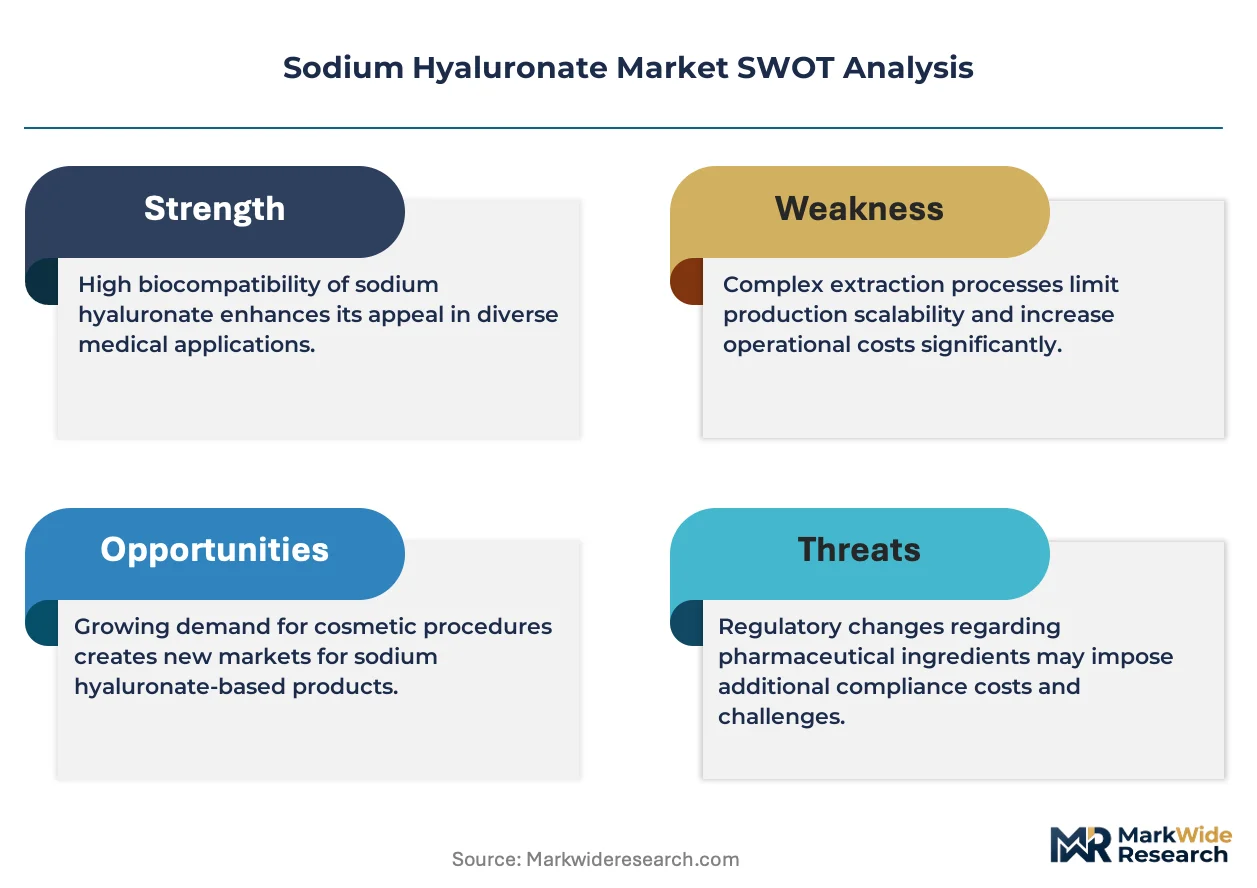
Fermentation-based manufacturing methods are redirecting capital flows as FDA and EMA tighten injectable purity standards, forcing legacy avian-extraction facilities into costly retrofit cycles or abandonment.
Growth Catalysts
- EMA MDR Reclassification:Class III device designation for high-viscosity dermal fillers mandates strengthened post-market surveillance, creating premium-tier demand for validated pharmaceutical-grade sodium hyaluronate.
- Aesthetic clinic chain expansion:Outpatient networks in South Korea and China standardize hyaluronic acid-based facial rejuvenation protocols, concentrating procurement volumes among fewer buyers.
- Single-source ophthalmology contracts:Hospital procurement committees unwind legacy multi-vendor purchasing patterns toward unified injectable supply agreements for surgical suites.
Market Restraints
- Energy-intensive fermentation:China's NMPA dual carbon goals constrain production facility expansion in Shandong and Jiangsu provinces, capping domestic supply growth.
- Avian-derived raw material dependency:Rooster comb extraction retains cost advantages in topical segments but faces sterility validation gaps for injectable pathways.
- Biologics licensing pathway friction:FDA's sterility documentation burdens extend clinical trial timelines for new injectable entrants, compressing margin pools for development-stage manufacturers.
Strategic Opportunities
- Ophthalmic viscosurgical device (OVD) penetration:Cataract surgery volume expansion in India creates unmet demand for cohesive-dispersive sodium hyaluronate formulations.
- Cross-linked gel innovation:Hybrid manufacturing techniques combining microbial fermentation with chemical modification open sustained-release therapeutic applications.
- Direct-to-consumer topical channels:Pharmacy and e-commerce access for cosmetic-grade serums bypasses clinical gatekeeper friction in European and North American markets.
Industry Challenges
- Fermentation process optimization talent:Microbial strain engineering and downstream purification expertise scarcity constrains capacity expansion at mid-scale biopolymer producers.
- Legacy equipment retrofit costs:Avian-extraction facilities face stranded asset risk as EMA MDR and FDA biologics pathways render existing cleanroom configurations non-compliant.
- Cross-regulatory compliance synchronization:Divergent US biologics and EU device frameworks force manufacturers to maintain parallel quality management systems, duplicating audit burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Hyaluronate Market |
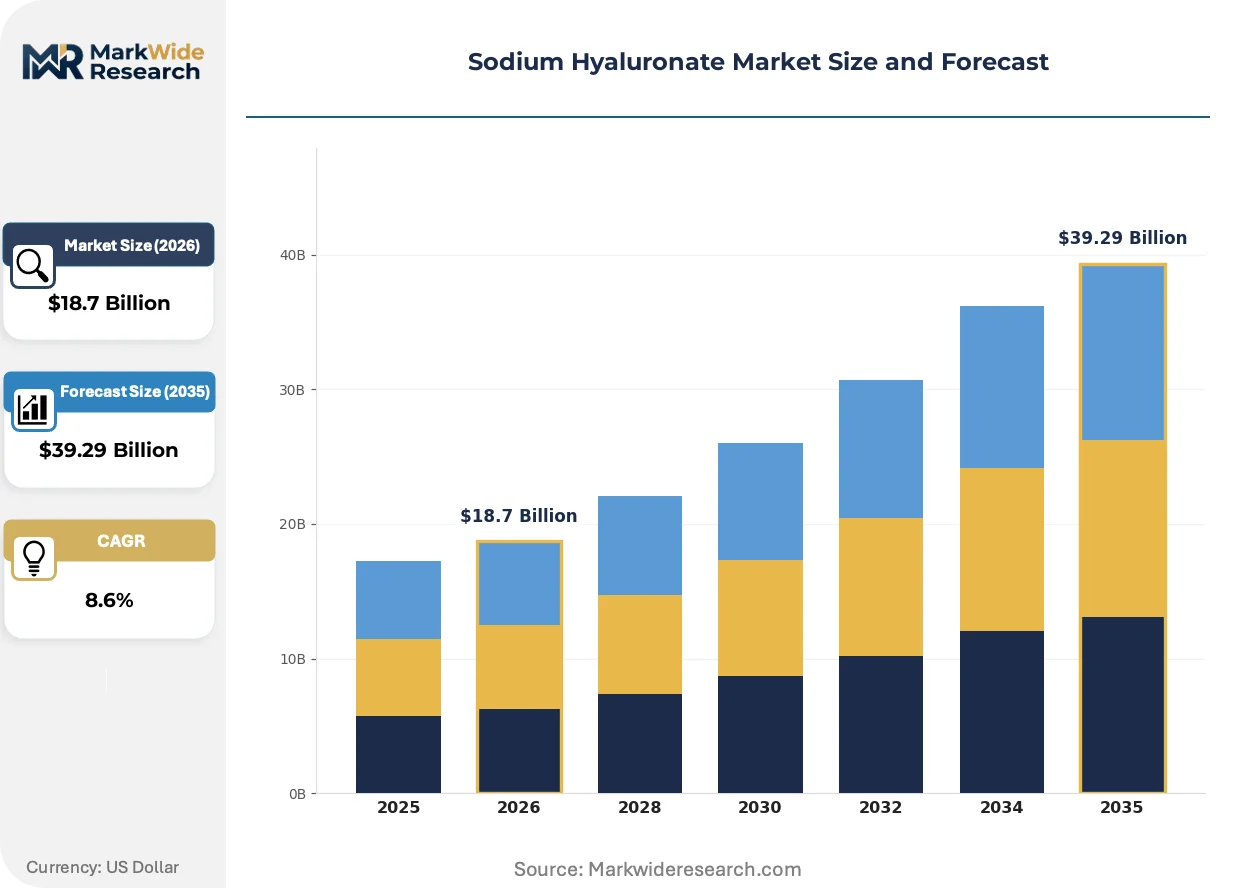
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Eye Drops, Topical, Capsules Application: Ophthalmology, Orthopedics, Aesthetic Medicine, Dermal Fillers End User: Hospitals, Clinics, Home Care, Research Laboratories Distribution Channel: Online, Offline, Pharmacies, Medical Supply Stores |
| Companies Covered | LG Chem, Allergan, Bloomage Bio-Technology Corporation, Bohus BioTech, Lifecore Biomedical, Anika Therapeutics, Fidia Farmaceutici, Zydus Cadila, Galderma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Hyaluronate Market Evolving Landscape
Recombinant microbial production platforms are displacing traditional extraction methods, while regulatory frameworks on both sides of the Atlantic harden certification requirements. These forces are compressing the supplier base toward fermentation-capable manufacturers with validated pharmaceutical-grade output.
Continuous fermentation technology is decomposing batch-based manufacturing economics in sodium hyaluronate production. Contract development and manufacturing organizations (CDMOs) in Germany and Switzerland adopt these systems to reduce per-unit costs and improve molecular weight consistency. The shift is decomposing price premiums previously commanded by established avian-extraction specialists.
EMA's Medical Device Regulation (MDR) framework reclassifies high-viscosity dermal fillers as Class III devices with strengthened post-market surveillance obligations. Manufacturers must now maintain clinical follow-up registries and periodic safety update reports, elevating compliance costs. European aesthetic channel distributors respond by consolidating supplier relationships toward vertically integrated producers with captive pharmacovigilance infrastructure.
Hospital procurement committees concentrate ophthalmology suite purchasing through single-source injectable contracts, displacing fragmented multi-vendor arrangements. This consolidation rewards manufacturers with dedicated sterile filling capacity and redundant supply chain documentation. The pattern is most visible in South Korea, where domestic clinic chains and hospital systems now demand unified supplier accountability across surgical and aesthetic product lines.
Sodium Hyaluronate Market Segmentation
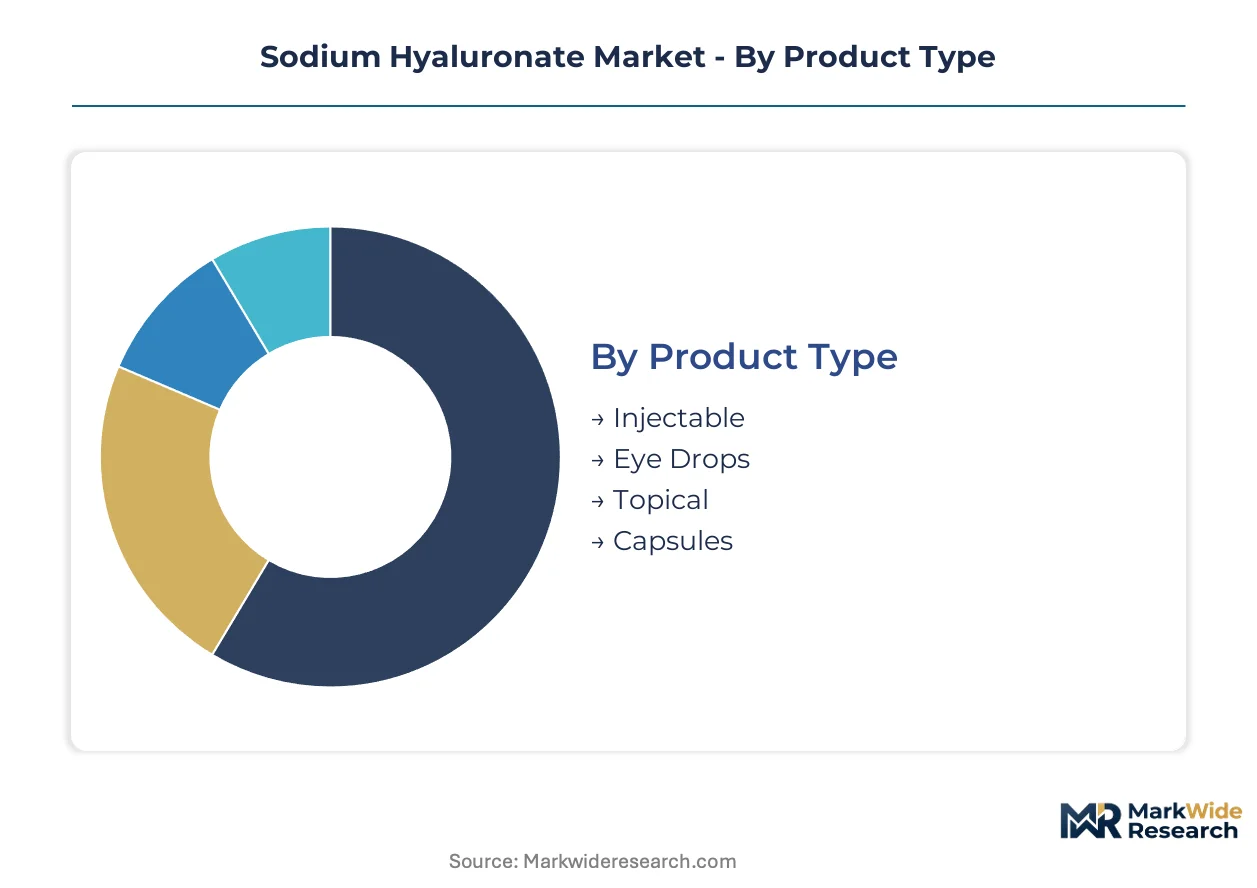
Sodium hyaluronate's molecular weight range and sterility requirements create sharp channel boundaries. Injectable grades demand closed-system hospital procurement, while cosmetic topicals flow through pharmacy and direct-to-consumer pathways with minimal clinical gatekeeping.
Product Type:
Channel-mix patterns diverge sharply: hospital procurement committees control injectable flows through single-source contracts, whereas eye drops and topicals fragment across pharmacy, e-commerce, and clinic retail channels.
- Injectable:High-viscosity formulations for intra-articular and dermal applications require fermentation-derived pharmaceutical-grade material with validated endotoxin levels below 0.5 EU/mL. Hospital procurement committees in South Korea and China are consolidating ophthalmology suite purchasing around unified injectable supply agreements that bundle surgical and aesthetic product lines.
- Eye Drops:Preservative-free ophthalmic solutions occupy pharmacy and hospital outpatient channels with lower sterility documentation burdens than injectable pathways. Demand concentrates in cataract surgery volume expansion across India, where cohesive-dispersive formulations address unmet viscosurgical device needs.
- Topical:Cosmetic-grade serums and moisturizers bypass clinical gatekeepers through e-commerce and pharmacy access in European and North American markets.
- Capsules:Oral dietary supplement formulations distribute through wellness retail and direct-to-consumer channels with minimal regulatory friction.
By volume, topical leads. By growth pace, injectable is ahead.
Application:
Cost tier differentiation separates premium-validated therapeutic uses from cosmetic-grade aesthetic applications, with regulatory compliance burdens determining margin architecture.
- Ophthalmology:Cataract surgery protocols standardize sodium hyaluronate as ophthalmic viscosurgical devices, with cohesive-dispersive formulations commanding premium positioning. India's expanding surgical volume creates demand for validated supply chains that can support high-volume hospital procurement.
- Dermal Fillers:Cross-linked gel formulations for facial rejuvenation represent the steepest expansion trajectory as outpatient clinic chains in South Korea and China standardize hyaluronic acid-based protocols. EMA's Class III device reclassification under MDR elevates compliance costs and consolidates supplier relationships toward vertically integrated producers.
- Orthopedics:Intra-articular injections for osteoarthritis management flow through hospital outpatient and specialized clinic channels with moderate sterility requirements.
- Aesthetic Medicine:Non-cross-linked applications in skinboosters and mesotherapy occupy mid-tier pricing between pharmaceutical and cosmetic grades.
Revenue concentrates in dermal fillers. Regulatory validation requirements favor ophthalmology.
End User:
Customer type determines purchasing protocol complexity, from centralized hospital procurement through fragmented home care self-selection.
- Hospitals:Centralized procurement committees unwind legacy multi-vendor patterns toward single-source injectable contracts that demand redundant supply chain documentation and captive sterile filling capacity.
- Clinics:Aesthetic clinic chains concentrate volumes among fewer buyers, standardizing hyaluronic acid-based facial rejuvenation protocols across South Korean and Chinese networks.
- Home Care:Self-administered topical and oral formulations distribute through pharmacy and e-commerce with minimal clinical oversight.
- Research Laboratories:Cell culture and tissue engineering applications require pharmaceutical-grade material with batch-specific certificates of analysis.
Procurement scale favors hospitals. Margin expansion concentrates in clinic chains.
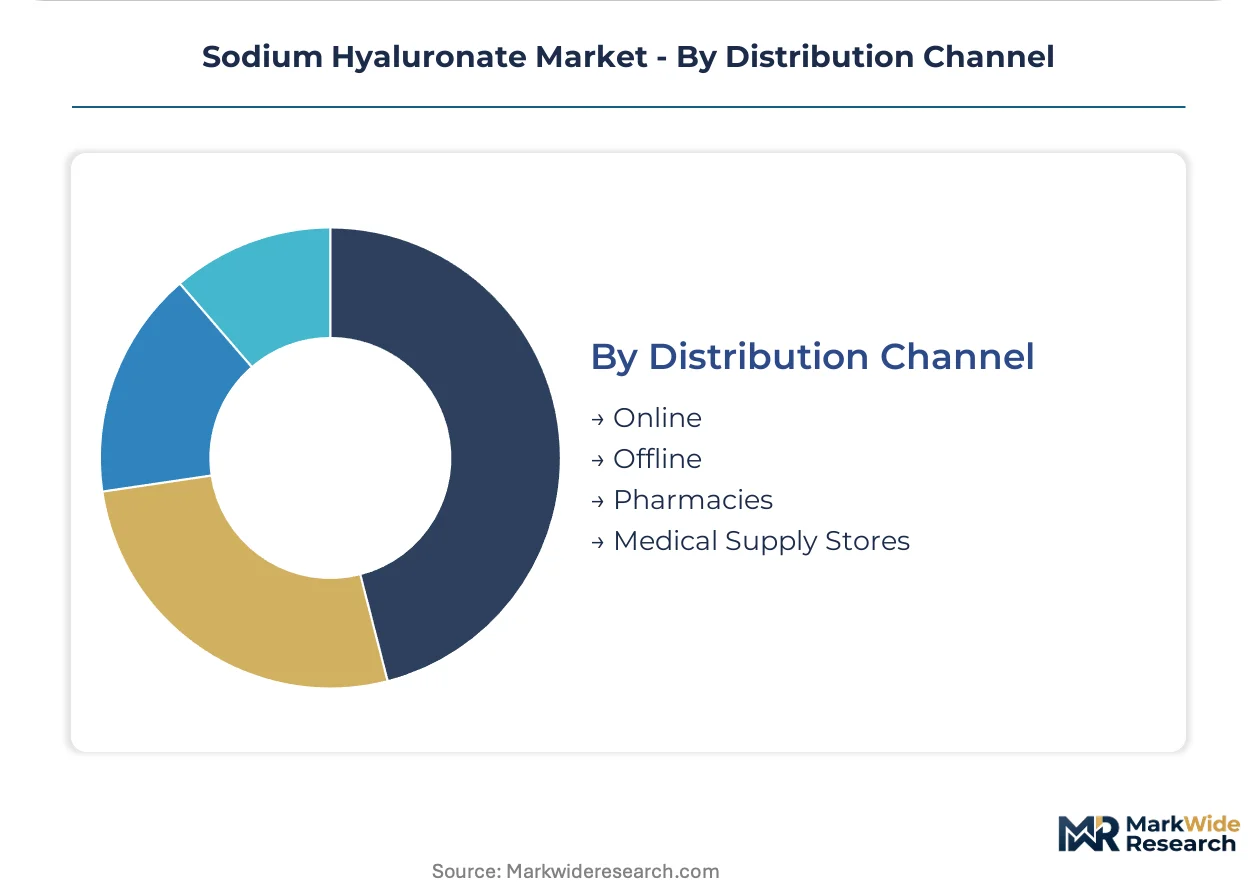
Distribution Channel:
Supply concentration in fermentation-capable manufacturers shapes channel access, with validated pharmaceutical-grade output restricting hospital and clinic flows to qualified distributors.
- Offline:Hospital procurement committees and clinic chains source directly from manufacturers with dedicated account management and pharmacovigilance infrastructure.
- Pharmacies:Community and hospital outpatient pharmacies handle eye drops and mid-tier topical formulations with prescription and over-the-counter stratification.
- Online:Direct-to-consumer e-commerce channels for cosmetic-grade serums bypass clinical gatekeeper friction in European and North American markets.
- Medical Supply Stores:Specialized distributors serve smaller clinics and outpatient surgical centers with fragmented purchasing patterns.
Offline captures hospital value. Online expands fastest in cosmetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation facilities export pharmaceutical-grade sodium hyaluronate to South Korean aesthetic clinic chains and Indian hospital procurement networks. Cross-border supply flows concentrate through Shandong Province manufacturing clusters serving ophthalmic viscosurgical device demand in cataract surgery expansion markets.
China
Domestic aesthetic clinic chains in Seoul and Busan source cross-linked gel formulations from Shandong-based fermentation specialists. NMPA dual carbon goals constrain energy-intensive production expansion in Jiangsu Province. Zibo and Weifang industrial corridors anchor captive pharmaceutical-grade output for intra-articular and dermal filler applications.
South Korea
Hospital procurement committees in Seoul Capital Area standardize single-source injectable contracts bundling surgical and aesthetic product lines. MFDS enforces strengthened post-market surveillance for high-viscosity dermal fillers under medical device reclassification. Busan-Ulsan manufacturing zones host downstream formulation facilities serving domestic clinic chain networks.
United States
Minnesota-based fermentation capacity supplies ophthalmology suites consolidating around unified injectable supply agreements. FDA biologics licensing pathways impose sterility documentation burdens extending clinical trial timelines for new entrants. Twin Cities medical device corridor anchors sterile filling infrastructure for validated endotoxin-compliant output.
India
Cataract surgery volume expansion in Maharashtra and Karnataka creates unmet demand for cohesive-dispersive ophthalmic viscosurgical devices. CDSCO regulates injectable purity standards under biologics frameworks parallel to FDA pathways. Hyderabad and Mumbai hospital procurement networks concentrate purchasing volumes among fewer validated suppliers.
Germany
Contract development and manufacturing organizations in Baden-Württemberg adopt continuous fermentation technology to reduce per-unit sodium hyaluronate costs. EMA MDR framework reclassifies high-viscosity dermal fillers as Class III devices with periodic safety update report obligations. Stuttgart industrial basin anchors downstream purification expertise for molecular weight consistency.
Sodium Hyaluronate Market Competitive Landscape
Listed leaders compete with private specialists across fermentation capacity and sterile filling infrastructure. The supplier base compresses toward vertically integrated manufacturers with captive pharmaceutical-grade output and redundant supply chain documentation. Three archetypes dominate: fermentation-capable biopolymer specialists, cross-linked gel formulators with device regulatory expertise, and avian-extraction legacy operators facing retrofit or abandonment. Consolidation accelerates through single-source hospital procurement mandates and EMA MDR compliance cost elevation.
Within the fermentation-specialist tier, Bloomage Bio-Technology Corporation and Lifecore Biomedical exemplify vertically integrated production architectures. Galderma occupies a position spanning European aesthetic channels with differentiated formulation capabilities. LG Chem anchors Korean-origin supply relationships with domestic clinic chain networks. These three represent the competitive spectrum from raw biopolymer production through branded therapeutic delivery.
| Leading Market Players |
|---|
| LG Chem |
| Allergan |
| Bloomage Bio-Technology Corporation |
| Bohus BioTech |
| Lifecore Biomedical |
| Anika Therapeutics |
| Fidia Farmaceutici |
| Zydus Cadila |
| Galderma |
| Others |
Value Network & Pricing Analysis
FDA biologics licensing pathways and EMA's MDR framework simultaneously gate supply qualification and stratify price tiers across injectable sodium hyaluronate markets. These dual regulatory regimes force manufacturers to absorb validation costs that translate directly into premium positioning for fermentation-derived pharmaceutical grades.
Pricing Analysis
Continuous fermentation technology is compressing the pricing gap between established microbial production platforms and legacy avian-extraction methods. Three-tier pricing structure across premium, standard, and economy levels separates validated endotoxin-compliant injectables from cosmetic-grade topicals and oral supplement formulations. Cost compression in mid-tier eye drop segments is intensifying because Shandong-based manufacturers are expanding capacity faster than Indian hospital procurement networks can absorb volume. Clinic chains in South Korea exhibit the lowest price sensitivity due to bundled service pricing, while European pharmacy channels for cosmetic serums face the highest margin pressure from direct-to-consumer e-commerce entrants.
Supply Chain Analysis
Strategic stockpiling of rooster comb-derived raw materials persists among topical-focused manufacturers despite fermentation's sterility advantages for injectable pathways. Supply concentrates in China, South Korea, and Germany, with Shandong Province fermentation clusters feeding downstream formulation facilities in Busan-Ulsan and Stuttgart industrial basins. Production draws from microbial strain banks, glucose feedstock supply agreements, and specialized downstream purification resin inventories. Single-source vulnerability runs through sterile filling capacity constraints at Minnesota-based captive facilities. Distribution runs through direct manufacturer relationships with hospital procurement committees, supplemented by specialized medical supply distributors serving fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sodium hyaluronate market is approaching a platform-economics inflection as EMA's MDR reclassification forces aesthetic clinic chains to consolidate supplier relationships around vertically integrated producers with captive pharmacovigilance infrastructure.
For Market Incumbents: Fortify sterile filling capacity and redundant supply chain documentation to defend single-source hospital procurement contracts against emerging CDMO competitors with continuous fermentation platforms. Bloomage Bio-Technology Corporation's backward integration into Shandong-based glucose feedstock supply demonstrates how upstream control over fermentation inputs insulates margin pools from NMPA dual carbon compliance costs. Prioritize ophthalmic viscosurgical device registrations in Maharashtra and Karnataka cataract surgery expansion markets before mid-scale biopolymer producers resolve their strain engineering talent scarcity. For New Entrants and Emerging Players: CDSCO's parallel biologics pathway to FDA standards offers a certification fast-track for injectable entrants targeting India's cohesive-dispersive ophthalmic viscosurgical device demand. White-space concentration exists in direct-to-consumer topical channels for European and North American pharmacy and e-commerce access, where clinical gatekeeper friction is minimal. Target research laboratory cell culture applications requiring pharmaceutical-grade material with batch-specific certificates of analysis. Go-to-market leverage rests on hybrid manufacturing techniques combining microbial fermentation with chemical modification for sustained-release therapeutic positioning. For Investors and Strategic Acquirers: EMA's MDR Class III device reclassification reshapes the acquisition landscape toward vertically integrated producers with validated pharmacovigilance infrastructure and captive sterile filling capacity. Long-term viability over the projection horizon favors fermentation-capable specialists with downstream cross-linked gel formulation expertise over avian-extraction legacy operators facing stranded asset risk. Target acquisition archetypes include mid-scale biopolymer producers with unresolved strain engineering talent gaps but established downstream distributor relationships. Monitor MFDS post-market surveillance enforcement intensity as the signal indicating Korean clinic chain procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive microbial production in Shandong Province reduces dependency on avian-derived raw material volatility. |
| Cross-Linked Gel Innovation | Hybrid manufacturing techniques open sustained-release therapeutic applications beyond aesthetic medicine. |
| Single-Source Contract Consolidation | Hospital procurement committees in Seoul Capital Area reward unified supplier accountability across surgical and aesthetic lines. |
| Continuous Fermentation Adoption | Baden-Württemberg CDMOs decompose batch-based economics to improve molecular weight consistency. |
| Direct-to-Consumer Channel Development | Pharmacy and e-commerce access for cosmetic-grade serums bypasses clinical gatekeeper friction in European markets. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, regulatory affairs leads at fermentation specialists, ophthalmic surgeons, aesthetic clinic chain purchasing directors, and CDMO technical directors and refined through secondary validation against FDA biologics licensing submissions, EMA MDR technical documentation, NMPA dual carbon policy filings, CDSCO injectable purity standards, and customs trade data for sodium hyaluronate raw material flows. Bottom-up demand modeling across molecular weight grades and sterility tiers was triangulated against top-down market sizing from production capacity disclosures.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each molecular weight segment and application pathway. Segmentation dimensions modeled include product type hierarchy, ophthalmology versus dermal filler versus orthopedic application channels, hospital versus clinic versus home care end-user archetypes, and offline versus online distribution channel splits. CAGRs were derived from installed fermentation capacity expansion schedules correlated with cataract surgery volume trajectories in India and aesthetic clinic chain penetration rates in South Korea.
Underlying assumptions cover regulatory enforcement continuity at FDA and EMA, NMPA dual carbon goal implementation pace, and MFDS post-market surveillance intensity, with deviation risk concentrated in China's energy policy enforcement variability and India's hospital procurement centralization velocity. Practitioners should keep alternative scenarios live as fermentation process optimization talent scarcity and avian-extraction facility retrofit economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Synthetic and Bio-Based Adipic Acid Market
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Middle East and Africa Polyvinylpyrrolidone (PVP) Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
5-Hydroxymethylfurfural Market