
 Warm Edge Spacer Market | 2026-2036
Warm Edge Spacer Market Size, Share, and Industry Trends Forecast 2026-2036
Warm Edge Spacer Market Analysis
Modular spacer-bar systems bundled with gas-fill and desiccant integration is realigning procurement patterns across insulated glass manufacturers. Swisspacer leverages its polymer extrusion expertise to dominate premium facade specifications in Central Europe. Edgetech sustains North American market presence through captive supply of dual-seal technology to Cardinal Glass. Ensinger competes with specialized high-performance thermoplastic formulations that reduce linear thermal transmittance below conventional aluminum alternatives.
A warm edge spacer is a thermally optimized perimeter component for insulated glass units, typically fabricated from stainless steel or engineered polymer composites with a thermal conductivity below 0.2 W/mK, designed to minimize heat loss at the glass edge and prevent condensation formation. Polymer-based configurations lead volume share due to cost-efficient extrusion and superior psi-values, while hybrid stainless steel-polymer laminates capture margin pools in structural glazing applications where load-bearing capacity meets thermal performance. Triple glazing demand accelerates fastest in Northern European climates where regulatory psi-value thresholds tighten, though double glazing retains scale dominance in renovation markets constrained by sash depth limitations.
REACH compliance governs material composition across European supply chains, while CE marking under the Construction Products Regulation mandates declared thermal performance for market access. The EPA Energy Star program in the United States shapes product positioning through whole-window U-factor certification requirements. Stakeholders must monitor evolving national building codes that progressively lower allowable window U-values and determine whether polymer or hybrid spacer architectures align with emerging structural glazing load standards.
Market Dynamics
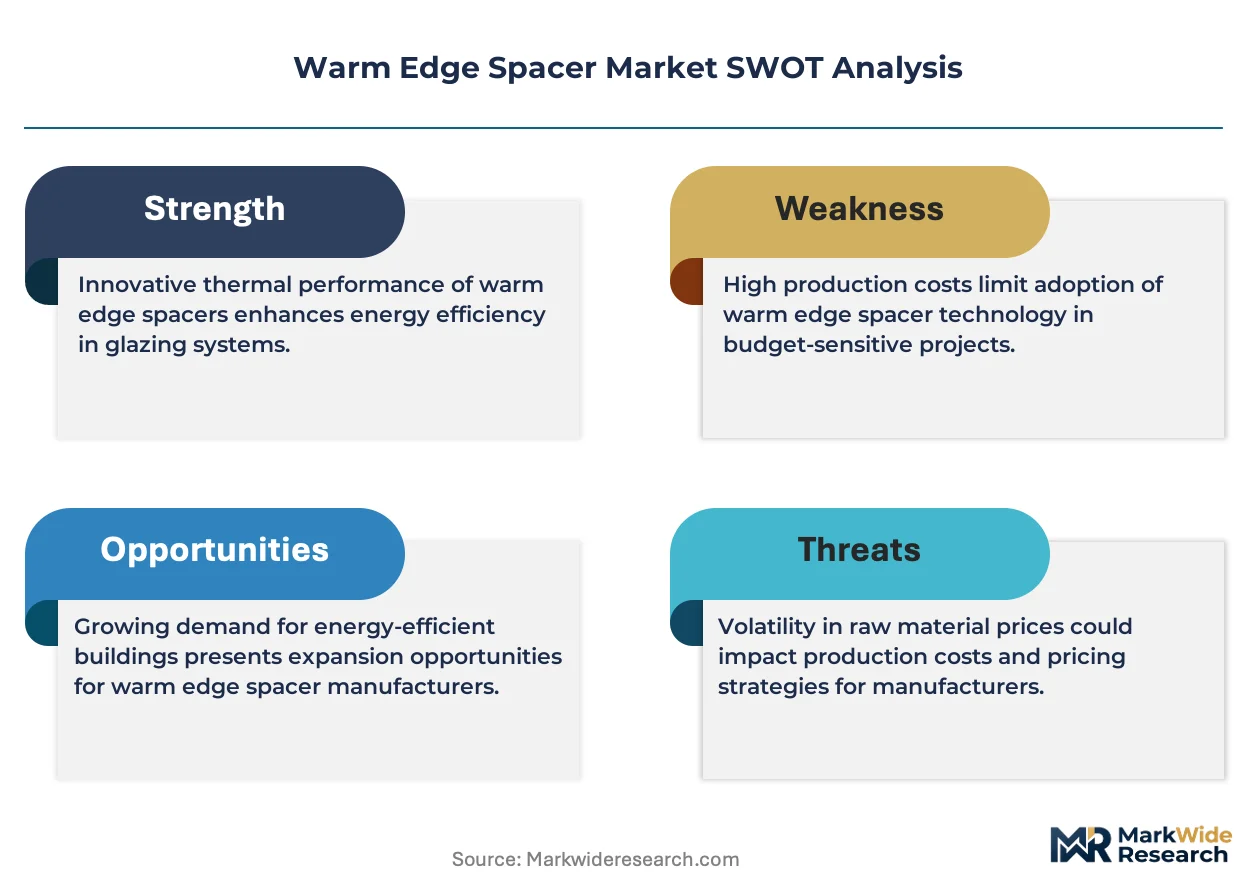
The EU Green Deal is compressing window U-value thresholds across member states, forcing insulated glass manufacturers to abandon conventional aluminum spacers for thermally optimized perimeter solutions that satisfy Passive House certification requirements.
Growth Catalysts
- Passive House Certification Mandates:German residential builders now specify warm edge spacers as standard to meet rigorous thermal bridge-free envelope requirements, accelerating specification velocity across Central European construction markets.
- Renovation Subsidy Frameworks:France's MaPrimeRénov program covers up to 90% of window replacement costs for low-income households, compressing payback periods and shortening replacement cycles for outdated fenestration.
- Triple Glazing Penetration:Northern European climates are mandating psi-values below 0.04 W/mK for new construction, eliminating conventional spacer options and expanding addressable market for polymer composite and hybrid stainless steel-polymer configurations.
Market Restraints
- Raw Material Volatility:Engineered thermoplastic resins and specialized desiccant formulations face price pressure from petrochemical feedstock fluctuations, squeezing margin pools for extrusion-based spacer manufacturers.
- Supply Concentration Risk:Polymer extrusion expertise concentrates among Swiss and German specialty chemical processors, creating bottleneck vulnerability for insulated glass units requiring CE-marked thermal performance declarations.
- Substitution Threat from Vacuum Glazing:Emerging vacuum-insulated glass technologies with edge-sealed designs eliminate perimeter spacer requirements entirely, threatening long-term demand in premium facade segments.
Strategic Opportunities
- Underpenetrated Southern European Markets:Spain and Italy exhibit lagging window replacement rates versus Northern Europe, presenting expansion opportunity as EU Green Deal funding reaches Mediterranean member states.
- Modular System Bundling:Integrated spacer-bar platforms combining gas-fill, desiccant, and primary seal functions enable specification lock-in with insulated glass manufacturers seeking procurement simplification.
- Structural Glazing Load Standards Evolution:Emerging European technical approvals for hybrid stainless steel-polymer laminates in point-fixed facade applications open margin-rich segments beyond conventional curtain walling.
Industry Challenges
- Thermal Modeling Expertise Scarcity:Accurate psi-value calculation and finite element analysis for complex glazing geometries require specialized engineering talent that insulated glass manufacturers struggle to recruit and retain.
- CE Marking Timeline Compression:Construction Products Regulation conformity assessment for novel polymer formulations demands 12-18 month testing cycles, delaying market entry for innovative material platforms.
- Dual-Seal Integration Complexity:Warm edge spacers must interface precisely with primary polyisobutylene and secondary silicone or polysulfide seals, requiring tight manufacturing tolerances that strain legacy production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warm Edge Spacer Market |
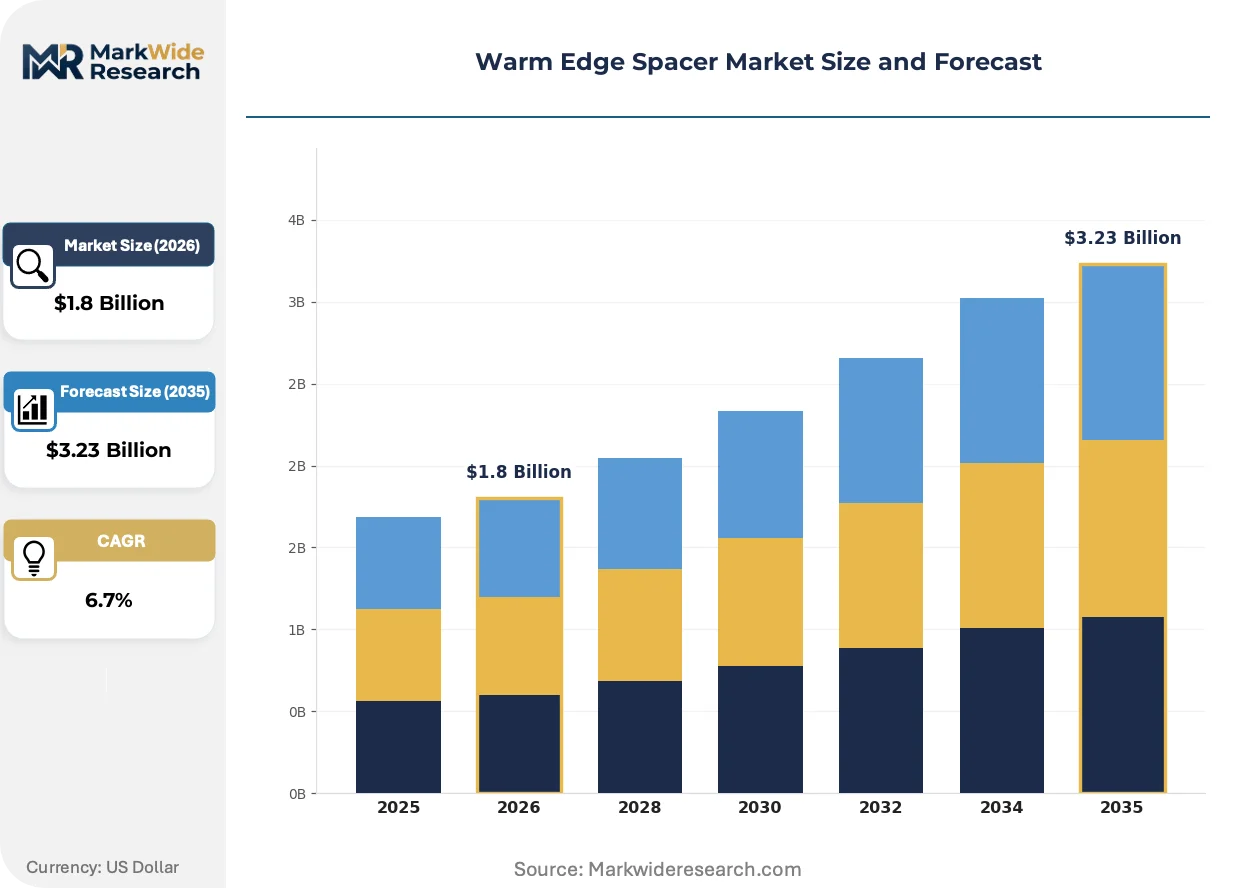
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Aluminum, Stainless Steel, Hybrid Application: Double Glazing, Triple Glazing, Passive House, Structural Glazing End User: Construction, Renovation, Automotive, Aerospace Installation Method: Manual, Automated, Semi-Automated, In-Line |
| Companies Covered | Swisspacer, Edgetech, Ensinger, Technoform, Thermiseal Group, Quanex Building Products, Cardinal Glass, AGC Glass, Alu Pro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warm Edge Spacer Market Emerging Trajectories
Material science advances and regulatory tightening are converging to transform how perimeter thermal performance is engineered, tested, and procured across the fenestration value chain.
Polymer composite spacer systems incorporating glass fiber reinforcement and low-conductivity desiccant matrices are decentralizing specification authority from facade consultants toward insulated glass manufacturers seeking in-house thermal optimization. Mid-size glazing fabricators in the Netherlands and Denmark are adopting these extrudable platforms to bypass premium-brand dependency and capture margin previously allocated to imported hybrid systems. The shift is compressing brand premium structures and accelerating commoditization of baseline thermal performance tiers.
REACH compliance enforcement through ECHA is tightening restrictions on phthalate plasticizers and heavy metal stabilizers historically used in PVC-based spacer formulations, forcing reformulation investments across European supply chains. The regulatory pressure is elevating thermoplastic elastomer and polypropylene block copolymer alternatives that satisfy both thermal conductivity and material safety requirements. German and Austrian insulated glass manufacturers are responding fastest, leveraging proximity to polymer compounders for rapid certification turnaround.
Building envelope procurement is fragmenting as large residential developers establish direct supplier relationships with spacer manufacturers, bypassing traditional window fabricator intermediaries. Volume buyers in Sweden and Finland are negotiating frame-account pricing for multi-year new construction pipelines, extracting transparency on raw material indices and extrusion capacity allocation. The disintermediation is most visible in serial passive house developments where thermal performance guarantees must trace to component-level documentation rather than assembled unit testing.
Warm Edge Spacer Market Segmentation
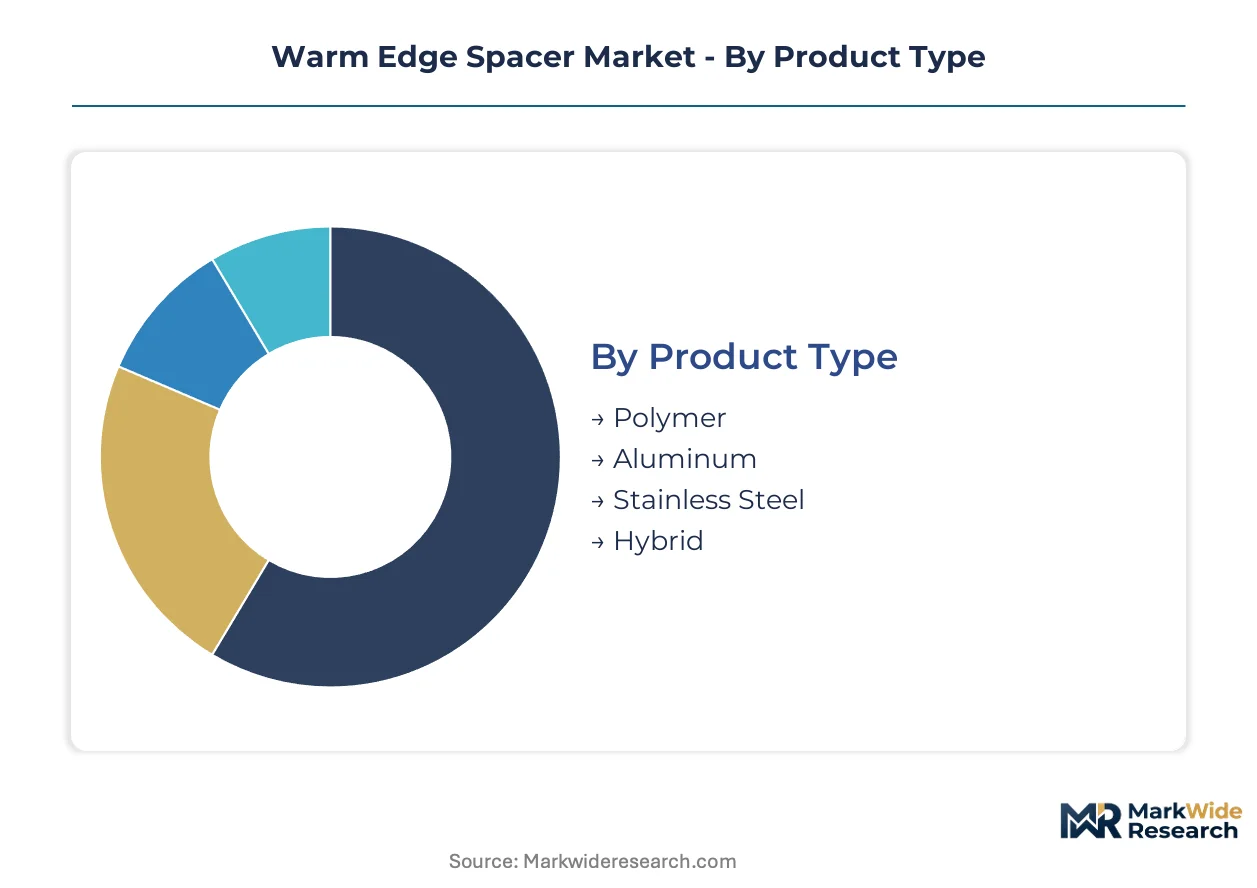
Warm edge spacer procurement patterns diverge sharply across material platforms and glazing architectures. Capital allocation decisions by insulated glass manufacturers hinge on thermal performance thresholds, automation compatibility, and regulatory compliance pathways that vary by segment.
Product Type:
Capital intensity peaks with hybrid stainless steel-polymer laminates requiring dual-material extrusion lines and precision bonding equipment. Polymer extrusion demands moderate tooling investment but scales efficiently. Aluminum spacers leverage legacy rolling stock with minimal retooling. Stainless steel configurations need specialized slitting and forming machinery.
- Polymer:Engineered thermoplastic formulations, typically polypropylene block copolymers or thermoplastic elastomers, achieve psi-values below 0.04 W/mK through glass fiber reinforcement. Demand concentrates in German and Austrian residential construction where REACH compliance and CE marking under the Construction Products Regulation accelerate specification. Cost-efficient extrusion and superior thermal performance drive procurement from mid-size glazing fabricators seeking in-house optimization.
- Hybrid:Stainless steel-polymer laminates combine structural load-bearing capacity with reduced linear thermal transmittance. Northern European triple glazing mandates in Sweden and Finland absorb volume, as regulatory psi-value thresholds below 0.04 W/mK eliminate conventional alternatives. Premium facade specifications in point-fixed structural glazing applications command margin pools inaccessible to pure polymer systems.
- Aluminum:Conventional rolled aluminum profiles with thermal breaks retain residual share in renovation markets constrained by sash depth limitations and cost sensitivity.
- Stainless Steel:Solid stainless steel configurations persist in structural glazing where point-fixed facade loads exceed polymer mechanical limits, though thermal bridging limits new specification.
Most installed capacity flows through Polymer. Expansion is steepest in Hybrid.
Application:
Volume distribution tracks regulatory stringency gradients across European climate zones. Double glazing retains scale dominance where renovation economics dominate, while Passive House and triple glazing segments concentrate new construction premium.
- Double Glazing:Two-pane insulated glass units with perimeter warm edge spacers remain the default specification for residential renovation across France, where MaPrimeRénov subsidies compress payback periods. Sash depth constraints in existing window frames prevent triple glazing retrofits, preserving addressable market for slimmer spacer profiles.
- Passive House:Certification mandates in Germany require thermal bridge-free envelope assemblies with psi-values demonstrably below conventional construction. Edgetech and Swisspacer specifications dominate German residential developments, with whole-window U-factor documentation tracing to component-level thermal modeling.
- Triple Glazing:Three-pane configurations with dual warm edge spacer sets achieve center-of-glass U-values approaching 0.5 W/m²K. Northern European new construction in Denmark and the Netherlands absorbs volume as national building codes tighten.
- Structural Glazing:Point-fixed and stick-system curtain walls demand hybrid spacer architectures satisfying both thermal performance and structural load requirements. European technical approval evolution is expanding addressable segments.
Double Glazing retains the largest installed base. Passive House specifications are climbing the fastest.
End User:
Customer concentration patterns reflect construction cycle timing and subsidy program design. Direct procurement by large residential developers is fragmenting traditional window fabricator intermediation.
- Construction:New residential and commercial building drives specification of high-performance warm edge spacers in serial Passive House developments. Swedish and Finnish volume buyers negotiate frame-account pricing for multi-year pipelines.
- Renovation:Window replacement cycles accelerate where subsidy frameworks cover installation costs. French low-income household programs and German KfW efficiency loans shape demand timing.
- Automotive:Heated windscreen and panoramic roof applications require specialized spacer formulations managing thermal stress and optical clarity.
- Aerospace:Cabin window systems for commercial aircraft demand extreme lightweighting and pressure cycling durability, representing a niche specification tier.
Construction channels the majority of volume. Renovation is gaining share fastest as subsidy programs mature.
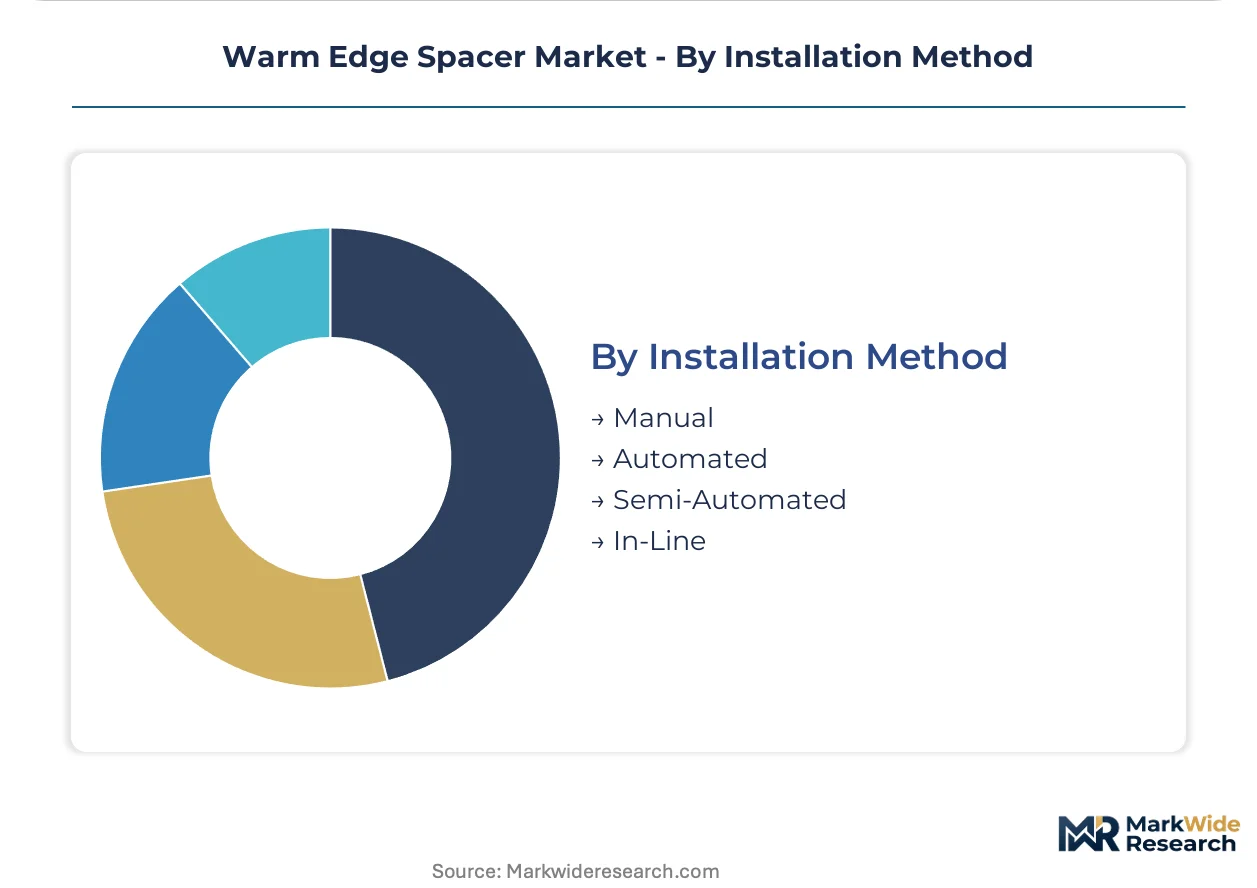
Installation Method:
Automation penetration correlates with production scale and labor cost structures. In-line integration with glass washing, gas-filling, and sealing equipment defines competitive manufacturing economics.
- Automated:Robotic spacer bar bending, desiccant filling, and primary seal application integrate with continuous glass processing lines. Large insulated glass manufacturers in Germany and the Netherlands achieve throughput rates incompatible with manual methods.
- In-Line:Fully continuous production systems synchronize spacer placement with gas filling and unit assembly, minimizing handling damage and dimensional tolerance drift.
- Semi-Automated:Partial mechanization of bending and desiccant loading suits mid-size fabricators with mixed product portfolios and batch changeover requirements.
- Manual:Hand assembly persists in custom architectural glazing and small-batch renovation orders where setup automation is uneconomical.
Automated systems process the most volume. In-Line configurations show the steepest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warm edge spacer manufacturing originated in German and Swiss engineering clusters during the 1990s, where polymer extrusion expertise met stringent building envelope thermal requirements. The industry subsequently diffused across Northern Europe before establishing production footholds in North America and Asia-Pacific.
Germany
Passive House certification mandates drive specification velocity across residential construction, with builders requiring thermal bridge-free envelope assemblies. The KfW efficiency loan program accelerates window replacement cycles by compressing payback periods for low-income households. Stuttgart and Munich industrial corridors host polymer compounders supplying REACH-compliant formulations to insulated glass manufacturers.
France
MaPrimeRénov subsidies cover up to 90 percent of window replacement costs, shortening renovation cycles for outdated fenestration. The country's national building code progressively tightens allowable window U-values under EU Green Deal implementation. Lyon and Paris basin fabrication clusters absorb volume from both new construction and retrofit segments.
Sweden
Triple glazing penetration reaches highest regional levels as national codes mandate psi-values below 0.04 W/mK. Volume buyers negotiate frame-account pricing for multi-year new construction pipelines, extracting transparency on raw material indices. Stockholm and Gothenburg residential developers establish direct supplier relationships, bypassing traditional window fabricator intermediaries.
United States
EPA Energy Star program shapes product positioning through whole-window U-factor certification requirements. Cardinal Glass captive supply relationships dominate large-scale insulated glass manufacturing. Midwest and Northeast industrial corridors concentrate extrusion capacity serving renovation markets constrained by existing sash depths.
Netherlands
Mid-size glazing fabricators adopt extrudable polymer platforms to bypass premium-brand dependency and capture margin previously allocated to imported hybrid systems. The country's national building code alignment with EU Green Deal timelines accelerates specification shifts. Eindhoven and Rotterdam manufacturing clusters integrate automated spacer bending with continuous glass processing lines.
Warm Edge Spacer Market Vendor Landscape
The competitive structure tilts toward specialty chemical processors with polymer extrusion expertise rather than diversified building materials conglomerates. Swiss and German engineering heritage concentrates technical capability among a tight vendor set serving premium facade specifications. Two strategic archetypes dominate: polymer compounders leveraging REACH-compliant formulation advantages, and hybrid system specialists capturing structural glazing margin pools. Capacity expansion and backward integration into desiccant and primary seal materials represent the dominant competitive vectors as manufacturers seek procurement simplification lock-in.
Among Central European compounders, Swisspacer and Ensinger exemplify the polymer extrusion archetype, occupying positions where thermal conductivity optimization meets regulatory compliance velocity. Edgetech anchors the hybrid system tier, representing North American manufacturing scale and dual-seal technology integration. These three entities collectively illustrate how geographic proximity to ECHA regulatory processes and CE marking infrastructure shapes competitive positioning across the fenestration value chain.
| Leading Market Players |
|---|
| Swisspacer |
| Edgetech |
| Ensinger |
| Technoform |
| Thermiseal Group |
| Quanex Building Products |
| Cardinal Glass |
| AGC Glass |
| Alu Pro |
| Others |
Supply Flow & Price Mechanics
German and Swedish volume buyers negotiating frame-account pricing for multi-year Passive House pipelines are extracting transparency on raw material indices and extrusion capacity allocation, forcing supply chains to consolidate polymer compounding expertise near ECHA regulatory infrastructure and compressing margin structures for non-integrated manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by CE marking tier and psi-value certification grade. Premium hybrid stainless steel-polymer laminates command structural glazing premiums, while polymer extrusion tiers compete on REACH compliance velocity and automation compatibility. Cost compression in standard polymer tiers is intensifying as mid-size Dutch and Danish fabricators bypass brand premiums through direct compounding relationships. Renovation contractors in France exhibit highest price sensitivity due to MaPrimeRénov subsidy caps, whereas Swedish residential developers prioritize thermal performance guarantees over unit cost.
Supply Chain Analysis
CE marking under the Construction Products Regulation and REACH compliance through ECHA create qualification bottlenecks that concentrate polymer extrusion expertise in Germany, Switzerland, and Austria. Engineered thermoplastic resins and specialized desiccant formulations draw from petrochemical feedstocks concentrated in Rhine-Ruhr and Basel industrial corridors. Single-source vulnerability persists for glass fiber reinforcement supply from German specialty chemical processors. Distribution runs through insulated glass manufacturers with in-line automation, though direct procurement by Swedish and Finnish residential developers is fragmenting traditional window fabricator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Warm Edge Spacer Market functions as a stable compounder, with EU Green Deal thermal performance mandates generating predictable specification upgrades across European fenestration replacement cycles.
For Market Incumbents: Cement specification lock-in through backward integration into desiccant and primary seal materials, creating procurement simplification bundles that raise switching costs for insulated glass manufacturers. Expand extrusion capacity in Stuttgart and Munich industrial corridors to capture KfW efficiency loan-driven replacement demand. Vacuum glazing substitution threats in premium facade segments require accelerated hybrid laminate certification for point-fixed structural applications. For New Entrants and Emerging Players: Launch via direct supply relationships with Spanish and Italian residential developers as EU Green Deal funding reaches Mediterranean member states, bypassing established window fabricator intermediaries. Target mid-size glazing fabricators in the Netherlands seeking extrudable polymer platforms to bypass premium-brand dependency. White-space opportunity concentrates in Southern European renovation markets with lagging replacement rates versus Northern Europe. For Investors and Strategic Acquirers: Asymmetric upside sits with polymer compounders possessing REACH-compliant formulation libraries and rapid CE marking turnaround capabilities. Five-to-ten year viability hinges on regulatory tightening trajectory rather than cyclical construction exposure. Acquisition candidates should demonstrate ECHA regulatory proximity and automated extrusion scale. The signal to watch is national building code adoption of psi-value thresholds below 0.04 W/mK in new member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Desiccant Supply | Captures margin pools previously allocated to third-party desiccant suppliers while ensuring REACH formulation control. |
| CE Marking Acceleration Investment | Compresses 12-18 month Construction Products Regulation conformity timelines to outpace reformulating competitors. |
| Direct Developer Procurement Channel | Bypasses window fabricator intermediation in Swedish and Finnish serial Passive House developments. |
| Hybrid Laminate Technical Approval | Opens point-fixed structural glazing segments inaccessible to pure polymer thermal performance systems. |
| Southern European Market Entry | Positions for EU Green Deal subsidy maturation in Spain and Italy renovation markets. |
Methodological Framework
Bottom-up fenestration demand modeling reconciled against top-down polymer extrusion capacity tracking forms the analytical core. Primary interviews with insulated glass manufacturing plant managers, procurement leads at window fabricators, polymer compounding technical directors, and facade consultant thermal modelers combined with secondary validation from ECHA REACH registration databases, CE marking declarations under the Construction Products Regulation, KfW efficiency loan disbursement records, and national building code amendment tracking across EU member states.
Input-output matrices map polymer formulation costs and psi-value performance tiers against regulatory threshold adoption curves across the projection horizon. Segmentation dimensions include material platform, glazing architecture, end-user channel, and automation integration level. CAGRs derive from regression analysis of replacement cycle timing against subsidy program maturation and building code tightening schedules. Forecast inputs incorporate ECHA enforcement intensity for phthalate restrictions and vacuum glazing technology cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under vacuum glazing substitution acceleration or petrochemical feedstock volatility. Model assumptions reflect documented regulatory timelines and construction cycle patterns. A model refresh is warranted upon material change in EU Green Deal funding allocation or national building code U-value threshold announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Sorbitan Esters Market
Chemicals & Materials
Melting Point Apparatus Market
Chemicals & Materials
Epoxy Casting Potting Resin Market
Chemicals & Materials
Global Neopentyl Glycol Market
Chemicals & Materials
United States Aerosol Cans Market
Chemicals & Materials
Roll-To-Roll Type UV Imprinting Machines Market
Chemicals & Materials
Organic Pigment Dispersions Market
Chemicals & Materials
Anti-Microbial Filter Market
Chemicals & Materials
Octyl Octanoate Market
Chemicals & Materials
Rosin Market
Chemicals & Materials
Spiral Wound Membrane Market
Chemicals & Materials
Global Saponin Market
Chemicals & Materials
North America and Australia Silica Market
Chemicals & Materials
Sheet Molding and Bulk Molding Compounds Market
Chemicals & Materials
Non-Woven Abrasives Market
Chemicals & Materials
Global Packaging Additives Market