
 Automotive Engine Cylinder Block Market | 2026-2036
Automotive Engine Cylinder Block Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Cylinder Block Market Analysis
Aluminum is consolidating its position against cast iron in passenger-vehicle cylinder block production, driven by weight-reduction mandates and thermal-efficiency targets. Cummins leverages its vertically integrated foundry network to secure raw material access across heavy-duty engine programs. Yasunaga Corporation anchors its competitiveness through precision machining capabilities that serve Japanese and Southeast Asian OEM supply chains. Ahresty Corporation differentiates via high-pressure die-casting expertise for aluminum blocks destined for hybrid powertrains.
An automotive engine cylinder block serves as the structural foundation housing cylinders, coolant passages, and crankcase assemblies, typically cast from gray iron, aluminum-silicon alloys, or compacted graphite iron with bore tolerances measured in micrometers. Its primary purpose is to provide rigid dimensional stability for piston reciprocation while managing thermal loads and lubricant distribution across operating cycles. Aluminum product types command expanding share in passenger-car applications where thermal conductivity and mass reduction offset material cost premiums. OEM end users concentrate procurement among tier-1 suppliers with captive casting capacity, while aftermarket providers occupy fragmented demand for remanufactured and replacement blocks in aging vehicle parcs.
EPA Corporate Average Fuel Economy standards and Euro 7 emissions frameworks from the European Commission directly constrain block weight and thermal-management performance thresholds, compelling foundries to recertify alloy compositions and surface-finishing protocols. China's MIIT enforces domestic new-energy vehicle production quotas that indirectly reshape cylinder block demand toward range-extender and hybrid-engine architectures. Stakeholders must monitor how multi-material bonding technologies and additive manufacturing of core tooling alter traditional sand-casting economics for block production.
Market Dynamics
Lightweighting mandates from EPA and Euro 7 protocols are forcing foundries to abandon gray iron for aluminum-silicon alloys, compressing traditional sand-casting economics and redrawing supplier qualification requirements across passenger-vehicle programs.
Growth Catalysts
- EPA CAFE Standards:US fuel economy mandates penalize curb weight, accelerating OEM procurement of aluminum blocks with integrated thermal-management galleries.
- China's MIIT Localization:Domestic engine production quotas in Jiangsu and Zhejiang provinces absorb foundry capacity and incentivize hybrid-architecture block designs.
- Compacted Graphite Iron:Heavy-duty commercial vehicles adopt CGI for its stiffness-to-weight ratio, extending block life under high-boost diesel combustion cycles.
Market Restraints
- Aluminum Alloy Volatility:Primary aluminum ingot prices fluctuate with LME trading patterns, squeezing margin predictability for independent foundries without captive smelter access.
- Tooling Lead Times:High-pressure die-casting core boxes require 16-20 week fabrication cycles, constraining rapid program ramp-ups for hybrid powertrain launches.
- Battery Electric Substitution:Pure-electric platforms eliminate cylinder block demand entirely, threatening long-term capacity planning for single-product foundries.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced automotive components attract greenfield aluminum casting investments serving Maruti Suzuki and Hyundai Motor India supply chains.
- Range-Extender Architectures:Small-displacement gasoline engines for series-hybrid EVs demand compact, thermally efficient blocks with integrated exhaust manifolds.
- Additive Manufacturing Convergence:Binder-jet printed sand cores reduce tooling costs and enable topology-optimized coolant passages previously impossible with conventional pattern-making.
Industry Challenges
- Dimensional Metrology Gap:Bore roundness tolerances below 5 micrometers require coordinate measuring machines and skilled technicians scarce in emerging manufacturing clusters.
- Multi-Material Bonding Certification:Aluminum-steel hybrid blocks with friction-stir welded inserts face extended OEM validation timelines before production release.
- Legacy Cast Iron Capacity Stranded:Brownfield gray iron foundries face asset write-downs as passenger-car demand shifts irreversibly toward aluminum alloys.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Cylinder Block Market |
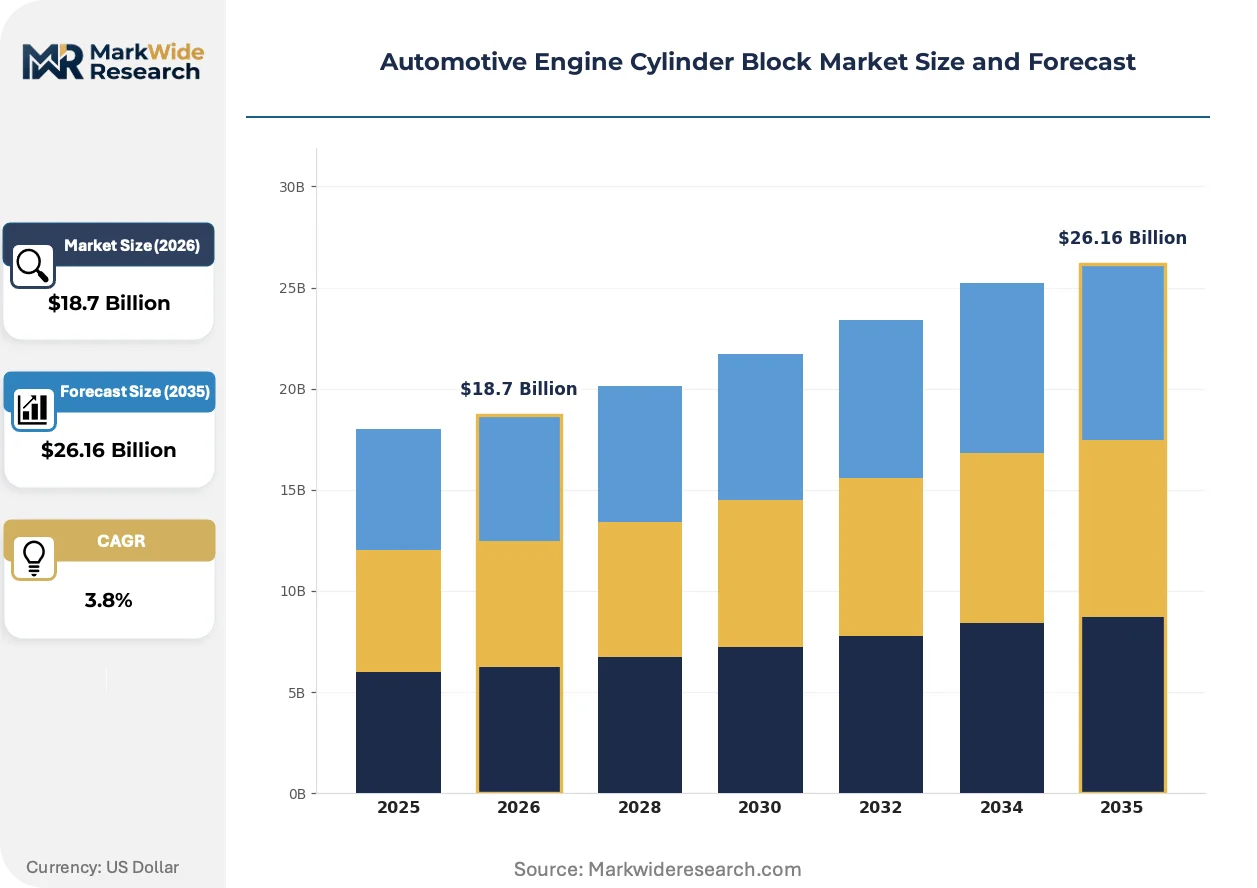
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron, Aluminum, Composite, Others End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Manufacturing Stage: Raw Material Processing, Machining, Finishing, Assembly Power Rating: Low Power, Medium Power, High Power, Heavy-Duty |
| Companies Covered | Cummins, Perkins Engines Company, Yasunaga Corporation, Fiat Chrysler Automobiles, Deutz, Cooper Corporation, Ahresty Corporation, Rico Auto Industries, Seaco Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Cylinder Block Market Emerging Trajectories
Digital foundry technologies and regulatory tightening are compressing development cycles while enabling geometric complexity previously excluded by cost constraints. Material science advances and procurement model evolution complete the transformation.
High-pressure die-casting with real-time shot monitoring is automating porosity detection and process adjustment during aluminum block production. Tier-1 suppliers deploy machine vision systems that reject defective castings before trimming operations. This capability is automating quality assurance labor and reducing downstream machining scrap rates.
Euro 7 emissions frameworks from the European Commission impose particulate number limits that constrain combustion chamber temperatures, compelling integrated exhaust manifold designs within the cylinder block. Foundries must recertify alloy thermal-fatigue resistance under combined mechanical and thermal loading. Passenger-car diesel applications face the steepest redesign requirements and supplier switching costs.
Long-term supply agreements with raw material pass-through clauses are displacing spot-market purchasing for aluminum ingot and magnesium additions. OEMs lock foundry capacity through take-or-pay structures covering hybrid program volumes. This pattern is most pronounced in Germany and Japan where just-in-sequence engine plant operations demand supply continuity guarantees.
Automotive Engine Cylinder Block Market Segmentation
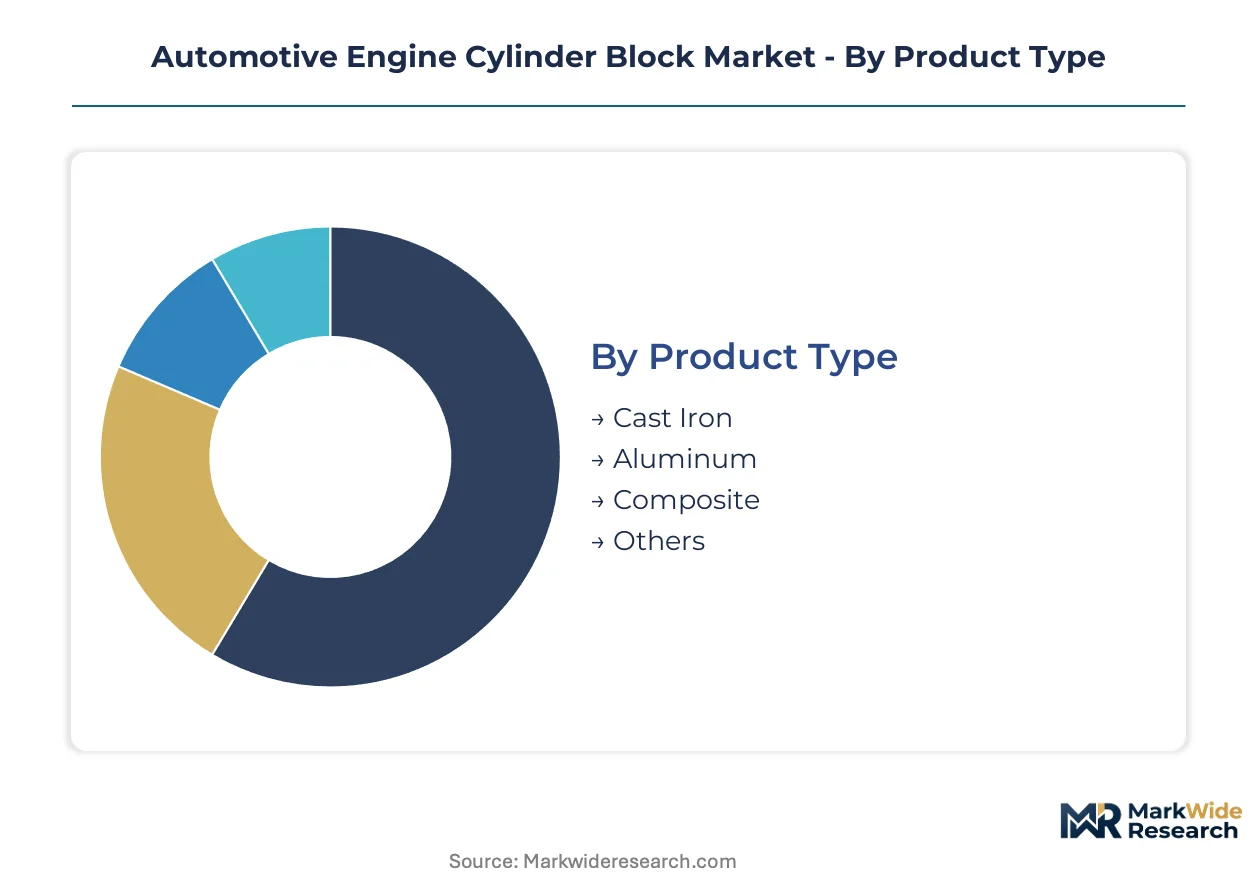
Cylinder block procurement patterns diverge sharply across material grades, end-user integration levels, and power-band requirements. Foundries must align casting capacity with distinct certification protocols and thermal-performance thresholds governing each segment.
Product Type:
Standardization dominates high-volume aluminum programs while cast iron retains customization for heavy-duty thermal cycles.
- Cast Iron:Gray iron and compacted graphite iron formulations deliver dimensional stability under extreme combustion pressures. Demand concentrates in commercial vehicle foundries across Michigan and Jiangsu provinces where EPA and MIIT emissions protocols sustain heavy-duty diesel production.
- Aluminum:Aluminum-silicon alloys with integrated cooling galleries reduce mass for passenger-car CAFE compliance. OEMs in Germany and Japan lock capacity through long-term offtake agreements as Euro 7 thermal-management requirements intensify.
- Composite:Hybrid aluminum-steel constructions with friction-stir welded reinforcements serve niche performance applications.
- Others:Magnesium-alloy prototypes and polymer-metal hybrids remain experimental for ultra-lightweight concepts.
Leading the category by volume: Aluminum. Growing fastest: Composite.
End User:
Margin concentration tracks backward from final assembly into captive foundry networks versus merchant supplier relationships.
- OEMs:Automakers with in-house casting divisions—Toyota, Volkswagen, General Motors—control alloy specification and thermal-fatigue testing protocols internally. Their engine plants in Kentucky, Lower Saxony, and Aichi prefecture demand just-in-sequence block delivery with zero ppm defect rates.
- Aftermarket Providers:Remanufacturers and replacement block suppliers serve aging vehicle parcs in Texas and São Paulo where extended vehicle lifecycles sustain demand for legacy cast iron architectures.
- Vehicle Assemblers:Contract manufacturers without captive engine production source blocks through tier-1 supply agreements.
- Tier-1 Suppliers:Independent foundries like Cummins and Ahresty compete on high-pressure die-casting precision for hybrid powertrain programs.
Highest margin capture: OEMs. Expanding most quickly: Tier-1 Suppliers.
Manufacturing Stage:
Process intensity escalates from commodity ingot conversion toward precision metrology and surface-finishing operations.
- Raw Material Processing:Primary aluminum smelting and scrap recycling operations in Quebec and Shandong province supply alloy specifications with tight silicon and copper tolerances. LME price volatility here compresses margin predictability for independent foundries lacking captive smelter access.
- Machining:CNC boring and honing operations achieve bore roundness below 5 micrometers using coordinate measuring machines scarce in emerging manufacturing clusters.
- Finishing:Thermal-spray cylinder liners and plateau honing extend surface durability for start-stop hybrid cycles.
- Assembly:Crankcase integration with bedplate joining and main bearing alignment represents final dimensional certification.
Capital intensity peaks: Machining. Technology disruption: Raw Material Processing.
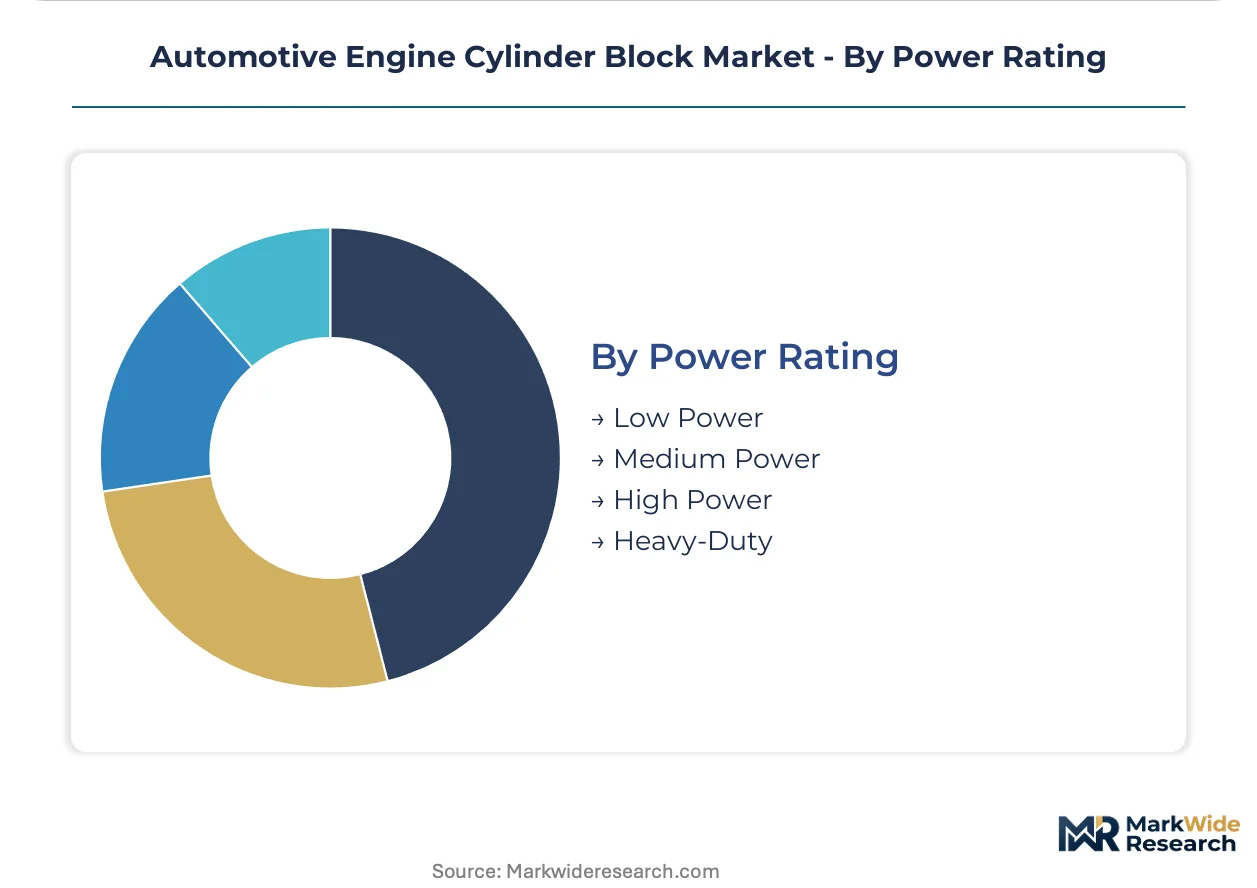
Power Rating:
Thermal loading and boost pressure separate architectural requirements across displacement categories.
- Low Power:Sub-1.5 liter three-cylinder blocks for range-extender hybrids prioritize compact packaging and rapid warm-up. Designs in Japan and South Korea integrate exhaust manifolds to meet Euro 7 cold-start emissions limits.
- Medium Power:1.5-2.5 liter four-cylinder architectures dominate C-segment vehicle production across China and Europe with aluminum-silicon alloys displacing gray iron.
- High Power:Performance-oriented six-cylinder blocks with deck-plate reinforcement serve premium SUV segments.
- Heavy-Duty:CGI and gray iron blocks withstand 250+ bar peak cylinder pressures in long-haul trucking applications across North American interstate corridors.
Volume concentration: Medium Power. Steepest expansion trajectory: Low Power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of foundry output for automotive engine cylinder blocks, with provincial localization programs and hybrid powertrain mandates concentrating demand across eastern manufacturing belts. Germany and the United States follow as regulatory pressure for lightweighting intensifies procurement of aluminum-silicon architectures. Japan and India round out the major demand centers, each shaped by distinct emissions frameworks and domestic production incentives.
China
MIIT production quotas for new-energy vehicles and engine localization programs in Jiangsu and Zhejiang provinces sustain foundry capacity absorption. The MIIT enforces domestic content requirements that reshape cylinder block demand toward range-extender and hybrid-engine designs. Foundry clusters in Changzhou and Ningbo specialize in high-pressure die-casting for aluminum blocks serving BYD and Geely supply chains.
Germany
Euro 7 emissions protocols from the European Commission impose particulate number limits that constrain combustion chamber temperatures and thermal-management specifications. The KBA enforces type-approval standards that extend OEM validation timelines for integrated exhaust manifold designs. Engine plants in Lower Saxony and Baden-Württemberg demand just-in-sequence aluminum block delivery with zero ppm defect rates from captive and tier-1 suppliers.
United States
EPA Corporate Average Fuel Economy standards penalize curb weight, accelerating OEM procurement of aluminum blocks with integrated thermal-management galleries. The NHTSA coordinates with EPA on enforcement mechanisms that tighten fleet-average requirements through 2032. Foundry operations in Kentucky and Michigan supply General Motors and Ford engine plants with hybrid-program capacity locked through long-term offtake agreements.
Japan
METI carbon-neutral targets and domestic vehicle production sustain demand for precision-machined aluminum blocks in compact and hybrid architectures. The Ministry of Land, Infrastructure, Transport and Tourism enforces emissions standards that align with Euro 7 thermal-efficiency thresholds. Manufacturing clusters in Aichi prefecture and Hiroshima prefecture anchor Yasunaga Corporation and Mazda supply chains for small-displacement gasoline engines.
India
The PLI scheme for advanced automotive components attracts greenfield aluminum casting investments serving Maruti Suzuki and Hyundai Motor India supply chains. BIS certification requirements for automotive components extend supplier qualification timelines for foreign foundries entering the market. Industrial corridors in Gujarat and Tamil Nadu concentrate new capacity for medium-power four-cylinder blocks displacing gray iron in passenger-car programs.
Automotive Engine Cylinder Block Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM captive foundries controlling specification authority while independent suppliers compete on die-casting precision and machining capability. The supplier base concentrates among tier-1 specialists with backward integration into raw material processing and multi-material bonding expertise. Three archetypes dominate: vertically integrated engine manufacturers, precision machining specialists, and high-pressure die-casting foundries. Competitive moves center on long-term capacity reservation agreements and additive manufacturing adoption for core tooling reduction.
Among North American and European engine manufacturers, Cummins and Deutz occupy positions representing heavy-duty and industrial powertrain specialization. Japanese precision fabricators include Yasunaga Corporation and Ahresty Corporation, exemplifying machining-intensive and die-casting-intensive archetypes respectively. These named entities anchor the competitive landscape without implying specific market share or strategic action claims.
| Leading Market Players |
|---|
| Cummins |
| Perkins Engines Company |
| Yasunaga Corporation |
| Fiat Chrysler Automobiles |
| Deutz |
| Cooper Corporation |
| Ahresty Corporation |
| Rico Auto Industries |
| Seaco Pvt Ltd |
| Others |
Supply Flow & Price Mechanics
Precision machinist concentration in Aichi prefecture and Lower Saxony widens labor-cost spreads between premium Japanese-German supply tiers and economy-grade Chinese foundry output, compressing mid-market pricing bands as OEMs dual-source across qualification levels.
Pricing Analysis
Volume concentration in aluminum-silicon passenger-car blocks trades margin for capacity absorption, while CGI heavy-duty architectures capture premium pricing through material scarcity and extended validation cycles. Pricing stratifies across premium OEM captive supply, standard tier-1 merchant foundries, and economy-grade aftermarket remanufacturers. Cost compression in standard-tier aluminum programs intensifies as LME volatility squeezes independent foundries lacking captive smelter access. Aftermarket providers serving aging vehicle parcs in Texas and São Paulo exhibit highest price sensitivity, while German and Japanese OEMs prioritize zero-ppm defect rates over unit cost.
Supply Chain Analysis
Remanufactured cast iron blocks flow through reverse-logistics networks serving São Paulo and Texas aftermarket clusters, extending asset life cycles as passenger-car demand shifts irreversibly toward aluminum. Primary supply concentrates in China, Germany, and Japan, with foundry clusters in Changzhou, Lower Saxony, and Aichi prefecture anchoring regional output. The chain draws from primary aluminum smelters in Quebec and Shandong, compacted graphite iron producers in Michigan, and precision machining equipment manufacturers in Switzerland. Single-source vulnerability around high-pressure die-casting core boxes constrains rapid program ramp-ups. Distribution runs through just-in-sequence engine plant operations with take-or-pay capacity reservation structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive engine cylinder block market operates as a vertical-integration race where captive smelter access and precision machining capability determine margin capture. Players are pursuing upstream control over primary aluminum supply as the decisive lever.
For Market Incumbents: Lock in long-term offtake agreements with hybrid-program OEMs before additive manufacturing disrupts traditional sand-casting economics. Secure captive smelter capacity or scrap-recycling operations to insulate margin predictability from LME volatility. Battery electric substitution threatens stranded assets for single-product gray iron foundries. For New Entrants and Emerging Players: Binder-jet printed sand core technology offers a technology-first wedge into topology-optimized coolant passage designs previously impossible with conventional pattern-making. Target India's PLI scheme corridors in Gujarat and Tamil Nadu for greenfield aluminum casting investments. Pursue qualification as tier-1 supplier to Maruti Suzuki and Hyundai Motor India through BIS certification pathways. For Investors and Strategic Acquirers: Re-rating potential sits with precision machining specialists given Euro 7 thermal-management requirements extending OEM validation timelines. Long-term viability favors foundries with multi-material bonding expertise and backward integration into raw material processing. Monitor EPA CAFE standard enforcement mechanisms and China's MIIT localization quotas as inflection indicators for capacity utilization shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Smelter Acquisition | Insulates margin predictability from LME aluminum price volatility for independent foundries. |
| Additive Manufacturing Adoption | Binder-jet printed sand cores reduce tooling costs and enable geometric complexity for hybrid blocks. |
| Long-term Capacity Reservation | Take-or-pay structures with German and Japanese OEMs secure utilization through hybrid program volumes. |
| Multi-material Bonding Certification | Friction-stir welded aluminum-steel hybrids unlock premium performance applications with extended validation. |
| Reverse-logistics Network Buildout | Remanufacturing capacity in Texas and São Paulo captures aftermarket demand from aging vehicle parcs. |
Methodological Framework
Multi-period observation of EPA CAFE compliance trajectories, Euro 7 type-approval timelines, and MIIT localization quotas anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, foundry operations managers, and precision machining equipment specialists. Secondary validation drew from EPA enforcement disclosures, KBA type-approval registers, vehicle production databases, IHS Markit registration data, and SEC filings from listed automotive suppliers. Bottom-up capacity modeling across Changzhou, Lower Saxony, and Kentucky foundry clusters triangulated against top-down OEM procurement survey data.
Input-output matrices linked primary aluminum ingot supply from Quebec and Shandong smelters through high-pressure die-casting and CNC machining stages to final engine plant assembly. Segmentation dimensions spanned material grade, end-user integration level, manufacturing stage intensity, and power-band thermal loading. CAGRs were derived from production volume reconciliations against OEM platform launch schedules and powertrain architecture shift assumptions. Forecast inputs incorporated MIIT new-energy vehicle quota enforcement and Euro 7 particulate number limit implementation pacing.
Several conditions sit outside the modeled scope, including unforeseen battery electric platform acceleration, trade policy disruptions affecting aluminum scrap flows, and breakthroughs in solid-state battery commercialization eliminating range-extender architectures. Forecasts reflect documented assumptions about regulatory enforcement continuity and OEM program timing. Practitioners should monitor EPA rulemaking comments, KBA validation backlog reports, and MIIT quarterly production statistics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
LNG Engine Market
Powertrain
Tachometer Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Gasoline Turbochargers Market
Powertrain
Car Active Purge Pump Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Global Automotive Clutch Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Iridium Spark Plug Market
Powertrain
Diesel Engine Market