
 Packed Vegan Foods Market | 2026-2036
Packed Vegan Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Packed Vegan Foods Market Analytics
Foodservice procurement is pivoting toward pre-portioned vegan meal solutions as contract caterers and institutional kitchens seek labor efficiency and menu standardization. Beyond Meat, Inc. leverages its extrusion technology leadership to supply high-volume foodservice channels with consistent protein texture. Amy's Kitchen, Inc. anchors the organic frozen meal segment through dedicated vegetarian production facilities and certified clean-label formulations. Oatly Group AB competes aggressively in barista-grade oat milk, controlling café distribution networks that drive brand trial and repeat purchase.
Packed vegan foods comprise plant-derived ingredients processed into shelf-stable or refrigerated formats using techniques such as high-pressure processing, retort sterilization, or modified-atmosphere packaging to achieve target water activity below 0.85 and extend commercial viability without animal inputs. Snacks and meals dominate current revenue contribution due to frequency of purchase and meal-replacement utility, while desserts command premium positioning through indulgence-oriented formulations that justify higher unit margins. Pouch packaging is gaining share against rigid containers as brands reduce material weight and target on-the-go consumption occasions among flexitarian and health-conscious consumer segments.
The FDA maintains standards of identity and allergen labeling requirements that packed vegan foods must satisfy for US interstate commerce, while the EU Green Deal and REACH frameworks govern packaging material sustainability and chemical migration limits across European markets. EFSA novel food approvals create variable timelines for ingredient market access, particularly for emerging protein sources such as precision-fermented dairy alternatives. Stakeholders must monitor evolving compostability mandates and front-of-pack labeling schemes that will determine which formulations retain retail distribution priority.
Market Dynamics
Foodservice procurement teams are consolidating supplier relationships around shelf-stable vegan formats that reduce kitchen labor and inventory complexity. This operational imperative is compressing vendor selection criteria toward extrusion-capable manufacturers with validated clean-label credentials.
Growth Catalysts
- EU Green Deal packaging mandates:Compostable barrier film requirements are forcing European co-packers to retool lines, creating first-mover advantages for brands with certified sustainable packaging already in market.
- Contract catering standardization:Institutional kitchens across Germany and France are specifying pre-portioned vegan proteins to reduce prep time and menu variance across multi-site operations.
- Precision fermentation scale-up:Emerging dairy-alternative ingredient streams are securing novel food approvals from EFSA, unlocking formulation flexibility for dessert and beverage applications.
Market Restraints
- Oat protein input volatility:Nordic oat harvest fluctuations and grain trading concentration in Scandinavian cooperatives create margin pressure for barista-grade milk alternatives.
- Retort sterilization capex barriers:Shelf-stable meal production requires capital-intensive autoclave infrastructure that fragments supply capacity among a limited set of European toll manufacturers.
- REACH chemical migration limits:Recycled content mandates for food-contact materials are technically constrained by detection thresholds for mineral oil saturated hydrocarbons, limiting circular packaging claims.
Strategic Opportunities
- Discounter private-label expansion:German hard discounters are elevating vegan ranges to premium aisle positioning, opening volume slots for manufacturers with dedicated vegetarian production facilities.
- High-pressure processing convergence:Cold-pasteurization technology paired with modified-atmosphere packaging is enabling refrigerated meal formats with extended shelf life and cleaner ingredient decks.
- Café distribution network capture:Barista-grade oat milk brands that secure exclusive equipment placement in independent coffee shops are building trial-to-loyalty conversion at lower customer acquisition cost than retail.
Industry Challenges
- Novel food approval timelines:EFSA's scientific opinion queues for precision-fermented proteins are extending market access delays beyond eighteen months for emerging ingredient suppliers.
- Extrusion technician scarcity:High-moisture extrusion operation requires specialized protein-texturization expertise that outpaces current vocational training output in European food manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packed Vegan Foods Market |
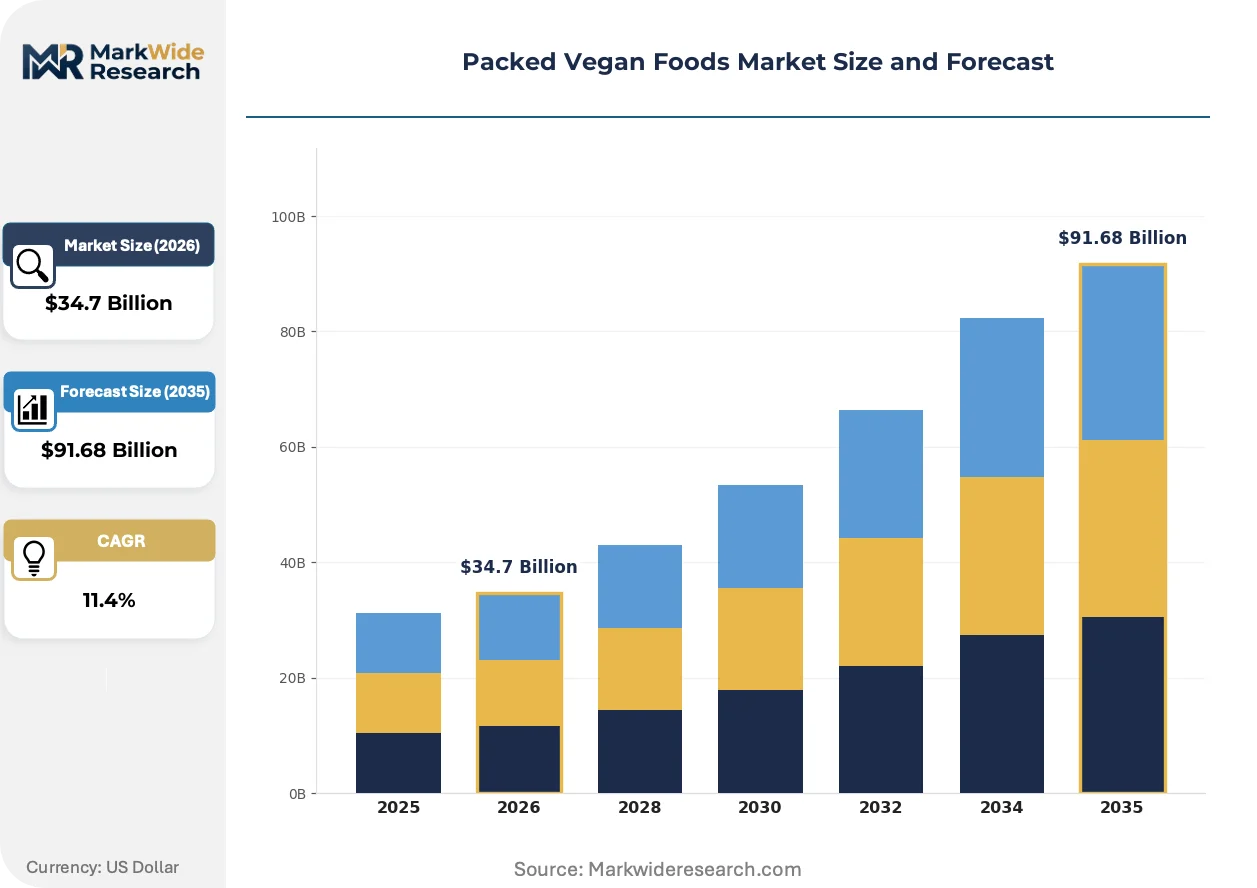
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Meals, Desserts, Condiments Packaging Type: Containers, Pouches, Boxes, Jars Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores Customer Type: Vegetarians, Flexitarians, Health-Conscious Consumers, Eco-Friendly Consumers |
| Companies Covered | Danone S.A., Beyond Meat, Inc., Impossible Foods Inc., Amy's Kitchen, Inc., Tofutti Brands, Inc., Annie's Homegrown, Inc., Oatly Group AB, Plamil Foods Ltd., General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packed Vegan Foods Market Evolving Landscape
Active reformulation and packaging technology deployment are compressing product development cycles while regulatory pressure on material sustainability intensifies. Three concurrent developments are restructuring competitive positioning.
High-moisture extrusion is rewriting protein texture replication standards. Contract caterers in France and Germany are adopting these formats for their consistency across batch volumes. The technology is compressing the performance gap between plant-based and conventional meat systems in institutional foodservice specifications.
REACH framework amendments on chemical migration are forcing laminate structure redesigns. European converters are trialing bio-based barrier layers to maintain oxygen transmission rates below 0.1 cc/m²/day. Dessert and ready-meal segments with premium positioning are absorbing material cost premiums to retain retail distribution.
Flexitarian consumers are consolidating purchase decisions around front-of-pack certification marks. Retail buyers in Germany are prioritizing SKUs with combined organic and climate-neutral labels, displacing conventional vegan products lacking third-party verification. Discounter assortment reviews are reflecting this preference compression most visibly.
Packed Vegan Foods Market Segmentation
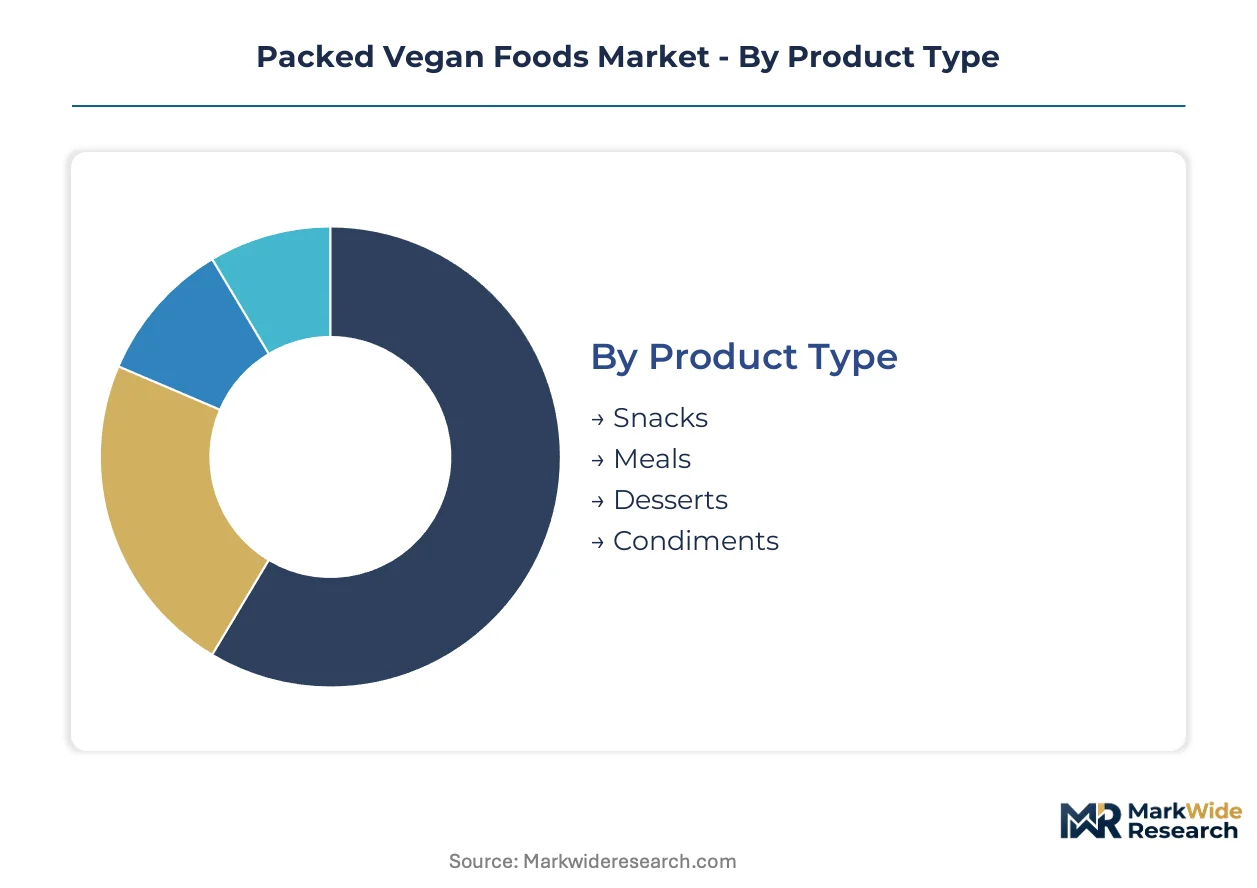
Segmentation in packed vegan foods reveals how supply chain configuration and procurement priorities fragment demand across product formats and channel structures. Understanding these divides exposes where extrusion capacity, barrier film innovation, and distribution slotting concentrate competitive advantage.
Product Type:
Extrusion-capable manufacturers and retort infrastructure owners concentrate supply capacity around specific meal formats, with demand fragmentation tracking institutional procurement versus retail velocity.
- Snacks:Shelf-stable formats using high-pressure processing or modified-atmosphere packaging dominate this segment. German discounters and French contract caterers drive volume through private-label protein puffs and seared strips that reduce kitchen labor.
- Meals:Retort-sterilized bowls and trays requiring autoclave investment represent the most capital-intensive production. Pre-portioned formats are capturing institutional foodservice specifications across Germany and France as multi-site operators standardize menus.
- Desserts:Precision-fermented dairy alternatives and coconut-based formulations occupy premium positioning. EFSA novel food approvals are gating ingredient access for emerging players.
- Condiments:Fermented plant-based sauces and cultured creams serve flexitarian transition demand. Clean-label formulations without synthetic stabilizers are securing shelf space in health-focused retail.
Meals absorb the bulk of installed capacity; snacks are expanding most quickly.
Packaging Type:
Material weight reduction and compostability mandates are reshaping converter relationships, with REACH chemical migration limits forcing laminate redesigns across European supply chains.
- Pouches:Flexible multilayer structures with bio-based barrier layers are displacing rigid formats. On-the-go consumption among flexitarian commuters drives adoption in German urban retail.
- Containers:Modified-atmosphere rigid trays remain essential for high-moisture extruded proteins. Retort-capable polypropylene formats serve shelf-stable meal applications where autoclave processing is required.
- Boxes:Paperboard with grease-resistant coatings targets premium frozen dessert positioning. EU Green Deal compliance is accelerating fiber-based material trials.
- Jars:Glass and high-barrier PET formats dominate condiment and cultured cream segments. Chemical migration testing for recycled content is constraining circular claims under REACH frameworks.
Pouches absorb the bulk of installed capacity; containers are expanding most quickly.
Distribution Channel:
Channel selection determines margin structure and certification requirements, with discounter slotting rules and café equipment placement creating divergent path-to-consumer economics.
- Supermarkets:Front-of-pack certification marks and combined organic-climate-neutral labels determine assortment priority. German retail buyers are displacing uncertified vegan SKUs in favor of third-party verified alternatives.
- Online Retail:Direct-to-consumer subscription models for frozen meals and precision-fermented desserts bypass conventional slotting fees. Cold-chain logistics investment is gating scale for refrigerated formats.
- Health Stores:Certified clean-label and allergen-free formulations command price premiums. Dedicated vegetarian production facility credentials are mandatory for shelf placement.
- Convenience Stores:Single-serve pouches and ambient-stable protein snacks target impulse purchase occasions. Limited refrigeration capacity favors retort-sterilized over chilled formats.
Supermarkets absorb the bulk of installed capacity; online retail is expanding most quickly.
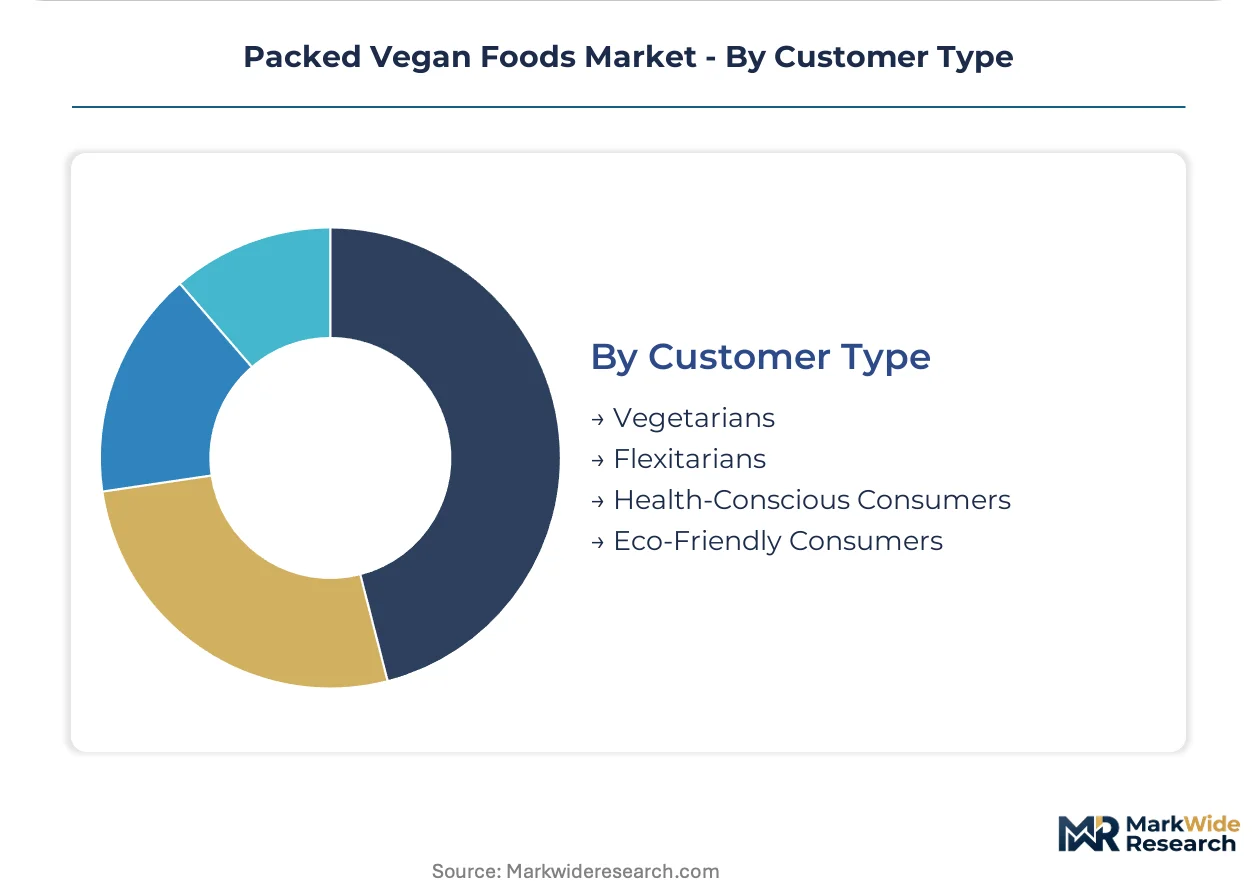
Customer Type:
Purchase frequency and certification sensitivity fragment demand, with flexitarian trial behavior and eco-conscious premium willingness creating distinct value pool concentrations.
- Flexitarians:This segment drives volume through protein-forward snacks and familiar meal formats that reduce animal product dependence without full dietary conversion. German and French urban consumers show highest trial rates for extruded meat alternatives.
- Health-Conscious Consumers:Clean-label ingredient decks and low-sodium formulations are non-negotiable purchase criteria. High-pressure processed refrigerated meals with extended shelf life are capturing this demand.
- Vegetarians:Established dietary commitment supports premium pricing for certified organic and dedicated facility production. Loyalty concentrates around familiar brands with long-standing vegetarian credentials.
- Eco-Friendly Consumers:Compostable packaging and climate-neutral certification marks override price sensitivity. EU Green Deal alignment is becoming a threshold requirement for consideration.
Flexitarians absorb the bulk of installed capacity; eco-friendly consumers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the Netherlands and Belgium concentrate European co-packing capacity for plant-based meal formats. These logistics hubs serve contract catering procurement across Germany and France with reduced customs friction.
Germany
Discounter private-label vegan ranges now command premium aisle positioning in Berlin and Hamburg retail. The EU Green Deal packaging mandates accelerate compostable barrier film trials among Baden-Württemberg converters. Bavaria hosts dedicated vegetarian production facilities supplying institutional foodservice across the DACH region.
United States
FDA standards of identity enforcement shapes interstate commerce for precision-fermented dairy alternatives. California clusters high-moisture extrusion R&D near Los Angeles and San Francisco Bay Area food-tech incubators. Midwest soybean processing corridors supply protein isolates to Chicago-area contract manufacturers.
United Kingdom
London-based foodservice distributors consolidate procurement around pre-portioned vegan proteins for contract catering. EFSA novel food approval timelines delay ingredient access for emerging precision-fermentation suppliers. Manchester and Birmingham co-packers specialize in retort-sterilized meal trays for NHS institutional kitchens.
France
Parisian contract caterers specify high-moisture extruded formats for multi-site menu standardization. REACH chemical migration limits force laminate redesigns among Lyon packaging converters. The Île-de-France region concentrates clean-label formulation expertise for organic-certified dessert ranges.
Netherlands
Rotterdam port logistics enable oat protein import flows from Nordic cooperatives. EFSA novel food queues extend approval timelines for emerging dairy-alternative ingredients. Eindhoven packaging technology clusters trial bio-based barrier layers under EU Green Deal compliance deadlines.
Packed Vegan Foods Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with shelf-stable meal production concentrating among retort-capable toll operators while refrigerated formats fragment across regional dairies. The vendor base organizes around three archetypes: extrusion-technology leaders, organic-certified clean-label specialists, and oat-milk platform operators with café distribution lock-in. Capacity expansion and strategic partnerships dominate competitive moves, particularly around high-pressure processing infrastructure and compostable packaging certification.
Within the branded specialist tier, Beyond Meat, Inc. and Amy's Kitchen, Inc. exemplify divergent positioning—one anchored in foodservice extrusion supply, the other in organic frozen meal certification. Oatly Group AB occupies a distinct platform position built on barista-grade format penetration and equipment placement economics. These three represent the primary competitive vectors: protein-texture technology, clean-label production credentials, and beverage-platform distribution capture.
| Leading Market Players |
|---|
| Danone S.A. |
| Beyond Meat, Inc. |
| Impossible Foods Inc. |
| Amy's Kitchen, Inc. |
| Tofutti Brands, Inc. |
| Annie's Homegrown, Inc. |
| Oatly Group AB |
| Plamil Foods Ltd. |
| General Mills Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters in Baden-Württemberg and Rhineland-Palatinate anchor European compostable film supply, their conservative balance sheets limiting capacity expansion despite EU Green Deal procurement mandates. This ownership pattern tightens pricing discipline across shelf-stable vegan formats as institutional buyers compete for finite autoclave toll-manufacturing slots.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as German discounters and French contract caterers compete for retort-sterilized meal capacity. Three-tier pricing structure across premium certified-organic, standard clean-label, and economy private-label levels tracks certification investment and dedicated facility credentials. Pricing pressure stems from Nordic oat protein input volatility and Scandinavian cooperative grain trading concentration. Flexitarian consumers in urban German retail show least price sensitivity for front-of-pack climate-neutral marks, while institutional foodservice procurement teams drive hardest volume discount negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Nordic oat protein suppliers and Baden-Württemberg retort toll manufacturers, constraining format expansion for emerging brands. Geographic supply concentrates in Germany, France, and the Netherlands, with Rotterdam port logistics feeding Nordic grain flows and Eindhoven packaging clusters trialing bio-based barrier layers. Raw material dependencies span oat isolates, high-moisture extrusion protein blends, and compostable laminate substrates. Tariff exposure on Nordic grain imports through Rotterdam creates margin volatility. Distribution runs through Dutch-Belgian co-packing hubs serving DACH and French institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort sterilization capex barriers and extrusion technician scarcity prop pricing power for incumbent toll manufacturers. Supply-constrained dynamics favor early capacity commitments over spot-market procurement.
For Market Incumbents: To counter precision-fermentation ingredient suppliers encroaching on dessert positioning, secure exclusive multi-year equipment placement contracts with independent café networks and deepen backward integration into Nordic oat protein sourcing through offtake agreements with Scandinavian cooperatives. For New Entrants and Emerging Players: Begin with high-pressure processed refrigerated meals targeting German health-conscious flexitarians, where clean-label positioning commands premium shelf space and cold-chain logistics investment barriers filter incumbent competition. White-space exists in precision-fermented condiments awaiting EFSA novel food approval. For Investors and Strategic Acquirers: Distressed-cycle entries favor retort-capable toll manufacturers with validated EU Green Deal packaging certifications in the Netherlands and Belgium. Long-term viability hinges on captive extrusion technician pipelines and compostable barrier film R&D partnerships. Signal to monitor: EFSA novel food approval queue compression for emerging dairy-alternative proteins.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Capacity Expansion | Autoclave infrastructure investments in Germany and France capture institutional foodservice procurement consolidation. |
| Compostable Packaging Certification | EU Green Deal compliance unlocks discounter premium aisle positioning for Baden-Württemberg converters. |
| High-Pressure Processing Convergence | Cold-pasteurization technology extends refrigerated meal shelf life for clean-label flexitarian demand. |
| Café Equipment Placement | Exclusive oat milk dispenser contracts with Berlin and Hamburg independent coffee shops build trial-to-loyalty conversion. |
| Precision-Fermentation Scale-Up | EFSA novel food approvals for emerging dairy-alternative ingredients unlock dessert formulation flexibility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of contract catering procurement directors, retort toll-manufacturing plant managers, German discounter category buyers, and Eindhoven packaging converter R&D leads. Bottom-up SKU-level velocity data triangulated against top-down EFSA novel food approval tracking and EU Green Deal implementation timelines across member states.
Data-stream reconciliation employed product-format segmentation by shelf-stable versus refrigerated processing technology, packaging material compliance tier, and distribution channel slotting economics. CAGRs derived from installed capacity utilization rates and procurement contract renewal patterns across the analysis window. Forecast inputs incorporated Nordic oat harvest yield variability and REACH chemical migration limit amendment schedules.
Novel food approval delays, Nordic grain trading concentration shifts, and compostable barrier film technical yield failures are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about regulatory timeline trajectories and institutional procurement standardization rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Oat Protein Market
Plant Based Food
Asia-Pacific Pea Protein Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
United States Pea Protein Market