
 Machine Vision Market | 2026-2036
Machine Vision Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Vision Market Insights
Aftermarket service revenue is reconfiguring profit pools across the machine vision value chain. Cognex Corporation leverages its installed base of barcode readers and vision systems to build recurring software maintenance contracts. KEYENCE CORPORATION anchors its competitive position through direct sales engineers who control technical consultation and system integration workflows. Basler AG specializes in industrial camera hardware, competing on sensor customization and GigE Vision protocol compliance rather than full-stack solutions.
Machine vision comprises electro-optical systems that capture, process, and analyze image data to automate inspection, measurement, and guidance tasks in industrial environments. These systems typically integrate CMOS or CCD sensors with resolutions from VGA to 25 megapixels, paired with specialized illumination and processing algorithms to execute decisions in sub-100-millisecond cycles. Smart cameras and vision sensors now dominate unit shipments by embedding processing directly at the edge, reducing latency for robotic guidance and quality inspection workflows. 3D vision and time-of-flight technologies represent the fastest-expanding technology layer as automotive battery pack assembly and semiconductor packaging demand depth-perception capabilities that 2D systems cannot deliver.
FDA software-as-medical-device oversight and the EU AI Act's risk-classification framework are elevating validation burdens for vision systems deployed in pharmaceutical production and food safety inspection. China's MIIT GB standards and SAMR certification requirements further fragment market access, forcing suppliers to maintain multiple compliance portfolios. Stakeholders must weigh regional regulatory divergence against the cost of modular platform architectures that can absorb jurisdiction-specific validation modules without full system redesign.
Market Dynamics
3D vision and time-of-flight sensors are collapsing the traditional boundary between hardware capture and real-time depth processing, forcing suppliers to rearchitect product portfolios around edge-computing inference rather than centralized vision controllers.
Growth Catalysts
- EU AI Act risk classification:Pharmaceutical manufacturers in Germany and France now mandate validated vision systems for defect detection, creating compliance-driven replacement cycles.
- Semiconductor packaging:Taiwan and South Korea wafer fabs embed machine vision at every inspection stage to maintain yield rates below 3nm process nodes.
- Smart camera edge processing:Embedded GPU and FPGA architectures reduce latency for robotic guidance below 50 milliseconds, displacing PC-based vision controllers in high-speed assembly.
Market Restraints
- CMOS sensor supply concentration:Sony and Samsung control over 70% of high-performance industrial image sensor output, creating single-source vulnerability for camera manufacturers.
- FDA software-as-medical-device validation:Pharmaceutical vision deployments require 18-24 month approval timelines, freezing capital allocation and compressing supplier margins.
- Laboratory-grade 3D vision cost structure:Structured-light and time-of-flight modules cost 4-6x equivalent 2D systems, limiting penetration outside automotive battery assembly.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for smartphone and component production create first-mover advantage for vision system integrators establishing local service networks.
- Food safety inspection automation:EU EFSA and national regulators are mandating optical sorting for allergen detection, opening greenfield deployment in protein processing facilities.
- Hyperspectral-vision convergence:Combining spectral imaging with deep learning enables chemical composition analysis, expanding addressable market from quality inspection to materials verification.
Industry Challenges
- Embedded vision engineering talent scarcity:Shortage of engineers proficient in both optical system design and TensorRT optimization limits product development velocity.
- Multi-jurisdiction certification burden:Suppliers must maintain parallel validation portfolios for FDA, EU AI Act, and China MIIT GB standards without modular platform architectures.
- Retrofit integration complexity:Legacy PLC and robotic controller protocols require custom gateway development, extending deployment timelines and eroding project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Vision Market |
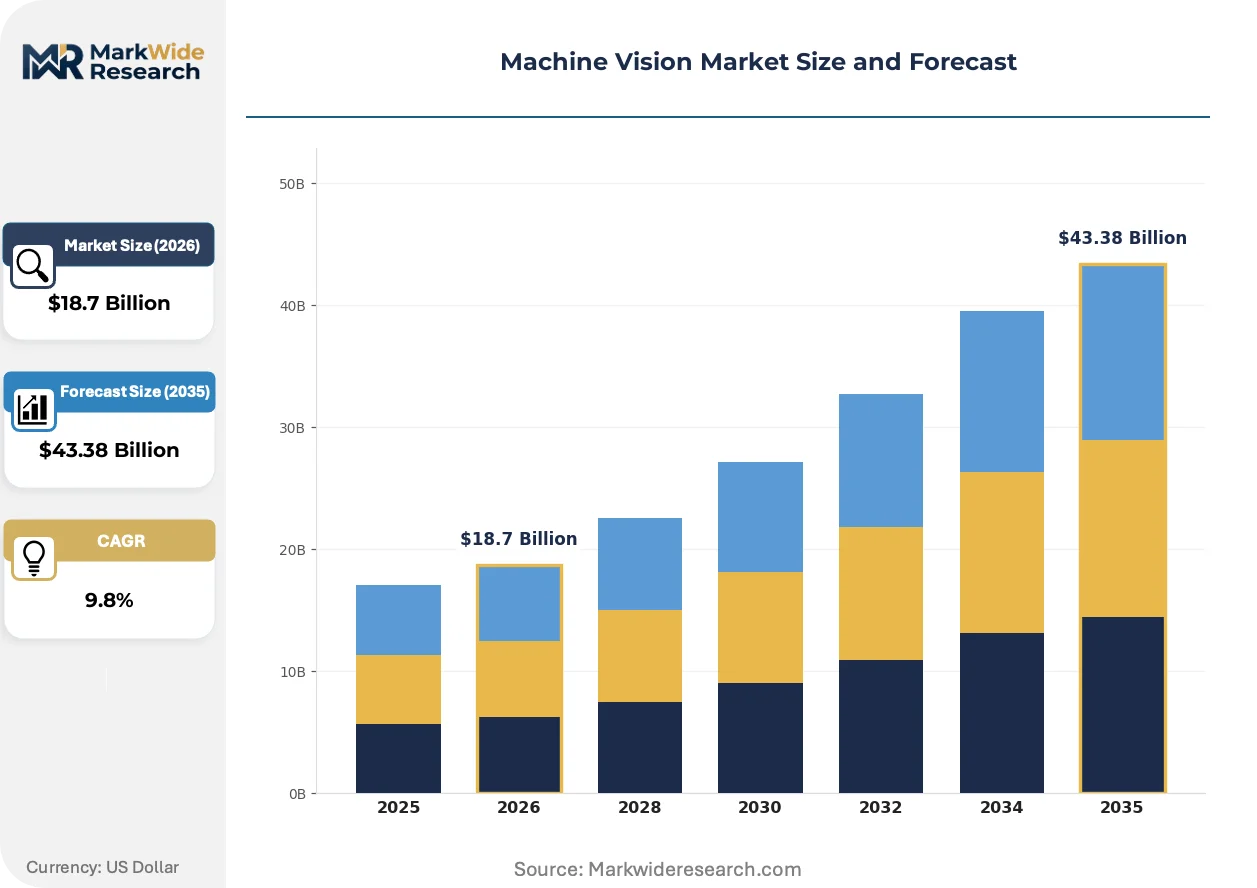
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cameras, Vision Sensors, Vision Software, Illumination Systems, Frame Grabbers Technology: 2D Vision, 3D Vision, Hyperspectral Imaging, Time-of-Flight, Infrared Imaging Application: Quality Inspection, Robotic Guidance, Barcode Reading, Surface Inspection, Sorting Systems End User Industry: Electronics Manufacturing, Food Processing, Packaging, Pharmaceutical Production, Semiconductor Assembly |
| Companies Covered | Cognex Corporation, KEYENCE CORPORATION, OMRON Corporation, Basler AG, Teledyne Technologies, Siemens, SICK AG, National Instruments, Allied Vision Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Vision Market Trends and Innovations
Vision system architectures are migrating from centralized processing to distributed edge inference, compressing hardware hierarchies and redefining how suppliers capture value across the technology stack.
Time-of-flight depth sensors are collapsing the cost-performance barrier that historically separated 2D inspection from 3D metrology. Automotive battery pack assemblers in Germany and China now deploy single-sensor solutions for weld inspection and dimensional verification, eliminating the need for separate laser triangulation systems. This convergence is compressing average selling prices for mid-range 3D vision hardware by half within three product generations.
China's MIIT GB standards and SAMR certification requirements are fragmenting market access protocols for foreign vision suppliers. Domestic camera manufacturers gain preferential approval timelines, while international vendors face extended technical documentation requirements. European and Japanese suppliers respond by establishing captive testing laboratories in Shanghai and Shenzhen to compress regulatory lead times.
Aftermarket service contracts are displacing perpetual software licenses as the dominant revenue mechanism for vision system vendors. Automotive OEMs in Michigan and Bavaria now demand predictive maintenance subscriptions tied to inspection throughput rather than upfront capital expenditure. This shift concentrates bargaining power with buyers who operate multi-site production networks and can consolidate service procurement across facilities.
Machine Vision Market Segmentation
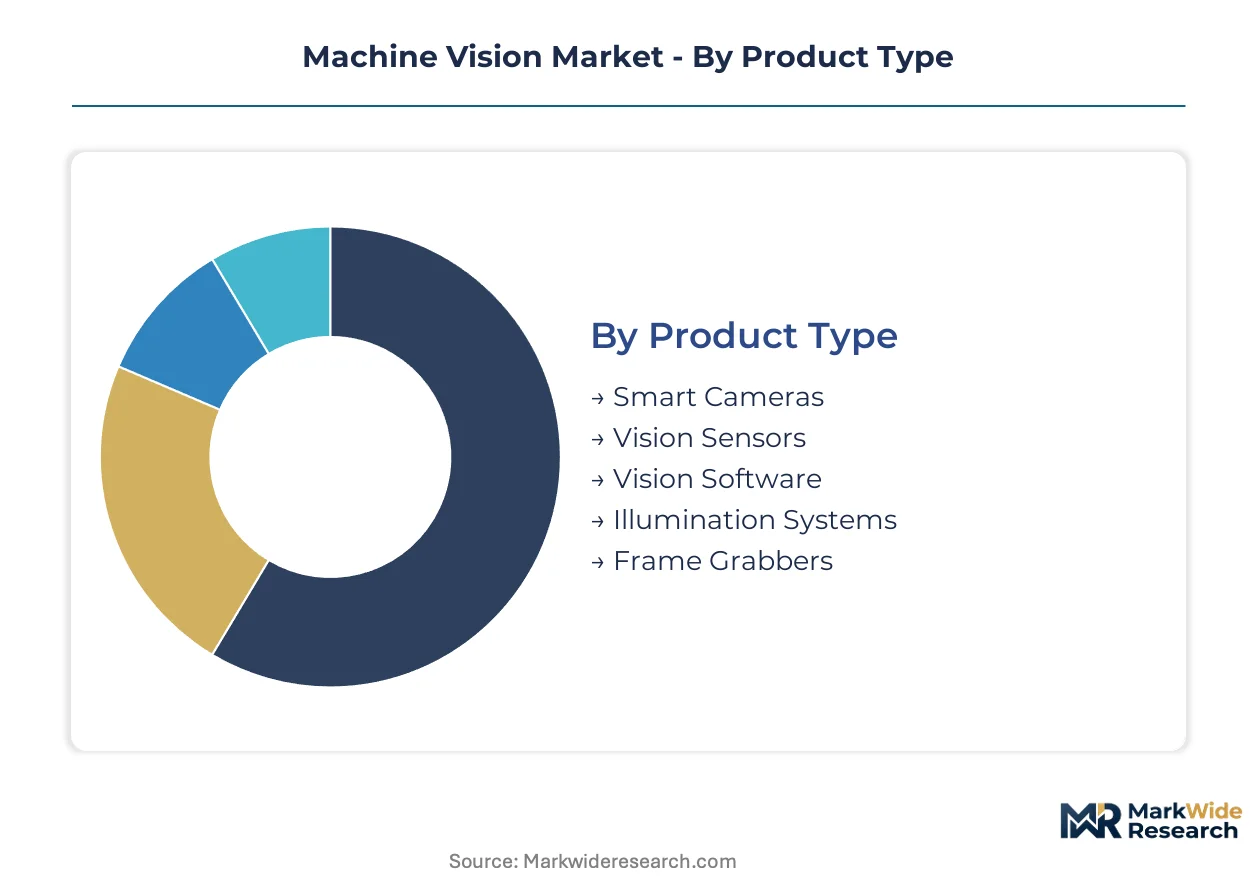
Machine vision segmentation reveals how hardware commoditization, software value capture, and vertical specialization reshape supplier economics. Suppliers must choose between full-stack integration and component dominance as edge computing collapses traditional system hierarchies.
Product Type:
Cost tier differentiation separates embedded edge devices from software-licensing revenue models in this hardware-software hybrid market.
- Smart Cameras:Embedded GPU and FPGA architectures integrate image capture with on-device inference, eliminating PC-based controllers. Taiwan and South Korea electronics manufacturers deploy these for sub-50-millisecond robotic guidance cycles.
- Vision Sensors:Compact units with fixed optics and pre-trained detection algorithms target high-volume barcode reading and presence-absence checks. Cognex and KEYENCE dominate installed bases through direct sales engineer networks that control integration workflows.
- Vision Software:Algorithm libraries and deep learning toolkits license per-inspection-line or subscription models. FDA software-as-medical-device validation requirements extend pharmaceutical deployment timelines to 18-24 months.
- Illumination Systems:Structured LED arrays and strobed lighting modules optimize contrast for specific surface geometries. Custom wavelength configurations differentiate premium tiers.
- Frame Grabbers:Interface cards bridge camera sensors to host processors, declining in volume as GigE Vision and USB3 Vision standards enable direct connectivity.
Smart cameras command the established base. The steepest expansion runs through vision software subscriptions.
Technology:
Application requirements for depth perception and material composition analysis are fragmenting the technology landscape beyond traditional 2D imaging.
- 2D Vision:Area scan and line scan configurations using CMOS sensors from VGA to 25 megapixels handle 80% of industrial inspection tasks. Mature pricing compresses margins for camera manufacturers dependent on Sony and Samsung sensor supply.
- 3D Vision:Stereo vision, laser triangulation, and structured light methods deliver dimensional metrology for automotive battery pack assembly. Laboratory-grade modules cost 4-6x equivalent 2D systems, limiting penetration outside high-value welding verification.
- Hyperspectral Imaging:Spectral cameras capture 100+ wavelength bands to identify chemical composition and contamination. Food processing facilities in Germany adopt these for EU EFSA-mandated allergen detection protocols.
- Time-of-Flight:Single-sensor depth measurement collapses hardware complexity for mid-range 3D applications. China's battery manufacturers deploy these for weld inspection and dimensional verification.
- Infrared Imaging:Thermal detection identifies heat anomalies in semiconductor packaging and electrical assembly. Specialized sensor cooling requirements sustain premium pricing.
2D vision retains volume leadership. Hyperspectral and time-of-flight combinations are gaining share fastest in food safety and battery manufacturing.
Application:
Customer workflows for defect prevention versus process automation create divergent performance specifications and procurement patterns.
- Quality Inspection:Dimensional verification, defect classification, and assembly completeness checks dominate machine vision deployment. EU AI Act risk classification mandates validated systems for pharmaceutical defect detection in Germany and France.
- Robotic Guidance:Part localization, path correction, and collision avoidance require sub-100-millisecond latency. Smart camera edge processing displaces centralized controllers in high-speed electronics assembly.
- Barcode Reading:1D and 2D code verification for traceability and inventory management represents highest unit volumes. Lower technical barriers intensify price competition.
- Surface Inspection:Cosmetic defect detection on metals, glass, and plastics demands specialized illumination and texture analysis algorithms. Automotive OEMs in Michigan demand predictive maintenance subscriptions tied to throughput.
- Sorting Systems:High-speed ejection of defective items integrates vision with pneumatic or mechanical actuators. Protein processing facilities represent greenfield deployment opportunity under tightening EU food safety mandates.
Quality inspection commands the established base. Robotic guidance shows the steepest expansion trajectory as collaborative robot adoption accelerates.
End User Industry:
Geographic production clustering and regulatory intensity concentrate demand in electronics and life sciences corridors.
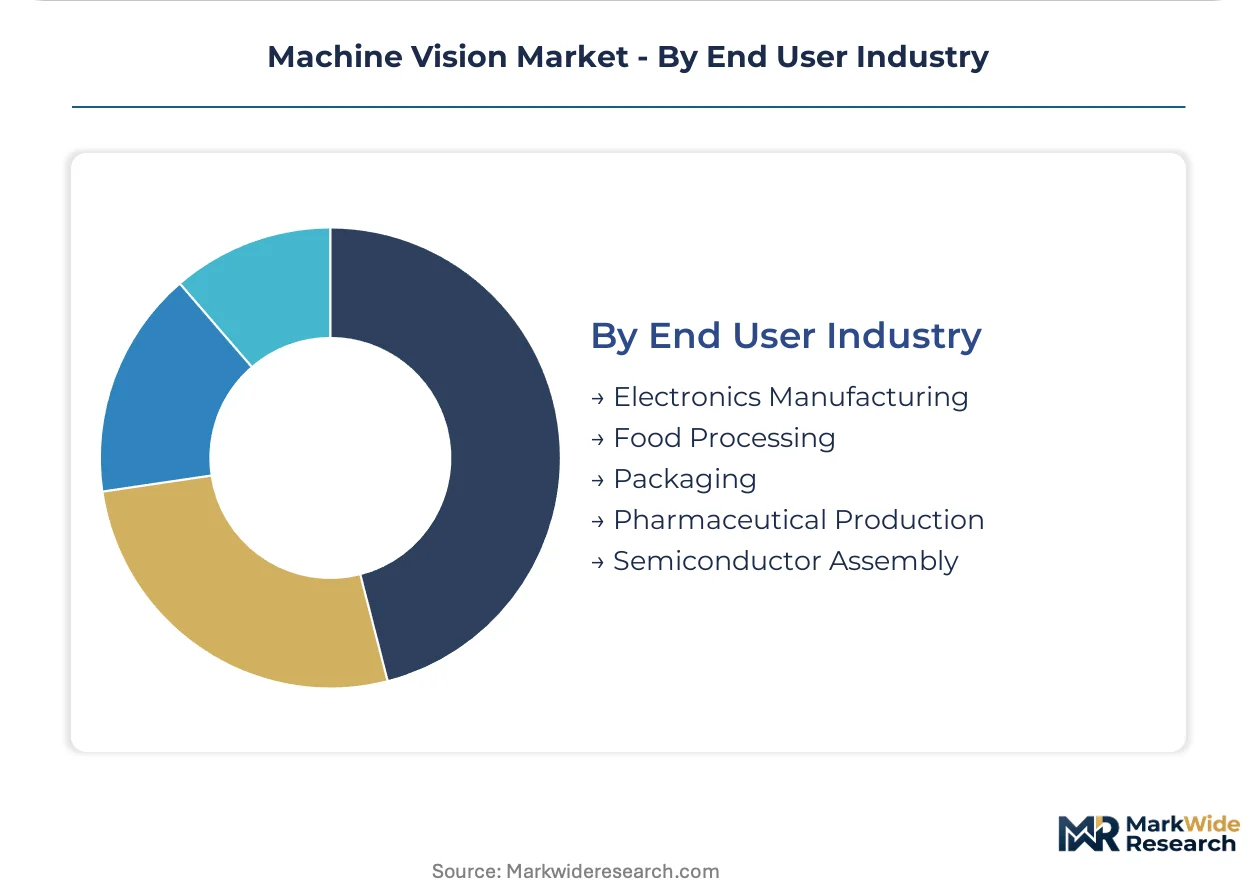
- Electronics Manufacturing:PCB inspection, component placement verification, and final assembly checks drive highest camera density per production line. China's provincial industrial policies subsidize smart factory retrofits in Shenzhen and Suzhou corridors.
- Food Processing:Optical sorting for contaminants, size grading, and packaging verification expands under EU EFSA and national allergen detection mandates. Hyperspectral convergence enables chemical composition analysis beyond visual defects.
- Packaging:Label verification, fill-level inspection, and seal integrity checks serve high-volume consumer goods production. Lower regulatory barriers sustain price competition.
- Pharmaceutical Production:FDA software-as-medical-device pathways and EU MDR requirements elevate validation burdens. Vision systems for tablet counting, blister inspection, and serialization require 18-24 month approval timelines.
- Semiconductor Assembly:Wafer inspection, die bonding verification, and packaging quality control embed vision at every process stage. Taiwan and South Korea fabs maintain yield rates below 3nm nodes through multi-stage automated inspection.
Electronics manufacturing commands the established base. Semiconductor assembly shows the steepest expansion as advanced packaging complexity intensifies inspection requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Semiconductor fabs in Taiwan and South Korea deploy machine vision at every wafer inspection stage for sub-3nm yield maintenance. Pharmaceutical manufacturers in Germany and France prioritize validated systems under EU AI Act risk classification. Electronics assemblers in China leverage provincial subsidies for smart factory retrofits.
China
Electronics manufacturing corridors in Shenzhen and Suzhou drive dense camera deployment per production line. MIIT GB standards and SAMR certification requirements fragment market access, forcing foreign suppliers to establish captive testing laboratories in Shanghai. Provincial industrial policies subsidize smart factory retrofits, concentrating demand in Yangtze River Delta and Pearl River Delta clusters.
Germany
Automotive battery pack assembly and pharmaceutical production anchor machine vision consumption. EU AI Act risk classification mandates validated vision systems for defect detection in pharmaceutical manufacturing. Bavaria and Baden-Württemberg host dense concentrations of automotive OEMs demanding predictive maintenance subscriptions tied to inspection throughput.
South Korea
Wafer fabs embed vision systems at every process stage to maintain yield rates at advanced nodes. MFDS regulatory alignment with FDA pathways streamlines pharmaceutical vision deployments for domestic biotech manufacturers. Seoul Capital Area and Busan-Ulsan corridors concentrate semiconductor packaging and electronics assembly demand.
United States
FDA software-as-medical-device pathways impose 18-24 month validation timelines for pharmaceutical vision deployments. Automotive OEMs in Michigan demand outcome-based service contracts rather than upfront capital expenditure. Greater Boston and Pacific Northwest clusters host machine vision R&D tied to robotics and AI acceleration.
India
PLI scheme subsidies for smartphone and component production create greenfield deployment opportunities. BIS certification requirements for industrial equipment slow foreign supplier market entry. Karnataka and Tamil Nadu electronics manufacturing corridors attract first-mover vision system integrators establishing local service networks.
Machine Vision Market Competitive Landscape
Capability concentration sits with specialized component manufacturers; scale advantage sits with full-stack system integrators. The market structures around three tiers: industrial camera hardware specialists, integrated smart camera and sensor providers, and vision software platform vendors. Dominant competitive moves include direct sales engineer networks controlling technical consultation workflows, and aftermarket service contracts displacing perpetual software licenses.
Among full-stack system integrators, Cognex Corporation and KEYENCE CORPORATION exemplify the direct sales engineer model that dominates high-volume electronics and automotive deployment. Basler AG occupies a position within the industrial camera hardware tier, competing on sensor customization and protocol compliance rather than integrated solutions. These three anchors illustrate how supplier economics diverge between component dominance and full-stack integration as edge computing collapses traditional system hierarchies.
| Leading Market Players |
|---|
| Cognex Corporation |
| KEYENCE CORPORATION |
| OMRON Corporation |
| Basler AG |
| Teledyne Technologies |
| Siemens |
| SICK AG |
| National Instruments |
| Allied Vision Technologies |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Sony and Samsung for high-performance CMOS sensors concentrates pricing power upstream while compressing margins for camera manufacturers, forcing tiered hardware sourcing strategies that separate premium sensor configurations from cost-optimized alternatives.
Pricing Analysis
Long-term service contracts now dominate commercial relationships, with automotive OEMs in Michigan and Bavaria subscribing to predictive maintenance tied to inspection throughput rather than purchasing perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from general industrial deployments, while aftermarket service bundling reduces price sensitivity among multi-site production networks. Cost compression in mid-range 3D vision hardware is intensifying because time-of-flight sensor convergence eliminates separate laser triangulation systems. Electronics manufacturers in China exhibit highest price sensitivity due to provincial subsidy constraints, whereas semiconductor fabs in Taiwan and South Korea prioritize yield assurance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China fragments component sourcing strategies for vision system assemblers. Manufacturing concentration in Taiwan, South Korea, and Japan supplies over 70% of industrial image sensor output, while Germany and China anchor illumination module and optical component production. Raw material dependencies on rare-earth phosphors for LED arrays, precision glass substrates, and FPGA silicon from TSMC create single-source vulnerability at multiple tiers. Distribution runs through direct sales engineer networks controlled by KEYENCE and Cognex, bypassing traditional distribution channels to capture integration workflow value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-computing inference architectures are collapsing traditional vision system hierarchies, creating asymmetric opportunity for suppliers who control embedded GPU optimization and TensorRT deployment pipelines.
For Market Incumbents: Insulate installed base value by converting perpetual software licenses into predictive maintenance subscriptions tied to throughput metrics, while deepening backward integration into sensor supply through strategic partnerships with Sony and Samsung to secure allocation priority during supply constraints. For New Entrants and Emerging Players: India's PLI-subsidized electronics manufacturing corridors offer the most penetrable geographic entry point, with Karnataka and Tamil Nadu production clusters lacking established local service networks. Target food safety inspection automation under EU EFSA allergen mandates as the lowest competitive intensity vertical, deploying hyperspectral-vision convergence as a differentiated technical wedge against established 2D incumbents. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors component specialists with embedded software capabilities over pure hardware manufacturers. Five-to-ten year viability hinges on edge AI optimization talent and multi-jurisdiction certification infrastructure. Watch FDA software-as-medical-device approval velocity as the critical signal for pharmaceutical vision system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Platform Integration | Embedded GPU architectures from NVIDIA and Intel reduce latency below 50 milliseconds for robotic guidance cycles. |
| Multi-Jurisdiction Certification Buildout | Parallel FDA, EU AI Act, and China MIIT GB validation portfolios unlock pharmaceutical and food safety verticals. |
| Backward Integration into Sensor Supply | Captive CMOS sensor allocation agreements with Sony and Samsung mitigate single-source vulnerability. |
| Aftermarket Service Network Expansion | Predictive maintenance subscriptions in Michigan and Bavaria convert capital expenditure into recurring revenue. |
| Hyperspectral-Vision Convergence | Spectral imaging combined with deep learning enables chemical composition analysis for EU EFSA allergen detection. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and vision system integration specialists. Secondary validation drew from SEC 10-K filings, customs and trade data, FDA software-as-medical-device submission databases, and EU AI Act implementation guidance. Bottom-up unit shipment modeling across smart cameras, vision sensors, and software subscriptions was triangulated against top-down market value estimates derived from supplier revenue disclosures.
Calibration against historical adoption curves in semiconductor packaging and automotive battery assembly informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product type, technology layer, application workflow, and end-user industry vertical. CAGRs were derived from fitted growth curves adjusted for regulatory approval timeline impacts and subsidy program phase-outs. Industry-specific inputs encompassed wafer fab capital expenditure cycles, PLI scheme disbursement schedules, and EU MDR implementation progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic camera manufacturers or hyperscaler edge AI entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
IR Camera Market
Imaging
Global in Ceiling Camera Market
Imaging
Hybrid Imaging Market
Imaging
Small CCTV Camera Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
High-Power Objective Lens Market
Imaging
Global Document Scanner Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Webcam Market
Imaging
Global Automotive Imaging Market
Imaging
Video Microscopes Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market
Imaging
High Dynamic Range Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Global Whole Slide Imaging Market
Imaging
Short-Wave Infrared (SWIR) Camera Market