
 Contract Packaging Market | 2026-2036
Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Packaging Market Intelligence
The rise of asset-light business models, where brands outsource capital-intensive packaging lines, is fragmenting the competitive landscape. Global players like Amcor leverage vast scale and a multi-material portfolio to serve large consumer packaged goods clients across multiple continents. In contrast, specialists such as Unicep Packaging differentiate through expertise in niche formats like single-use liquid and gel dispensing for the personal care industry. WestRock sustains its position by integrating paperboard supply with advanced machinery systems for automated cartoning.
Contract packaging involves outsourcing the process of enclosing or protecting products for distribution, storage, sale, and use. This service includes specialized operations like aseptic filling, which requires sterile environments to ensure product safety and extend shelf life for beverages and pharmaceuticals. Within service types, pouch filling and blister packaging are expanding rapidly, driven by the personal care and pharmaceutical industries. While plastic remains a dominant packaging material, paperboard and flexible films gain share due to sustainability pressures and material innovation.
Regulatory compliance is a critical competency, with agencies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) setting stringent cGMP standards. These regulations govern everything from material selection to process validation in pharmaceutical packaging. ISO 9001 certification for quality management is a baseline for serving multinational clients. Future success depends on navigating material science challenges while maintaining operational efficiency and full supply chain traceability.
Market Dynamics
The central force is the collision of sustainability mandates with asset-light business models. This creates demand for partners who can manage both cost-efficiency and the complex regulatory landscape for material circularity.
Growth Catalysts
- Food & Beverage Demand:
Expansion of single-serve formats in the food and beverage sector requires specialized pouch filling and flexible packaging, driving volume for contract packagers.
- EU Sustainability Mandates:
The CSRD compels brands to report packaging circularity, creating a pull for partners with expertise in certified recyclable and compostable materials.
- Manufacturing Relocation:
Production concentration in Vietnam and Thailand necessitates co-location of sophisticated contract packaging facilities to support regional export supply chains.
Market Restraints
- Material Cost Volatility:
Price fluctuations in polymer resins and paperboard create margin pressure, making it difficult to maintain stable pricing in long-term service agreements.
- Regulatory Divergence:
Navigating distinct cGMP requirements from the US FDA and European Medicines Agency complicates process validation and increases compliance overhead for pharmaceutical packagers.
- High-Barrier Technology Costs:
The significant capital investment for advanced services like aseptic filling limits the number of providers, creating supply bottlenecks for certain products.
Strategic Opportunities
- Cold-Chain Biologics:
The rise of cell and gene therapies creates a need for specialized cryogenic packaging services that ensure product integrity and traceability.
- Bio-Based Material Expertise:
Government incentives for a circular economy create an opportunity for packagers who invest in processing capabilities for emerging bio-based and compostable films.
- Smart Packaging Integration:
Combining serialized codes or NFC tags with primary packaging offers a service to manage anti-counterfeiting for high-value pharmaceutical and cosmetic clients.
Industry Challenges
- Automation Skill Gaps:
A shortage of technicians qualified to operate and maintain advanced robotics and automated cartoning systems limits operational efficiency and throughput for many firms.
- Sterile Line Qualification:
The time and capital needed to validate new sterile filling lines to cGMP standards acts as a barrier to capacity expansion in pharmaceuticals.
- Recycled Content Traceability:
Verifying the origin and compliance of post-consumer recycled content is a significant operational challenge, complicating sustainability claims and regulatory audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Packaging Market |
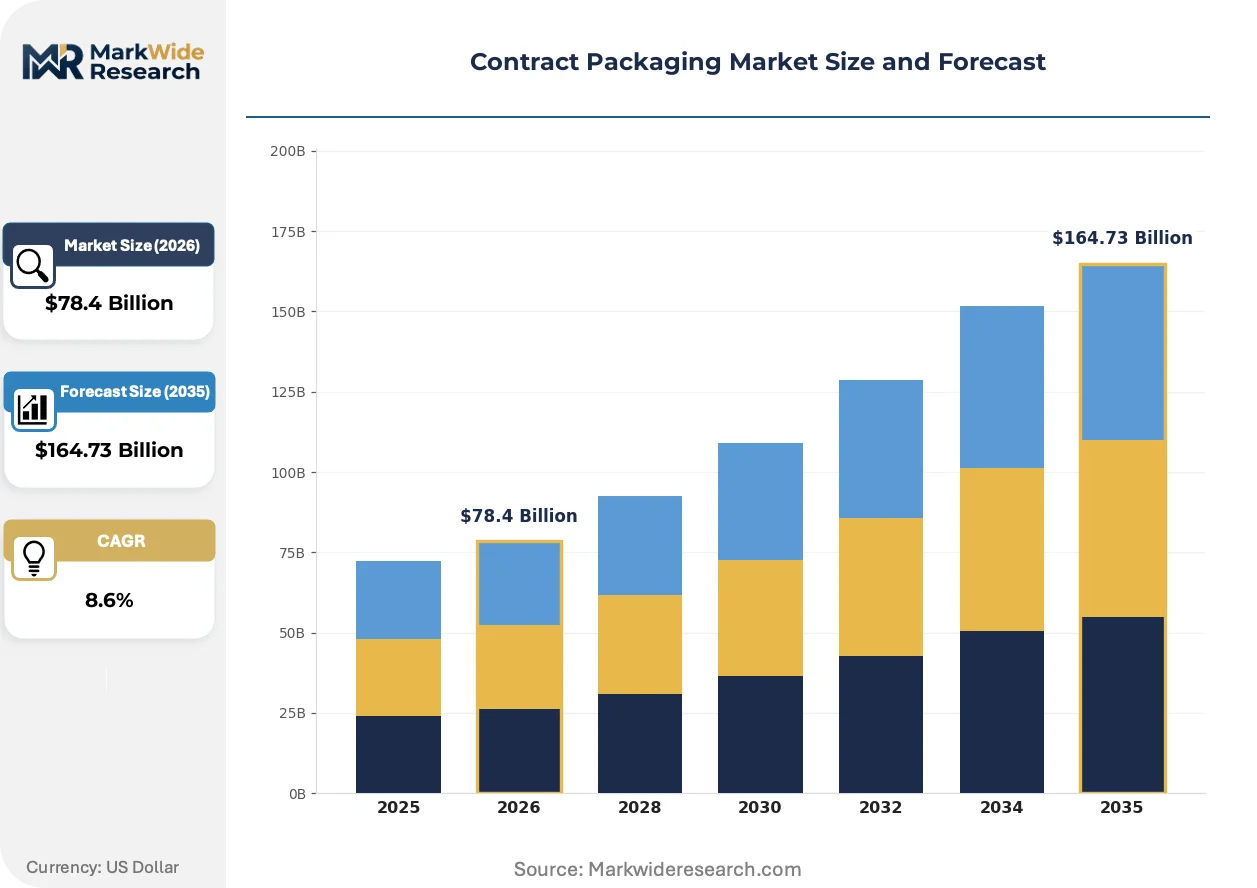
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Blister Packaging, Cartoning, Bottling, Labeling, Pouch Filling Packaging Material: Plastic, Glass, Metal, Paperboard, Flexible Film Industry Vertical: Pharmaceuticals, Personal Care, Food and Beverage, Electronics, Chemicals Distribution Channel: Direct Procurement, Distributor Networks, Online Marketplaces, Retail Chains |
| Companies Covered | Aaron Thomas Company, Unicep Packaging, Multi-Pack Solutions, Reed Lane, Sharp Corporation, Sonoco Products, Amcor, WestRock, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Packaging Market Strategic Shifts & Innovations
The market's evolution is defined by a dual-track transformation. One track involves material science for sustainability, while the other uses digital technologies to enhance efficiency, traceability, and quality assurance.
Integrated robotics and machine vision systems provide automated, high-speed quality control on packaging lines. Pharmaceutical and medical device clients are rapidly adopting these solutions for zero-defect production. This adoption is digitizing the quality assurance function, replacing manual inspection with continuous, data-logged verification.
The European Union’s Corporate Sustainability Reporting Directive (CSRD) is a pivotal policy shift. It requires large companies to disclose detailed data on their supply chain’s environmental impact, including packaging material circularity. This is forcing contract packagers serving brands in the EU to invest in transparent material traceability systems.
Brands are moving from single-provider contracts toward a multi-sourcing strategy for specialized packaging. This disaggregates the market, as clients bypass generalists to engage niche experts for services like blister packaging. The trend is most visible in the fast-moving personal care and nutraceuticals industries.
Contract Packaging Market Segmentation
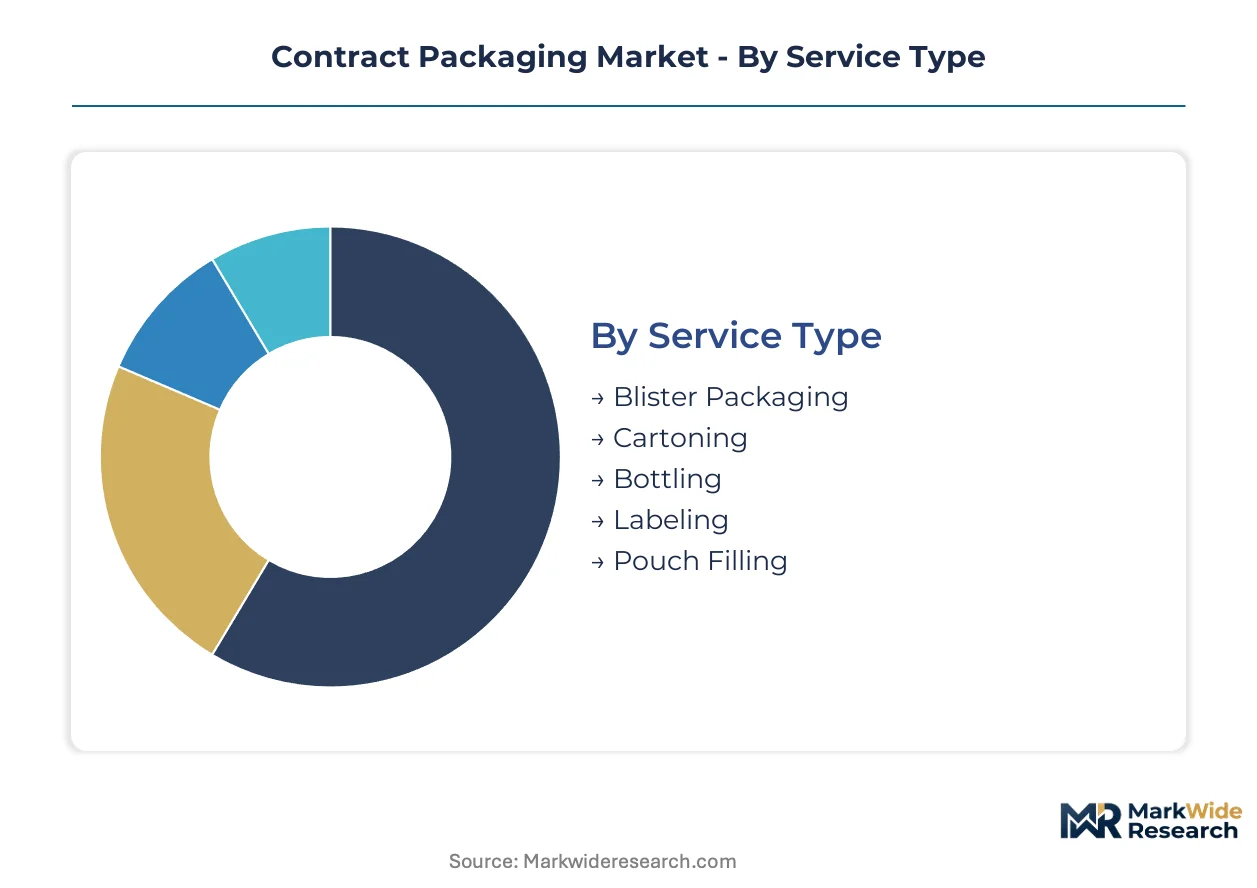
Understanding the Contract Packaging Market through segmentation reveals how specialized services and materials address diverse industry needs. This granular view highlights the unique demands of various clients, from stringent regulatory compliance to sustainable material innovation. It also clarifies where investment in new capabilities yields the greatest strategic advantage.
Service Type:
The after-sales-service intensity for contract packaging solutions directly correlates with the technical complexity and regulatory scrutiny inherent in each service type.
- Blister Packaging:This service involves enclosing products in a pre-formed plastic cavity and sealing them with a backing material, providing robust protection and tamper evidence. Demand is concentrating in the pharmaceutical and personal care industries, driven by unit-dose requirements and product visibility needs.
- Cartoning:Cartoning services automate the process of placing products into folded paperboard boxes, offering both primary and secondary packaging solutions for brand presentation.
- Bottling:Bottling involves filling liquids or gels into various container types, often requiring precise dosing and sealing for product integrity.
- Labeling:Labeling services apply product information, branding, and regulatory data to packaged goods, often integrated with automated vision systems.
- Pouch Filling:This service fills flexible pouches with liquids, gels, or granular products, offering lightweight, single-serve, and cost-effective packaging solutions. Demand is accelerating in the food and beverage sector for convenience formats and in nutraceuticals for portion control.
Pouch Filling holds the largest share; momentum sits with Blister Packaging.
Packaging Material:
Packaging materials are differentiated by their cost tier, which impacts both manufacturing expenses and the final product's market positioning.
- Plastic:Plastic materials, including PET, HDPE, and PP, offer versatility, durability, and barrier properties for a wide range of products. They remain dominant due to their low cost and adaptability, particularly for food and beverage as well as personal care applications.
- Glass:Glass packaging provides excellent barrier protection and a premium aesthetic, especially valued for high-end beverages, cosmetics, and pharmaceutical products.
- Metal:Metal packaging, primarily aluminum and steel, offers superior barrier protection against light, oxygen, and moisture for sensitive food items and aerosols.
- Paperboard:Paperboard provides a sustainable and customizable option for secondary packaging and dry goods, favored for its printability, especially in Europe due to CSRD mandates.
- Flexible Film:Flexible films, including laminates and co-extrusions, offer lightweight, adaptable, and resource-efficient packaging solutions with customizable barrier properties. Their adoption is gaining share across multiple sectors due to sustainability pressures and material innovation.
Plastic materials dominate the market, while flexible films are experiencing the steepest expansion trajectory.
Industry Vertical:
Industry verticals dictate specific packaging applications, driving demand for specialized materials and processing capabilities.
- Pharmaceuticals:This vertical demands sterile filling, tamper-evident features, and strict regulatory compliance from agencies like the US FDA and European Medicines Agency for drug safety. Specialized services like aseptic filling are critical.
- Personal Care:The personal care industry requires aesthetically pleasing, functional packaging for cosmetics, toiletries, and hygiene products.
- Food and Beverage:The food and beverage sector requires high-volume, cost-effective packaging that ensures product freshness and extends shelf life. Single-serve formats and flexible packaging are particularly in demand.
- Electronics:Electronics packaging focuses on protection from shock, static, and moisture during transit, often utilizing custom inserts and anti-static materials.
- Chemicals:The chemicals industry requires robust, leak-proof, and often hazardous-material-compliant packaging solutions for industrial and consumer chemicals.
The Food and Beverage sector commands the largest volume, with the Pharmaceutical industry exhibiting rapid expansion.
Distribution Channel:
Distribution channels are often shaped by the customer type, influencing logistics, order volumes, and fulfillment requirements.
- Direct Procurement:This channel involves direct contracts between brands and contract packagers, typically for large-volume, long-term, and highly customized packaging projects. It offers greater control and cost efficiencies for major clients.
- Distributor Networks:Distributors act as intermediaries, aggregating demand from smaller brands or handling regional distribution for larger clients.
- Online Marketplaces:These platforms facilitate connections between brands and contract packagers, often catering to smaller businesses or specialized niche packaging needs.
- Retail Chains:Contract packagers sometimes work directly with retail chains to develop private-label packaging solutions or manage in-store display-ready packaging.
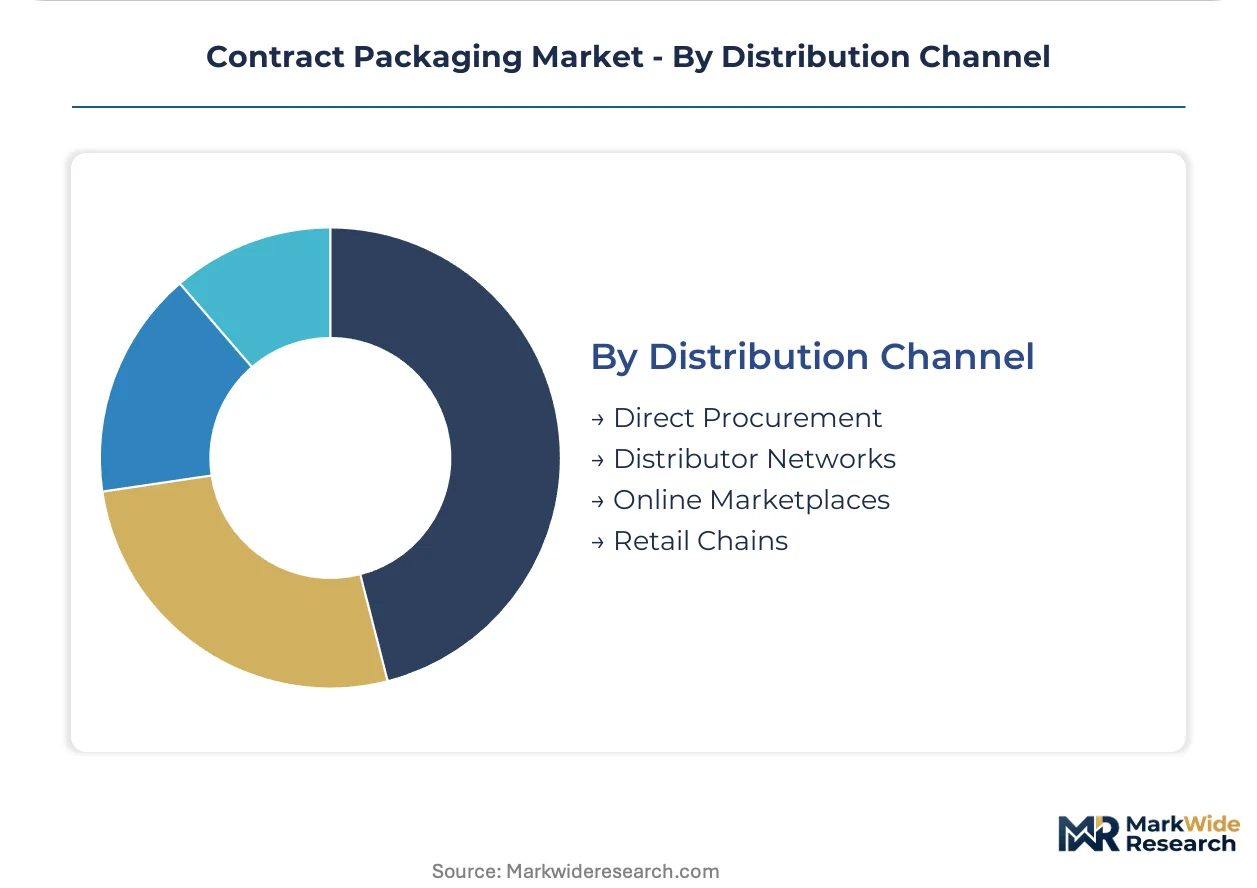
Direct Procurement represents the primary channel for large-volume contracts, as Online Marketplaces increasingly capture new business.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry between Europe and Southeast Asia shapes contract packaging engagements. European providers command higher margins due to stringent regulatory compliance and advanced technical capabilities. Conversely, Southeast Asian nations offer cost-effective production, attracting multinational brands seeking export-oriented supply chains.
United States
Demand for specialized aseptic filling services for biologics and advanced pharmaceutical packaging drives market growth. The US FDA mandates rigorous cGMP standards, requiring significant investment in sterile line qualification and process validation. Manufacturing hubs in New Jersey and California focus on high-value pharmaceutical and personal care products for domestic distribution.
Germany
European Union's CSRD compels German brands to report packaging circularity, boosting demand for certified recyclable and compostable materials. The European Medicines Agency sets stringent pharmaceutical packaging standards, favoring highly compliant contract packagers with advanced capabilities. The Rhine-Main region concentrates expertise in advanced pharmaceutical and food packaging solutions for European markets.
Vietnam
Production relocation from China drives substantial contract packaging demand for export-oriented goods in Vietnam. Government incentives support foreign investment in high-tech manufacturing, including advanced packaging facilities and material innovation. Industrial zones near Ho Chi Minh City serve as key export hubs for multinational consumer brands across Asia.
India
India's rapidly expanding pharmaceutical sector and food processing industry necessitate high-volume, cost-effective packaging solutions. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical packaging, driving demand for compliant services and material traceability. Manufacturing clusters in Gujarat and Maharashtra are expanding capabilities for both domestic consumption and export markets.
Contract Packaging Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing niche material or service expertise. The contract packaging market exhibits a tiered structure, with global players offering broad multi-material portfolios and regional specialists focusing on specific formats. Strategic archetypes include large-scale generalists, niche technology experts, and geographically focused providers. Companies pursue capacity expansion and strategic partnerships to strengthen market presence and broaden service offerings.
At the scale-driven end, Amcor exemplifies a global player leveraging vast material science capabilities to serve diverse consumer packaged goods clients across multiple continents. WestRock occupies a position among integrated providers, combining paperboard supply with advanced machinery systems for automated cartoning solutions for various industries. Unicep Packaging represents a specialist in niche formats, providing expertise in single-use liquid and gel dispensing for the personal care industry, differentiating through focused technical proficiency and compliance.
| Leading Market Players |
|---|
| Aaron Thomas Company |
| Unicep Packaging |
| Multi-Pack Solutions |
| Reed Lane |
| Sharp Corporation |
| Sonoco Products |
| Amcor |
| WestRock |
| Berry Global |
| Others |
Cost & Logistics Intelligence
The Southeast Asian shipping routes, connecting manufacturing hubs in Vietnam and Thailand to global markets, directly influence material procurement costs and downstream contract packaging price differentiation. Supply concentration in these export-oriented regions shapes both the cost base for packagers and their ability to offer competitive pricing for multinational brands.
Pricing Analysis
Industrial OEM buyers anchor long-term, contract-based pricing in the contract packaging market. Price differentiation stems from the level of regulatory compliance, such as US FDA cGMP certification for pharmaceuticals, and the volume scale of the engagement. Pricing softness reflects intense competition for large-volume contracts, particularly in commodity packaging segments. Pharmaceutical and biologics clients exhibit the lowest price sensitivity due to stringent quality and regulatory requirements, while food and beverage clients are highly sensitive to unit costs.
Supply Chain Analysis
The global contract packaging capacity concentrates in Vietnam, Thailand, and Germany, alongside specialized hubs in the United States and India. The industry relies heavily on polymer resins, paperboard, and flexible films as primary raw material inputs. Commodity price volatility in these materials presents a significant structural supply chain risk for packagers. Downstream distribution runs through direct procurement models for major brands, ensuring customized solutions and integrated logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Contract Packaging Market offers a defensive-moat story, primarily due to the high switching costs associated with validating new packaging lines and ensuring regulatory compliance for complex products.
For Market Incumbents:
Entrench market leadership by investing in advanced aseptic filling and cryogenic packaging capabilities, particularly for cold-chain biologics. Consolidate smaller, specialized packagers to gain niche expertise and expand geographic reach, addressing the fragmentation driven by asset-light business models. Mitigate margin pressure from material cost volatility through long-term supply agreements with polymer and paperboard manufacturers. Pursue ISO 9001 certification upgrades and cGMP validation for new pharmaceutical lines as a lever for higher-value contracts.
For New Entrants and Emerging Players:
Underpenetration in specialized bio-based and compostable material processing offers a significant white-space opportunity. Target nutraceuticals and personal care industries, which increasingly demand sustainable flexible packaging solutions for portion control and single-serve formats. Focus on developing expertise in smart packaging integration, including serialized codes and NFC tags, to serve high-value cosmetic and pharmaceutical clients. A go-to-market angle emphasizing rapid prototyping and regulatory-compliant material innovation can attract early adopters.
For Investors and Strategic Acquirers:
Niche technology experts specializing in aseptic filling or bio-based material processing represent attractive acquisition targets. The long-term viability of the contract packaging market is strong, driven by outsourcing trends and sustainability mandates. Watch for increasing M&A activity among mid-sized players as a signal of market consolidation and capacity rationalization. Investment in facilities compliant with EU CSRD requirements will yield sustained returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Aseptic Filling Capacity | Expands service offerings for high-value pharmaceutical and biologics products requiring sterile environments. |
| Acquire Bio-Based Material Specialists | Addresses growing demand for sustainable packaging solutions driven by EU sustainability mandates. |
| Implement Advanced Robotics & Vision Systems | Enhances operational efficiency and quality assurance for zero-defect production across packaging lines. |
| Expand into Vietnam and Thailand | Supports multinational brands seeking export-oriented production bases in cost-effective manufacturing clusters. |
| Develop Cold-Chain Biologics Packaging | Captures new demand from the rapidly expanding cell and gene therapy market requiring specialized integrity solutions. |
Research Approach
A standing panel of packaging engineers, regulatory compliance officers, brand procurement leads, and material scientists provided ongoing calibration for market sizing and trend validation. This primary input was cross-referenced with secondary data from US FDA filings, European Medicines Agency submissions, trade association reports, and company financial disclosures. Bottom-up and top-down triangulation ensured robust market volume and value estimates.
Scenario-bracketing framed the quantitative analytical framework across the projection horizon. Segmentation dimensions modeled included service type, packaging material, industry vertical, distribution channel, and regional regulatory stringency. Compound annual growth rates were derived from historical growth patterns and projected shifts in demand drivers. New product launches in pharmaceuticals and new sustainability mandates served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global players or significant regulatory shifts would shift outcomes. Quarterly review of material cost indices and new regulatory directives is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market