
 United Kingdom Packaging Market | 2026-2036
United Kingdom Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Packaging Market Analytics
Market Dynamics
England's corrugated board capacity expansion is reconfiguring domestic supply availability for fast-moving consumer goods. DS Smith PLC leverages integrated paper mill and box plant networks across the Midlands to sustain just-in-time delivery contracts with major supermarket chains. Mondi Group anchors its kraft paper position through backward integration into sustainable forestry certification schemes. Smurfit WestRock competes on scale with automated converting lines that reduce lead times for e-commerce shippers.
Product and Segment Analysis
Packaging encompasses engineered enclosures, wraps, and containers manufactured from paperboard, plastic films, metal foils, or glass to protect, preserve, and present goods throughout distribution and retail display. Paperboard grades range from 150 gsm folding boxboard to triple-wall corrugated exceeding 1,000 gsm burst strength for heavy-duty transit applications. Flexible packaging leads volume in food end-use segments where barrier films extend shelf life for chilled ready meals. Rigid containers capture premium positioning in cosmetics and spirits where glass bottles and injection-molded jars signal quality differentiation. Pharmaceutical blister formats favor cold-form aluminum laminates that satisfy child-resistance and moisture-vapor transmission specifications.
Regulatory Environment
The UK Environment Agency enforces Plastic Packaging Tax thresholds at 30% recycled content, while DEFRA's Extended Producer Responsibility framework shifts waste management costs upstream to brand owners and importers. British Standards Institution specifications for compostable packaging and the Food Standards Agency's migration limits for food-contact materials constrain material selection and testing protocols. Stakeholders must monitor anticipated revisions to packaging waste recovery notes and carbon reporting rules under the UK Emissions Trading Scheme alignment.
Market Dynamics
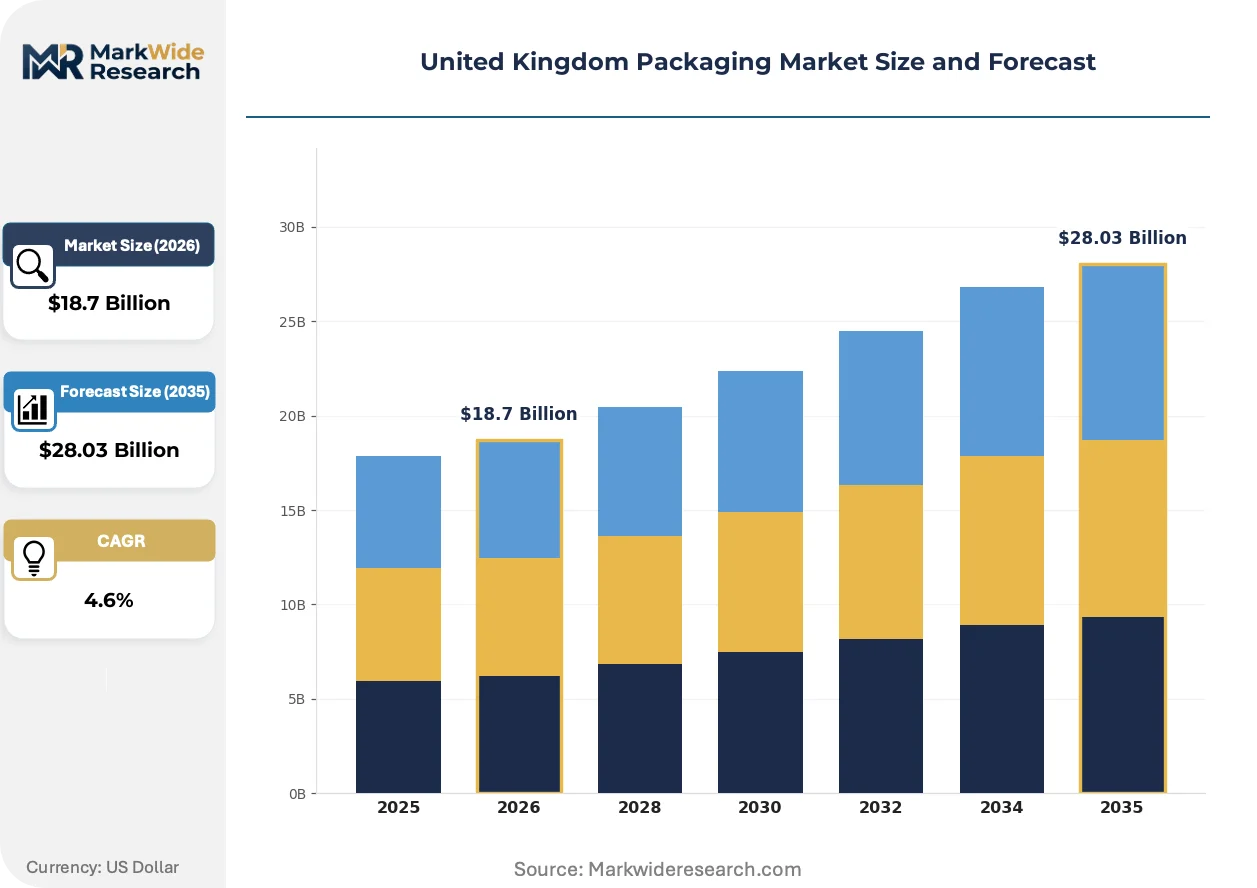
The UK Packaging Market is restructuring around material substitution mandates that force converters to abandon virgin plastic formats ahead of regulatory deadlines. DEFRA's Extended Producer Responsibility framework and the Plastic Packaging Tax are compressing decision timelines for FMCG brand owners.
Growth Catalysts
- Plastic Packaging Tax thresholds:The 30% recycled content mandate accelerates fiber-based protective format adoption across online grocery fulfillment networks.
- Midlands converting cluster proximity:Corrugated capacity concentration near FMCG distribution hubs enables just-in-time delivery contracts with major supermarket chains.
- Extended Producer Responsibility cost shifts:Upstream waste management liability transfers from municipalities to brand owners and importers, incentivizing lightweighting and circular design.
Market Restraints
- Pulp and recovered paper cost volatility:Energy-intensive kraft paper production exposes converters to natural gas price swings and OCC supply fluctuations.
- Domestic glass container supply concentration:Heavyweight transit economics limit viable sourcing to a narrow geographic radius around furnace operations in Yorkshire and the North West.
- Barrier performance limitations:Fiber-based formats struggle to match extended shelf life specifications for chilled ready meals without polyethylene lamination layers.
Strategic Opportunities
- Scottish spirits export packaging:Premium glass and decorative carton demand from whisky distilleries offers high-margin positioning insulated from commodity corrugated cycles.
- Compostable packaging certification alignment:British Standards Institution specifications for industrial composting create first-mover advantage for converters achieving EN 13432 compliance.
- Automation convergence with digital print:Integrated converting lines with variable-data inkjet enable short-run customization for craft food brands bypassing traditional plate costs.
Industry Challenges
- Migration testing specialist scarcity:Food Standards Agency compliance for food-contact materials requires analytical chemists with specific GC-MS expertise that outpaces graduate pipeline output.
- Legacy ERP integration with carbon reporting:UK Emissions Trading Scheme alignment demands real-time Scope 3 data capture that existing MRP systems cannot automate without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Glass Bottles, Paperboard Material: Plastic, Metal, Glass, Wood End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Service Type: Design, Manufacturing, Consulting, Distribution |
| Companies Covered | Amcor PLC, Sonoco Products Company, DS Smith PLC, Westrock Company, International Paper Company, Mondi Group, Ball Corporation, Greif Inc., Smurfit WestRock, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Packaging Market Evolving Landscape
Material science breakthroughs and regulatory enforcement timelines are compressing format transition windows. Converters must now validate alternative substrates at pilot scale before policy mandates take full effect.
Mono-material polyethylene films with enhanced barrier properties are rendering obsolete multi-layer laminates that complicate mechanical recycling streams. Major chilled ready meal manufacturers are fast-tracking qualification programs to meet supermarket sustainability scorecards. This substrate transition is compressing technical service timelines as film suppliers race to match oxygen transmission rates previously achieved through nylon or EVOH layers.
DEFRA's packaging waste recovery note reforms are tightening audit trails for reprocessing evidence. Brand owners now face downstream liability if exporter claims prove fraudulent. The food and beverage segment is responding by shortening supplier approval lists to vertically integrated paper mills with certified chain-of-custody documentation.
Consolidated buying desks at major supermarket chains are unbundling historical supplier relationships. Category managers now rotate format sourcing across regional converters based on carbon intensity scores rather than incumbent status. This procurement recalibration is most visible in the Midlands manufacturing corridor where e-commerce shippers benchmark total landed cost including packaging waste compliance fees.
United Kingdom Packaging Market Segmentation
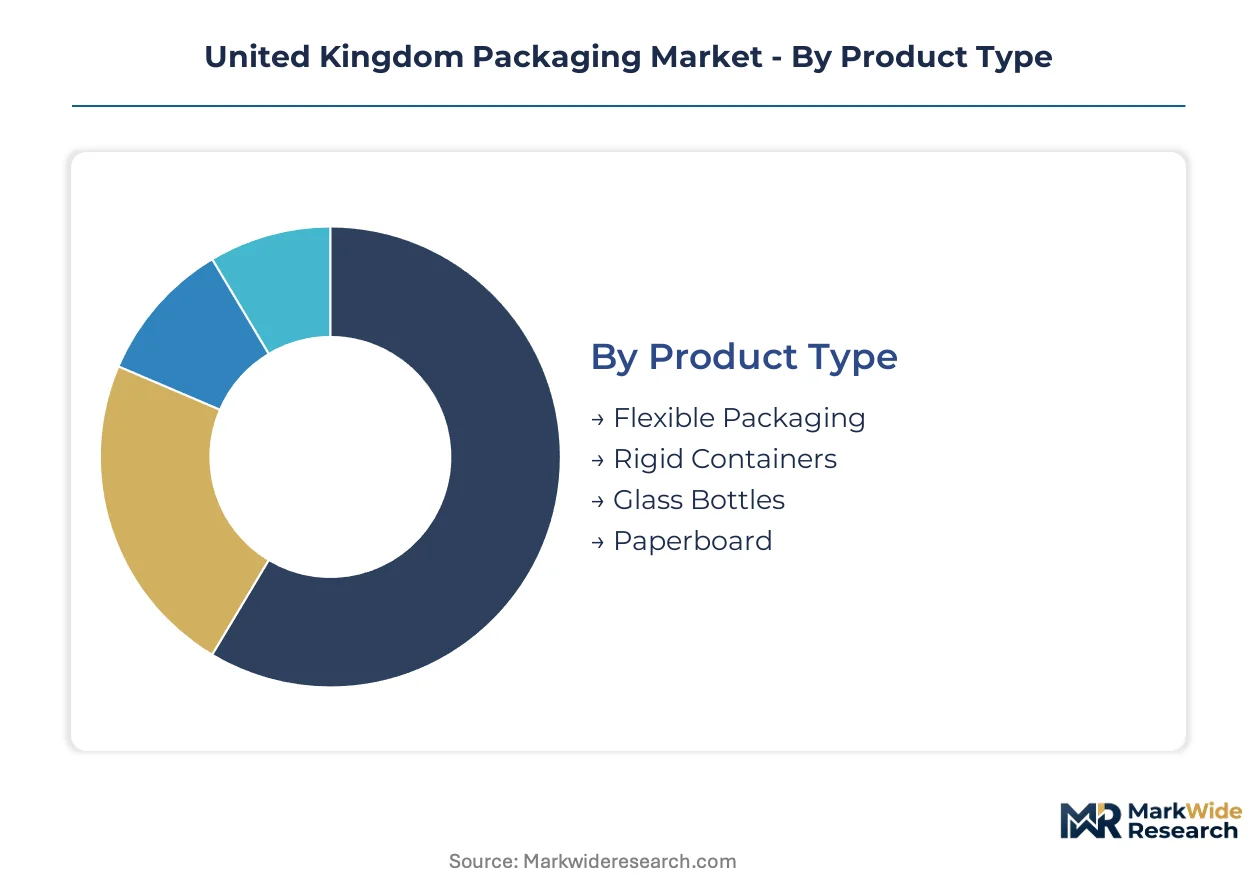
Packaging converters in the United Kingdom must align format selection with DEFRA's Extended Producer Responsibility cost allocations and the Plastic Packaging Tax's recycled content thresholds. Segment-specific compliance burdens vary sharply across material categories and end-use applications.
Product Type:
Mature formats dominate volume while emerging substrates capture regulatory tailwinds.
- Flexible Packaging:Barrier films and pouches manufactured from mono-material polyethylene or laminated structures extend shelf life for chilled ready meals. Demand concentrates in supermarket private-label supply chains where lightweighting reduces Extended Producer Responsibility fees.
- Rigid Containers:Injection-molded jars, thermoformed trays, and blow-molded bottles serve dairy, spreads, and household chemicals. The Midlands converting cluster supplies just-in-time volumes to FMCG distribution hubs near Birmingham and Leicester.
- Glass Bottles:Furnace-produced containers for spirits and pharmaceuticals offer infinite recyclability but carry heavyweight transit penalties.
- Paperboard:Folding cartons and corrugated cases from 150 gsm to triple-wall grades protect goods through e-commerce fulfillment networks.
Paperboard retains volume leadership; flexible packaging holds the steepest expansion curve.
Material:
Cost tier positioning separates premium certified grades from commodity substitutes.
- Plastic:Virgin and recycled polyethylene, polypropylene, and PET films face the 30% recycled content mandate under UK Plastic Packaging Tax enforcement. Major film extruders are qualifying post-consumer recycled feedstocks ahead of audit deadlines.
- Metal:Aluminum laminates for pharmaceutical blisters and steel aerosol cans deliver barrier performance and mechanical strength. Cold-form foil formats satisfy child-resistance specifications for the National Health Service supply chain.
- Glass:Soda-lime silica containers from Yorkshire and North West furnace operations serve whisky export markets with decorative finishing and premium positioning.
- Wood:Pallets, crates, and dunnage support heavy machinery and construction material transit, with heat-treated certification meeting ISPM 15 phytosanitary requirements for cross-border shipping.
Plastic commands absolute volume; metal laminates are climbing fastest on pharmaceutical compliance demand.
End User:
Application-specific performance standards dictate material selection and testing protocols.
- Food & Beverage:Chilled ready meals, fresh produce, and spirits packaging must satisfy Food Standards Agency migration limits and shelf-life specifications. Supermarket sustainability scorecards now penalize multi-layer laminates that complicate mechanical recycling.
- Pharmaceuticals:Blister packs, vials, and compliance packaging require child-resistance certification and moisture-vapor transmission rate validation. The Medicines and Healthcare products Regulatory Agency enforces serialization for traceability.
- Cosmetics:Premium glass bottles and decorative folding cartons signal quality differentiation in fragrance and skincare segments.
- Electronics:Anti-static films and molded pulp cushions protect high-value components through distribution, with WEEE directive alignment for end-of-life recovery.
Food & Beverage retains volume leadership; Pharmaceuticals holds the steepest expansion curve on serialization and barrier requirements.
Service Type:
Customer type separates integrated converters from specialized service providers.
- Design:Structural and graphic design services optimize pack performance for shelf impact, supply chain efficiency, and circularity compliance. Design consultancies in London and Manchester serve brand owners lacking in-house packaging engineering.
- Manufacturing:Integrated paper mills, extrusion lines, and converting equipment produce finished packaging at scale. Automated corrugators in the Midlands reduce lead times for e-commerce shippers.
- Consulting:Regulatory compliance advisory, life-cycle assessment, and carbon accounting support brand owners navigating Extended Producer Responsibility obligations and UK Emissions Trading Scheme alignment.
- Distribution:Warehousing, inventory management, and vendor-managed inventory services position packaging stock near FMCG production facilities for just-in-time delivery.
Manufacturing retains volume leadership; Consulting is climbing fastest on regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DEFRA's Extended Producer Responsibility framework anchors England's regulatory environment, with sub-regional manufacturing corridors diverging in material specialization and compliance cost exposure.
Midlands
Corrugated converting capacity clusters near Birmingham and Leicester to serve FMCG distribution hubs with just-in-time delivery contracts. The Plastic Packaging Tax's 30% recycled content mandate accelerates fiber-based protective format adoption across e-commerce fulfillment networks. Automated corrugator investments at Smurfit WestRock and DS Smith PLC facilities reduce lead times for supermarket chains.
North West England
Glass furnace operations in Yorkshire and Lancashire supply spirits export packaging for whisky distilleries with premium positioning insulated from commodity cycles. Heavyweight transit economics constrain viable sourcing radii around furnace locations. The UK Environment Agency enforces packaging waste recovery note reforms that tighten audit trails for reprocessing evidence.
London and Southeast
Design consultancies and brand owner headquarters concentrate in London and Manchester, driving structural and graphic packaging innovation for cosmetics and premium food segments. British Standards Institution specifications for compostable packaging create first-mover advantage for converters achieving EN 13432 compliance. Carbon reporting rules under UK Emissions Trading Scheme alignment demand real-time Scope 3 data capture from supply chains.
Scotland
Whisky distillery packaging demand centers on decorative cartons and premium glass bottles for export markets. Scottish Enterprise programs support circular design investments in fiber-based formats. Aberdeen and Edinburgh host regulatory compliance advisory services for pharmaceutical serialization under Medicines and Healthcare products Regulatory Agency enforcement.
Wales
Manufacturing corridors near Cardiff and Newport supply rigid containers and flexible films for chilled ready meals. Food Standards Agency migration limits for food-contact materials constrain material selection and testing protocols. Welsh Government industrial strategy funds automation convergence with digital print for short-run craft food brand customization.
United Kingdom Packaging Market Competitive Landscape
Integrated paper mill operators and specialized converters split the market between scale-driven corrugated supply and niche barrier film qualification. Tier-one players command supermarket private-label contracts through backward integration into recovered fiber networks. Mid-cap specialists occupy pharmaceutical and spirits segments where compliance documentation and decorative finishing command price premiums. Competitive dynamics center on M&A consolidation of regional converting assets and vertical integration into sustainable forestry certification schemes.
Among UK-headquartered integrated operators, DS Smith PLC and Mondi Group exemplify the mill-to-box-plant model that secures just-in-time FMCG contracts. Smurfit WestRock represents the transnational scale archetype with automated converting lines serving e-commerce shippers. Amcor PLC anchors the flexible packaging specialist tier with barrier film expertise for food shelf-life extension.
| Leading Market Players |
|---|
| Amcor PLC |
| Sonoco Products Company |
| DS Smith PLC |
| Westrock Company |
| International Paper Company |
| Mondi Group |
| Ball Corporation |
| Greif Inc. |
| Smurfit WestRock |
| Others |
Value Network & Pricing Analysis
Corrugated overcapacity in the Midlands manufacturing corridor compresses converter margins while concentrating pricing power among integrated paper mill operators with captive fiber supply. Utilization rates below 80% at independent box plants force spot-market discounting, whereas DS Smith PLC and Mondi Group leverage backward integration into recovered fiber networks to defend contract pricing with major supermarket chains.
Pricing Analysis
Geographic price spreads between Yorkshire glass furnace operations and Midlands corrugated converters exceed 15% on equivalent volumetric shipments due to heavyweight transit penalties. Three-tier pricing structure across premium certified-sustainable grades, standard FSC-labeled formats, and economy non-certified substitutes separates supermarket private-label contracts from spirits export packaging. Cost compression in commodity corrugated is intensifying because recovered paper supply volatility feeds through to OCC bale pricing. Discounters and online grocery fulfillment networks exhibit highest price sensitivity, while whisky distilleries accept premiums for decorative carton and premium glass bottle combinations.
Supply Chain Analysis
UK Environment Agency packaging waste recovery note reforms function as export-control regime analogues, tightening audit trails for reprocessing evidence and limiting fraudulent exporter claims. Geographic supply concentration centers on domestic paper mill networks in England, Scottish forestry certification schemes, and Nordic kraft pulp imports for barrier-grade papers. Raw material dependencies encompass recovered old corrugated containers, virgin softwood pulp, and aluminum cold-form foils for pharmaceutical applications. Single-source vulnerability concentrates around natural gas supply for energy-intensive kraft paper production. Distribution runs through just-in-time vendor-managed inventory systems positioning finished packaging stock adjacent to FMCG production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemists with GC-MS migration testing expertise represent the critical capability gap constraining food-contact material qualification timelines, with graduate pipeline output lagging regulatory enforcement deadlines by 18-24 months.
For Market Incumbents: Insulate margin position by deepening captive supply of certified sustainable fiber through forestry certification scheme investments, and accelerate automation convergence with digital print to capture short-run craft food brand volumes before regional competitors replicate capability. The Plastic Packaging Tax's recycled content mandate threatens virgin plastic film specialists lacking post-consumer recycled feedstock qualification. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical blister packaging compliance advisory, where Medicines and Healthcare products Regulatory Agency serialization requirements and child-resistance certification create specialist scarcity premiums. Scottish spirits export packaging offers insulated demand with decorative finishing requirements that commodity corrugated converters cannot easily replicate. Lead with regulatory compliance consulting bundled with design services to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regulatory compliance advisory services tied to Extended Producer Responsibility obligations, where annual retainer structures replace project-based consulting. Long-term viability over the next decade favors vertically integrated paper mill operators with certified chain-of-custody documentation and automated converting lines serving e-commerce fulfillment networks. The signal to watch is supermarket chain procurement desk consolidation rotating format sourcing based on carbon intensity scores rather than incumbent supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Forestry Certification | DS Smith PLC and Mondi Group secure FSC chain-of-custody documentation required by supermarket sustainability scorecards. |
| Automation Convergence with Digital Print | Integrated converting lines with variable-data inkjet enable short-run customization for craft food brands bypassing traditional plate costs. |
| Pharmaceutical Compliance Advisory Services | Regulatory expertise in Medicines and Healthcare products Regulatory Agency serialization creates recurring-revenue advisory models. |
| Post-Consumer Recycled Feedstock Qualification | Film extruders qualifying 30% recycled content ahead of UK Plastic Packaging Tax audit deadlines defend contract renewals. |
| Vendor-Managed Inventory Positioning | Warehousing packaging stock adjacent to FMCG production facilities captures just-in-time delivery premiums from supermarket chains. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with packaging converters, brand owner sustainability directors, supermarket category buyers, and regulatory compliance consultants; and secondary validation through DEFRA policy documentation, UK Environment Agency enforcement notices, British Standards Institution certification registries, and Food Standards Agency migration limit specifications. Bottom-up triangulation across material-grade volume estimates and top-down cross-check against FMCG sector packaging spend allocations anchored forecast ranges.
Forecast inputs encompassed segment-specific growth trajectories across flexible packaging, rigid containers, glass bottles, and paperboard formats, with end-use splits for food and beverage, pharmaceuticals, cosmetics, and electronics applications. CAGRs were derived from regression analysis of historical capacity utilization, regulatory enforcement timeline impacts, and substitution elasticity between plastic and fiber-based formats. Modeled variables included Plastic Packaging Tax compliance cost pass-through rates and Extended Producer Responsibility fee structures by material category.
Sensitivities concentrate around pulp and recovered paper cost volatility, natural gas price swings affecting kraft paper production economics, and potential delays to packaging waste recovery note reforms. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution technology maturation timelines. Material shifts in barrier performance specifications for chilled ready meals or acceleration of UK Emissions Trading Scheme alignment deadlines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market