
 Sterilized Packaging Market | 2026-2036
Sterilized Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilized Packaging Market Outlook
The EU Green Deal is broadening sustainability mandates across European healthcare supply chains, forcing sterilized packaging converters to eliminate halogenated additives and reduce carbon footprints in sterile barrier production. Amcor plc leverages its integrated film manufacturing network to supply hospitals and pharmaceutical firms with recyclable sterilizable laminates. Berry Global anchors North American demand through its healthcare specialty films division, which sustains multi-site sterile packaging contracts with major medical device OEMs.
Sterilized packaging comprises engineered barrier systems designed to maintain microbial exclusion through validated sterilization cycles, typically employing ethylene oxide, gamma irradiation, or steam sterilization at specified temperature-pressure parameters, with seal integrity measured against ISO 11607 burst and peel strength thresholds. Flexible packaging dominates volume in pharmaceutical sachets and IV overwrap applications where lightweighting reduces distribution costs, while rigid containers capture premium margins in surgical kit trays requiring dimensional stability through autoclaving. Glass vials and metal sterilization containers retain niche positions in high-value biologics and reusable surgical systems respectively, though plastic continues displacing traditional materials in single-use sterile barriers.
FDA enforces sterile barrier validation through 21 CFR Part 820 quality system regulations, while ISO 11607 and EU MDR CE marking requirements shape design control and post-market surveillance obligations for manufacturers selling into US and European markets. BSI certification provides third-party conformity assessment pathways for UK market access following Brexit divergence from EU notified body frameworks. Stakeholders must monitor evolving extended producer responsibility legislation in Germany and France, where sterilized packaging waste streams face new recycling quota obligations that will reshape material selection and supplier qualification criteria.
Market Dynamics
Pharmaceutical contract manufacturers are consolidating sterile fill-finish capacity around automated isolator technology, compressing validation timelines and reshaping supplier qualification criteria across North American and European supply chains.
Growth Catalysts
- EU MDR validation mandates:Tighter sterile barrier system requirements under the Medical Device Regulation are forcing device OEMs to upgrade packaging specifications, expanding demand for ISO 11607-compliant materials.
- Biologics fill-finish expansion:Contract manufacturers in Germany's Tuttlingen corridor and North Carolina's Research Triangle are adding isolator lines that require specialized sterile barrier films and rigid containers.
- Gamma irradiation infrastructure:New sterilization facilities in Belgium and Illinois are extending serviceable radius for radiation-sterilized packaging, reducing logistics costs for pharmaceutical distributors.
Market Restraints
- Ethylene oxide supply concentration:Sterilization capacity for EO-sensitive materials clusters around a handful of US Gulf Coast facilities, creating bottleneck risk for medical device supply chains.
- Halogenated additive phase-outs:EU Green Deal restrictions on chlorinated and brominated flame retardants are eliminating proven stabilizer chemistries from sterile barrier formulations without drop-in replacements.
- Glass-to-plastic substitution limits:High-value biologics requiring inert contact surfaces resist polymer migration, preserving glass vial demand that constrains flexible packaging penetration in parenteral segments.
Strategic Opportunities
- Recyclable sterilizable laminates:Amcor's integrated film manufacturing network enables hospitals and pharmaceutical firms to meet extended producer responsibility quotas in Germany and France without performance degradation.
- Steam sterilization compatibility:Rigid container manufacturers can capture surgical kit tray demand by engineering dimensional stability through autoclaving cycles that flexible barriers cannot withstand.
- Post-Brexit UK certification pathways:BSI conformity assessment provides alternative market access routes for sterile barrier suppliers seeking to bypass EU notified body backlogs.
Industry Challenges
- ISO 11607 validation expertise scarcity:Burst and peel strength testing protocols require specialized technicians that contract packaging organizations struggle to recruit against pharmaceutical manufacturing wage premiums.
- Multi-site sterile packaging contract complexity:Medical device OEMs demand synchronized qualification across Berry Global's healthcare specialty films division locations, extending audit timelines and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilized Packaging Market |
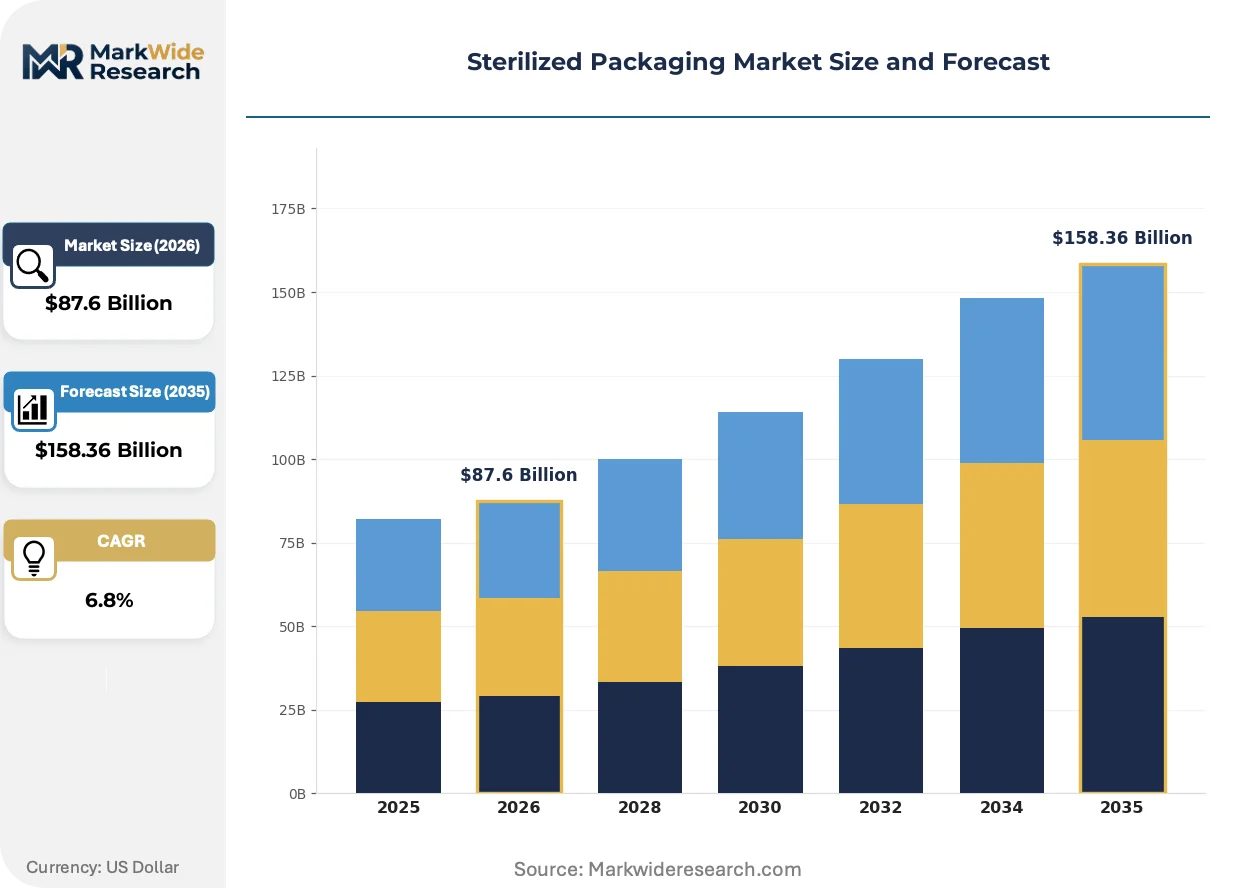
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Pouches, Trays Material: Plastic, Paper, Metal, Glass End User: Healthcare, Pharmaceuticals, Food & Beverages, Laboratory Certification: ISO, FDA, CE Mark, BSI |
| Companies Covered | Amcor plc, Berry Global, DuPont de Nemours, West Pharmaceutical Services, 3M Company, Sonoco Products Company, Gerresheimer AG, Sealed Air Corporation, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilized Packaging Market Strategic Shifts
Sterile packaging technology is bifurcating between lightweight flexible systems for pharmaceutical distribution and dimensionally stable rigid formats for surgical applications, with material science and regulatory pressure as the twin engines of change.
Polyethylene-based sterilizable laminates are overtaking legacy PVC and PVDC structures in IV overwrap and sachet applications. Hospital procurement groups in the Netherlands and Denmark are specifying these materials to meet recycling quota obligations. This shift is overtaking established supply relationships as converters retool extrusion lines to eliminate halogenated chemistries.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer coatings from sterile barrier films. European converters are migrating to silicone-based alternatives for release liner applications. High-value biologics packaging in Switzerland and Germany faces the steepest reformulation timelines as Swissmedic and national regulators align inspection protocols.
Consolidated buying by pharmaceutical contract manufacturers is compressing supplier qualification cycles. Tier-one fill-finish operators in Massachusetts and Bavaria are mandating dual-source sterile barrier agreements that disqualify single-film converters. This concentration is most visible in parenteral packaging, where multi-year sole-source contracts are giving way to annual competitive tenders with technical scorecards.
Sterilized Packaging Market Segmentation
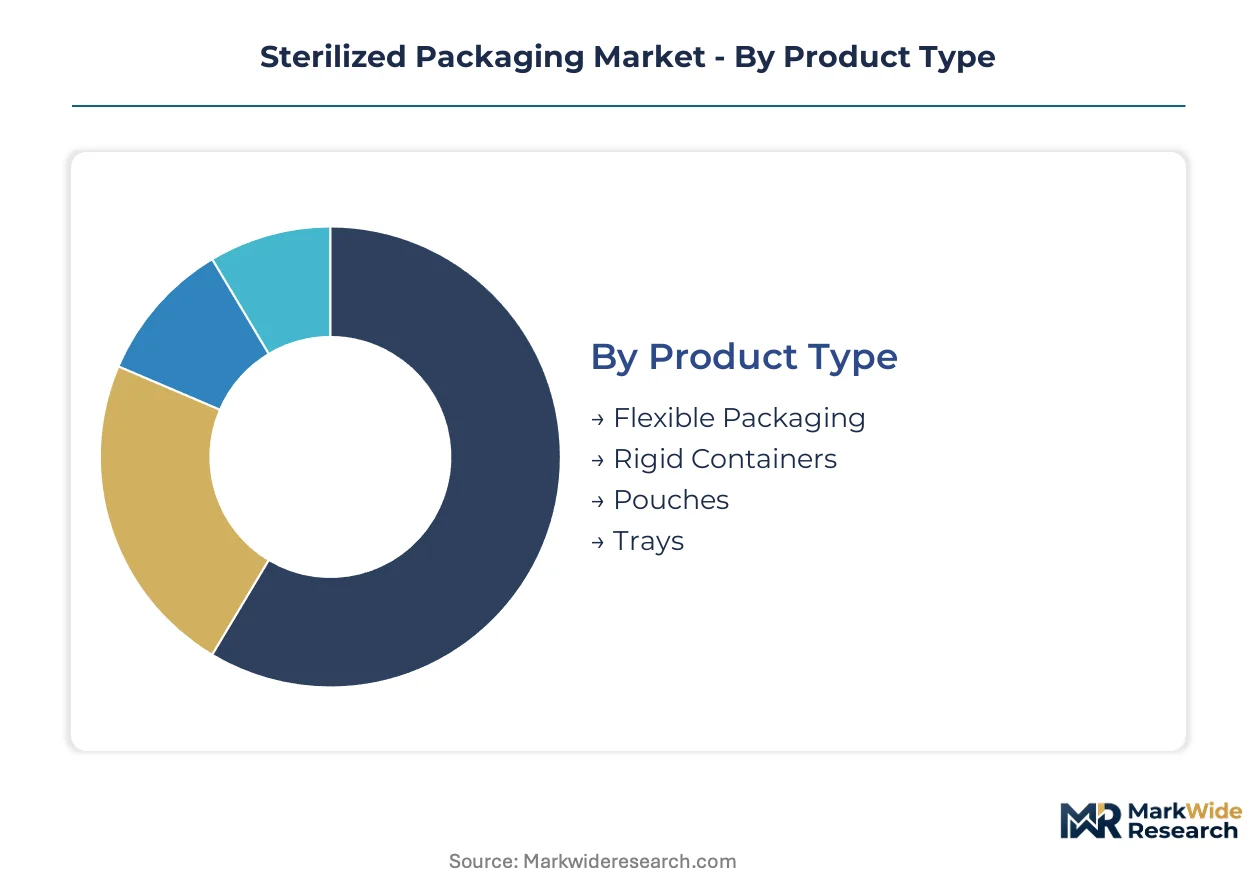
Sterilized packaging purchasing decisions hinge on sterilization method compatibility, barrier performance requirements, and regulatory pathway alignment. Each segment category reflects distinct technical trade-offs between cost, validation burden, and end-use performance specifications.
Product Type:
Cost tier determines buyer selection between disposable flexible systems and capital-intensive rigid formats.
- Flexible Packaging:Polyethylene-based laminates and films dominate IV overwrap and pharmaceutical sachet applications where lightweighting reduces distribution spend. Hospital procurement groups in the Netherlands and Denmark specify these materials to meet recycling quota obligations under extended producer responsibility frameworks.
- Rigid Containers:Injection-molded polymer or metal sterilization containers deliver dimensional stability through steam autoclaving cycles that flexible barriers cannot withstand. Surgical kit tray demand concentrates in Germany's Tuttlingen medical technology corridor, where OEMs require multi-cavity formats for instrument organization.
- Pouches:Tyvek-film or paper-plastic combinations serve low-cost disposable applications with moderate barrier requirements.
- Trays:Thermoformed PETG or HDPE formats balance visibility with sterilization compatibility for device presentation.
Flexible packaging leads on scale; rigid containers lead on momentum as surgical procedure volumes recover and kit standardization advances.
Material:
Application temperature and chemical resistance requirements dictate material selection across sterilization modalities.
- Plastic:Polypropylene, polyethylene, and polycarbonate formulations displace legacy materials in single-use barriers, though REACH restrictions on halogenated additives are forcing reformulation of stabilizer chemistries without drop-in replacements.
- Glass:Borosilicate vials retain necessity in high-value biologics where polymer migration risks compromise drug stability, constraining flexible packaging penetration in parenteral segments despite cost disadvantages.
- Paper:Medical-grade kraft and synthetic papers provide breathable sterilization barriers for ethylene oxide and steam cycles.
- Metal:Anodized aluminum sterilization containers sustain reusable surgical systems with multi-decade service life.
Plastic dominates volume throughput; glass commands premium positioning in biologics containment.
End User:
Regulatory scrutiny intensity and validation timeline pressure vary sharply across customer categories.
- Healthcare:Hospital central sterile supply departments drive demand for steam-compatible rigid containers and peel pouches, with procurement consolidating around GPO contracts that privilege suppliers with multi-site qualification capabilities.
- Pharmaceuticals:Contract fill-finish operators in Massachusetts and Bavaria mandate dual-source sterile barrier agreements, disqualifying single-film converters and compressing supplier qualification cycles to annual competitive tenders.
- Food & Beverages:Aseptic packaging for shelf-stable products employs overlapping barrier technologies with lower validation burdens than medical applications.
- Laboratory:Research and diagnostic applications require sterile barriers with rapid turnaround and lower lot minimums.
Healthcare anchors installed base; pharmaceuticals is expanding most quickly as biologics manufacturing capacity scales.
Certification:
Geographic market access requirements determine certification investment priority for barrier suppliers.
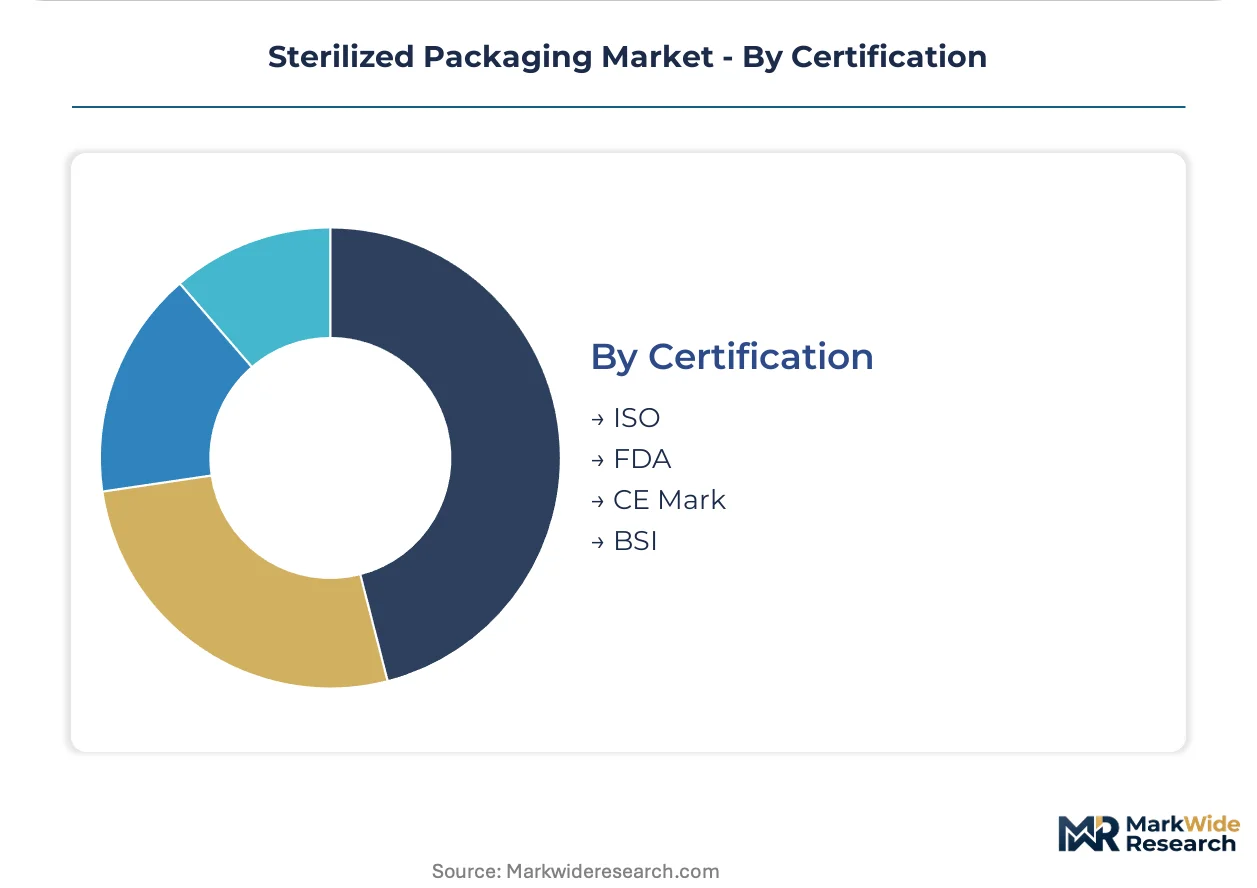
- ISO:ISO 11607 compliance provides baseline sterile barrier system validation recognized across jurisdictions, with burst and peel strength testing protocols requiring specialized technicians that contract packaging organizations struggle to recruit.
- FDA:21 CFR Part 820 quality system regulations enforce design control and post-market surveillance obligations for US market entry, with warning letter trends elevating documentation expectations.
- CE Mark:EU MDR tightened sterile barrier system requirements, forcing device OEMs to upgrade packaging specifications and expanding demand for validated materials.
- BSI:UKCA conformity assessment provides alternative market access following Brexit divergence from EU notified body frameworks.
ISO certification underpins cross-border trade; CE Mark carries the steepest compliance escalation trajectory under MDR implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sterile barrier validation technicians concentrate in Germany's Tuttlingen corridor, North Carolina's Research Triangle, and Switzerland's Basel-Land canton, anchoring regional capability clusters that pharmaceutical contract manufacturers tap for ISO 11607 expertise.
United States
Pharmaceutical contract manufacturers in Massachusetts and North Carolina are adding automated isolator lines that compress supplier qualification timelines. FDA enforces sterile barrier validation through 21 CFR Part 820 quality system regulations with escalating documentation expectations. The Research Triangle hosts multi-site sterile packaging contracts with major medical device OEMs demanding synchronized qualification across locations.
Germany
Medical device OEMs in the Tuttlingen medical technology corridor require multi-cavity rigid container formats for surgical kit organization. EU MDR tightened sterile barrier system requirements, forcing packaging specification upgrades and expanding demand for validated materials. Bavarian fill-finish operators mandate dual-source sterile barrier agreements that disqualify single-film converters.
Switzerland
High-value biologics packaging faces steep reformulation timelines as Swissmedic aligns inspection protocols with REACH restrictions on per- and polyfluoroalkyl substances. The country's national pharmaceutical regulator enforces migration limits that preserve glass vial demand in parenteral segments. Basel-Land canton anchors sterile fill-finish capacity serving European biologics manufacturers.
Belgium
New gamma irradiation facilities are extending serviceable radius for radiation-sterilized packaging, reducing logistics costs for pharmaceutical distributors. ECHA REACH restrictions on halogenated additives are eliminating proven stabilizer chemistries without drop-in replacements. Antwerp-Brussels corridor concentration of sterilization infrastructure supports just-in-time delivery models for Benelux hospital networks.
Netherlands
Hospital procurement groups specify polyethylene-based sterilizable laminates to meet recycling quota obligations under extended producer responsibility frameworks. The EU Green Deal broadens sustainability mandates across healthcare supply chains, forcing converters to eliminate halogenated additives. Eindhoven-Rotterdam logistics hub enables rapid turnaround for sterile barrier shipments to German and UK markets.
Sterilized Packaging Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the sterilized packaging landscape. Integrated film manufacturers with captive extrusion capacity face off against specialized converters sourcing substrate from merchant markets. Three archetypes dominate: diversified packaging conglomerates with healthcare divisions, pure-play medical device packaging specialists, and materials science firms supplying substrate to downstream converters. Consolidation pressure manifests through multi-site contract awards and backward integration into resin compounding.
Among diversified packaging conglomerates, Amcor plc and Berry Global exemplify scale-driven positions anchored by integrated manufacturing networks. Amcor plc represents the vertically integrated archetype with film manufacturing capabilities supplying hospitals and pharmaceutical firms. Berry Global occupies a position within healthcare specialty films, sustaining multi-site sterile packaging contracts through distributed production assets. DuPont de Nemours sits within the materials science tier, supplying substrate technologies to downstream converters rather than finished sterile barriers.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| DuPont de Nemours |
| West Pharmaceutical Services |
| 3M Company |
| Sonoco Products Company |
| Gerresheimer AG |
| Sealed Air Corporation |
| AptarGroup |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal sustainability mandates gate qualified supply and premium-tier pricing access, as converters eliminating halogenated additives face reformulation costs that pass through to validated sterile barrier systems while disqualifying uncertified competitors from hospital procurement contracts.
Pricing Analysis
Bundled validation services versus unbundled material-only supply splits pricing structures across the sterile packaging landscape. Three-tier pricing stratifies across ISO 11607-certified premium grades, standard FDA-compliant tiers, and economy pouches for non-critical applications. Cost compression in flexible film laminates intensifies as polyethylene converters in the Netherlands and Denmark compete for recycling-mandated hospital contracts. Pharmaceutical contract manufacturers show lowest price sensitivity due to validation timeline penalties, while laboratory research buyers prioritize cost minimization over certification depth.
Supply Chain Analysis
Single-source vulnerability sits with ethylene oxide sterilization capacity concentrated on the US Gulf Coast, where a handful of facilities service radiation-sensitive medical device packaging. Raw material flows draw from German resin compounding for medical-grade polypropylene, Belgian fluoropolymer coating alternatives, and Chinese substrate for standard polyethylene films. Tariff exposure on imported sterilization equipment amplifies cost uncertainty for North American converters. Distribution runs through pharmaceutical distributors in the Antwerp-Brussels corridor and GPO-contracted hospital networks in the Research Triangle.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterilized packaging market functions as a regulatory compounder, where EU MDR implementation and REACH additive restrictions continuously escalate validation requirements that expand addressable demand for certified suppliers.
For Market Incumbents: Lock in multi-site sterile packaging contracts with major medical device OEMs before dual-source mandates harden into procurement policy. Backward integration into resin compounding defends margin position against halogenated additive phase-outs. Prioritize BSI certification pathways to capture post-Brexit UK market share while EU notified body backlogs persist.
For New Entrants and Emerging Players: Launch via Swissmedic-aligned biologics packaging services, where migration-limit enforcement preserves premium positioning for glass-compatible barrier specialists. Target steam-sterilizable rigid container segments in Germany's Tuttlingen corridor, where surgical kit standardization creates procurement consolidation opportunities. Pursue hospital GPO contracts in the Netherlands as extended producer responsibility frameworks reshape material specifications.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap sterile barrier converters because ISO 11607 validation expertise scarcity creates durable competitive moats that scale across acquired platforms. Five-to-ten year viability hinges on REACH-compliant material pipelines. Watch ECHA regulatory bulletins on per- and polyfluoroalkyl substance restrictions as the inflection signal for coating technology substitution cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11607 Certification Investment | Validates sterile barrier systems for EU MDR compliance, opening hospital procurement channels in Germany and Switzerland. |
| Backward Integration into Resin Compounding | Captures margin on medical-grade polypropylene while securing supply continuity for REACH-compliant formulations. |
| Gamma Irradiation Infrastructure Partnership | Extends serviceable radius for radiation-sterilized packaging, reducing logistics costs for Belgian pharmaceutical distributors. |
| Recyclable Laminate Product Line Launch | Meets extended producer responsibility quotas in France and the Netherlands without sacrificing burst strength performance. |
| BSI Conformity Assessment Pathway | Provides UKCA market access following Brexit divergence from EU notified body frameworks. |
Study Parameters
Direct dialogue with sterile packaging procurement managers at pharmaceutical contract manufacturers, biomedical engineers at hospital central supply departments, regulatory affairs leads at medical device OEMs, and technical directors at sterilization facilities grounded this analysis. Secondary validation drew from FDA 21 CFR Part 820 guidance documents, ECHA REACH restriction dossiers, ISO 11607 technical standards, and EU MDR implementation notices. Bottom-up demand modeling triangulated against top-down industry value chain assessments.
Segmented outputs across the projection horizon reflect product type splits between flexible packaging, rigid containers, and pouch formats; material categories spanning plastic, glass, and metal substrates; and end-user distinctions among healthcare, pharmaceutical, and laboratory applications. CAGRs were derived from sterilization modality adoption curves, biologics fill-finish capacity expansion timelines, and surgical procedure volume recovery patterns. Forecast inputs incorporated EU MDR validation mandate compliance costs and ECHA additive restriction implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH restriction timelines or ethylene oxide facility shutdown scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
Halal Packaging Market