
 Global Shelf Ready Packaging Market | 2026-2036
Global Shelf Ready Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shelf Ready Packaging Market Foresight
Packaging engineering talent is bifurcating between corrugated structural designers and digital print specialists, constraining how quickly manufacturers scale complex display formats. Smurfit Kappa leverages its European mill network to sustain integrated supply of kraft paperboard. WestRock anchors North American retail partnerships through high-volume folding carton operations. Mondi Group competes via specialty coatings that extend moisture resistance in chilled food trays.
Shelf ready packaging denotes retail-display containers engineered for direct placement on shelves without secondary handling, typically constructed from 200–400 gsm paperboard with die-cut apertures and stacking tabs that withstand 15–20 kg vertical load. The format eliminates unpacking labor, reduces shrinkage, and accelerates replenishment cycles in high-velocity retail environments. Corrugated trays and wrap arounds dominate volume as established categories with thin margins, while folding cartons capture expanding margin pools in premium personal care and pharmaceutical applications where lithographic print quality commands price premiums. Recycled paperboard is displacing virgin kraft in European supermarket supply chains as ESG procurement criteria harden.
The EU Green Deal, FDA food contact substance notifications, and China's GB standards collectively shape material compliance burdens and market access conditions for multi-territory suppliers. REACH restrictions on certain plasticizers and the EU Packaging and Packaging Waste Regulation are redirecting R&D investment toward fiber-based barrier technologies. Stakeholders must monitor how divergent national extended producer responsibility schemes reshape total cost of ownership calculations across their manufacturing footprints.
Market Dynamics
Retail labor cost compression is restructuring shelf ready packaging procurement, with automated replenishment systems and display-ready formats eliminating secondary handling steps across high-velocity supermarket chains.
Growth Catalysts
- EU Green Deal implementation:Mandatory recycled content thresholds in European supermarket supply chains are accelerating fiber-based barrier adoption and displacing virgin kraft specifications.
- Supermarket labor optimization:German and US hypermarket operators are mandating display-ready formats to reduce restocking hours and shrinkage in high-turnover categories.
- Digital print convergence:Lithographic quality standards are migrating to corrugated substrates, enabling premium personal care brands to consolidate packaging tiers.
Market Restraints
- Recycled fiber supply concentration:European kraft paperboard availability depends on Smurfit Kappa's integrated mill network, creating single-source vulnerability for mid-tier converters.
- REACH plasticizer restrictions:Barrier coating reformulations face extended ECHA notification timelines, delaying moisture-resistant chilled food tray launches.
- Structural designer scarcity:Packaging engineering programs produce insufficient corrugated specialists relative to folding carton talent, constraining complex display format scaling.
Strategic Opportunities
- Chinese GB standards alignment:Export-oriented converters can capture pharmaceutical shelf ready carton demand by certifying fiber sourcing to national food contact substance protocols.
- Pharmaceutical cold chain expansion:Specialty coated trays for temperature-sensitive biologics represent an underpenetrated application with price premium capture potential.
- Extended producer responsibility schemes:France and Italy's packaging fee differentials favor lightweight paperboard designs, rewarding material optimization investments.
Industry Challenges
- Die-cut precision tooling:Stacking tab tolerances below 0.5 millimeters require capital-intensive laser cutting upgrades that strain mid-cap converter balance sheets.
- FDA food contact synchronization:Dual compliance with US substance notifications and EU migration limits extends product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shelf Ready Packaging Market |
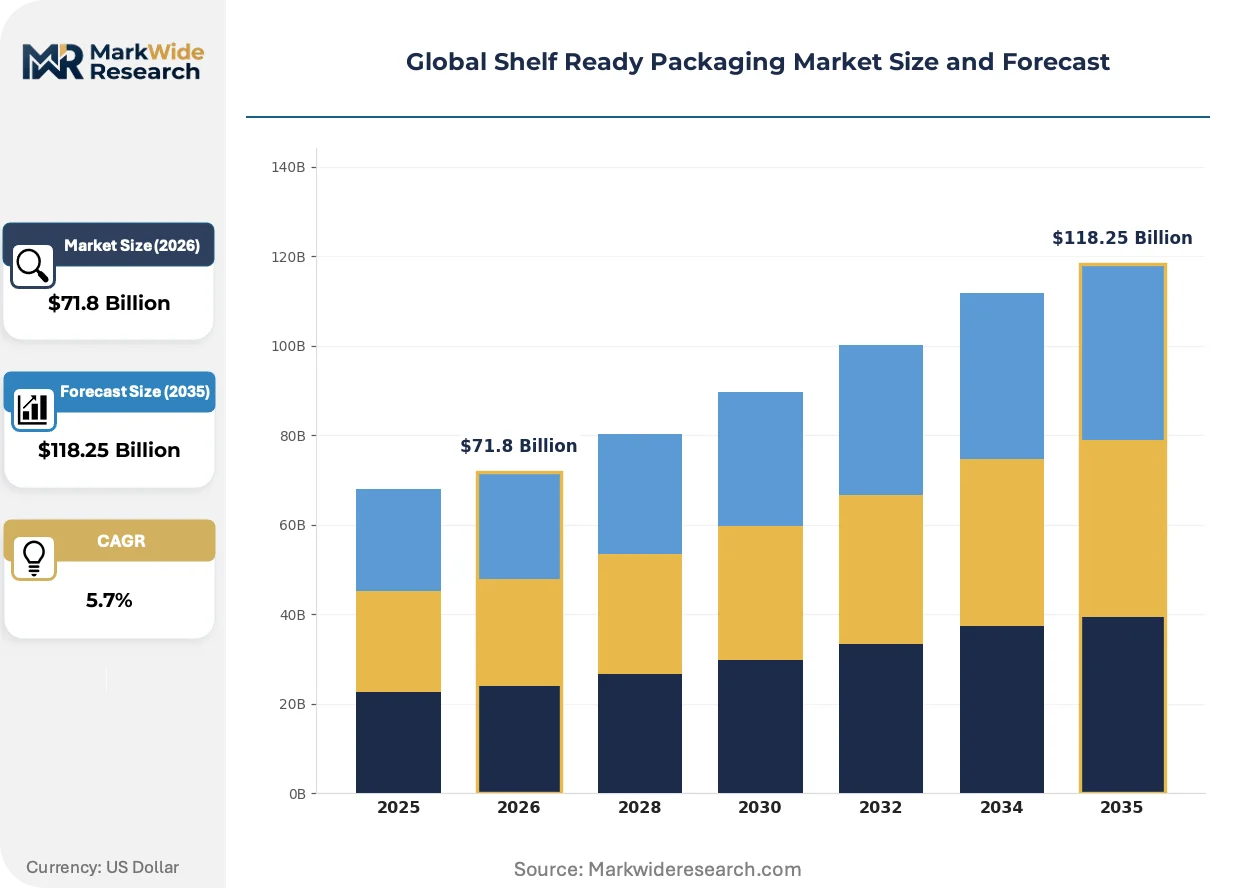
| Market Size in 2026 | $71.8 Billion |
| Market Size in 2035 | $118.25 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Trays, Blister Packs, Wrap Arounds, Display Trays, Folding Cartons Material: Kraft Paperboard, Polyethylene Terephthalate, Polyvinyl Chloride, Polystyrene, Recycled Paperboard End User Industry: Food & Beverage Manufacturers, Personal Care Brands, Pharmaceutical Producers, Consumer Electronics Companies, Pet Care Sector Distribution Channel: Supermarkets, Hypermarkets, Convenience Stores, Wholesale Clubs, Online Retailers |
| Companies Covered | Smurfit Kappa, WestRock, Mondi Group, DS Smith, International Paper, Sonoco Products Company, Graphic Packaging Holding Company, Amcor, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shelf Ready Packaging Market Shifts & Advancements
Barrier technology migration and regulatory material mandates are compressing legacy plastic tray specifications while digital print quality standards reshape competitive differentiation across substrate categories.
Water-based polymer coatings with oxygen scavenging functionality are supplanting extruded polyethylene barriers in chilled protein applications. German retail chains have adopted these fiber-based alternatives for private-label meat and seafood programs since late 2023. The shift is compressing demand for multi-material laminates that complicate post-consumer sorting infrastructure.
REACH restrictions on phthalate plasticizers are forcing coating reformulations across European converter operations. Industrial consequence includes eighteen-month validation cycles for new barrier chemistries and accelerated R&D partnerships with cellulose derivative suppliers. Chilled ready-meal categories face the steepest compliance burden given moisture and grease resistance requirements.
Consolidated retail procurement is compressing supplier panels and mandating pan-continental specification standardization. German and French buying alliances now require identical stacking strength and print registration tolerances across their combined footprint. This concentration rewards converters with multi-plant quality certification and penalizes single-facility specialists.
Global Shelf Ready Packaging Market Segmentation
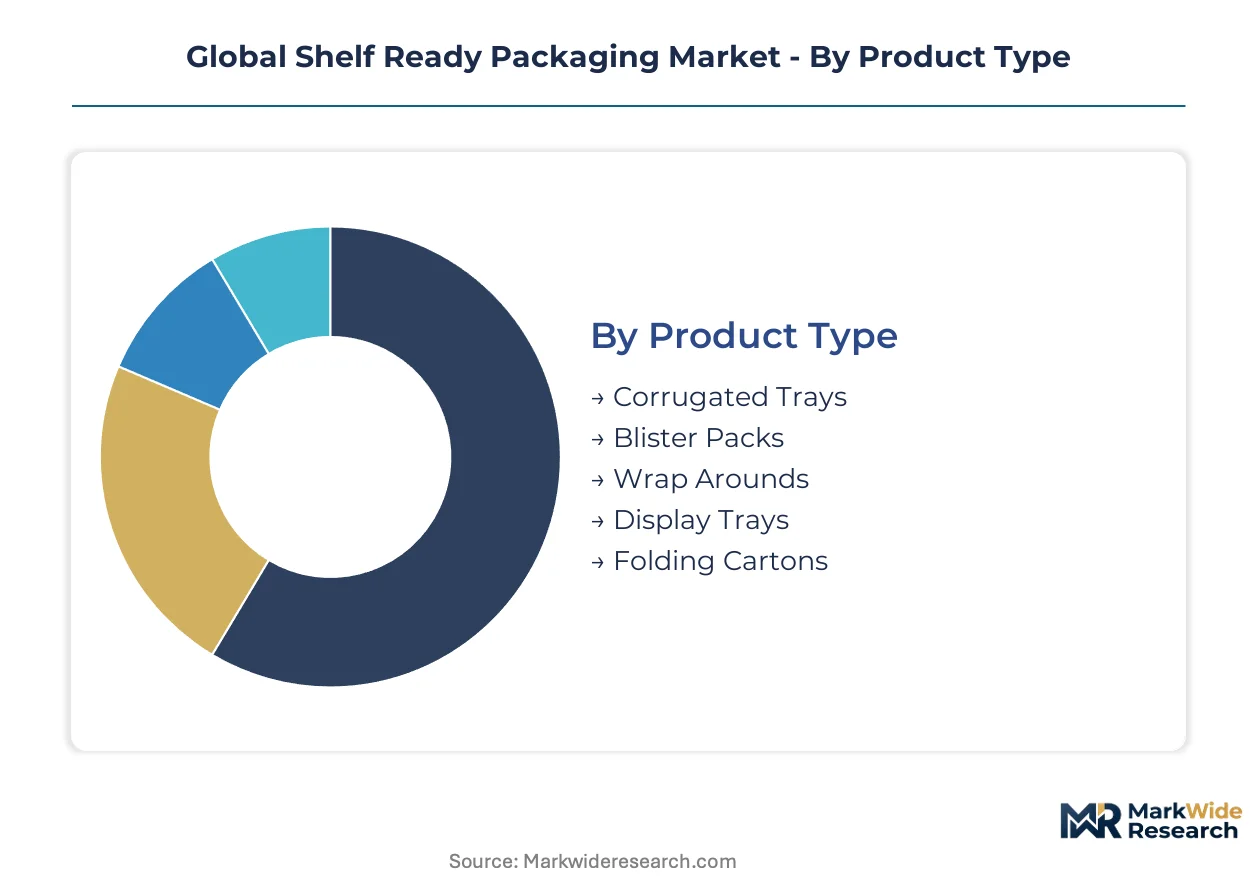
Segmentation in shelf ready packaging reveals how substrate choices and channel requirements fragment procurement specifications. Retail format dictates structural load requirements, while regulatory pressure on material composition reshapes converter investment priorities across end-use categories.
Product Type:
Corrugated formats face substitution pressure from rigid plastic trays in chilled protein applications where moisture resistance gaps persist.
- Corrugated Trays:Constructed from 200–400 gsm kraft linerboard with die-cut stacking tabs engineered for 15–20 kg vertical compression. German and US hypermarket operators specify these for ambient grocery categories where automated replenishment systems demand uniform pallet-to-shelf dimensions.
- Folding Cartons:Lithographic-printed solid bleached sulfate constructions capturing premium personal care and pharmaceutical applications. EU Green Deal recycled content mandates are compressing virgin fiber specifications in European pharmaceutical supply chains.
- Wrap Arounds:Pre-glued corrugated sleeves that encase primary containers for beverage multipacks.
- Blister Packs:Thermoformed plastic cavities sealed to printed card backing for small-format electronics and personal care items.
- Display Trays:Single-face corrugated or solid fiberboard platforms with built-in header cards for promotional end-cap placement.
Corrugated Trays anchors the volume base while Folding Cartons gains share at the steepest rate.
Material:
Cost tier differentiation separates fiber-based specifications from polymer alternatives facing regulatory compression.
- Recycled Paperboard:Post-consumer fiber processed to 250–350 gsm with proprietary barrier coatings for grease and moisture resistance. French and Italian extended producer responsibility schemes penalize heavier substrates, accelerating lightweight recycled specifications in private-label retail programs.
- Kraft Paperboard:Virgin unbleached sulfate pulp delivering superior tear strength and printability for high-velocity beverage and dry grocery applications. Smurfit Kappa's integrated European mill network supplies major converter operations, though ESG procurement criteria are narrowing specification windows.
- Polyethylene Terephthalate:Thermoformed clear trays for chilled ready-meal visibility requirements.
- Polystyrene:Foam and rigid formats for electronics cushioning and temperature insulation.
- Polyvinyl Chloride:Blister pack backing and transparent clamshells facing REACH plasticizer restrictions.
Recycled Paperboard climbs the fastest as ESG procurement hardens, while Polyvinyl Chloride contracts under regulatory pressure.
End User Industry:
Application maturity varies sharply, with food sector standardization contrasting pharmaceutical compliance complexity.
- Food & Beverage Manufacturers:The largest procurement volume, spanning ambient dry goods, chilled proteins, and beverage multipacks. German retail buying alliances mandate identical stacking strength tolerances across pan-continental footprints, rewarding converters with multi-plant quality certification.
- Pharmaceutical Producers:Temperature-sensitive biologics and high-value OTC categories requiring specialty coated trays with validated cold chain performance. China's GB standards for food contact substances create certification barriers for export-oriented converters seeking market entry.
- Personal Care Brands:Premium cosmetics and skincare lithographic cartons with metallic embellishment.
- Consumer Electronics Companies:Anti-static corrugated and foam-in-place protection for high-value devices.
- Pet Care Sector:Heavy-duty bags and multiwall constructions for dry food bulk formats.
Food & Beverage Manufacturers anchors the volume base while Pharmaceutical Producers shows the steepest margin expansion trajectory.
Distribution Channel:
Customer type concentration in consolidated retail groups compresses supplier panels and harmonizes specifications.
- Supermarkets:High-velocity replenishment environments where display-ready formats eliminate secondary handling labor. US and German operators have mandated shelf-ready specifications for top-turnover categories, with automated backroom systems requiring precise dimensional tolerances.
- Hypermarkets:Large-format operators with centralized distribution demanding pallet-to-shelf efficiency. French buying alliances now require identical print registration standards across combined footprints, penalizing single-facility specialists.
- Convenience Stores:Smaller format locations with limited backroom space favoring compact case counts.
- Wholesale Clubs:Bulk multipack formats with club-specific branding and pallet display requirements.
- Online Retailers:Ship-in-own-container specifications merging shelf-ready and e-commerce durability standards.
Supermarkets anchors the volume base while Online Retailers gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German supermarket operators specify display-ready formats for automated replenishment systems, while Chinese pharmaceutical exporters navigate GB food contact certification barriers. The United States anchors high-volume corrugated tray consumption for beverage multipacks, and French retail buying alliances enforce pan-continental print registration standards.
United States
FDA food contact substance notifications govern barrier coating approvals for chilled protein trays. Retail labor optimization drives adoption of pallet-to-shelf corrugated specifications in high-velocity grocery chains. The Midwest manufacturing corridor hosts folding carton converters serving pharmaceutical and personal care brand headquarters.
Germany
EU Green Deal recycled content mandates compress virgin kraft specifications in supermarket supply chains. ECHA REACH restrictions on plasticizers force eighteen-month coating reformulation cycles for ready-meal applications. The Rhine-Ruhr industrial cluster concentrates integrated paperboard mill and converter operations.
China
GB standards for food contact substances create certification hurdles for export-oriented pharmaceutical carton suppliers. Domestic e-commerce platforms merge shelf-ready and ship-in-own-container durability specifications. The Yangtze River Delta hosts specialty coated tray manufacturers targeting temperature-sensitive biologics cold chain demand.
France
Extended producer responsibility packaging fee differentials penalize heavier substrates and reward lightweight recycled paperboard designs. ANSM pharmaceutical packaging regulations govern barrier performance for high-value OTC categories. The Île-de-France region anchors retail buying alliance procurement consolidation mandating harmonized stacking strength tolerances.
India
FSSAI food safety standards shape barrier coating compliance for chilled dairy and ready-meal applications. Organized retail expansion in metropolitan markets drives first-wave adoption of display-ready formats. Maharashtra and Gujarat industrial corridors host emerging corrugated tray converters supplying modern trade supermarket chains.
Global Shelf Ready Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mill-owning conglomerates commanding kraft paperboard supply security while mid-cap converters compete on die-cut precision and regional logistics. The competitive terrain separates scale-driven integrated producers from coating technology specialists and folding carton quality leaders. Consolidation pressure intensifies as retail procurement panels compress and pan-continental quality certification becomes table stakes. Dominant competitive moves include backward integration into captive fiber supply and geographic expansion through multi-plant quality certification.
Among European integrated producers, Smurfit Kappa and Mondi Group exemplify the mill-network archetype that sustains kraft linerboard supply security for high-volume corrugated operations. WestRock anchors North American positioning through scale-driven folding carton partnerships with retail consolidators. These three entities represent distinct competitive vectors: European fiber integration, North American retail scale, and specialty barrier technology respectively.
| Leading Market Players |
|---|
| Smurfit Kappa |
| WestRock |
| Mondi Group |
| DS Smith |
| International Paper |
| Sonoco Products Company |
| Graphic Packaging Holding Company |
| Amcor |
| Georgia-Pacific |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German retail buying alliances and integrated paperboard mills lock in both kraft linerboard supply access and eighteen-month price visibility, insulating converters from spot market volatility in recycled fiber markets. These contracts tether shelf ready packaging procurement to Smurfit Kappa's Rhine-Ruhr mill network, where capacity reservation clauses override short-term price fluctuations for ambient grocery tray specifications.
Pricing Analysis
Contract-based long-term offtake dominates procurement for high-volume corrugated trays, while spot purchasing governs specialty coated folding cartons. Price differentiation separates premium lithographic pharmaceutical cartons with FDA food contact certification from standard recycled paperboard supermarket trays. Cost compression in mid-tier converter operations is intensifying because ECHA REACH compliance extends barrier coating development cycles. Private-label retail chains exhibit highest price sensitivity, whereas temperature-sensitive biologics producers accept premium positioning for validated cold chain performance.
Supply Chain Analysis
Rhine-Ruhr industrial cluster concentration underwrites European kraft paperboard availability, with Smurfit Kappa's integrated mill network serving as the primary chokepoint for corrugated linerboard supply. Raw material dependencies center on post-consumer recycled fiber, virgin unbleached sulfate pulp, and water-based polymer barrier coatings. Single-source vulnerability runs through mid-tier converters lacking captive fiber supply or multi-plant quality certification. Distribution runs through centralized retail procurement panels that mandate pan-continental specification standardization across German and French buying alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shelf ready packaging incumbents face substitution pressure from rigid plastic trays in chilled protein applications where moisture-resistant fiber barriers remain unproven at scale. Defense requires securing barrier technology leadership before water-based polymer coatings achieve commercial parity with extruded polyethylene specifications.
For Market Incumbents: Secure captive supply of kraft linerboard through backward integration into European mill assets or long-term offtake with Rhine-Ruhr producers. Invest in multi-plant quality certification to meet pan-continental retail procurement consolidation, defending against single-facility specialists excluded from German-French buying alliance panels. Prioritize ECHA-compliant barrier coating R&D partnerships to compress eighteen-month validation cycles threatening chilled ready-meal market access.
For New Entrants and Emerging Players: Lead with pharmaceutical cold chain applications for temperature-sensitive biologics, where specialty coated trays command price premiums and incumbent capacity concentrates on high-volume grocery formats. Target Chinese GB standards certification for export-oriented pharmaceutical carton supply, exploiting certification barriers that constrain European converter market entry. Establish coating technology partnerships with cellulose derivative suppliers to bypass Smurfit Kappa's fiber integration advantages.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with die-cut precision capabilities and established retail logistics relationships, positioned for acquisition by integrated producers seeking geographic expansion. Long-term viability favors assets with multi-plant quality certification and demonstrated ESG procurement compliance as EU Green Deal recycled content mandates harden. Monitor ECHA notification timelines for new barrier chemistries as inflection indicators for chilled food tray launch readiness and competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Paperboard Mills | Captive fiber supply insulates against Smurfit Kappa network concentration and secures long-term offtake pricing. |
| Multi-Plant Quality Certification Investment | Pan-continental retail procurement panels mandate identical stacking tolerances across German and French footprints. |
| Water-Based Polymer Barrier R&D Partnership | ECHA REACH restrictions on phthalate plasticizers force coating reformulations with eighteen-month validation cycles. |
| Chinese GB Standards Certification Program | Export-oriented pharmaceutical carton demand requires national food contact substance protocols for market access. |
| Lightweight Recycled Paperboard Design Optimization | French and Italian extended producer responsibility fee differentials penalize heavier substrates in private-label programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and mill production disclosures to construct bottom-up and top-down triangulation. Primary interviews engaged packaging engineering directors at corrugated converters, procurement leads at German and US hypermarket operators, barrier coating R&D specialists, and extended producer responsibility scheme administrators. Secondary validation drew from ECHA REACH substance notifications, EU Packaging and Packaging Waste Regulation drafts, FDA food contact substance inventories, and Chinese GB standards documentation. Cross-referencing converter capacity announcements with retail buying alliance specification releases tested volume assumptions.
Segmentation dimensions modeled span substrate category, end-use industry, distribution channel, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections tied to retail labor optimization adoption curves and material substitution timelines. Industry-specific forecast inputs incorporated ESG procurement criteria hardening trajectories and automated replenishment system penetration rates in high-velocity supermarket chains. Pharmaceutical cold chain expansion and temperature-sensitive biologics tray adoption formed scenario-weighted upside cases.
Forecasts assume regulatory continuity in EU Green Deal implementation, ECHA REACH restriction timelines, and FDA food contact notification pathways; material policy shifts would require re-modeling of barrier coating investment returns and recycled content compliance costs. Practitioners should keep alternative scenarios live as extended producer responsibility fee structures and national packaging waste regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Strawless Lids Market