
 Advanced Packaging Market | 2026-2036
Advanced Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Packaging Market Analysis
Project finance for advanced packaging fabs is narrowing the competitive field to capital-rich operators. ASE Technology leverages its scale across fan-out and system-in-package lines to sustain technology leadership. Taiwan Semiconductor Manufacturing Company anchors the foundry-linked packaging segment through co-located advanced nodes. Samsung Electronics dominates memory-integrated packaging with in-house DRAM and NAND supply.
Advanced packaging encompasses heterogeneous integration techniques that combine multiple dies within a single substrate using through-silicon vias, redistribution layers, and microbumps at pitches below 40 micrometers. These methods enable higher interconnect density and thermal performance than conventional wire bonding, serving the semiconductor industry's need for continued performance scaling beyond planar transistor limits. Active Packaging and Intelligent Packaging segments lead margin pools as sensors and communication modules command premium pricing, while Biodegradable Packaging within the technology dimension grows fastest amid regulatory pressure on electronic waste streams. Flexible Packaging and Rigid Packaging product types split the volume base, with flexible formats gaining in wearable electronics applications.
FDA oversight of medical device electronics and EPA hazardous substance rules shape material selection and qualification timelines for packaging destined for healthcare and consumer applications. REACH restrictions on lead and halogenated compounds in Europe, alongside RoHS compliance requirements, force reformulation of solder materials and substrate resins across supply chains. Stakeholders must monitor evolving export control frameworks and carbon border adjustments that threaten to fragment qualified supplier bases.
Market Dynamics
Project finance concentration is compressing the advanced packaging vendor base to capital-rich operators capable of funding billion-dollar fab investments while absorbing yield risk on sub-40-micron interconnect nodes.
Growth Catalysts
- Heterogeneous integration mandates:High-performance computing architects demand chiplets and 3D stacking to sustain transistor scaling beyond planar limits, pulling advanced packaging into the critical path of semiconductor roadmaps.
- EU Green Deal material rules:REACH restrictions on halogenated compounds and lead content force substrate resin reformulation, accelerating biodegradable substrate qualification cycles across European-bound supply chains.
- Memory-integrated packaging pull:DRAM and NAND suppliers in South Korea anchor captive demand for system-in-package formats serving AI accelerators and edge inference modules.
Market Restraints
- Substrate material volatility:Ajinomoto Build-up Film and bismaleimide-triazine resin supply concentrates among Japanese chemical specialists, exposing cost structures to yen-denominated input swings.
- Equipment lead time extension:Die bonder and lithography tool delivery stretches beyond 18 months, constraining capacity expansion for fan-out wafer-level packaging lines.
- Organic substrate thermal ceiling:Polyimide and epoxy-based materials hit thermal conductivity limits around 0.3 W/mK, restricting power density in high-performance compute applications.
Strategic Opportunities
- India PLI scheme attraction:Semiconductor packaging incentives under the country's production-linked incentive framework draw assembly and test investment away from traditional East Asian hubs.
- Photonics-electronics convergence:Co-packaged optics integration with silicon photonics dies opens margin pools in datacenter transceivers and telecommunications switching.
- Wearable form factor expansion:Flexible substrate demand from fitness trackers and medical patches creates volume upside for roll-to-roll processed fan-out panels.
Industry Challenges
- Process engineer scarcity:Redistribution layer lithography and through-silicon via etch expertise concentrates among Taiwan and South Korea talent pools, constraining geographic diversification.
- Multi-die qualification timelines:Automotive AEC-Q100 and medical ISO 13485 certification cycles extend 18-24 months for complex system-in-package designs, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Packaging Market |
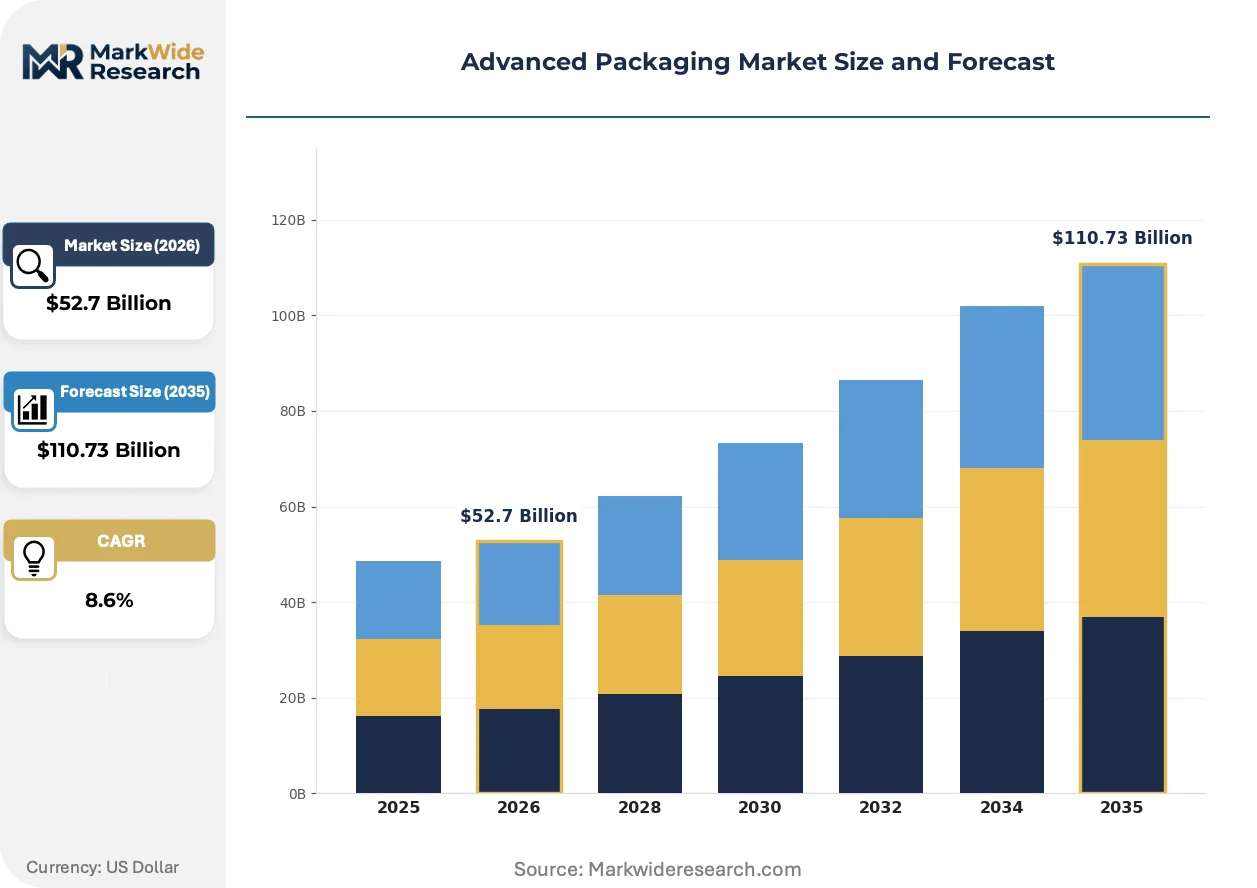
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Semi-Rigid Packaging, Sustainable Packaging Material: Plastic, Paperboard, Metal, Glass Technology: Active Packaging, Intelligent Packaging, Traditional Packaging, Biodegradable Packaging Application: Food & Beverages, Personal Care, Pharmaceuticals, Electronics |
| Companies Covered | ASE Technology, JCET Group, Taiwan Semiconductor Manufacturing Company, ChipMOS Technologies, Powertech Technology, Samsung Electronics, Intel Corporation, Tongfu Microelectronics, Amkor Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Packaging Market Emerging Trajectories
Hybrid bonding and glass core substrates are redrawing the cost-performance frontier for high-density interconnect, while regulatory pressure on electronic waste streams accelerates material substitution timelines.
Hybrid bonding is collapsing the pitch gap between die-to-wafer and wafer-to-wafer stacking. Memory suppliers now deploy copper-to-copper direct bonding below 10-micron pitch, eliminating microbump parasitics. This compression enables logic-memory stacking density previously unreachable with solder-based interconnect.
REACH substance restrictions are forcing solder material reformulation across European-bound production. ECHA candidate list expansions target brominated flame retardants in substrate laminates, compelling resin suppliers to qualify phosphorus-based alternatives. Medical device packaging faces the steepest compliance burden under MDR substance documentation rules.
Co-design workflows between foundries and packaging houses are displacing sequential handoff models. Fabless customers now embed thermal and electrical constraints from die floorplanning through final substrate routing. Taiwan and South Korea integrated device manufacturers demonstrate the tightest coupling, compressing time-to-yield for complex multi-die products.
Advanced Packaging Market Segmentation
Advanced packaging segmentation reveals competing priorities across substrate flexibility, interconnect density, and environmental compliance. Material choices and technology tiers determine access to margin pools in high-performance computing versus cost-sensitive consumer applications.
Product Type:
Mature formats dominate current volume, while emerging structures capture design-in momentum from wearable and foldable device architects.
- Flexible Packaging:Polyimide and liquid crystal polymer substrates enable bend radii below 5 millimeters for fitness trackers and medical patches. Demand concentrates in South Korean display-integrated module supply chains driven by foldable smartphone form factors.
- Rigid Packaging:Bismaleimide-triazine and Ajinomoto Build-up Film laminates provide dimensional stability for high-layer-count substrates above 10 metal layers. Taiwan's Hsinchu corridor anchors production for AI accelerator and networking switch applications where warpage control determines yield.
- Semi-Rigid Packaging:Hybrid constructions blending rigid core layers with flexible outer regions serve automotive radar modules requiring vibration tolerance.
- Sustainable Packaging:Bio-based substrate resins and recyclable metallization processes address EU Green Deal electronic waste mandates.
Rigid Packaging retains volume leadership; Sustainable Packaging holds the steepest expansion curve.
Material:
Cost tier stratification separates premium thermal performance substrates from commodity laminates in high-volume consumer applications.
- Plastic:Epoxy molding compounds and polyimide films constitute the baseline substrate material for fan-out wafer-level packaging and system-in-package modules. Taiwan and South Korea chemical suppliers dominate formulation expertise for low-alpha particle grades required by memory-integrated stacks.
- Paperboard:Fiber-based substrates with printed conductive traces serve disposable medical sensors and environmental monitoring patches where cost minimization outweighs durability requirements.
- Metal:Copper lead frames and aluminum heat spreaders manage thermal dissipation in power modules and automotive electronics.
- Glass:Borosilicate and alkali-free glass cores enable sub-30-micron through-glass vias for RF and millimeter-wave packaging with low dielectric loss.
Plastic substrates command the widest application footprint; Glass materials are climbing the fastest as RF integration intensifies.
Technology:
Application requirements across sensing, computation, and sustainability compliance drive divergence between functional and baseline packaging tiers.
- Active Packaging:Integrated sensors, power management circuits, and communication modules embedded within the substrate structure enable real-time condition monitoring. Pharmaceuticals and cold-chain logistics drive qualification in Europe under EMA temperature excursion tracking mandates.
- Intelligent Packaging:Near-field communication tags and printed electronics provide authentication and supply chain traceability. Personal care and luxury goods sectors in France and Germany absorb volume amid anti-counterfeiting regulatory pressure.
- Traditional Packaging:Passive interconnect structures without embedded active components serve cost-optimized consumer electronics and standard semiconductor devices.
- Biodegradable Packaging:Compostable substrate materials and transient electronics dissolve after specified operational lifetimes, addressing REACH restrictions on persistent electronic waste in European medical and agricultural deployments.
Traditional Packaging maintains the broadest installed base; Biodegradable Packaging gains share fastest under tightening waste regulations.
Application:
End-use concentration patterns align packaging complexity with device performance requirements and regulatory scrutiny intensity.
- Food & Beverages:Modified atmosphere packaging with oxygen scavengers and moisture barriers extends shelf life for perishable goods. Japan's METI food safety standards drive intelligent packaging adoption for freshness indication.
- Personal Care:Airless pumps and precision dispensers combine with anti-tamper features for high-value cosmetic and dermatological formulations.
- Pharmaceuticals:FDA and EMA compliance requirements for temperature monitoring, child resistance, and tamper evidence elevate packaging qualification timelines. Cold-chain biologics demand active thermal management substrates.
- Electronics:Heterogeneous integration of logic, memory, and photonic dies in AI accelerators and datacenter switches represents the highest interconnect density tier. South Korean memory suppliers and Taiwan foundries anchor demand for 3D stacking and fan-out configurations.
Electronics applications generate the highest value per unit; Pharmaceuticals packaging faces the steepest regulatory compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in advanced packaging equipment and substrates concentrate among three East Asian economies, with secondary demand absorption in North America and Europe. Taiwan and South Korea post consistent packaging service surpluses, while the United States and Germany remain net importers of high-density interconnect capacity. Regulatory divergence on substance restrictions and carbon border adjustments is fragmenting qualified supplier bases across destination markets.
Taiwan
Hsinchu Science Park anchors the world's densest concentration of fan-out wafer-level packaging capacity, serving fabless AI accelerator designers and smartphone chipset vendors. The National Development Council's semiconductor advancement programs subsidize advanced node packaging R&D through 2026. ASE Technology and Taiwan Semiconductor Manufacturing Company operate co-located facilities in Taichung and Tainan, compressing time-to-yield for complex multi-die products.
South Korea
Captive demand from Samsung Electronics and SK Hynix drives memory-integrated packaging volumes for AI training accelerators and edge inference modules. The Ministry of Trade, Industry and Energy classifies advanced packaging as a strategic technology under national industrial policy frameworks. Pyeongtaek and Yongin host the primary clusters for 3D DRAM stacking and high-bandwidth memory assembly.
United States
Domestic packaging capacity lags wafer fabrication investments, creating persistent reliance on Asian assembly and test services for advanced node products. CHIPS Act funding allocations target substrate and packaging reshoring through 2027, with Arizona and Texas designated as priority zones. Intel Corporation's New Mexico and Oregon facilities represent the largest captive advanced packaging footprint outside East Asia.
Germany
Automotive semiconductor packaging for power modules and radar systems concentrates in Bavaria and Saxony, serving Volkswagen, BMW, and Continental supply chains. REACH substance restrictions and the EU Green Deal accelerate biodegradable substrate qualification cycles for European-bound production. Dresden's Silicon Saxony cluster hosts Infineon and Bosch packaging operations for automotive-qualified system-in-package modules.
Japan
Ajinomoto Build-up Film and bismaleimide-triazine resin supply concentrates among Tokyo and Osaka chemical specialists, exposing global cost structures to yen-denominated input volatility. METI's semiconductor materials security initiatives prioritize domestic substrate resin capacity expansion through 2028. Kyushu's Kumamoto region hosts packaging facilities serving Sony image sensor and automotive semiconductor demand.
Advanced Packaging Market Vendor Landscape
On the supply side, the industry is consolidating around capital-rich operators capable of absorbing billion-dollar fab investments and sub-40-micron yield risk. Project finance concentration has compressed the vendor base to integrated device manufacturers, dedicated packaging houses, and foundry-affiliated operations. Three strategic archetypes dominate: captive packaging divisions of memory and logic suppliers, independent outsourced assembly and test providers, and foundry-co-located advanced packaging specialists. Competitive positioning hinges on M&A-driven technology acquisition and geographic capacity expansion into subsidy-attractive jurisdictions.
Within the foundry-linked tier, Taiwan Semiconductor Manufacturing Company exemplifies tight coupling between leading-edge node fabrication and advanced packaging services. Among independent providers, ASE Technology and Amkor Technology occupy positions spanning fan-out wafer-level packaging and system-in-package formats. Samsung Electronics represents the captive integration archetype, leveraging in-house DRAM and NAND supply to anchor memory-integrated packaging demand. These three entities collectively illustrate the capital intensity and technology specialization required to sustain position in high-density interconnect markets.
| Leading Market Players |
|---|
| ASE Technology |
| JCET Group |
| Taiwan Semiconductor Manufacturing Company |
| ChipMOS Technologies |
| Powertech Technology |
| Samsung Electronics |
| Intel Corporation |
| Tongfu Microelectronics |
| Amkor Technology |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Taiwan's fan-out wafer-level packaging fabs drives aggressive equipment procurement and pricing power consolidation among ASE Technology and Taiwan Semiconductor Manufacturing Company, while South Korean memory-integrated packaging lines absorb premium pricing for high-bandwidth memory stacks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for advanced packaging services, with pricing stratifying across premium, standard, and economy tiers based on interconnect density and automotive qualification grade. Price differentiation hinges on AEC-Q100 certification level and volume scale, with automotive-qualified system-in-package modules commanding substantial premiums over consumer-grade fan-out configurations. Cost compression in standard-tier consumer packaging is intensifying because equipment lead time extension constrains capacity expansion. Fabless AI accelerator designers exhibit the least price sensitivity due to performance-critical die-stacking requirements, while commodity consumer electronics OEMs drive hard negotiations on per-unit assembly costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for substrate material flows, compelling qualification of alternative resin suppliers outside traditional East Asian hubs. Geographic supply concentration centers on Taiwan, South Korea, and Japan, with Ajinomoto Build-up Film and bismaleimide-triazine resin formulation expertise anchored in Tokyo and Osaka chemical specialists. Raw material dependencies rest on copper microbump plating chemistries, polyimide dielectric films, and glass core substrates for RF applications. Single-source vulnerability in die bonder equipment from Japanese and Dutch suppliers constrains capacity scaling. Distribution runs through co-located foundry-packaging facilities in Hsinchu and Pyeongtaek, with secondary hub development in Arizona and Texas under CHIPS Act incentives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced packaging is approaching a platform-economics inflection where co-design workflows between foundries and packaging houses create interoperability lock-in, with heterogeneous integration roadmaps binding fabless customers into multi-year technology partnerships.
For Market Incumbents: Pre-empt margin erosion in fan-out wafer-level packaging by securing captive supply of Ajinomoto Build-up Film through backward integration into substrate resin formulation, while accelerating biodegradable substrate qualification to meet EU Green Deal compliance deadlines ahead of REACH substance restriction enforcement. Capacity addition in India under PLI scheme incentives offers geographic hedge against concentration risk in Taiwan and South Korea talent pools. For New Entrants and Emerging Players: Build out roll-to-roll processed fan-out panel capabilities for wearable form factors, where flexible substrate demand from fitness trackers and medical patches remains underpenetrated by incumbent rigid-format specialists. Photonics-electronics convergence in datacenter transceivers represents the most penetrable white-space segment, with co-packaged optics integration requiring packaging expertise that memory-centric incumbents have not prioritized. Go-to-market angle: partner with silicon photonics die suppliers for joint qualification of glass core substrate solutions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foundry-co-located advanced packaging specialists with multi-year service agreements tied to leading-edge node tape-outs, offering visibility through semiconductor capital expenditure cycles. Long-term viability over the five-to-ten year window favors acquisition targets with hybrid bonding expertise below ten-micron pitch and established co-design workflows with fabless AI accelerator designers. Signal to watch: automotive OEM direct sourcing of system-in-package modules bypassing traditional Tier 1 supplier relationships, indicating vertical integration pressure that reshapes packaging vendor selection criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Scale-Up | Copper-to-copper direct bonding below ten-micron pitch eliminates microbump parasitics for logic-memory stacks. |
| Glass Core Substrate Qualification | Borosilicate cores enable sub-thirty-micron through-glass vias with low dielectric loss for RF integration. |
| Biodegradable Substrate Development | Compostable resins address REACH restrictions on persistent electronic waste in European medical deployments. |
| India PLI Scheme Participation | Production-linked incentives draw assembly and test investment away from traditional East Asian packaging hubs. |
| Co-Packaged Optics Integration | Silicon photonics die bonding opens margin pools in datacenter transceivers and telecommunications switching. |
Methodological Framework
Desk research of SEC filings from ASE Technology, Samsung Electronics, and Intel Corporation preceded structured interviews with packaging process engineers, fabless semiconductor procurement directors, and substrate material R&D leads. Secondary validation drew from Taiwan's National Development Council semiconductor advancement program disclosures, South Korea's Ministry of Trade, Industry and Energy strategic technology classifications, and ECHA REACH substance restriction candidate list updates. Bottom-up capacity modeling across fan-out wafer-level packaging lines triangulated against top-down market sizing from heterogeneous integration demand forecasts.
Assumptions held fixed include continued fabless reliance on outsourced advanced packaging for leading-edge AI accelerators and sustained memory-integrated packaging pull from DRAM and NAND suppliers. The analytical framework modeled segmentation across product type, material, technology, and application dimensions, with interconnect density tiers and regulatory compliance clusters as cross-cutting variables. CAGRs were derived from capacity expansion announcements, equipment delivery schedules, and design-in momentum for chiplets and three-dimensional stacking configurations.
Practitioners should monitor equipment lead time extension beyond eighteen months and substrate material volatility in yen-denominated inputs for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Airless Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
Consumer Packaging Market