
 Global E-Commerce Packaging Market | 2026-2036
Global E-Commerce Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Commerce Packaging Market Analysis
Sustainability-focused retailers and direct-to-consumer brands is bifurcating demand away from conventional bulk shippers. Smurfit Kappa Group dominates European corrugated supply through integrated recycling and paper mill networks. Mondi plc differentiates via performance-grade kraft papers tailored for automated fulfillment lines. Sealed Air Corporation specializes in inflatable protective systems that reduce dimensional weight charges for air freight.
Global E-Commerce Packaging comprises engineered containment and cushioning systems—typically corrugated fiberboard between 3mm and 7mm flute profiles, polyethylene air pillows, or molded pulp inserts—designed to protect goods through single-parcel distribution chains from seller to individual residence. Flexible packaging and protective packaging represent the fastest-expanding product categories as apparel and electronics shippers substitute lightweight mailers and air cushions for rigid boxes to cut last-mile shipping costs. Cardboard sustains the largest material share by tonnage, though sustainable materials including grass-fiber and recycled-content substrates are capturing margin pools in premium subscription and cosmetic segments where unboxing experience commands price premiums.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and extended producer responsibility schemes, while the US EPA pushes source reduction guidelines that favor right-sized designs. China's SAMR enforces GB standards for express packaging that limit single-use plastics and promote reusable containers. Stakeholders must monitor how fragmented national compliance calendars reshape material specifications and supplier qualification timelines.
Market Dynamics
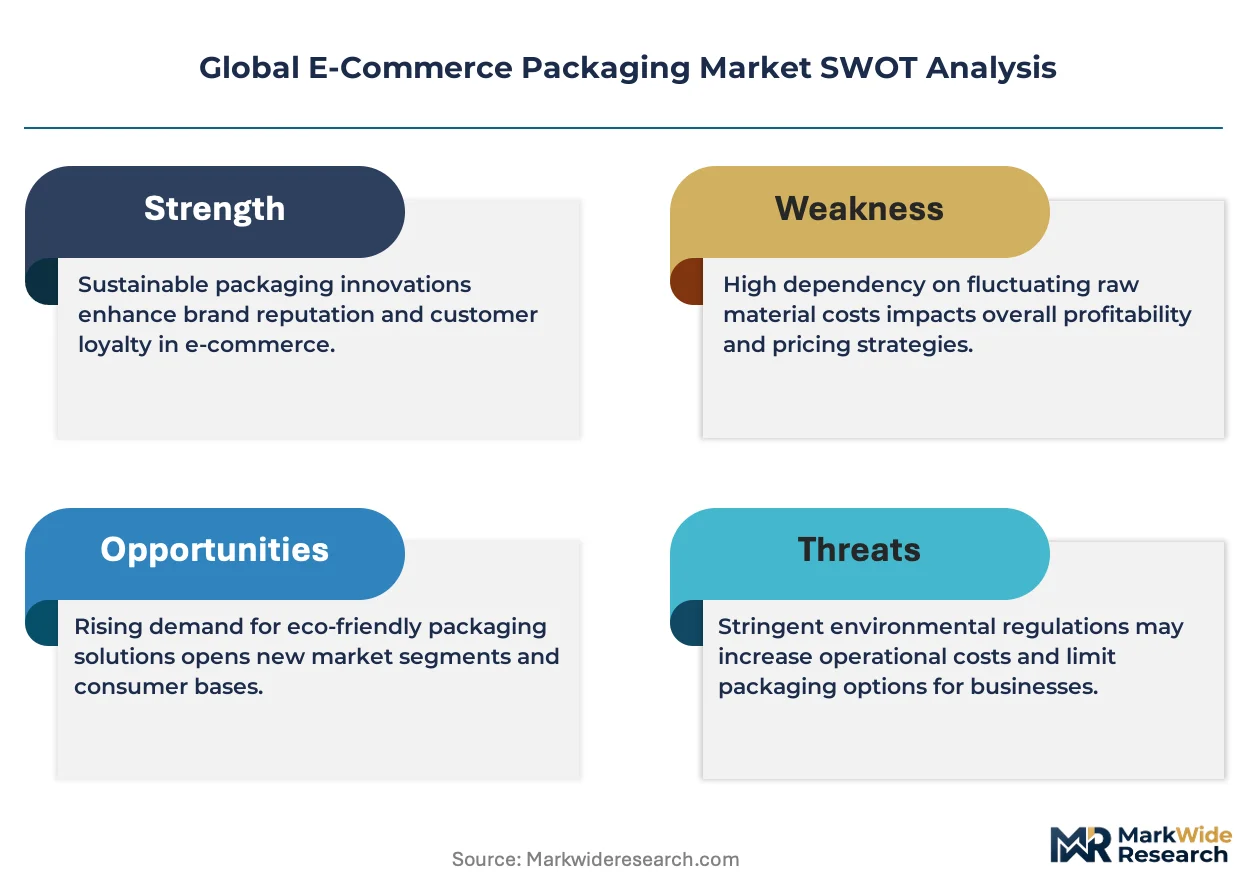
The EU Packaging and Packaging Waste Regulation is forcing a material specification rewrite across fulfillment networks, as recyclability mandates collide with cost-minimization pressures in high-velocity parcel operations.
Growth Catalysts
- Live-stream commerce proliferation:China's same-day delivery networks multiply parcel volumes, creating demand for lightweight protective formats that withstand repeated handling.
- Temperature-controlled fulfillment expansion:Online grocery retailers in Germany and France are scaling insulated box procurement for fresh food last-mile distribution.
- GB standards enforcement:China's SAMR mandates limiting single-use plastics in express packaging are accelerating adoption of reusable container systems across domestic e-commerce platforms.
Market Restraints
- Recycled fiber cost volatility:Old corrugated containerboard prices swing with municipal collection disruptions, compressing margin on post-consumer content claims.
- Fluting substrate concentration:European kraft liner supply clusters in Nordic integrated mills, creating geographic vulnerability to energy price spikes.
- Biodegradable film performance ceiling:Polylactic acid barriers fail moisture protection tests for electronics, blocking substitution in high-value parcel segments.
Strategic Opportunities
- Grass-fiber substrate white space:Underpenetrated premium cosmetic subscription boxes in the United States command price premiums for alternative fiber unboxing experiences.
- Automated fulfillment convergence:Machine-vision sortation systems paired with right-sized box-on-demand equipment are opening retrofit contracts with mid-tier apparel distributors.
- Extended producer responsibility tailwinds:France's Citeo eco-modulation fees reward designs above recycled content thresholds, creating margin arbitrage for compliant suppliers.
Industry Challenges
- Food-contact certification timelines:Recycled-content polyethylene mailers face extended FDA migration testing cycles, delaying US market entry for European converters.
- Legacy warehouse management integration:Right-sizing algorithms require API reconfiguration with existing WMS platforms, stretching IT deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Commerce Packaging Market |
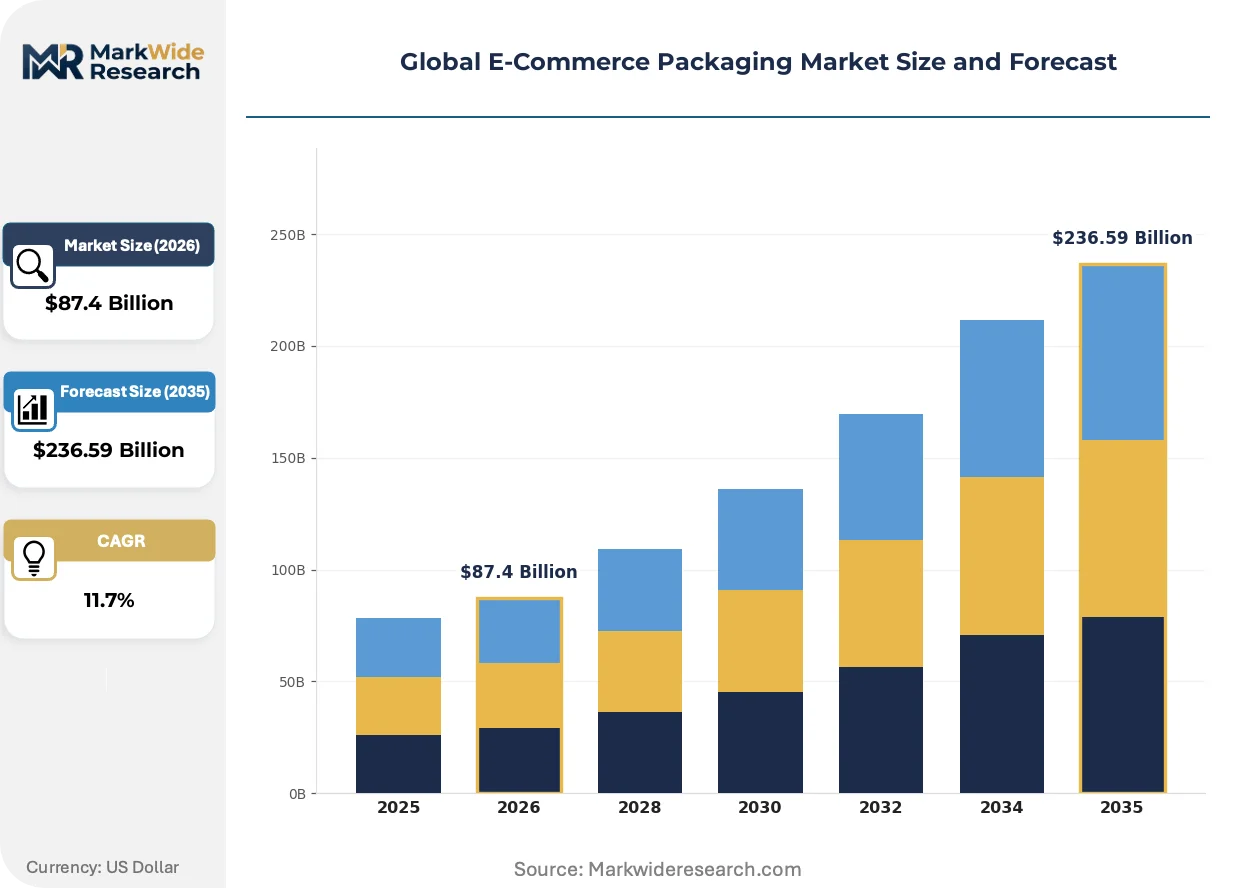
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $236.59 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxed Packaging, Flexible Packaging, Protective Packaging, Pallet Packaging Material: Cardboard, Plastic, Bubble Wrap, Sustainable Materials End User: Retailers, Wholesalers, Manufacturers, Logistics Providers Delivery Mode: Standard Shipping, Express Delivery, Same-Day Delivery, Curbside Pickup |
| Companies Covered | Smurfit Kappa Group, WestRock Company, International Paper Company, Berry Global Group, Inc., Sealed Air Corporation, DS Smith plc, Amcor plc, Sonoco Products Company, Mondi plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Commerce Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory compliance automation are compressing design-to-shelf cycles, while fulfillment robotics reshape dimensional optimization requirements.
Curbside-recyclable paper cushioning is decomposing the air pillow monopoly in apparel fulfillment. Mid-market fashion retailers in the United Kingdom and Netherlands are piloting accordion-fold kraft inserts at scale. This substitution is decomposing polyethylene demand in non-fragile parcel categories and redirecting capital toward pulp molding capacity.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from food-contact mailers. European corrugated converters are qualifying silicone-free alternatives through ECHA-registered testing protocols. Frozen meal kit distributors in Scandinavia are absorbing cost premiums to maintain single-material recyclability claims for consumer sorting convenience.
Unboxing experience has become a discrete procurement criterion with dedicated budget lines. Direct-to-consumer beauty brands in South Korea and the United States are specifying magnetic-closure rigid boxes with soy-ink printing for social media shareability. This specification tier commands three to five times the unit cost of standard shipper formats, creating a defensible margin pool for substrate innovators.
Global E-Commerce Packaging Market Segmentation
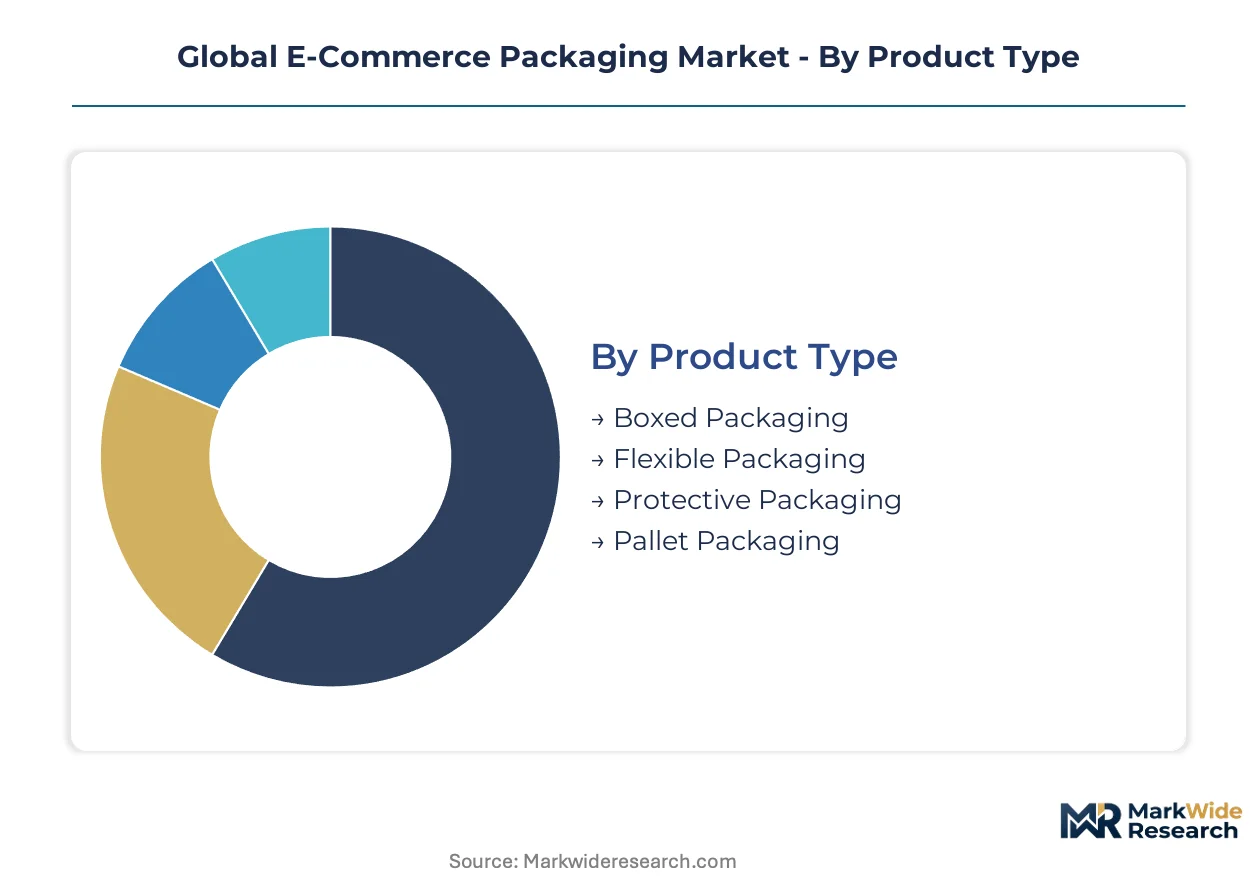
Channel mix dictates packaging specification tiers in e-commerce fulfillment. Automated sortation hubs favor rigid formats, while last-mile density networks drive flexible alternatives. Material and delivery mode selections cascade from these channel economics.
Product Type:
Channel economics split demand between fulfillment center formats and last-mile optimized designs. Automated warehouses favor rigidity; dense urban delivery networks prioritize dimensional efficiency.
- Boxed Packaging:Corrugated fiberboard between 3mm and 7mm flute profiles dominates automated fulfillment lines. Demand concentrates in China's live-stream commerce networks where same-day handling cycles require structural integrity through multiple touchpoints.
- Flexible Packaging:Polyethylene mailers and polypropylene pouches reduce dimensional weight charges for apparel shippers. European fashion retailers in Germany and France are substituting rigid boxes to cut last-mile costs in dense urban delivery zones.
- Protective Packaging:Air pillows, molded pulp, and paper cushioning systems shield electronics and cosmetics through single-parcel distribution.
- Pallet Packaging:Stretch film and corner board systems secure bulk consolidation for B2B e-commerce fulfillment.
By volume, Boxed Packaging leads. By growth pace, Flexible Packaging is ahead.
Material:
Cost tier stratification separates commodity substrates from certified sustainable alternatives commanding procurement premiums.
- Cardboard:Kraft liner and recycled-content medium constitute the tonnage base. Nordic integrated mills supply European demand, exposing buyers to energy price volatility in pulp production.
- Sustainable Materials:Grass-fiber and agricultural residue substrates capture margin pools in premium cosmetic subscriptions. United States direct-to-consumer beauty brands specify these for unboxing shareability.
- Plastic:Linear low-density polyethylene dominates mailer films and air pillow construction.
- Bubble Wrap:Co-extruded polyethylene barriers provide cushioning for fragile electronics and glassware.
Cardboard maintains volume dominance. Sustainable Materials are climbing the fastest on subscription box procurement.
End User:
Customer type determines specification complexity and compliance burden intensity.
- Retailers:Omnichannel operators balance store replenishment shippers against direct-to-consumer formats. China's e-commerce platforms drive reusable container mandates under SAMR GB standards enforcement.
- Logistics Providers:Third-party fulfillment operators standardize across client portfolios to maximize sortation throughput. European networks face EU Packaging and Packaging Waste Regulation recyclability rewrites.
- Wholesalers:B2B consolidation operations prioritize pallet-level efficiency over individual parcel protection.
- Manufacturers:Brand-direct fulfillment requires unboxing experience specifications for social media differentiation.
Retailers lead by parcel volume. Logistics Providers are expanding fastest on outsourced fulfillment growth.
Delivery Mode:
Speed tier determines protective intensity and temperature control requirements.
- Same-Day Delivery:Repeated handling cycles in China's urban networks multiply demand for lightweight protective formats. Temperature-controlled fulfillment for fresh food expands insulated box procurement in Germany and France.
- Express Delivery:Air freight economics favor inflatable protective systems that reduce dimensional weight charges. Sealed Air Corporation's inflatable formats target this velocity tier.
- Standard Shipping:Ground distribution tolerates lighter protection for non-fragile categories.
- Curbside Pickup:Reduced transit handling permits minimal protective specifications.
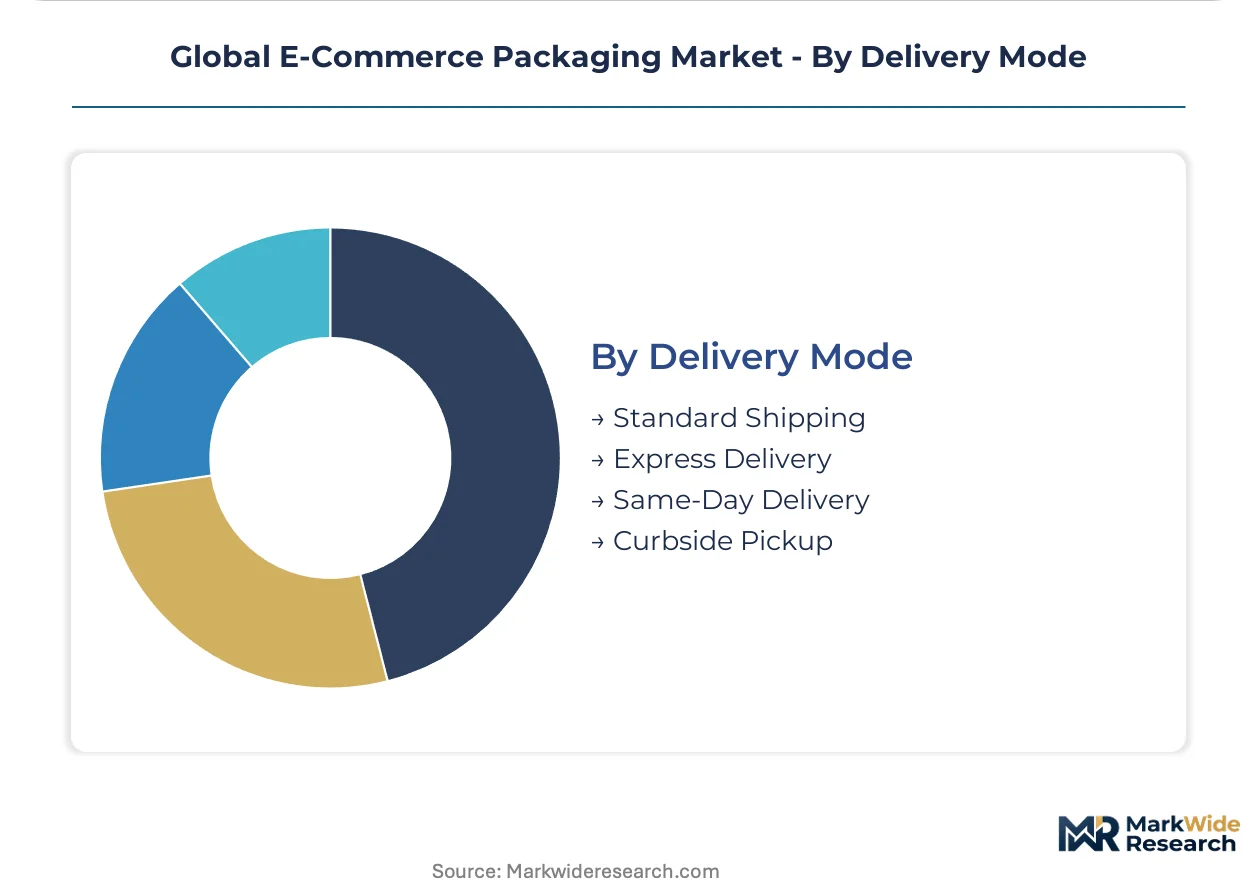
Standard Shipping leads by volume. Same-Day Delivery shows the steepest expansion trajectory on live-stream commerce proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated paper mills cluster in Nordic regions and China's eastern seaboard, exposing buyers to energy cost volatility and pulp supply disruptions. Recycled fiber networks concentrate in Germany and the Netherlands, creating secondary supply hubs. Regulatory divergence across major economies is fragmenting material specifications and compliance timelines.
China
Live-stream commerce platforms and same-day delivery networks in Shanghai and Hangzhou multiply parcel volumes beyond any other single market. SAMR's GB standards enforcement limits single-use plastics in express packaging and mandates reusable container adoption. The Yangtze River Delta hosts the densest concentration of automated fulfillment centers, driving demand for lightweight protective formats that withstand repeated handling cycles.
Germany
Online grocery retailers in Berlin and Munich are scaling insulated box procurement for fresh food last-mile distribution. The EU Packaging and Packaging Waste Regulation imposes minimum recycled content thresholds and extended producer responsibility schemes across fulfillment networks. The Rhine-Ruhr industrial corridor anchors European corrugated supply through integrated recycling and paper mill operations.
United States
Direct-to-consumer beauty brands in Los Angeles and New York specify magnetic-closure rigid boxes with soy-ink printing for social media shareability. The EPA pushes source reduction guidelines that favor right-sized designs and curbside-recyclable formats. The Southeast manufacturing belt—spanning Georgia, Tennessee, and the Carolinas—concentrates molded pulp capacity for electronics cushioning.
France
Frozen meal kit distributors in Paris and Lyon absorb cost premiums to maintain single-material recyclability claims for consumer sorting convenience. Citeo eco-modulation fees reward designs above recycled content thresholds, creating margin arbitrage for compliant suppliers. The Hauts-de-France region clusters kraft liner production, linking pricing to Nordic pulp cost swings.
United Kingdom
Mid-market fashion retailers in London and Manchester pilot accordion-fold kraft inserts at scale, decomposing polyethylene demand in non-fragile parcel categories. REACH substance restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant coatings from food-contact mailers. The Midlands logistics corridor standardizes across client portfolios to maximize sortation throughput for third-party fulfillment operators.
Global E-Commerce Packaging Market Vendor Landscape
Concentration sits with integrated paper and board producers that control recycled fiber supply chains from municipal collection through finished corrugated conversion. The market structure splits between scale-driven multinational converters and regional specialists with captive pulp supply. Three archetypes dominate: Nordic-integrated mills with energy-intensive kraft liner production, automated fulfillment solution providers, and sustainable substrate innovators capturing premium cosmetic subscriptions. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players seek backward integration into pulp supply and geographic coverage in high-velocity parcel markets.
Within the integrated paper and board tier, Smurfit Kappa Group and Mondi plc exemplify archetypes with European mill networks and performance-grade substrate specialization. Sealed Air Corporation occupies a distinct position among protective systems providers. These three companies anchor competitive dynamics across fulfillment automation, sustainable material certification, and air freight dimensional weight reduction—representing the strategic vectors that reshape procurement relationships with omnichannel retailers and third-party logistics operators.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| WestRock Company |
| International Paper Company |
| Berry Global Group, Inc. |
| Sealed Air Corporation |
| DS Smith plc |
| Amcor plc |
| Sonoco Products Company |
| Mondi plc |
| Others |
Supply Flow & Price Mechanics
Mill-scale utilization at Nordic integrated pulp facilities anchors cost floors for kraft linerboard across European corrugated supply, concentrating pricing power among producers with captive fiber recycling networks and exposing converters to energy cost pass-through volatility. This scale concentration stratifies procurement tiers between multinational retailers with long-term offtake contracts and mid-market distributors purchasing on spot-indexed terms.
Pricing Analysis
Volume-discount tiering separates enterprise omnichannel retailers with multi-year corrugated contracts from spot-market purchasers facing Old Corrugated Containerboard price swings. Price differentiation rests on recycled-content certification grade and fulfillment automation compatibility, with EU Packaging and Packaging Waste Regulation compliance commanding premiums. Cost compression in standard-grade kraft liner is intensifying as Chinese live-stream commerce platforms drive demand for lightweight formats. Third-party logistics operators show highest price sensitivity due to thin margin structures, while direct-to-consumer beauty brands absorb premiums for magnetic-closure rigid boxes.
Supply Chain Analysis
Inventory lead-times for molded pulp cushioning extend during peak Q4 fulfillment seasons as Southeast US capacity runs at effective maximum. Supply concentrates in China for polyethylene air pillow films, in Germany and the Netherlands for recycled fiber networks, and across Nordic regions for virgin kraft liner production. Raw material dependencies draw from OCC collection streams, grass-fiber agricultural residues, and LLDPE resin feedstocks. Single-source vulnerability sits with Nordic integrated mills exposed to natural gas price spikes. Distribution runs through automated sortation hubs in the Yangtze River Delta and Rhine-Ruhr corridor before last-mile handoff to regional parcel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global E-Commerce Packaging Market is entering a cyclical upswing as live-stream commerce proliferation and same-day delivery network expansion drive replacement demand for protective formats. This recovery phase rewards suppliers with certified sustainable material pipelines and automated fulfillment integration capabilities.
For Market Incumbents: Secure backward integration into grass-fiber pulp supply to defend margin position against agricultural residue substrate innovators capturing premium cosmetic subscriptions. Expand molded pulp capacity in the Southeast US manufacturing belt to serve electronics cushioning demand from direct-to-consumer brands. Prioritize API-enabled right-sizing algorithm development to capture retrofit contracts with mid-tier apparel distributors facing legacy warehouse management integration challenges. For New Entrants and Emerging Players: FSC-certified grass-fiber fast-track qualification opens white-space in United States premium subscription box procurement where unboxing experience commands price premiums. Target underpenetrated temperature-controlled fulfillment networks in Germany and France scaling insulated box procurement for fresh food last-mile distribution. Lead with curbside-recyclable paper cushioning pilots to displace polyethylene air pillows in mid-market fashion retail segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated fulfillment solution providers with machine-vision sortation and box-on-demand equipment integration capabilities. Long-term viability over the next decade hinges on regulatory compliance automation and extended producer responsibility scheme participation. Monitor Citeo eco-modulation fee structures as the inflection signal for margin arbitrage opportunities in recycled-content threshold compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive grass-fiber sourcing insulates margin from OCC price volatility and agricultural residue competition. |
| Automated Fulfillment Equipment Deployment | Machine-vision sortation paired with box-on-demand systems captures retrofit contracts with mid-tier apparel distributors. |
| Extended Producer Responsibility Compliance | Citeo eco-modulation fee optimization creates margin arbitrage for designs above recycled content thresholds in France. |
| Curbside-Recyclable Material Qualification | REACH-compliant silicone-free coatings maintain single-material recyclability claims for frozen meal kit distributors. |
| Temperature-Controlled Format Expansion | Insulated box procurement scaling in Germany and France addresses online grocery fresh food last-mile distribution demand. |
Methodological Framework
The analysis maps corrugated fiberboard, flexible mailers, protective cushioning, and temperature-controlled formats, each validated through procurement directors at omnichannel retailers, plant managers at integrated paper mills, and sustainability officers at direct-to-consumer brands. Primary interviews with logistics providers operating automated sortation hubs and corrugated converters serving subscription box markets combined with secondary validation from EPA source reduction guidelines, EU Packaging and Packaging Waste Regulation filings, and SAMR GB standards documentation. Bottom-up volume modeling across delivery modes and top-down value triangulation against pulp production capacity data ensured cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material grade tier, end-user channel, and delivery speed segmentation dimensions. CAGRs were derived from parcel volume growth trajectories in live-stream commerce networks and recycled fiber cost curve analysis. Forecast inputs incorporated temperature-controlled fulfillment expansion rates and automated warehouse penetration curves without specifying baseline periods.
Decision-makers should treat outputs as directional under sustained e-commerce parcel volume growth and regulatory compliance timeline assumptions; material deviation in pulp energy costs or collection stream disruptions would warrant model refresh. Specific risk factors include municipal OCC collection interruptions, REACH substance restriction expansions, and SAMR reusable container mandate acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market