
 South Korea Automation and Industrial Control Market | 2026-2036
South Korea Automation and Industrial Control Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automation and Industrial Control Market Analytics
Small-to-mid-sized electronics subcontractors is redrawing procurement patterns across South Korea's automation landscape. LS Electric Co. Ltd. anchors domestic supply through its integrated PLC and servo portfolio. Mitsubishi Electric Corporation leverages its Korean subsidiary to localize motion control solutions for display panel makers. Doosan Robotics Inc. differentiates through collaborative robot platforms targeting precision assembly lines in Incheon and Suwon.
Automation and industrial control encompasses electromechanical systems, software platforms, and communication protocols that govern manufacturing processes through real-time sensing, logic execution, and actuator command with response latencies below ten milliseconds. These systems synchronize production lines, enforce quality tolerances, and enable remote diagnostics across distributed facilities. PLC and DCS hardware retains the largest installed base, while Industrial IoT and AI technology layers are expanding fastest as manufacturers overlay predictive analytics onto legacy SCADA architectures. Cloud Computing integration in HMI dashboards is shifting margin pools toward software subscription models and away from one-time controller sales.
METI-aligned Smart Factory certifications and KOSHA occupational safety mandates are elevating minimum performance thresholds for new installations, effectively filtering out uncertified component vendors. MFDS pharmaceutical manufacturing guidelines and Korea Electric Power Corporation grid standards further segment compliance requirements across end-user verticals. Stakeholders must weigh the capital efficiency of retrofitting existing DCS networks against greenfield deployments that natively embed AI-driven process optimization.
Market Dynamics
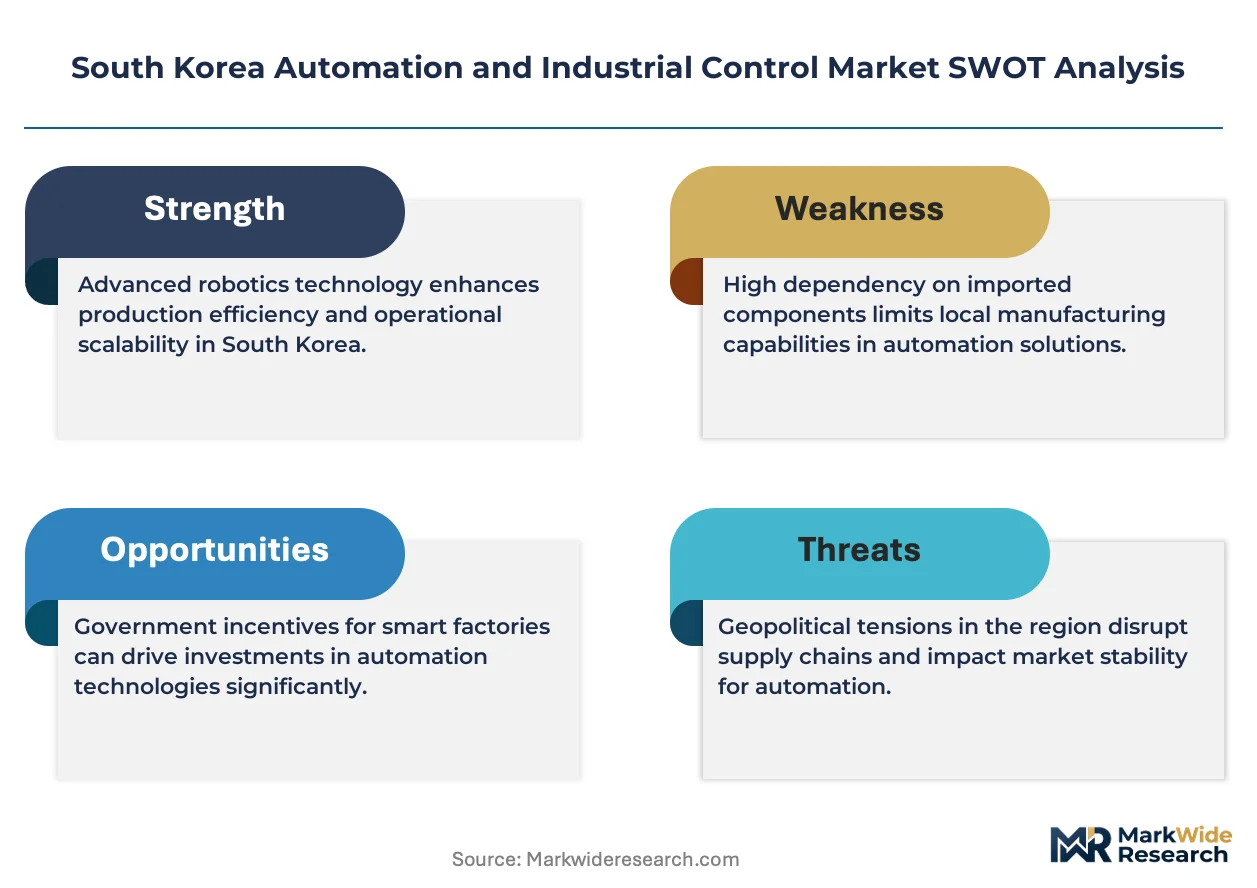
Smart Factory certifications under METI-aligned frameworks are compressing upgrade cycles across South Korean manufacturing, forcing suppliers to accelerate AI-native control architectures while legacy PLC networks face premature obsolescence.
Growth Catalysts
- KOSHA Occupational Safety Mandates:New machine-guarding and emergency-stop requirements are mandating sensor-rich retrofit installations across metalworking and automotive stamping facilities.
- Semiconductor Capital Expansion:Wafer fab construction in Yongin and Pyeongtaek is pulling vacuum-compatible motion controllers and ultra-precise temperature regulation systems at unprecedented scale.
- Industrial Edge Computing:Localized inference engines are reducing latency for quality inspection, enabling real-time defect rejection without cloud round-trips.
Market Restraints
- Specialized Servo Motor Concentration:High-torque precision motors for robotic arms concentrate among Japanese and German suppliers, exposing Korean system integrators to yen-euro volatility and allocation risk.
- Legacy DCS Lock-in:Petrochemical complexes in Ulsan and Yeosu run 1990s-era distributed control systems with proprietary communication protocols, creating technical debt that resists modular replacement.
- Substrate Material Cost Volatility:Rare-earth magnet prices for servo motors and silicon carbide substrates for power electronics swing with Chinese export quotas and mining output disruptions.
Strategic Opportunities
- Gwangju-Jeonnam Manufacturing Belt:Underinvested automotive parts and food processing clusters present greenfield deployment opportunities for integrated robot-vision-control packages.
- Pharmaceutical Batch Processing:MFDS guidelines for continuous manufacturing are creating demand for hybrid PLC-DCS platforms that bridge discrete and process automation.
- 5G-TSN Convergence:Time-sensitive networking over private 5G slices enables wireless deterministic control, opening mobile robot coordination and reconfigurable line architectures.
Industry Challenges
- Embedded AI Firmware Talent Scarcity:Control engineers with simultaneous expertise in real-time operating systems and neural network quantization remain exceptionally scarce in domestic labor pools.
- Multi-Protocol Integration Complexity:Facilities must bridge EtherCAT, Profinet, and CC-Link IE networks simultaneously, requiring gateway hardware that introduces jitter and diagnostic blind spots.
- KOSHA-MFDS Dual Certification Timelines:Safety and pharmaceutical validation processes run sequentially rather than in parallel, stretching commissioning schedules for hybrid manufacturing environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automation and Industrial Control Market |
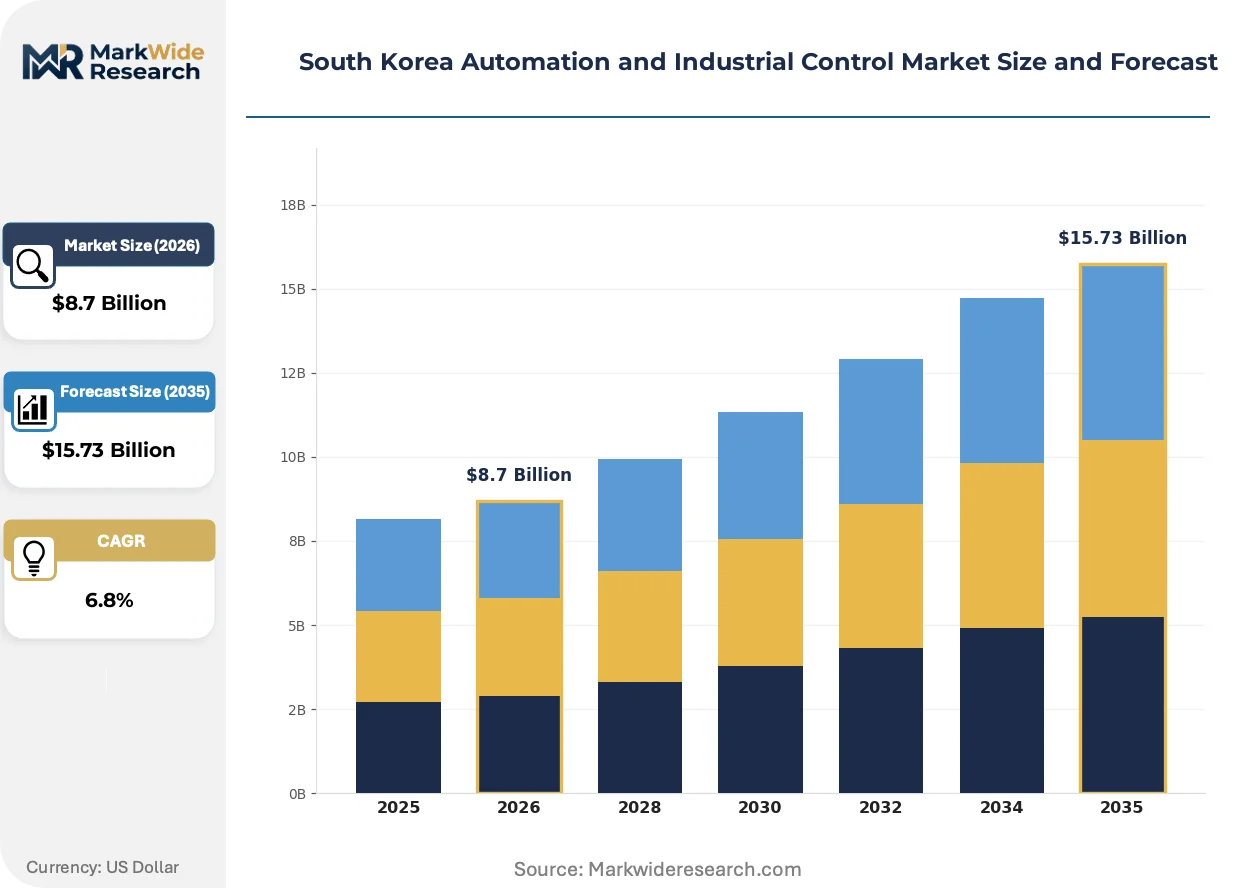
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, SCADA, HMI, DCS Technology: Industrial IoT, Cloud Computing, AI, Machine Learning End User: Manufacturing, Oil & Gas, Pharmaceuticals, Utilities Service Type: Consulting, Integration, Maintenance, Support |
| Companies Covered | Mitsubishi Electric Corporation (Mitsubishi Electric Automation Korea Co. Ltd.), Rockwell Automation Inc., LS Electric Co. Ltd., Yokogawa Electric Corporation, Omron Corporation (Omron Electronics Korea Co. Ltd.), ABB Ltd. (ABB Korea Co. Ltd.), Schneider Electric SE, Doosan Robotics Inc., Siemens AG (Siemens Korea), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automation and Industrial Control Market Evolving Landscape
Edge-native AI inference is displacing centralized SCADA analytics across Korean shop floors, while software-defined motion control and private 5G deterministic networking are rewriting hardware procurement patterns.
Embedded vision processors with integrated neural accelerators are miniaturizing defect detection from standalone PC-based stations to camera-mounted modules. Display panel manufacturers in Gyeonggi Province are adopting these units for micro-crack identification at bonding stages. The shift is miniaturizing inspection infrastructure and collapsing the traditional machine vision system integration value chain into component-level sales.
METI-aligned Smart Factory certification tiers now mandate documented cybersecurity hardening and functional safety validation for Level 3 and above ratings. Automotive tier-one suppliers in Asan and Hwaseong are restructuring supplier qualification questionnaires to prioritize certified control architectures. Battery cell manufacturers seeking export qualification are front-loading certification spending to avoid downstream audit failures.
System integrators in Incheon and Suwon are unbundling hardware supply from commissioning services, selling controller configurations as recurring software subscriptions with remote monitoring overlays. Electronics subcontractors with volatile order books prefer OpEx-based automation spending over capital-intensive ownership. The model concentrates margin with firmware-fluent integrators while commoditizing commodity PLC hardware.
South Korea Automation and Industrial Control Market Segmentation
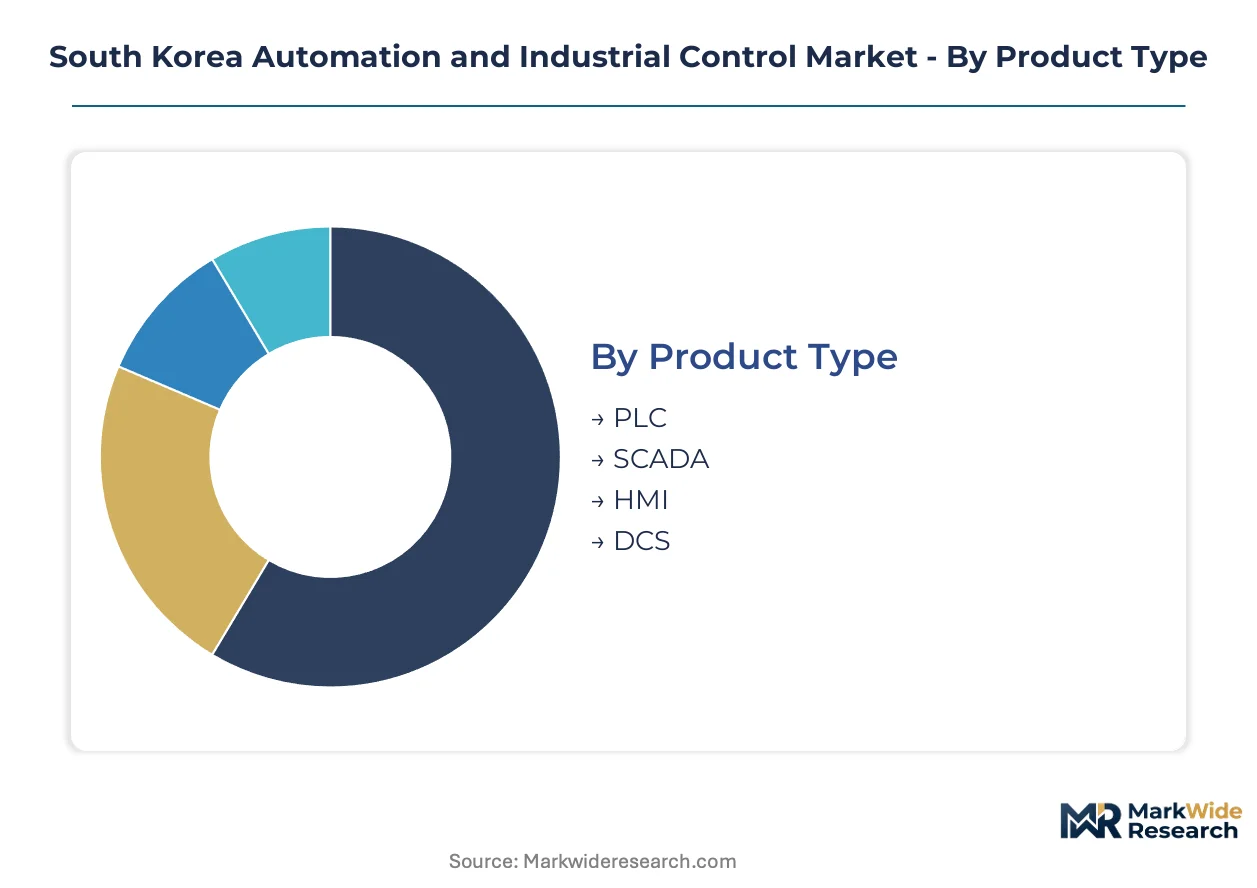
Segmentation in South Korea's automation market reflects divergent compliance burdens and capital intensity across industrial verticals. METI-aligned Smart Factory tiers and KOSHA safety mandates create non-uniform procurement specifications that reshape vendor qualification pathways.
Product Type:
KOSHA certification requirements and METI Smart Factory tier thresholds fragment hardware procurement by functional safety grade and cybersecurity hardening level.
- PLC:Programmable logic controllers with deterministic scan cycles below ten milliseconds anchor discrete manufacturing lines. Gyeonggi Province electronics subcontractors in Suwon and Incheon specify IEC 61131-3 compliant units with integrated safety I/O for KOSHA machine-guarding compliance.
- SCADA:Supervisory control and data acquisition platforms aggregate field-level telemetry into centralized historian databases. Ulsan petrochemical operators prioritize OPC UA-secured architectures to bridge legacy DCS islands while satisfying Korea Electric Power Corporation grid interconnection standards.
- HMI:Human-machine interface panels with HTML5 rendering engines enable remote diagnostics through tablet and smartphone endpoints.
- DCS:Distributed control systems govern continuous process loops in Yeosu chemical complexes with proprietary controller-to-I/O communication protocols.
PLC handles the majority of throughput; SCADA is expanding most quickly as facilities overlay analytics onto brownfield installations.
Technology:
Technology selection tracks the capital efficiency of retrofit deployment versus greenfield native integration, with subscription pricing models accelerating software-layer adoption.
- Industrial IoT:Sensor networks with MQTT and CoAP messaging protocols stream equipment health data to edge gateways. Display panel manufacturers in Gyeonggi Province deploy vibration and thermal monitoring arrays to predict vacuum pump failures before wafer contamination events.
- Cloud Computing:Scalable compute instances host digital twin simulations and cross-facility production optimization algorithms. Small-to-mid-sized automotive parts suppliers in the Gwangju-Jeonnam belt favor OpEx-based SaaS control configurations over on-premise server capital expenditure.
- AI:Neural network inference engines embedded in vision controllers enable real-time defect classification without cloud round-trip latency.
- Machine Learning:Predictive maintenance models trained on historical failure patterns reduce unplanned downtime in semiconductor etching equipment.
Industrial IoT carries the largest installed base; Cloud Computing is climbing the fastest as integrators unbundle hardware from recurring software subscriptions.
End User:
End-user segmentation maps directly to regulatory jurisdiction, with MFDS pharmaceutical mandates, KOSHA industrial safety rules, and Korea Electric Power Corporation grid standards creating distinct procurement specifications.
- Manufacturing:Discrete assembly operations spanning electronics, automotive, and food processing verticals. Smart Factory certification pressure in Asan and Hwaseong automotive clusters accelerates AI-native control architecture replacement of legacy relay logic systems.
- Oil & Gas:Refining and petrochemical continuous processes with explosion-proof instrumentation requirements. Ulsan and Yeosu complexes face technical debt from 1990s-era proprietary DCS networks that resist modular incremental upgrade.
- Pharmaceuticals:Batch and continuous drug manufacturing governed by MFDS validation protocols. Yongin biologics facilities specify hybrid PLC-DCS platforms that bridge discrete unit operations with process analytical technology integration.
- Utilities:Power generation and distribution infrastructure with Korea Electric Power Corporation interoperability mandates.
Manufacturing dominates absolute spend; Pharmaceuticals is gaining share fastest as continuous manufacturing adoption compresses batch cycle economics.
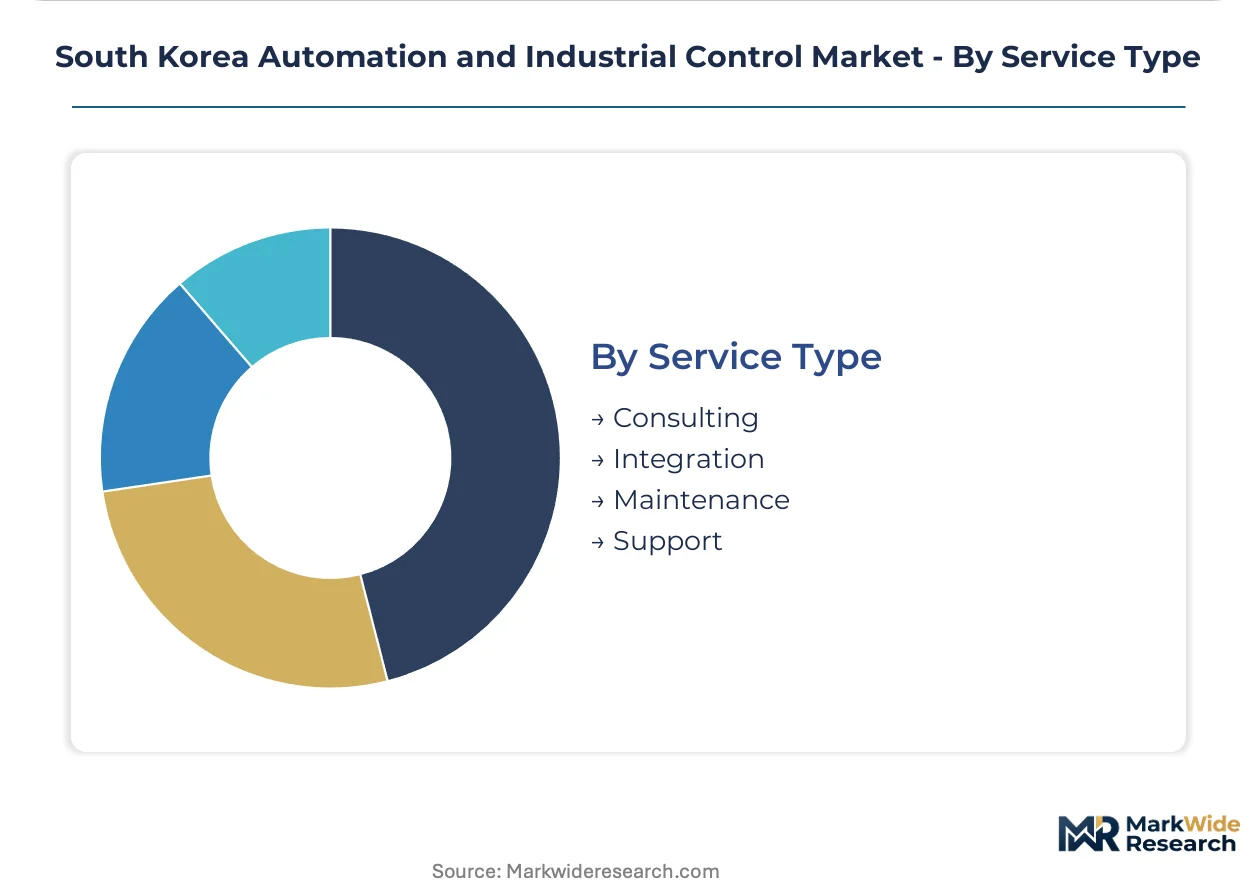
Service Type:
Service procurement patterns reflect the scarcity of embedded AI firmware talent and the complexity of multi-protocol integration across heterogeneous legacy networks.
- Consulting:Front-end engineering studies for Smart Factory certification pathway design and cybersecurity hardening roadmaps. System integrators in Incheon structure certification spending to front-load METI Level 3 documentation before construction milestones.
- Integration:Field deployment of controller hardware, network commissioning, and HMI configuration. Gyeonggi Province display panel projects require simultaneous EtherCAT, Profinet, and CC-Link IE gateway deployment to bridge Japanese, German, and Korean equipment fleets.
- Maintenance:Preventive service contracts with remote monitoring overlays and spare parts logistics.
- Support:Help desk and firmware update services for software-defined control architectures.
Integration commands the largest project value; Consulting is expanding most quickly as certification complexity outpaces in-house engineering capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese automation suppliers route precision motion controllers through Busan port to serve Gyeonggi Province display panel fabs, while German engineering houses anchor petrochemical DCS deployments across Ulsan and Yeosu complexes.
Seoul Capital Area
Semiconductor equipment builders in Yongin and Pyeongtaek specify vacuum-compatible servo drives and sub-millisecond PLCs for wafer handling robotics. METI-aligned Smart Factory Level 3 certifications now mandate cybersecurity hardening for these installations. Samsung and SK Hynix captive suppliers in Suwon compress upgrade cycles to match fab expansion timelines.
Busan-Ulsan Corridor
Petrochemical continuous processes in Ulsan demand explosion-proof DCS architectures with proprietary controller protocols from the 1990s. Korea Electric Power Corporation grid interconnection standards force concurrent telemetry upgrades. Yeosu chemical complexes face technical debt from legacy distributed control islands that resist modular replacement.
Daegu-Gyeongbuk
Automotive stamping and metalworking facilities absorb KOSHA-mandated machine-guarding retrofits with safety-integrated PLC systems. Daegu machinery builders source high-torque servo motors from Japanese and German suppliers, exposing procurement to yen-euro volatility. Local system integrators specialize in bridging EtherCAT and CC-Link IE protocol mismatches.
Daejeon-Sejong
Public research institutes and government-funded pilot factories test 5G-TSN convergent control architectures for mobile robot coordination. Sejong smart city infrastructure provides testbeds for private 5G deterministic networking. MFDS pharmaceutical guidelines drive hybrid PLC-DCS platform validation for continuous manufacturing research.
Gwangju-Honam
Underinvested automotive parts and food processing clusters present greenfield deployment opportunities for integrated robot-vision packages. Gwangju-based SMEs prefer OpEx-based automation subscriptions over capital-intensive ownership. The region lags in METI certification penetration, creating first-mover advantages for certified system integrators.
South Korea Automation and Industrial Control Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and firmware subscription models. The vendor base stratifies between diversified electrical conglomerates with captive semiconductor demand and focused robotics pure-plays targeting collaborative assembly. Three archetypes dominate: integrated PLC-servo houses, motion control localization subsidiaries, and collaborative robot specialists. Competitive intensity centers on Smart Factory certification pre-qualification and unbundled hardware-from-software service contracts.
Within the domestic integrated tier, LS Electric Co. Ltd. anchors Korean supply through its captive electrical equipment heritage, while Doosan Robotics Inc. exemplifies the collaborative automation pure-play archetype with precision assembly positioning. Mitsubishi Electric Corporation occupies a position representing Japanese engineering localization through its Korean subsidiary structure. These three entities collectively illustrate the market's segmentation between diversified industrial electrics and focused robotics specialization.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation (Mitsubishi Electric Automation Korea Co. Ltd.) |
| Rockwell Automation Inc. |
| LS Electric Co. Ltd. |
| Yokogawa Electric Corporation |
| Omron Corporation (Omron Electronics Korea Co. Ltd.) |
| ABB Ltd. (ABB Korea Co. Ltd.) |
| Schneider Electric SE |
| Doosan Robotics Inc. |
| Siemens AG (Siemens Korea) |
| Others |
Value Network & Pricing Analysis
Wafer fab capacity utilization above ninety percent in Yongin and Pyeongtaek compresses component lead times and elevates price floors for vacuum-compatible motion controllers. This scale concentration grants Japanese and German servo motor suppliers outsized pricing power while Korean system integrators absorb yen-euro volatility.
Pricing Analysis
Next-generation AI-native PLCs command thirty-to-fifty percent premiums over IEC 61131-3 baseline units, while legacy relay-logic systems trade at distressed clearance levels. Three-tier pricing structure across METI Level 3 certified, KOSHA-compliant, and uncertified hardware tiers reflects cybersecurity hardening and functional safety validation costs. Cost compression in standard-grade PLCs is intensifying because Chinese suppliers are flooding Southeast Asian export channels. Small-to-mid-sized electronics subcontractors in Gyeonggi Province exhibit highest price sensitivity, whereas semiconductor captive suppliers prioritize specification compliance over unit economics.
Supply Chain Analysis
Japan and Germany anchor high-torque precision servo motor production, while China dominates rare-earth magnet refining and silicon carbide substrate growth. Korean system integrators draw from Japanese motion control subsidiaries in Busan and German engineering houses serving Ulsan petrochemical complexes. Single-source vulnerability concentrates in neodymium-dysprosium magnet alloys subject to Chinese export quota volatility. Distribution runs through authorized distributor networks with certified integrator partnerships rather than direct OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's automation market is crossing a platform-economics inflection as METI Smart Factory certification tiers create interoperability standards that privilege ecosystem-embedded vendors over standalone hardware suppliers.
For Market Incumbents: Compound firmware subscription attach rates by unbundling hardware supply from remote monitoring services, mirroring the shift already visible among Incheon and Suwon integrators. Deepen backward integration into safety-integrated I/O modules to offset Japanese servo motor pricing power. Prioritize KOSHA-MFDS dual certification pre-validation to compress commissioning timelines for pharmaceutical hybrid manufacturing environments. For New Entrants and Emerging Players: METI Level 3 fast-track certification offers entry pathway into Asan and Hwaseong automotive tier-one supplier networks currently restructuring qualification questionnaires. Target Gwangju-Jeonnam manufacturing belt for greenfield robot-vision-control packages where certification penetration lags and OpEx-based subscription models face less incumbent saturation. Lead with 5G-TSN convergent architectures for mobile robot coordination to differentiate from legacy EtherCAT-Profinet gateway solutions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among system integrators with firmware-fluent engineering teams and METI certification documentation libraries. Long-term viability favors acquisition targets with hybrid PLC-DCS platform capabilities bridging discrete and process automation verticals. Watch for inflection when pharmaceutical continuous manufacturing adoption accelerates MFDS-guided hybrid platform procurement beyond current batch processing dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unbundled hardware-from-software subscriptions concentrate margin with firmware-fluent integrators serving volatile-order electronics subcontractors. |
| Certification Investment | METI Level 3 cybersecurity hardening and KOSHA functional safety validation filter uncertified vendors from Samsung and SK Hynix captive supplier networks. |
| Backward Integration | In-house production of safety-integrated I/O modules reduces exposure to yen-euro volatility in Japanese and German servo motor procurement. |
| Geographic Expansion | Gwangju-Jeonnam belt presents first-mover advantages for certified integrators where METI penetration lags and SMEs prefer OpEx automation spending. |
| Strategic Partnership | 5G-TSN convergent architectures with private network operators enable wireless deterministic control for mobile robot coordination in reconfigurable lines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, system integrators, and aftermarket service heads across Seoul Capital Area and Busan-Ulsan Corridor; and secondary validation through customs trade data, Korea Electric Power Corporation grid interconnection filings, METI Smart Factory certification registries, and SEC 10-K disclosures from listed automation suppliers. Bottom-up segment sizing triangulated against top-down industry association estimates.
Across the analysis window, the forecasting framework modeled product type segmentation by functional safety grade, technology adoption by retrofit versus greenfield capital efficiency, and end-user verticals by regulatory jurisdiction overlap. CAGRs derived from installed base turnover rates, fab expansion timelines, and certification mandate compliance deadlines. Semiconductor capital expenditure cycles and rare-earth magnet price volatility curves served as industry-specific sensitivity inputs.
Decision-makers should treat outputs as directional under assumptions of continued METI certification tier escalation and stable Korea-China rare-earth trade flows; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in KOSHA regulatory enforcement intensity and MFDS pharmaceutical manufacturing guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Drilling Automation Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
UV Curing System Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Industrial Embedded Systems Market