
 Europe Warehouse Management Systems Market | 2026-2036
Europe Warehouse Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Warehouse Management Systems Market Insights
E-commerce fulfillment is rebalancing the end-user mix as retailers and third-party logistics providers replace legacy installations. SAP SE leverages its S/4HANA backbone to anchor enterprise-grade deployments across German and Benelux distribution hubs. Manhattan Associates Inc competes through specialized warehouse execution layers that optimize labor orchestration in high-velocity environments. Oracle Corp extends its cloud infrastructure to sustain hybrid architectures bridging on-premise material handling with centralized analytics.
Europe Warehouse Management Systems comprise software platforms that coordinate inventory tracking, labor allocation, equipment scheduling, and order fulfillment through real-time data exchange with automated material handling systems. These systems typically process transaction volumes exceeding 10,000 stock-keeping unit movements per hour while maintaining 99.9% inventory accuracy thresholds for pharmaceutical and food-grade operations. Cloud-based deployments now lead new installations as operators prioritize elastic capacity during seasonal demand spikes, while on-premise installations retain dominance among defense and classified-goods facilities with air-gapped security requirements. RFID and IoT integrations represent the fastest-expanding technology pairing, though barcode scanning still occupies the largest installed base across mid-market European third-party logistics providers.
REACH compliance and the EU AI Act shape platform development by mandating algorithmic transparency for automated picking decisions and chemical traceability in battery and hazardous-goods warehousing. Germany's Supply Chain Due Diligence Act further compels warehouse operators to document labor conditions and environmental impacts within their software audit trails. Stakeholders must evaluate how forthcoming CSRD reporting obligations will force WMS vendors to embed emissions tracking directly into inventory lifecycle modules rather than relying on bolt-on sustainability tools.
Market Dynamics
Cloud-native WMS architectures are compressing deployment cycles from 18-month waterfall implementations to 8-week agile rollouts, forcing incumbent vendors to restructure professional services revenue models around subscription retention rather than perpetual license margins.
Growth Catalysts
- EU AI Act compliance mandates:Automated picking algorithms in German and Dutch distribution centers now require documented decision audit trails, accelerating replacement of opaque legacy rule engines with explainable AI modules.
- Battery warehouse traceability:REACH chemical registration obligations for lithium-ion storage are driving RFID-integrated WMS upgrades across Polish and Hungarian e-fulfillment hubs handling electronics.
- Same-day delivery density:Urban micro-fulfillment networks in Paris, Madrid, and Milan require elastic cloud capacity that on-premise systems cannot provision, pulling SaaS WMS adoption into mid-market 3PLs.
Market Restraints
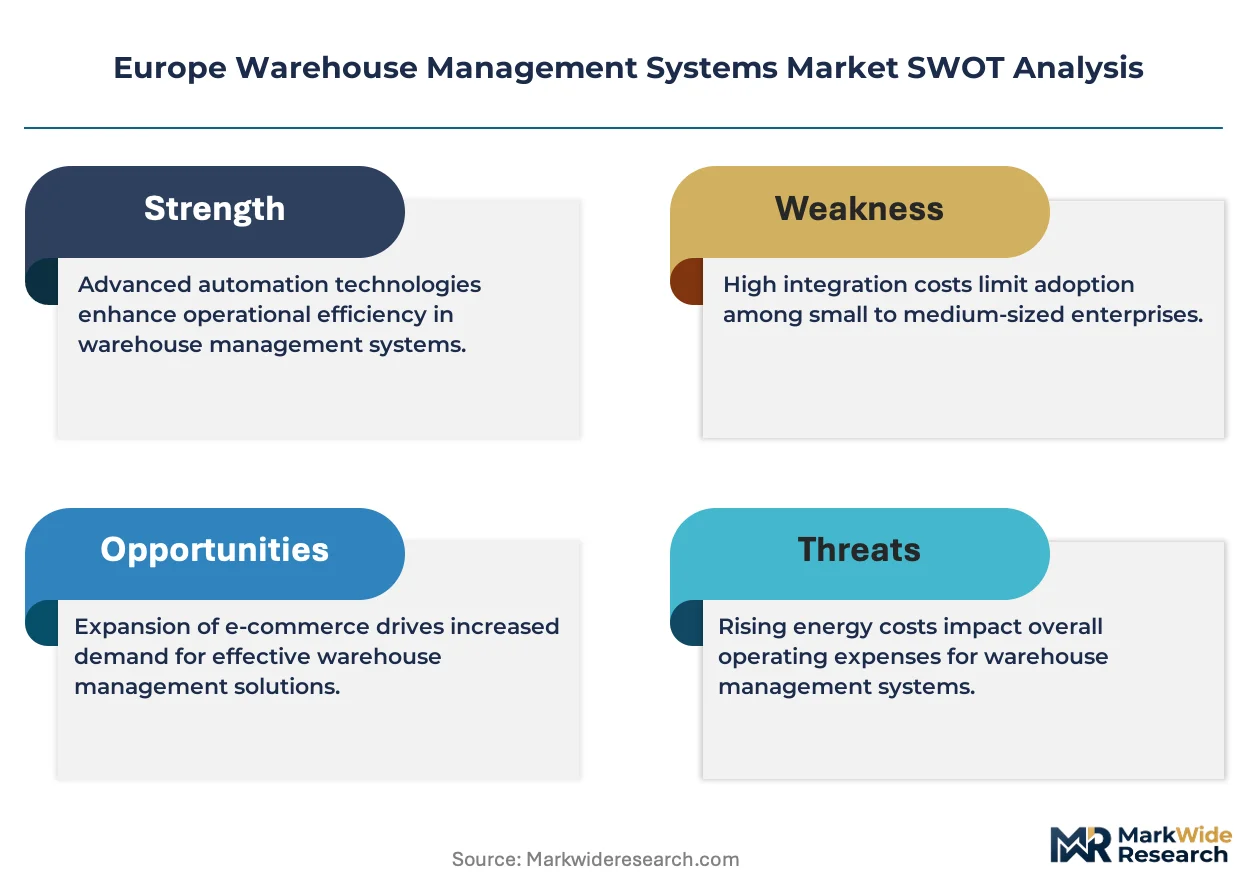
- Specialized integration talent scarcity:SAP EWM and Manhattan WMo certification holders command 40% salary premiums in the DACH labor market, inflating total cost of ownership for complex multi-site deployments.
- Air-gapped security requirements:Defense and aerospace warehousing in France and the UK retains on-premise mandates that block cloud migration, fragmenting vendor R&D investment across dual architecture tracks.
- Interoperability protocol fragmentation:VDA 5050, MassRobotics, and proprietary AGV command languages create integration bottlenecks that extend commissioning timelines for automated facilities.
Strategic Opportunities
- CSRD emissions tracking integration:Upcoming corporate sustainability reporting obligations will force WMS vendors to embed Scope 3 carbon accounting directly into inventory lifecycle modules rather than bolt-on tools.
- Port-centric 4PL convergence:Rotterdam and Antwerp logistics clusters are consolidating control tower functions, creating demand for WMS platforms that federate multi-operator yard, warehouse, and vessel scheduling.
- Pharmaceutical serialization depth:EMA Falsified Medicines Directive enforcement is expanding from finished goods to active ingredient storage, opening specialized cold-chain WMS segments in Ireland and Switzerland.
Industry Challenges
- Legacy ERP entanglement:Brownfield facilities running SAP ECC 6.0 face S/4HANA migration timelines that conflict with WMS cloud roadmaps, forcing parallel integration layer investments.
- Cyber-physical attack surface expansion:IoT sensor density in automated warehouses multiplies ransomware entry points, requiring security operations center capabilities that 3PLs lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Warehouse Management Systems Market |
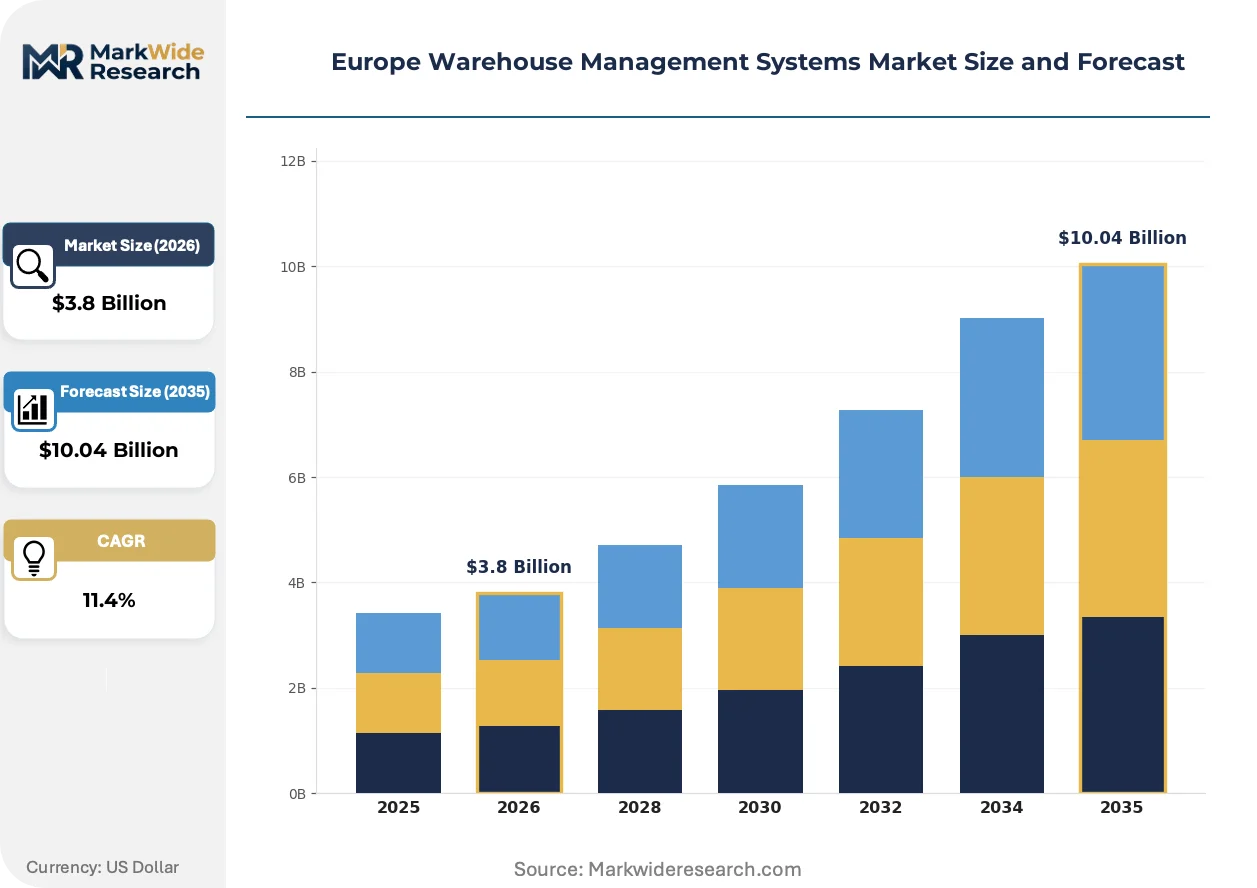
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, SaaS End User: Retail, E-commerce, Manufacturing, Healthcare Deployment: Warehouse, Distribution Center, Third-party Logistics, Freight Technology: RFID, Barcode Scanning, IoT, AI |
| Companies Covered | SAP SE, Infor, Manhattan Associates Inc, Oracle Corp, Korber AG, PSI Logistics GmbH, Epicor Software, Consafe Logistics, Reply SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Warehouse Management Systems Market Trends and Innovations
Edge computing architectures are redistributing computational load away from centralized cloud instances, enabling millisecond-latency equipment coordination that batch-processed WMS cores cannot sustain.
Digital twin simulation is decentralizing warehouse design validation by enabling 3D facility modeling on commodity hardware rather than licensed CAE workstations. Retailers in the Benelux region are adopting these tools to test seasonal layout reconfigurations before physical moves. The technology compresses capital deployment risk by identifying throughput bottlenecks during simulation rather than post-commissioning.
The EU AI Act's risk classification framework is forcing algorithmic transparency into warehouse automation procurement specifications. High-risk automated picking systems must now demonstrate human oversight capabilities and bias testing documentation before deployment. Pharmaceutical distributors in Germany and Denmark are leading compliance investment, creating specification templates that cascade into adjacent food-grade and electronics verticals.
Outcome-based contracting is displacing traditional software license transactions in third-party logistics relationships. Major retailers in France and Spain now negotiate WMS engagements against guaranteed order accuracy and labor productivity thresholds rather than feature checklists. This shifts vendor compensation toward operational performance metrics and accelerates vendor investment in predictive analytics capabilities that demonstrate measurable warehouse efficiency gains.
Europe Warehouse Management Systems Market Segmentation
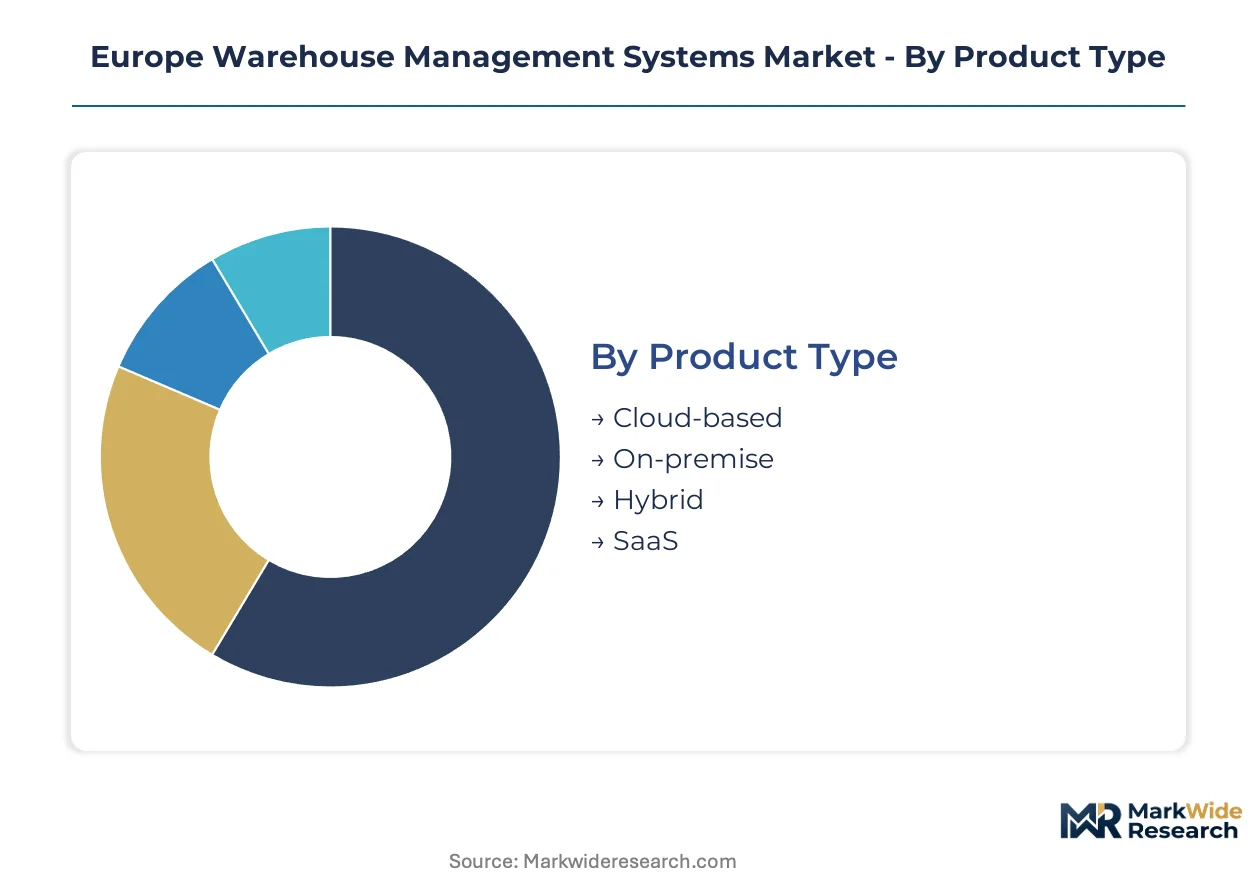
Warehouse Management Systems in Europe exhibit divergent technology maturities and compliance burdens across deployment modes. Cloud-native platforms face distinct integration challenges versus legacy on-premise estates, while end-user verticals impose sector-specific traceability mandates under REACH and the EU AI Act.
Product Type:
Supply concentration in German and Benelux distribution hubs favors platforms with rapid deployment elasticity and subscription-based commercial terms.
- Cloud-based:Multi-tenant architectures provision computational resources across federated warehouse networks without capital-intensive infrastructure. French and Spanish retailers driving same-day delivery density favor these platforms for seasonal capacity spikes.
- On-premise:Perpetual-license software running on operator-owned hardware dominates defense and aerospace warehousing in France and the UK, where air-gapped security mandates block external connectivity. Legacy SAP ECC 6.0 integrations complicate migration timelines.
- Hybrid:Split architectures bridge edge computing for equipment coordination with centralized analytics, serving brownfield facilities transitioning from perpetual licenses.
- SaaS:Subscription-native platforms compress implementation cycles to eight-week agile rollouts, displacing traditional professional services revenue models among mid-market 3PLs.
On-premise installations absorb the bulk of installed capacity; SaaS deployments are expanding most quickly.
End User:
Cost tier differentiation separates high-compliance pharmaceutical operations from volume-driven retail fulfillment networks.
- Retail:Seasonal demand volatility and micro-fulfillment expansion in Paris, Madrid, and Milan pull elastic cloud capacity into urban logistics networks. Outcome-based contracting now ties vendor compensation to order accuracy thresholds.
- E-commerce:High-velocity order profiles exceeding 10,000 SKU movements per hour demand specialized warehouse execution layers with labor orchestration capabilities. Polish and Hungarian electronics hubs drive RFID-integrated upgrades for battery traceability.
- Manufacturing:Production-integrated inventory modules synchronize raw material flows with assembly schedules, prevalent in German automotive supply clusters.
- Healthcare:EMA Falsified Medicines Directive enforcement mandates serialization depth from finished goods through active ingredient storage, opening specialized cold-chain segments in Ireland and Switzerland.
Retail commands the largest addressable spend; healthcare is climbing the fastest on compliance investment.
Deployment:
Volume concentration in port-centric logistics clusters shapes platform requirements for multi-operator coordination.
- Warehouse:Standalone facilities with dedicated WMS instances remain prevalent among single-site operators in Southern Europe.
- Distribution Center:High-throughput nodes in Duisburg and Hamburg anchor enterprise-grade SAP S/4HANA deployments with real-time equipment scheduling.
- Third-party Logistics:Multi-tenant platforms serving fragmented shipper bases prioritize rapid onboarding and cross-customer inventory segregation. Certification scarcity for SAP EWM and Manhattan WMo inflates ownership costs.
- Freight:Yard and vessel scheduling integration at Rotterdam and Antwerp creates demand for federated control tower functions spanning warehouse and maritime operations.
Third-party logistics absorbs the dominant share of new platform investment; freight-linked deployments are gaining share fastest.
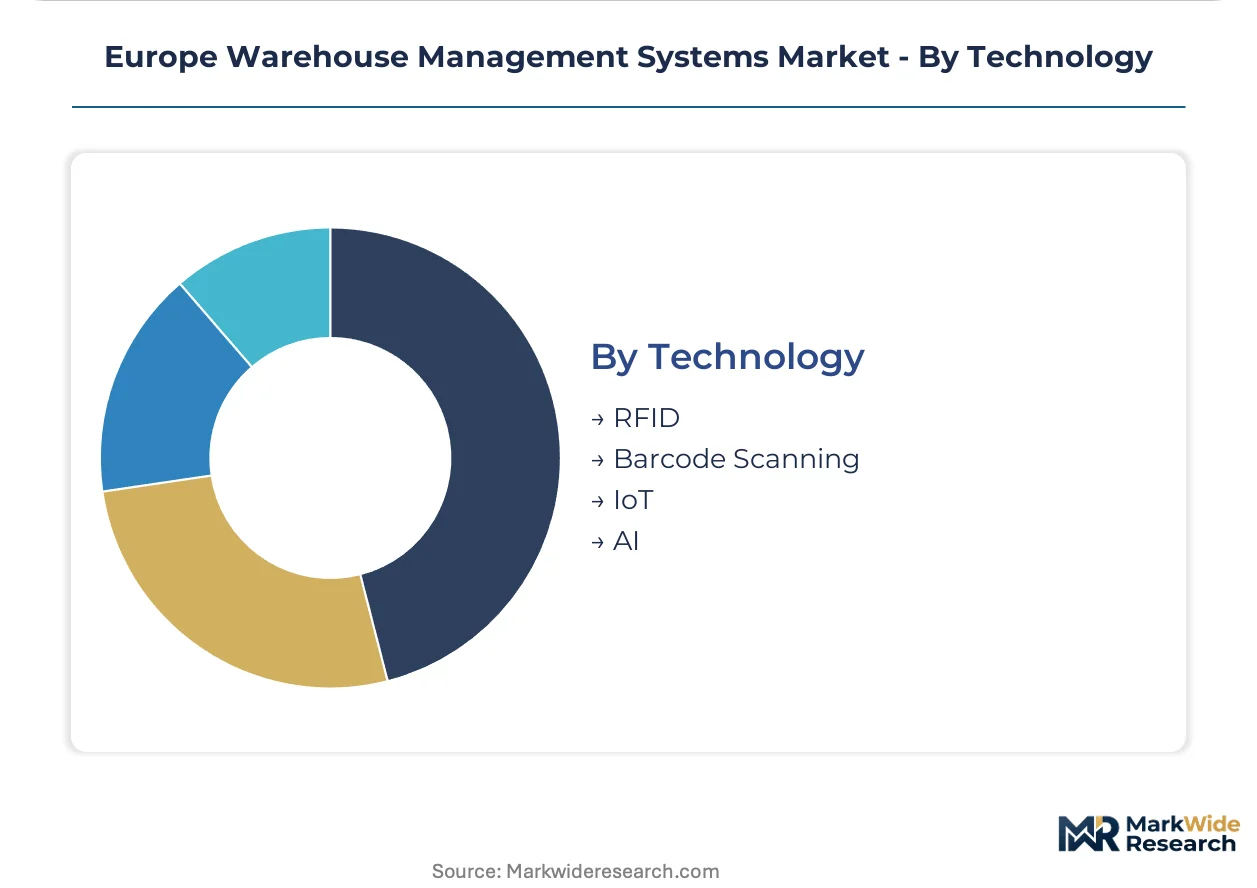
Technology:
Margin structure varies sharply between mature barcode infrastructure and emerging AI compliance modules.
- RFID:Passive and active radio-frequency identification enables non-line-of-sight inventory tracking for lithium-ion battery warehousing under REACH chemical registration obligations. Fastest-expanding technology pairing with IoT sensors.
- Barcode Scanning:Linear and 2D symbology systems retain the largest installed base across mid-market European 3PLs due to low capital requirements and established integration protocols.
- IoT:Dense sensor networks multiply ransomware entry points, requiring security operations capabilities that 3PLs increasingly outsource. Edge computing redistributes computational load for millisecond-latency coordination.
- AI:Automated picking algorithms now require documented decision audit trails under the EU AI Act's risk classification framework, forcing replacement of opaque rule engines with explainable modules in German and Dutch facilities.
Barcode scanning retains the largest installed base; AI modules are expanding most quickly on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the Netherlands and Belgium concentrate WMS investment through port-centric logistics incentives that reduce customs friction for transshipment operations. German Zollverein bonded warehouse status accelerates platform upgrades in Rhine-Ruhr distribution clusters.
Germany
Automotive supply chain digitization and pharmaceutical serialization mandates drive enterprise WMS refresh cycles. The Supply Chain Due Diligence Act compels labor-condition documentation in software audit trails. Duisburg and Hamburg anchor SAP S/4HANA deployments with real-time equipment scheduling across multi-site distribution networks.
Netherlands
Rotterdam port automation and e-commerce fulfillment density pull cloud-native platforms into 3PL networks. REACH chemical traceability requirements for lithium-ion battery storage accelerate RFID-integrated upgrades. The Randstad logistics corridor concentrates multi-tenant SaaS deployments serving fragmented shipper bases.
France
Defense and aerospace warehousing mandates air-gapped security requirements that block cloud migration for sensitive facilities. ANSM pharmaceutical traceability enforcement expands serialization depth to active ingredient storage. Paris micro-fulfillment networks demand elastic capacity for same-day delivery density.
United Kingdom
Post-Brexit customs complexity drives demand for WMS platforms with integrated duty-deferment and origin-certificate tracking. MHRA pharmaceutical serialization rules align with EMA directives for cross-border compliance. Midlands distribution clusters prioritize hybrid architectures bridging legacy ERP with cloud analytics.
Poland
Electronics manufacturing and battery warehouse expansion concentrate in Polish e-fulfillment hubs serving Central European markets. EU AI Act risk classifications for automated picking systems accelerate explainable AI module procurement. Warsaw and Krakow logistics zones attract 3PL investment with lower labor costs than Western European alternatives.
Europe Warehouse Management Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise-grade ERP-integrated platforms commanding premium positioning against modular best-of-breed alternatives. The vendor landscape organizes into three tiers: S/4HANA backbone providers, specialized warehouse execution layer developers, and cloud-native SaaS entrants. Consolidation pressure intensifies as agile deployment cycles compress professional services margins. M&A activity targets vertical-specific compliance modules, while strategic partnerships bridge interoperability gaps between AGV command protocols.
Among German-headquartered enterprise software groups, SAP SE and Korber AG exemplify divergent architectural philosophies—one leveraging ERP backbone dominance, the other specializing in modular warehouse execution. Manhattan Associates Inc represents the North American specialist archetype competing through labor orchestration capabilities. PSI Logistics GmbH occupies a position within the mid-market DACH-focused tier, while Oracle Corp anchors cloud infrastructure plays for hybrid deployment scenarios.
| Leading Market Players |
|---|
| SAP SE |
| Infor |
| Manhattan Associates Inc |
| Oracle Corp |
| Korber AG |
| PSI Logistics GmbH |
| Epicor Software |
| Consafe Logistics |
| Reply SpA |
| Others |
Pricing and Supply Chain Analysis
Mid-market third-party logistics providers in Poland and Hungary anchor volume procurement, compressing SaaS WMS pricing toward subscription tiers that sacrifice customization depth for rapid deployment velocity. Their procurement concentration forces vendors to absorb integration complexity into standard license fees rather than bill professional services separately.
Pricing Analysis
Short lead-time premiums dominate enterprise procurement in German automotive clusters, where SAP S/4HANA deployments command 40% cost escalation over standard timelines due to certified integration specialist scarcity. Three-tier pricing structure across premium, standard, and economy levels stratifies by deployment complexity and regulatory module depth. Pricing pressure stems from agile eight-week rollout benchmarks that erode perpetual-license margins. Mid-market 3PLs exhibit highest price sensitivity; pharmaceutical distributors under EMA serialization mandates show lowest.
Supply Chain Analysis
Edge computing hardware supply rests on Taiwanese semiconductor foundries and German industrial automation component manufacturers, with cloud infrastructure provisioning anchored in Irish and Dutch hyperscaler regions. Critical dependencies include ARM-based processors, industrial Ethernet switches, and lithium-ion sensor power systems. Single-source vulnerability concentrates in specialized RFID tag production for REACH-compliant battery traceability. Distribution runs through systems integrators in the DACH corridor who bundle software with material handling equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native deployment acceleration functions as a consolidation mechanism, eliminating vendors lacking subscription-retention economics and agile implementation capabilities. Compressed professional services margins force weaker players toward acquisition or exit.
For Market Incumbents: Lock in multi-year SaaS retention through embedded CSRD emissions tracking modules that raise switching costs ahead of regulatory deadlines. Acquire specialized warehouse execution layer developers in the Benelux corridor to close labor orchestration gaps against Manhattan Associates' positioning. SAP SE and Oracle Corp face emerging cloud-native entrants exploiting eight-week deployment benchmarks; vertical integration into edge computing hardware partnerships defends against disintermediation. For New Entrants and Emerging Players: Cloud-native SaaS platforms targeting Polish and Hungarian electronics fulfillment hubs offer the most penetrable white-space, where REACH battery traceability mandates outpace legacy vendor upgrade cycles. Outcome-based contracting against guaranteed order accuracy thresholds opens retail relationships in France and Spain without incumbent professional services entanglement. Prioritize RFID-IoT integration bundles that compress commissioning timelines below incumbent eighteen-month baselines. For Investors and Strategic Acquirers: The window for entry favors vertical-specific compliance module developers with EU AI Act audit-trail capabilities and pharmaceutical cold-chain serialization depth. Long-term viability centers on vendors embedding sustainability accounting directly into inventory lifecycle modules rather than bolt-on architectures. Watch CSRD enforcement timing as the inflection indicator for accelerated platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Vertical compliance modules for EU AI Act audit trails accelerate pharmaceutical and food-grade certification. |
| Platform Integration | Federated control tower architectures at Rotterdam and Antwerp port clusters capture 4PL convergence demand. |
| Strategic Partnership | Edge computing hardware alliances with Taiwanese semiconductor suppliers reduce millisecond-latency equipment coordination costs. |
| Product Launch | Explainable AI picking modules with documented decision trails preempt German and Dutch regulatory procurement specifications. |
| Geographic Expansion | Warsaw and Krakow logistics zone presence exploits lower labor costs than Western European 3PL alternatives. |
Research Methodology
Independent corroboration across WMS vendor product management, third-party logistics operations directors, and systems integration specialists underwrites the qualitative findings. Secondary validation draws from EU regulatory filings, hyperscaler infrastructure capex disclosures, and customs data on material handling equipment imports. Bottom-up deployment volume estimates triangulate against top-down enterprise software spend benchmarks across German, Dutch, and French distribution clusters.
Rate-of-change decomposition separates cloud-native adoption velocity from legacy on-premise replacement cycles across the analysis window. Segmentation dimensions span deployment architecture, end-user vertical, integration complexity tier, and regional regulatory cluster. CAGRs derive from equipment procurement pipelines, professional services hiring patterns, and SaaS booking disclosures. Pharmaceutical serialization depth and battery warehouse traceability mandates serve as industry-specific demand accelerators in the forecasting framework.
Inputs from vendor financial disclosures and logistics operator procurement databases were available through the study window; gaps in private 3PL contract terms introduce uncertainty bands around outcome-based pricing penetration estimates. Forecasts reflect documented assumptions on EU AI Act enforcement timing and CSRD reporting phase-in schedules. Regulatory delay or accelerated compliance deadlines would revise trajectory. A small set of named triggers—CSRD module adoption rates, VDA 5050 protocol standardization progress, and DACH certification specialist wage inflation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
United States Managed Services Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Enterprise Collaboration Service Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Shared Services Market