
 UK Industrial Automation System Integrator Market | 2026-2036
UK Industrial Automation System Integrator Market Size, Share, and Industry Trends Forecast 2026-2036
UK Industrial Automation System Integrator Market Insights
Multi-source outsourcing of automation integration is expanding across UK manufacturing as facility managers seek specialized expertise unavailable in-house. Wood PLC leverages deep project engineering capabilities to anchor large-scale process automation contracts across energy and pharmaceutical sites. Jacobs U.K. Limited sustains competitive positioning through R&D-intensive digital twin and advanced process control solutions. Siemens Mobility Limited dominates rail and transport automation integration, extending its technology leadership into adjacent industrial verticals.
A UK industrial automation system integrator designs, commissions, and maintains interconnected control architectures comprising programmable logic controllers, distributed control systems, and supervisory data acquisition platforms with millisecond-level process loop response requirements. These integrators engineer human-machine interface layers and robotic workcells to synchronize material flow, quality inspection, and energy consumption across continuous and batch manufacturing operations. Control systems and SCADA deployments capture the largest margin pools among product type segments, reflecting long-term service attach rates and software licensing renewals. Process automation applications lead volume demand from pharmaceutical and oil and gas end users, while robotic process automation exhibits the fastest structural growth as labour-constrained food and beverage producers retrofit packaging and palletising lines.
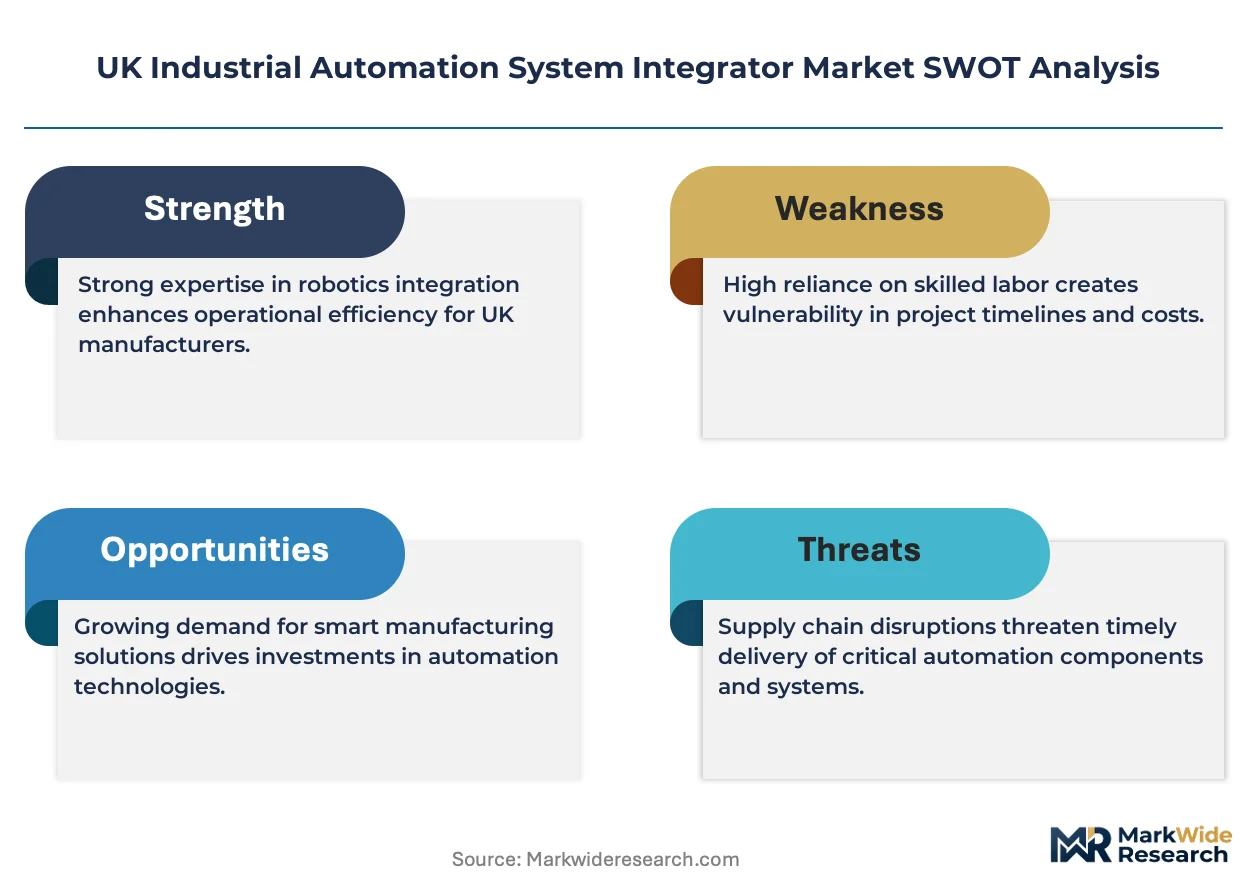
The Health and Safety Executive enforces Control of Major Accident Hazards regulations that mandate certified safety instrumented systems in chemical and pharmaceutical facilities, directly shaping integrator competency requirements and project scopes. BSI standards for functional safety and cybersecurity certification create compliance-driven demand for accredited system integrators serving critical infrastructure operators. Stakeholders must monitor evolving UKCA marking transitions and carbon reporting obligations under the Streamlined Energy and Carbon Reporting framework to anticipate procurement specification changes.
Market Dynamics
The UK's Net Zero Strategy and HSE process safety directives are forcing pharmaceutical and chemical facilities to modernize legacy control architectures, creating sustained demand for certified system integrators capable of safety instrumented system deployment.
Growth Catalysts
- COMAH Regulations:The Health and Safety Executive mandates certified safety instrumented systems in chemical and pharmaceutical facilities, expanding project scopes for accredited integrators.
- Food and Beverage Modernization:Labour-constrained producers across Greater Manchester and Yorkshire are retrofitting packaging and palletising lines with robotic process automation.
- Midlands Pharmaceutical Cluster:Outsourced automation integration projects are accelerating across Nottinghamshire and Derbyshire manufacturing corridors.
Market Restraints
- Specialized Engineering Talent Scarcity:Millisecond-level process loop response requirements demand scarce control systems expertise concentrated in the South East.
- UKCA Marking Transition Friction:Divergence from CE marking standards creates certification timeline uncertainty for integrators serving EU-UK dual markets.
- Legacy Protocol Proliferation:Proprietary fieldbus architectures in ageing industrial estates constrain interoperability with modern Ethernet-based control platforms.
Strategic Opportunities
- North West Carbon Capture Integration:Merseyside and Cheshire industrial clusters require process automation for carbon capture and hydrogen production facilities.
- Digital Twin Convergence:Advanced process control solutions are converging with physics-based simulation for predictive maintenance in oil and gas terminals.
- SECR Framework Compliance Services:The Streamlined Energy and Carbon Reporting framework creates recurring revenue streams for integrators monitoring energy consumption across manufacturing operations.
Industry Challenges
- Functional Safety Certification Bottlenecks:BSI accreditation timelines for TÜV-certified engineers delay project mobilization for critical infrastructure operators.
- Multi-Protocol Integration Complexity:Synchronizing material flow across heterogeneous control architectures demands specialized commissioning expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Industrial Automation System Integrator Market |
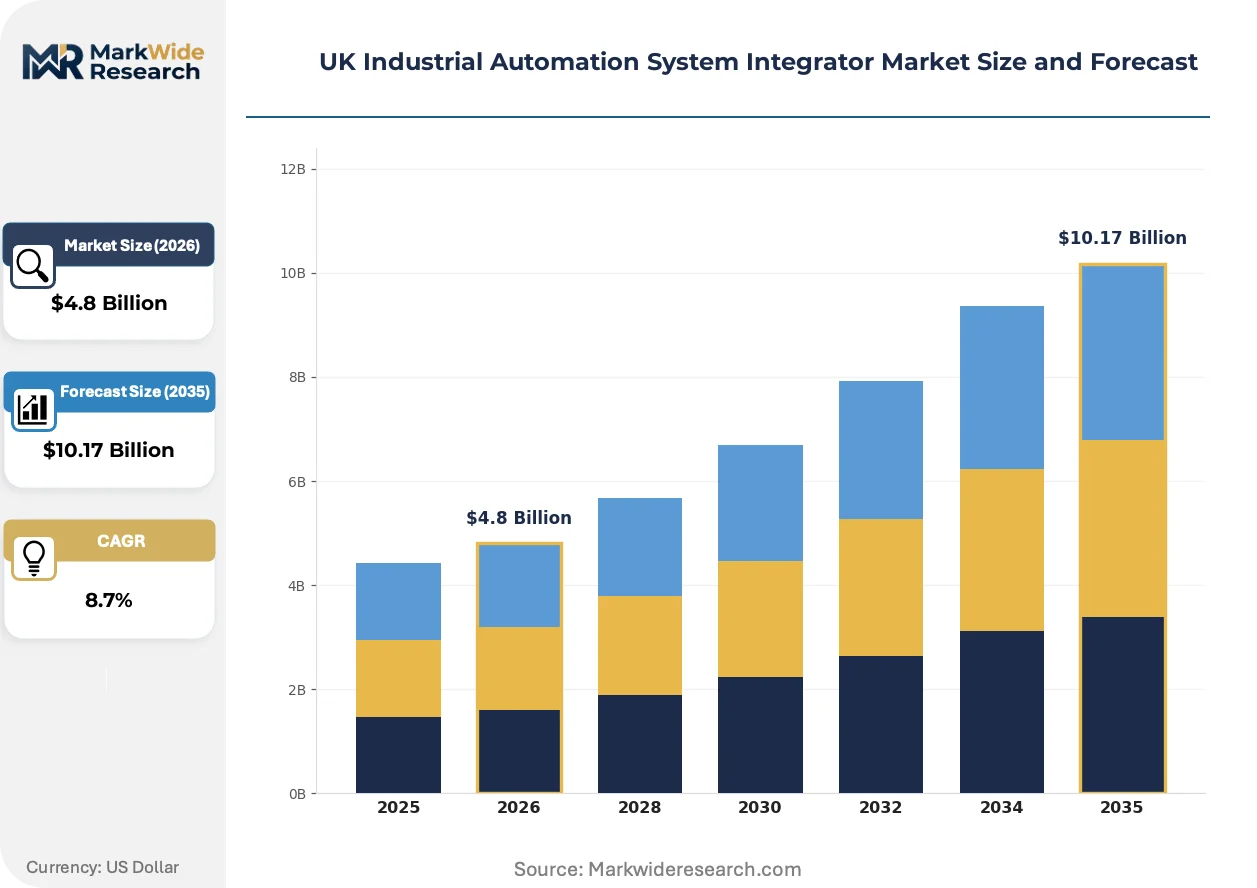
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, SCADA, Industrial Robots, Human-Machine Interface Technology: IoT, Cloud Computing, AI, PLC, Sensor Technology End User: Manufacturing, Oil & Gas, Pharmaceuticals, Food & Beverage Application: Process Automation, Robotic Process Automation, Building Automation, Energy Management |
| Companies Covered | Wood PLC, Jacobs U.K. Limited, Siemens Mobility Limited, Altec Engineering Limited, Cougar Automation Limited, Adsyst Automation Ltd., Au Automation, Core Control Solutions, Emerson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Industrial Automation System Integrator Market Trends and Innovations
Digital twin technology and advanced process control solutions are reshaping how UK manufacturers optimize energy consumption and predictive maintenance. These innovations compress commissioning cycles and enable remote diagnostics.
Edge computing platforms are converging with traditional SCADA architectures to enable real-time quality inspection at food and beverage packaging lines. Pharmaceutical manufacturers in the Midlands are deploying these systems to reduce batch release timelines. The structural consequence is compressing the traditional seven-layer automation pyramid into flatter, more responsive architectures.
The Streamlined Energy and Carbon Reporting framework mandates granular energy monitoring across qualifying industrial facilities. This regulatory pressure is expanding demand for integrated power management modules within control system deployments. Oil and gas terminals in Scotland and North East England are prioritizing certified integrators with carbon reporting platform expertise.
Outcome-based service contracts are displacing traditional time-and-materials arrangements for control system maintenance. Food and beverage producers across Yorkshire are unbundling hardware procurement from multi-year performance agreements. This shift is most visible among mid-cap manufacturers seeking guaranteed uptime metrics rather than capital expenditure ownership.
UK Industrial Automation System Integrator Market Segmentation
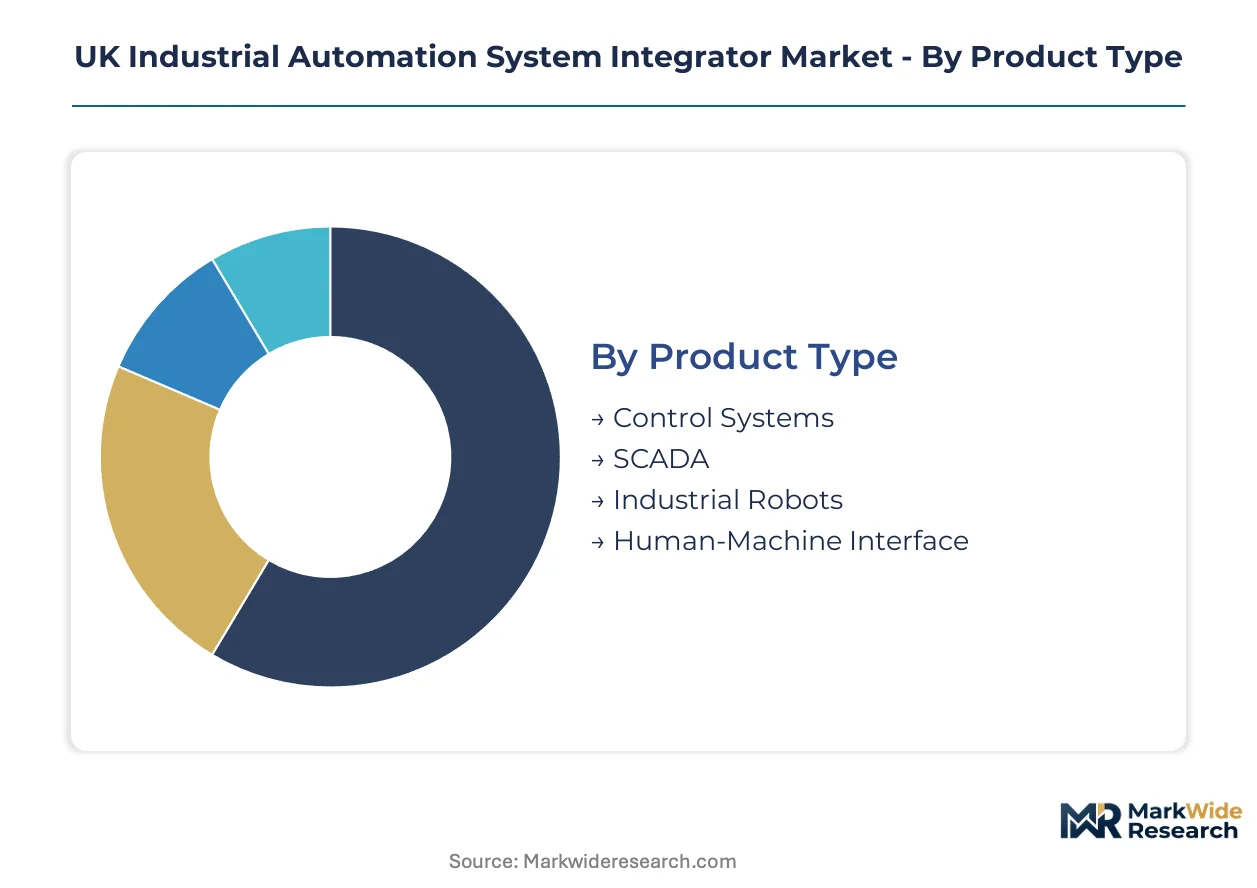
UK industrial automation system integrators navigate distinct procurement patterns across product types, technologies, and end-use verticals. Each segment carries unique commissioning cycles, certification requirements, and margin structures that shape integrator specialization strategies.
Product Type:
Replacement and upgrade cycles vary dramatically by product category, with legacy control infrastructure in Midlands manufacturing corridors driving concentrated demand for specific system architectures.
- Control Systems:Programmable logic controllers and distributed control systems form the core revenue base for integrators serving continuous process industries. Pharmaceutical manufacturers across Nottinghamshire and Derbyshire are modernizing aging DCS platforms to meet HSE COMAH compliance deadlines, expanding project scopes for certified safety instrumented system deployments.
- SCADA:Supervisory control and data acquisition platforms capture recurring revenue through software licensing renewals and long-term service attach rates. Oil and gas terminals in Scotland and North East England prioritize integrators with cybersecurity-hardened SCADA architectures that align with BSI functional safety standards.
- Industrial Robots:Articulated and collaborative robot integrations are gaining traction among labour-constrained food producers retrofitting packaging lines across Greater Manchester and Yorkshire.
- Human-Machine Interface:HMI layer upgrades enable remote diagnostics and compressed commissioning cycles for pharmaceutical batch operations in the Midlands.
Control Systems sits at the top of the volume ranking, with Industrial Robots climbing the fastest.
Technology:
Technology adoption patterns reflect divergent maturity curves, with established platforms dominating current spend while emerging architectures reshape long-term integrator competency requirements.
- IoT:Industrial internet-of-things deployments connect legacy field devices to cloud analytics platforms, enabling predictive maintenance in oil and gas infrastructure. North Sea operators are retrofitting brownfield assets with IoT-enabled condition monitoring to reduce unplanned shutdowns.
- Cloud Computing:Edge-to-cloud architectures compress data latency for real-time quality inspection at food and beverage packaging lines. Yorkshire producers are unbundling on-premise SCADA from hybrid cloud analytics subscriptions.
- AI:Machine learning models optimize process parameters in pharmaceutical batch operations, though deployment remains concentrated among large-cap manufacturers with dedicated data science functions.
- PLC:Traditional programmable logic controller programming maintains dominant share in automotive and general manufacturing applications across the West Midlands.
- Sensor Technology:Smart sensor integration supports the Streamlined Energy and Carbon Reporting framework by enabling granular power consumption tracking across qualifying industrial facilities.
PLC maintains the largest installed base, though Cloud Computing is expanding most quickly among mid-cap manufacturers seeking subscription-based operational expenditure models.
End User:
End-use verticals exhibit starkly different automation maturity levels, with regulated industries prioritizing safety certification while consumer-facing sectors emphasize throughput and flexibility.
- Manufacturing:General manufacturing spans automotive, electronics, and discrete assembly operations concentrated in the West Midlands and South East. These facilities prioritize robotic workcell integration for material handling and quality inspection.
- Oil & Gas:Upstream and downstream operators in Scotland and North East England require process automation for carbon capture readiness and hydrogen production pilot projects. Merseyside and Cheshire industrial clusters are emerging as focal points for integrators with energy transition expertise.
- Pharmaceuticals:COMAH-regulated facilities across Nottinghamshire and Derbyshire are accelerating outsourced automation integration to modernize legacy control architectures. BSI-accredited integrators with TÜV-certified engineers command premium positioning.
- Food & Beverage:Labour-constrained producers across Greater Manchester and Yorkshire are retrofitting packaging and palletising lines with robotic process automation to maintain throughput amid workforce shortages.
Manufacturing represents the broadest addressable base, while Pharmaceuticals generates the highest project values per engagement.
Application:
Application-level demand concentrates around process-intensive operations, with energy management emerging as a compliance-driven growth vector under UK carbon reporting obligations.
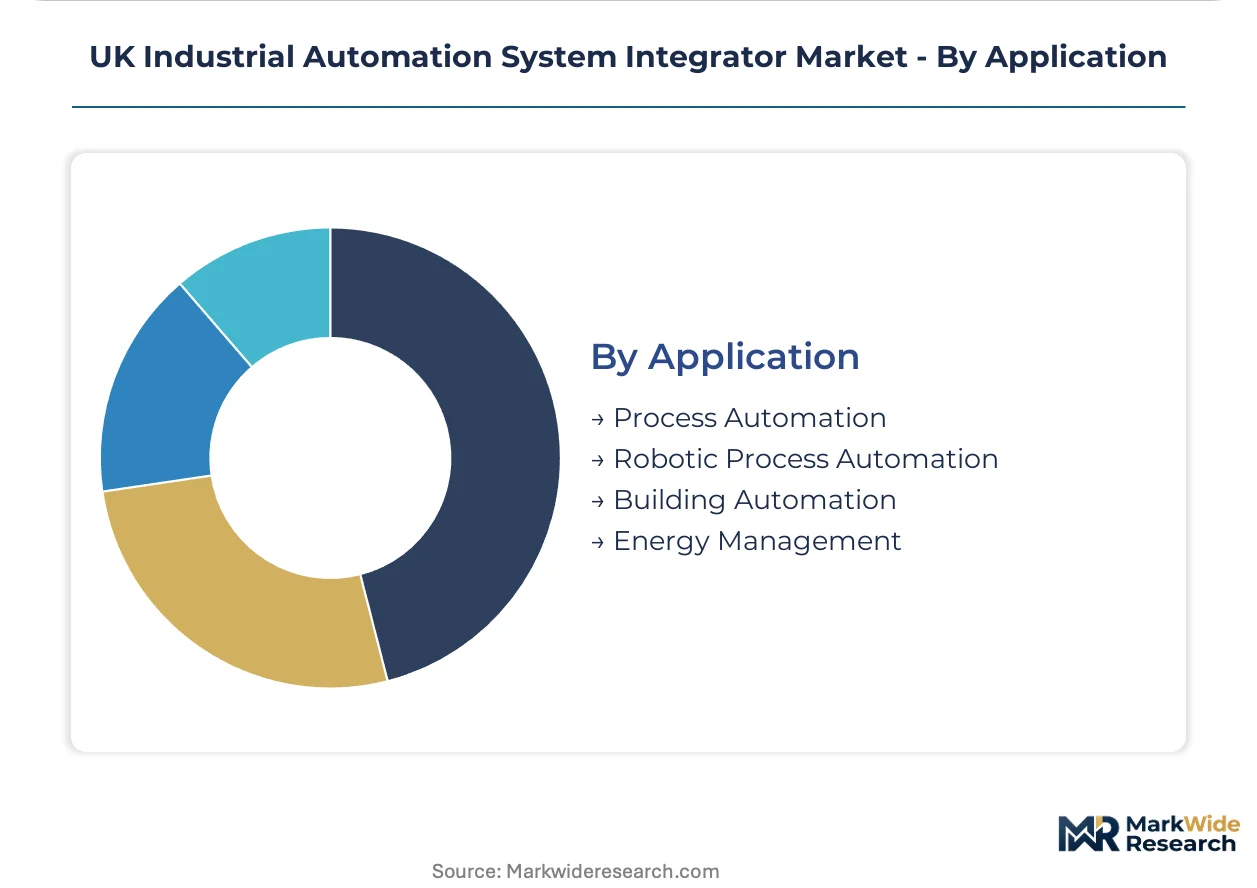
- Process Automation:Continuous and batch manufacturing control dominates integrator revenue, spanning chemical reactors, distillation columns, and mixing operations. Pharmaceutical and oil and gas end users drive volume demand for millisecond-level process loop response systems.
- Robotic Process Automation:Packaging, palletising, and pick-and-place applications are displacing manual labour in food and beverage facilities. These deployments exhibit the steepest expansion trajectory as mid-cap manufacturers seek guaranteed uptime metrics through outcome-based service contracts.
- Building Automation:HVAC and environmental control integration serves pharmaceutical cleanrooms and research facilities requiring precise temperature and humidity management.
- Energy Management:Integrated power monitoring modules are becoming standard inclusions within control system deployments to satisfy Streamlined Energy and Carbon Reporting framework obligations.
Process Automation anchors current integrator workloads, with Energy Management gaining share fastest as carbon reporting deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping automation integration demand as pharmaceutical and chemical producers migrate toward regions with clearer UKCA marking pathways and established COMAH enforcement frameworks, compressing procurement timelines for certified system integrators.
Midlands
Pharmaceutical manufacturers across Nottinghamshire and Derbyshire are accelerating outsourced automation integration to meet HSE Control of Major Accident Hazards deadlines. The Streamlined Energy and Carbon Reporting framework mandates granular energy monitoring for qualifying facilities. BSI-accredited integrators with TÜV-certified engineers command premium positioning across this manufacturing corridor.
North West
Merseyside and Cheshire industrial clusters require process automation for carbon capture readiness and hydrogen production pilot projects. The Health and Safety Executive enforces certified safety instrumented systems in chemical facilities. Labour-constrained food producers across Greater Manchester are retrofitting packaging lines with robotic process automation to maintain throughput.
Greater Manchester and Yorkshire
Food and beverage producers across this production corridor are unbundling hardware procurement from multi-year performance agreements. The UK's Net Zero Strategy compels facilities to modernize legacy control architectures. Mid-cap manufacturers here are prioritizing outcome-based service contracts with guaranteed uptime metrics over capital expenditure ownership.
Scotland
Oil and gas terminals in the North East and Central Belt prioritize integrators with cybersecurity-hardened SCADA architectures aligned to BSI functional safety standards. North Sea operators are retrofitting brownfield assets with IoT-enabled condition monitoring to reduce unplanned shutdowns. Carbon reporting platform expertise is becoming a decisive procurement criterion.
North East England
Downstream operators in Teesside require process automation for energy transition projects including hydrogen production and carbon capture integration. The HSE COMAH regulations mandate certified safety instrumented systems in chemical processing facilities. Integrators with combined process automation and carbon monitoring capabilities are capturing disproportionate contract value.
UK Industrial Automation System Integrator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital twin and edge computing specializations to differentiate beyond traditional control system deployment. The vendor base stratifies across three tiers: global engineering conglomerates anchoring large-scale process automation contracts, mid-cap specialists dominating regional pharmaceutical and food manufacturing clusters, and boutique integrators capturing niche safety instrumented system certifications. Competitive positioning depends on BSI accreditation depth, TÜV-certified engineer headcount, and demonstrated UKCA marking transition expertise. M&A activity concentrates on acquiring functional safety competencies, while strategic partnerships with cloud platform providers reshape service delivery models.
Among UK-based engineering specialists, Wood PLC and Jacobs U.K. Limited exemplify the scale-driven tier, with the former representing deep project engineering capabilities across energy and pharmaceutical sites and the latter occupying a position anchored in R&D-intensive digital twin deployments. Siemens Mobility Limited, despite its German corporate origin, sits within the technology leadership archetype through its dominance of rail and transport automation integration extending into adjacent industrial verticals. These three entities represent contrasting pathways for market participation: engineering execution depth, digital innovation intensity, and technology platform leverage.
| Leading Market Players |
|---|
| Wood PLC |
| Jacobs U.K. Limited |
| Siemens Mobility Limited |
| Altec Engineering Limited |
| Cougar Automation Limited |
| Adsyst Automation Ltd. |
| Au Automation |
| Core Control Solutions |
| Emerson |
| Others |
Pricing and Supply Chain Analysis
Vertical integration into safety instrumented system design anchors both supply security and pricing power for UK integrators serving COMAH-regulated pharmaceutical and chemical facilities. Captive engineering capabilities around TÜV-certified talent and BSI-accredited commissioning reduce dependency on subcontracted specialists, compressing project mobilization timelines and supporting premium rate capture.
Pricing Analysis
Distributor margins on hardware procurement compress as mid-cap manufacturers unbundle equipment purchase from multi-year service agreements. Project-based pricing dominates certified safety instrumented system deployments, with three-tier pricing structure across premium, standard, and economy levels reflecting TÜV engineer headcount and UKCA marking transition expertise. Pricing pressure stems from outcome-based contract proliferation as food and beverage producers prioritize guaranteed uptime metrics over capital expenditure ownership. Pharmaceutical manufacturers exhibit lowest price sensitivity due to COMAH compliance deadlines, while general manufacturing buyers negotiate aggressively on robotic workcell integrations.
Supply Chain Analysis
UKCA marking divergence from CE standards reshapes sourcing patterns for control hardware and safety instrumented system components. Programmable logic controllers and distributed control system hardware concentrate in Germany, Japan, and the United States, while industrial robot arms and collaborative robot platforms source primarily from Japan, Germany, and China. Semiconductor shortages in motion control chips and power electronics create single-source vulnerability for specialized servo drives. Distribution runs through authorized distributor networks serving regional manufacturing clusters, with direct OEM relationships commanding volume discounts for large-scale pharmaceutical and oil and gas deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certified safety system deployment and recurring carbon reporting services, as regulatory compliance burdens shift buyer budgets toward premium-tier integrators with demonstrated HSE and SECR framework expertise.
For Market Incumbents: Deepen TÜV-certified engineering bench strength to defend against boutique specialists capturing niche COMAH compliance contracts. Acquire functional safety competencies through targeted capability purchases rather than full-firm acquisitions, preserving capital for UKCA marking transition tooling. Lock in multi-year outcome-based agreements with Midlands pharmaceutical manufacturers facing 2024-2025 HSE deadline clustering.
For New Entrants and Emerging Players: Cloud platform providers represent the most penetrable channel partnership archetype for edge computing and digital twin service layering. Target Yorkshire food and beverage mid-caps with robotic process automation retrofit packages bundled under subscription-based operational expenditure models. Lead with energy management module integration to satisfy Streamlined Energy and Carbon Reporting framework obligations as the primary foot-in-the-door offering.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap regional specialists because BSI accreditation timelines and TÜV engineer scarcity create durable competitive moats against rapid organic replication. Five-to-ten-year viability hinges on carbon capture integration and hydrogen production facility positioning in Merseyside and Cheshire industrial clusters. Watch HSE enforcement intensity around COMAH deadline extensions as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | TÜV-certified engineer acquisition accelerates COMAH-regulated project mobilization for pharmaceutical facilities. |
| Digital Twin Platform Integration | Physics-based simulation convergence with advanced process control compresses commissioning cycles for oil and gas terminals. |
| Carbon Reporting Service Layer | Streamlined Energy and Carbon Reporting compliance modules create recurring revenue streams across manufacturing verticals. |
| UKCA Marking Transition Expertise | Certification pathway mastery captures procurement preference among dual EU-UK market operators. |
| Edge Computing Architecture Deployment | Real-time quality inspection capabilities differentiate integrators serving Yorkshire food packaging retrofit demand. |
Research Methodology
Direct dialogue with control systems engineers, pharmaceutical facility managers, HSE compliance officers, and food and beverage production directors grounded qualitative demand assessment. Secondary validation drew from Health and Safety Executive enforcement notices, BSI certification registries, SECR framework guidance documents, and trade data on industrial automation hardware imports. Bottom-up project pipeline analysis across Nottinghamshire, Derbyshire, Greater Manchester, and Yorkshire manufacturing corridors triangulated against top-down market sizing from sectoral automation spend surveys.
Segment-level outputs across product type, technology, end user, and application dimensions were generated through the projection horizon. Control systems and SCADA replacement cycles, robotic process automation adoption curves in labour-constrained sectors, and pharmaceutical COMAH compliance deadline clustering served as primary forecast inputs. CAGRs were derived from regression analysis of historical integration project values against regulatory event timing and capital expenditure survey responses.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to UKCA marking implementation delays, HSE enforcement intensity variations, and carbon reporting framework scope expansions. Assumptions reflect current regulatory trajectories without anticipating material policy reversals. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Process Automation Market
Industrial Automation
Multi-Axis Motion Controller Market
Industrial Automation
Linear Motion System Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Europe ICS Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Grippers Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
UV Curing System Market
Industrial Automation
Smart Industries Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Tilt Tray Sorter Market