
 Global Industrial Control and Factory Automation Market | 2026-2036
Global Industrial Control and Factory Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Control and Factory Automation Market Outlook
ISO 10218 robot safety certification is collapsing the supplier pool for collaborative robot deployments in European automotive plants. Siemens AG leverages its digital twin portfolio to anchor software-defined automation architectures across German and Chinese facilities. ABB competes through its vertically integrated motion control and robotics supply chain, while Rockwell Automation specializes in programmable automation controllers for North American process industries.
Industrial control and factory automation encompasses the hardware, software, and networked systems that govern machine operation, process flow, and production sequencing in manufacturing environments, typically integrating programmable controllers with real-time sensor feedback loops operating at sub-millisecond cycle times to optimize throughput and minimize unplanned downtime. The primary commercial purpose centers on substituting manual oversight with deterministic, repeatable control logic that reduces defect rates and extends equipment operational life. Distributed Control Systems command the largest installed base in continuous process industries such as oil refining and chemical production where fault tolerance and modular redundancy justify premium system costs. Industrial Internet of Things technology is expanding fastest as edge computing architectures enable predictive maintenance models that shift revenue from equipment sales to outcome-based service contracts.
The U.S. Occupational Safety and Health Administration enforces machine guarding standards that mandate risk assessments before deploying automated systems, while the EU Machinery Directive requires CE marking with documented conformity to essential health and safety requirements for market access. China's Ministry of Industry and Information Technology promotes domestic GB standards for industrial Ethernet protocols that favor local control system vendors in state-backed manufacturing upgrades. Stakeholders must weigh the capital intensity of full stack automation against modular, retrofit-friendly architectures that preserve optionality as technology standards continue to fragment across regulatory blocs.
Market Dynamics
The EU's F-Gas Regulation is compressing equipment replacement cycles across industrial cooling systems, forcing manufacturers to accelerate R&D timelines for alternative refrigerant architectures while simultaneously reshaping supplier qualification requirements.
Growth Catalysts
- Automotive robotic assembly:German manufacturers around Stuttgart and Wolfsburg are expanding collaborative robot deployments to offset labor shortages in precision welding operations.
- CE marking acceleration:The EU Machinery Directive's conformity requirements are creating competitive moats for certified system integrators serving pan-European production networks.
- Edge computing architectures:Sub-millisecond sensor feedback loops are enabling predictive maintenance models that convert capital equipment sales into recurring service revenue streams.
Market Restraints
- ISO 10218 certification scarcity:The collapsing supplier pool for collaborative robot safety compliance is extending deployment timelines in European automotive plants.
- Copper and rare earth volatility:Motion control systems face input cost pressure from concentrated upstream mining operations in Chile and the Democratic Republic of Congo.
- Legacy protocol lock-in:Proprietary industrial Ethernet standards fragment interoperability, trapping process manufacturers in single-vendor upgrade paths.
Strategic Opportunities
- Chinese state-backed upgrades:MIIT's promotion of domestic GB standards for industrial Ethernet protocols favors local control system vendors in government-funded manufacturing modernization programs.
- Digital twin convergence:Software-defined automation architectures integrating real-time physics simulation with live production data are opening new consulting revenue pools.
- Retrofit-friendly modular systems:Preserving optionality through interoperable subsystems addresses capital-constrained small and medium manufacturers in India's industrial corridors.
Industry Challenges
- Functional safety engineering shortage:The talent gap for IEC 61508 certified engineers is delaying safety integrity level verification in oil refining DCS deployments.
- Multi-protocol integration complexity:Harmonizing legacy fieldbus networks with OPC UA over TSN requires specialized system integrators with scarce cross-platform expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Control and Factory Automation Market |
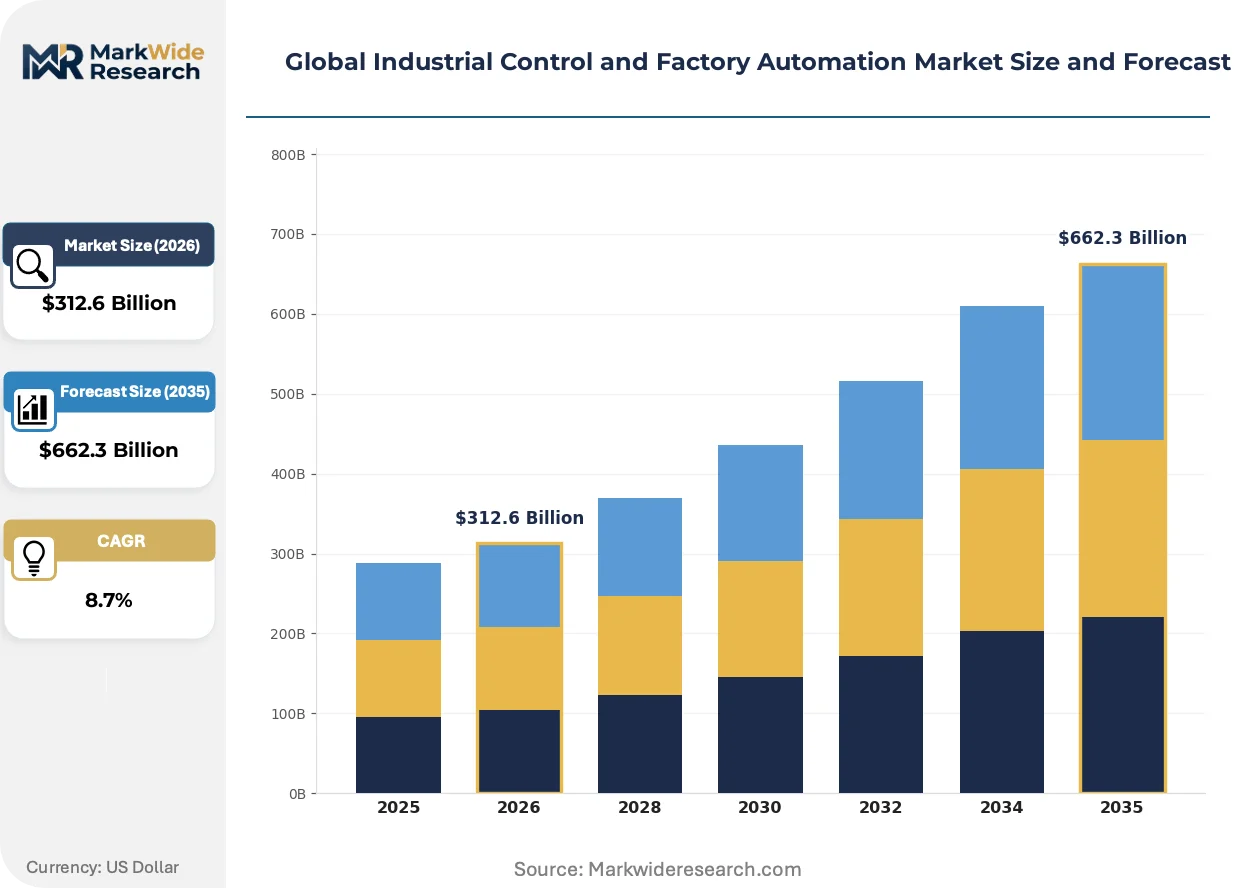
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Distributed Control Systems, Supervisory Control and Data Acquisition, Human Machine Interface Technology: Industrial Internet of Things, Artificial Intelligence, Cloud Computing, Blockchain End User: Manufacturing, Oil & Gas, Pharmaceuticals, Automotive Application: Process Automation, Factory Automation, Building Automation, Energy Management |
| Companies Covered | FANUC Corporation, Honeywell, Siemens AG, KUKA, Schneider Electric, Rockwell Automation, Yaskawa Electric, Emerson Automation Solutions, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Control and Factory Automation Market Strategic Shifts
Deterministic control logic is migrating from centralized programmable controllers to distributed edge nodes, compressing fault response times while fragmenting vendor ecosystems across competing real-time operating system architectures.
Time-Sensitive Networking over standard Ethernet is supplanting proprietary fieldbus protocols in automotive assembly lines. BMW and Volkswagen production facilities in Germany are adopting TSN-enabled sensor networks at pilot scale. This convergence is collapsing the historical separation between information technology and operational technology procurement functions.
REACH chemical restrictions and the EU F-Gas Regulation are banning hydrofluorocarbon refrigerants in industrial cooling equipment by 2030. Compressor manufacturers are accelerating ammonia and CO2 system development. German chemical producers and food processors face the steepest retrofit obligations given their installed base of high-GWP cooling infrastructure.
Automotive buyers are consolidating automation procurement under outcome-based performance contracts. Tier-1 suppliers now contract for units-per-hour guarantees rather than equipment ownership. This shift is most pronounced in Volkswagen Group's supplier agreements, where penalty clauses for unplanned downtime now exceed capital lease payments.
Global Industrial Control and Factory Automation Market Segmentation
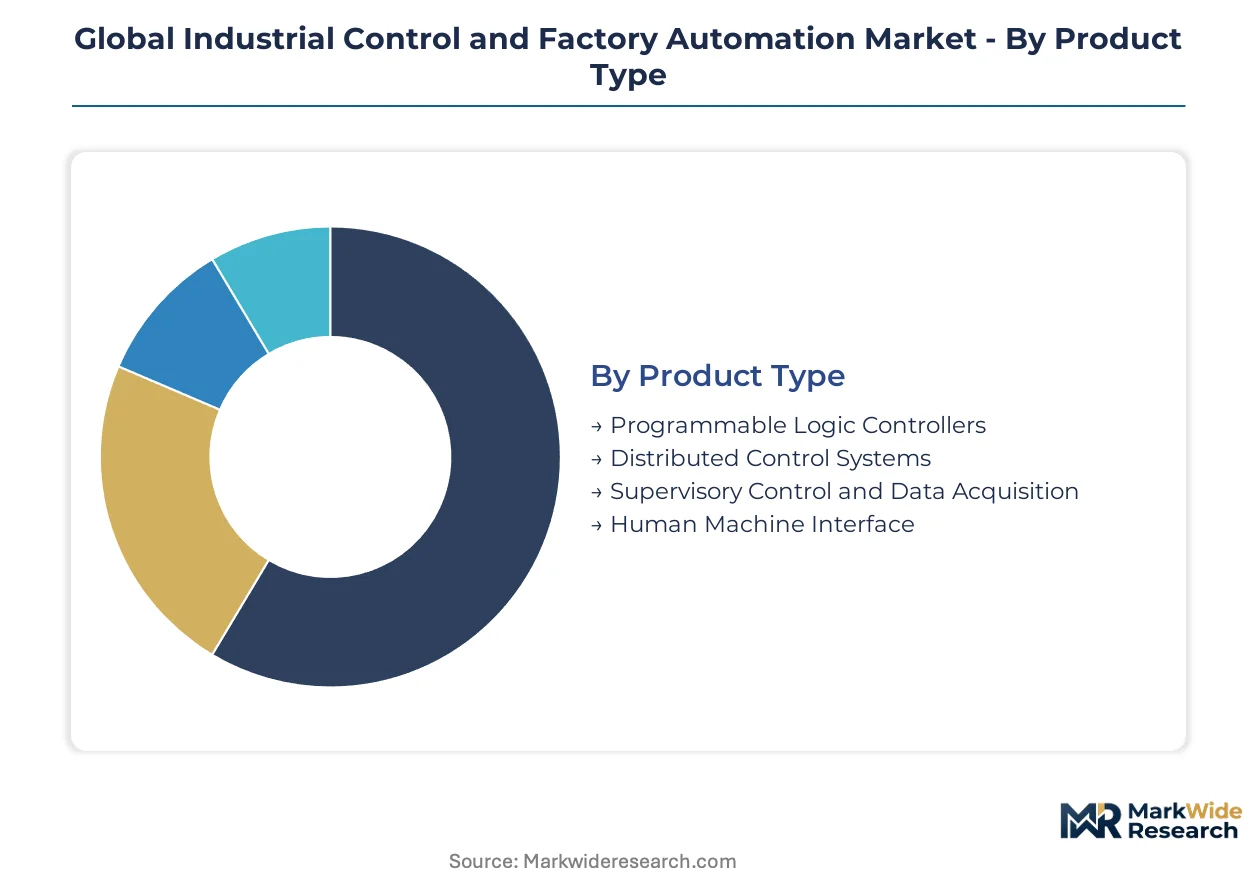
Segmentation in industrial control and factory automation reveals how procurement patterns split between capital-intensive continuous process industries and discrete manufacturing environments with shorter replacement cycles. Technology adoption curves diverge sharply across these boundaries.
Product Type:
Channel flows concentrate through systems integrators for complex DCS deployments, while PLCs and HMIs move through distributor networks serving retrofit markets.
- Programmable Logic Controllers:Ruggedized controllers executing ladder logic and structured text with deterministic scan times below 10 milliseconds. Demand clusters in Germany's automotive belt around Stuttgart for robotic cell coordination, driven by ISO 10218 safety certification requirements compressing supplier pools.
- Distributed Control Systems:Modular architectures with redundant controllers and fault-tolerant I/O for continuous process industries. Oil refineries along the US Gulf Coast and chemical complexes in Rotterdam prioritize these systems, constrained by functional safety engineering shortages delaying IEC 61508 verification.
- Supervisory Control and Data Acquisition:Layered software platforms aggregating field-level data into centralized historian databases.
- Human Machine Interface:Touch-panel and web-based visualization terminals enabling operator interaction with underlying control layers.
By volume, Programmable Logic Controllers leads. By growth pace, Distributed Control Systems is climbing the fastest.
Technology:
Cost tiers separate premium edge-computing stacks from commoditized connectivity modules, with AI commanding implementation premiums above standard IIoT sensor networks.
- Industrial Internet of Things:Sensor networks and edge gateways transmitting operational data via OPC UA and MQTT protocols. German automotive plants piloting TSN-enabled architectures face multi-protocol integration complexity requiring scarce cross-platform expertise.
- Artificial Intelligence:Machine learning models deployed at edge nodes for predictive maintenance and quality inspection. Volkswagen Group's outcome-based supplier contracts in Wolfsburg are accelerating AI adoption, displacing traditional equipment sales with uptime guarantee structures.
- Cloud Computing:Scalable infrastructure for remote monitoring and centralized analytics across distributed production sites.
- Blockchain:Distributed ledger applications for supply chain traceability and automated contract execution.
Industrial Internet of Things dominates current deployment volumes. Artificial Intelligence shows the steepest expansion trajectory as automotive buyers consolidate procurement under performance contracts.
End User:
Application maturity varies dramatically, with oil and gas maintaining decades-long DCS lifecycles while automotive embraces 3-5 year robotic system refresh cycles.
- Manufacturing:Discrete production environments spanning food processing to electronics assembly. India's industrial corridors are driving modular retrofit-friendly system demand among capital-constrained small and medium manufacturers.
- Oil & Gas:Upstream extraction and downstream refining operations requiring SIL-rated safety systems. US Gulf Coast refineries face talent gaps for IEC 61508 certified engineers, extending project timelines.
- Pharmaceuticals:Batch processing and continuous manufacturing governed by FDA validation requirements.
- Automotive:Robotic welding, painting, and assembly lines with sub-millisecond synchronization demands. BMW and Volkswagen facilities in Germany are adopting TSN-enabled sensor networks, collapsing IT and OT procurement separation.
Manufacturing leads by installed base. Automotive is gaining share fastest through collaborative robot deployments offsetting precision welding labor shortages.
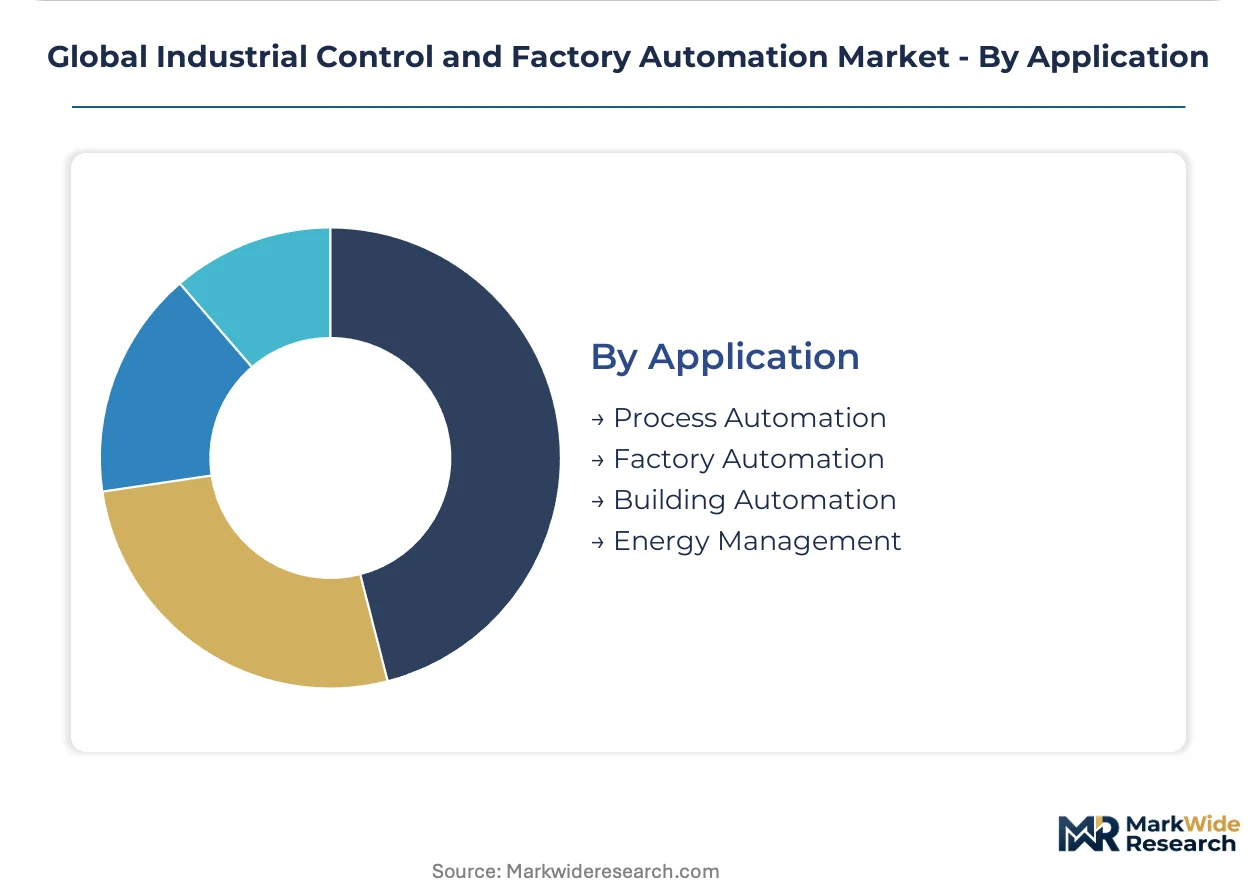
Application:
Customer type segmentation splits between owner-operators seeking full-stack integration and contract manufacturers prioritizing interoperable subsystems for equipment mobility.
- Process Automation:Continuous flow control in chemical, petrochemical, and utility operations. German chemical producers face steep F-Gas Regulation retrofit obligations for high-GWP cooling infrastructure.
- Factory Automation:Discrete manufacturing coordination including robotics and material handling. China's MIIT promotion of domestic GB standards favors local vendors in state-backed manufacturing modernization programs.
- Building Automation:HVAC, lighting, and security integration for commercial and industrial facilities.
- Energy Management:Power monitoring, demand response, and renewable integration for industrial facilities.
Process Automation retains the largest revenue pool. Factory Automation is expanding most quickly as edge computing architectures enable predictive maintenance service conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and process industry operators concentrate procurement authority in Germany, China, and the United States, with tier-1 suppliers and systems integrators following these buyer clusters into adjacent markets.
Germany
Volkswagen Group and BMW drive collaborative robot deployments across precision welding operations. The EU F-Gas Regulation mandates hydrofluorocarbon phase-out by 2030, compressing cooling system replacement cycles. Stuttgart and Wolfsburg anchor demand concentration, with ISO 10218 certification requirements collapsing the supplier pool for safety-compliant installations.
China
State-backed manufacturing modernization programs prioritize domestic GB standards for industrial Ethernet protocols. MIIT promotion of local control system vendors shapes procurement in government-funded upgrades. Yangtze River Delta automotive plants adopt edge computing architectures for predictive maintenance service conversions.
United States
OSHA machine guarding standards enforce risk assessments before automated system deployment, extending project timelines. Oil refineries along the Gulf Coast maintain decades-long DCS lifecycles, constrained by functional safety engineering shortages delaying IEC 61508 verification. Houston and Corpus Christi concentrate process automation demand.
Japan
METI industrial policy emphasizes real-time operating system development for distributed control architectures. Automotive manufacturers in Toyota City and Nagoya integrate sub-millisecond sensor feedback loops for robotic assembly synchronization. JIS standards compliance creates qualification barriers for foreign control system vendors.
India
Capital-constrained small and medium manufacturers in Maharashtra and Gujarat drive demand for retrofit-friendly modular systems. PLI scheme incentives for electronics manufacturing attract automation vendors to set up local integration capabilities. Bangalore-Tamil Nadu industrial corridor pilots edge computing deployments for quality inspection applications.
Global Industrial Control and Factory Automation Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with captive robotics and motion control capabilities, creating tiered competition between full-stack automation providers and specialized component vendors. Siemens AG anchors software-defined automation through digital twin portfolios, while Rockwell Automation dominates North American process industries with programmable controller specialization. Strategic moves center on backward integration into edge computing hardware and outcome-based service contract structures that displace traditional equipment sales.
Within the diversified conglomerate tier, Siemens AG, ABB, and FANUC Corporation exemplify competing approaches to vertical scope. Siemens leverages digital twin convergence across German and Chinese facilities. ABB represents integrated motion control and robotics supply chain control. FANUC anchors Japanese precision manufacturing automation with concentrated automotive customer relationships. Rockwell Automation occupies a distinct position in North American process industries, while Honeywell and Emerson Automation Solutions compete for oil and gas DCS deployments.
| Leading Market Players |
|---|
| FANUC Corporation |
| Honeywell |
| Siemens AG |
| KUKA |
| Schneider Electric |
| Rockwell Automation |
| Yaskawa Electric |
| Emerson Automation Solutions |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Ninety-day component lead times for programmable logic controllers are compressing pricing power for European system integrators while amplifying cost-plus indexation leverage for German robotics suppliers serving Stuttgart automotive clusters. This inventory pressure concentrates margin capture upstream with semiconductor and rare earth processors, forcing downstream automation vendors toward fixed-price contract renegotiation.
Pricing Analysis
Cost-plus contracts indexed to copper and rare earth price indices dominate motion control system procurement between German automotive OEMs and their Tier-1 suppliers. Pricing stratifies across SIL-certified safety tiers, ISO 10218 compliance grades, and bundled after-sales service levels. Cost compression in standard PLCs is intensifying because Chinese domestic vendors are undercutting European brands in India's industrial corridors. Small and medium manufacturers in Maharashtra and Gujarat exhibit the highest price sensitivity, while Volkswagen Group's outcome-based performance contracts show minimal elasticity to equipment list prices.
Supply Chain Analysis
Port congestion on the Shanghai-Rotterdam trade lane is elevating inbound logistics costs for edge computing hardware destined to German automotive plants. Supply concentrates in Germany for precision motion control components, China for industrial Ethernet switches and edge gateways, and Japan for high-reliability servo motors. The chain draws from Chilean copper, Congolese rare earths, and Taiwanese semiconductors. Single-source vulnerability in IEC 61508-certified safety processor chips creates qualification bottlenecks for oil refinery DCS deployments. Distribution runs through systems integrators for complex deployments and distributor networks for PLC retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory blocs is creating specialized niche opportunities as automotive buyers abandon single-vendor automation stacks in favor of interoperable subsystem architectures. This demand-side shift rewards modular specialists over full-stack conglomerates.
For Market Incumbents: Compound digital twin consulting revenue by anchoring software-defined automation architectures in Chinese state-backed manufacturing programs. Deepen backward integration into edge computing hardware to offset margin pressure from commoditized connectivity modules. Defend against emerging Chinese domestic vendors by accelerating ISO 10218 certification pipelines for collaborative robot deployments.
For New Entrants and Emerging Players: Lead with retrofit-friendly modular PLCs targeting capital-constrained small and medium manufacturers in India's industrial corridors. The most penetrable white space sits in TSN-enabled sensor networks for automotive quality inspection, where cross-platform integration expertise remains scarce. Pursue outcome-based service contracts with Tier-1 automotive suppliers seeking units-per-hour guarantees rather than equipment ownership.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core automation divisions amid portfolio rationalization pressures. Long-term viability favors specialists with captive safety certification capabilities and recurring service revenue exceeding fifty percent of total mix. Watch for inflection signals in MIIT procurement guidelines favoring domestic GB standards compliance as mandatory for state-funded projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Computing Hardware | Captures margin pools from semiconductor suppliers serving German automotive digital twin deployments. |
| ISO 10218 Safety Certification Investment | Collapses supplier competition for collaborative robot installations in Volkswagen Group facilities. |
| Outcome-Based Performance Contracting | Converts capital equipment sales into recurring revenue with penalty clauses for unplanned downtime. |
| GB Standards Compliance Development | Qualifies vendors for MIIT-funded manufacturing modernization programs in China's Yangtze River Delta. |
| Retrofit-Friendly Modular System Design | Preserves optionality for capital-constrained small and medium manufacturers in India's industrial corridors. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at German automotive OEMs, procurement leads at US Gulf Coast refineries, systems integrators specializing in TSN deployments, and aftermarket service heads at European robotics vendors, then refined through secondary validation against SEC 10-K filings, EU F-Gas Regulation implementation guidance, MIIT policy circulars, and customs trade data for industrial automation components. Bottom-up demand modeling triangulated with top-down market sizing across the analysis window.
Variance decomposition across product type, technology tier, end-use industry, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth trajectories weighted by installed base evolution and replacement cycle compression. Forecast inputs incorporated F-Gas Regulation phase-out timelines, collaborative robot penetration curves in precision welding, and edge computing adoption rates in predictive maintenance service conversions.
Forecasts assume regulatory continuity in EU machinery safety directives, US OSHA machine guarding enforcement, and Chinese MIIT domestic standard promotion; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
UV Curing System Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Asia Pacific Retail Automation Market
Industrial Automation
Industrial Automation Spares Market