
 Europe Solar E-Bike Market | 2026-2036
Europe Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar E-Bike Market Analytics
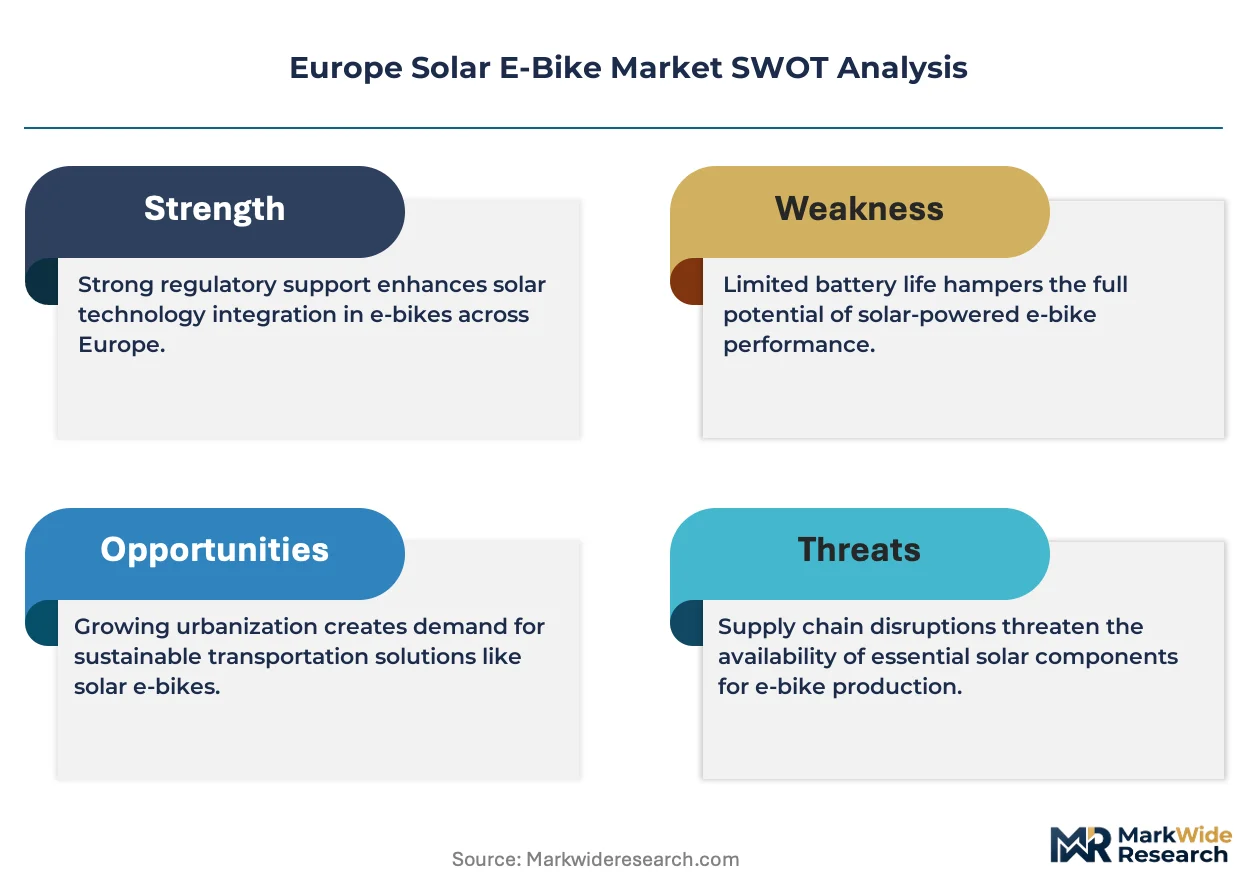
Lithium iron phosphate is consolidating as the preferred battery chemistry across European solar e-bike production, displacing heavier lead-acid configurations that once dominated price-sensitive segments. Bosch eBike Systems leverages its Stuttgart engineering base to sustain integrated drive system dominance from motor to battery management. Riese & Müller anchors premium positioning through Munich-based manufacturing of full-suspension solar e-bike platforms. Kalkhoff Werke GmbH dominates German retail channels with established dealer networks spanning over 1,500 points of sale.
A solar e-bike integrates photovoltaic panels into frame surfaces or detachable charging units, converting sunlight into electrical energy stored in 400–800 Wh lithium-ion battery packs to assist pedal propulsion via hub or mid-drive motors rated 250–750 W. The primary commercial purpose extends urban commuter range beyond plug-in dependency while reducing grid electricity consumption for daily transport. Mountain and folding product types lead unit volume as outdoor enthusiasts seek off-grid charging capability and urban commuters prioritize storage efficiency in compact apartments. Battery management technology captures disproportionate margin pools as thermal regulation algorithms and cell balancing systems differentiate reliability across temperature extremes from Nordic winters to Mediterranean summers.
The EU Green Deal and F-Gas Regulation shape product standards by restricting fluorinated greenhouse gases in cooling systems for battery thermal management, while ECHA oversight of REACH chemical compliance governs solar panel semiconductor materials and frame coatings. CE marking mandates under the EU Machinery Directive establish safety thresholds for electrical systems, braking performance, and electromagnetic compatibility that non-compliant imports cannot bypass. Stakeholders must monitor whether Brussels extends battery passport requirements to light electric vehicles, as traceability rules would force upstream disclosure of cobalt and lithium sourcing across solar e-bike supply chains.
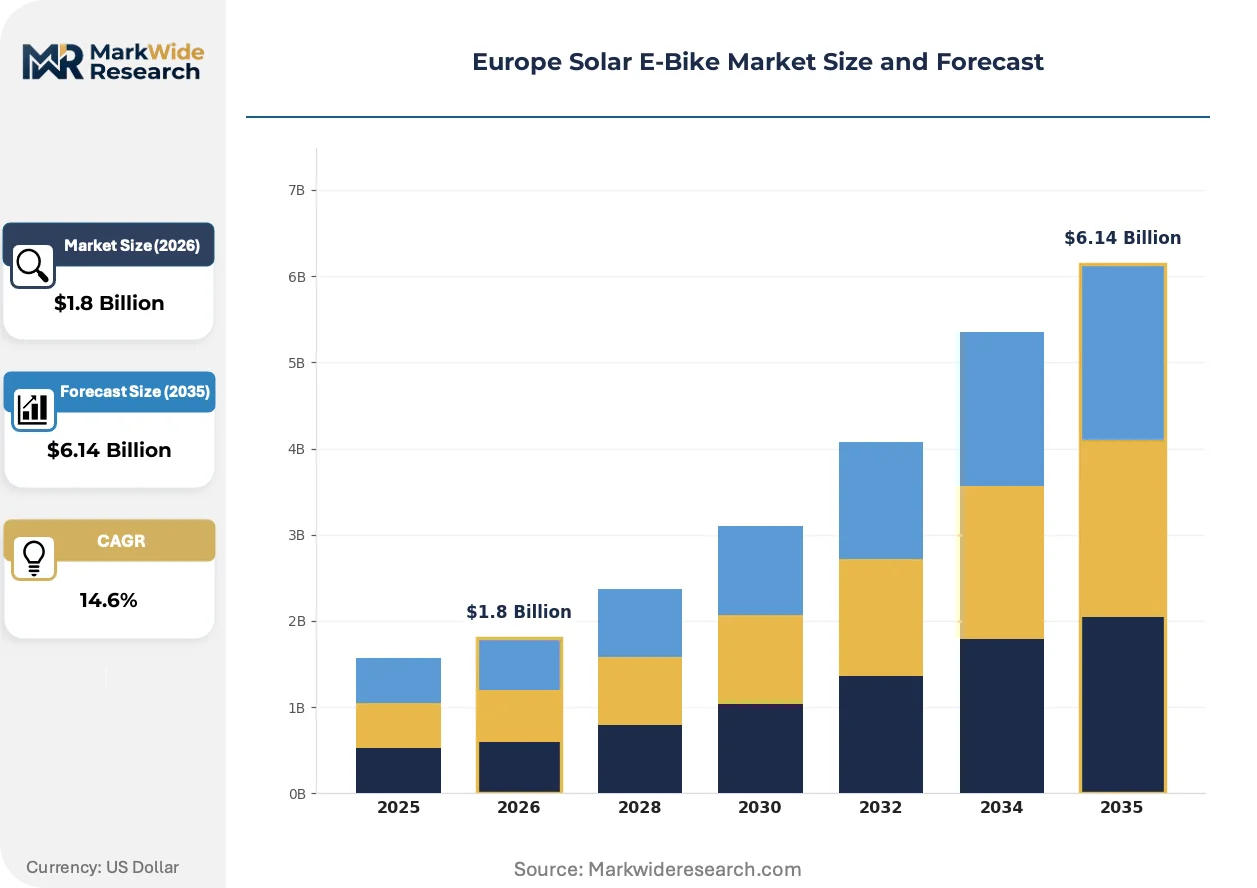
Market Dynamics
EU Green Deal emission mandates for commercial transport are compressing procurement timelines across urban last-mile delivery fleets, forcing logistics operators to accelerate solar e-bike deployment ahead of 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal commercial transport mandates:Tightening emission standards for urban delivery fleets in Amsterdam, Berlin, and Copenhagen are accelerating fleet electrification programs.
- Lithium iron phosphate battery chemistry:Superior thermal stability and cycle life are displacing lead-acid configurations across price-sensitive commuter segments.
- Dutch and German cycling infrastructure density:Dedicated lane networks and secure parking facilities reduce operational friction for daily solar e-bike commuters.
Market Restraints
- Photovoltaic panel semiconductor supply concentration:Dependence on concentrated Asian wafer production exposes European assemblers to input volatility and logistics bottlenecks.
- REACH chemical compliance costs:ECHA oversight of solar panel materials and frame coatings imposes testing and documentation burdens that inflate landed costs for smaller manufacturers.
- Weather-dependent charging reliability:Nordic winter irradiance levels drop below viable thresholds for several months, limiting year-round utility in Scandinavian markets.
Strategic Opportunities
- Polish and Romanian urban logistics expansion:Underpenetrated last-mile delivery markets in Eastern European capitals present first-mover advantages for solar e-bike fleet operators.
- Battery passport traceability requirements:Upcoming Brussels disclosure mandates for cobalt and lithium sourcing will reward early supply chain auditors with premium positioning.
- Photovoltaic-integrated frame manufacturing:Convergence of lightweight composite fabrication and flexible solar cell lamination enables differentiated product architectures.
Industry Challenges
- Battery thermal management algorithm development:Scarce firmware engineering talent capable of optimizing cell balancing across Mediterranean summer and Nordic winter temperature extremes.
- CE marking electromagnetic compatibility certification:Extended testing timelines for integrated solar charging systems delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar E-Bike Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fat Tire, Folding, Mountain, Cruiser Technology: Solar Panel Integration, Battery Management, Regenerative Braking, Smart Connectivity End User: Commuters, Outdoor Enthusiasts, Delivery Services, Recreational Riders Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Rental Services |
| Companies Covered | Accell Group, Giant Manufacturing Co. Ltd., Trek Bicycle Corporation, Bosch eBike Systems, Yamaha Motor Corporation, Riese & Müller, Kalkhoff Werke GmbH, Derby Cycle, Specialized Bicycle Components, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar E-Bike Market Evolving Landscape
Photovoltaic integration is migrating from accessory-mounted panels to structural frame-embedded architectures, while battery chemistry standardization and procurement model evolution are compressing supplier margins and reshaping channel economics.
Flexible monocrystalline silicon solar cells laminated into carbon fiber frame tubes are absorbing direct structural loads while generating 15-25 watts under peak irradiance. Cargo fleet operators in Copenhagen and Utrecht are specifying these integrated platforms for daily routes exceeding 60 kilometers. The technology is absorbing design responsibility from separate component suppliers into consolidated frame manufacturers.
F-Gas Regulation restrictions on fluorinated greenhouse gases in battery cooling systems are forcing thermal management redesigns across European production facilities. Manufacturers must substitute hydrocarbon or CO2-based cooling circuits for conventional refrigerants. German and Dutch assemblers face the steepest compliance costs given their concentration of mid-drive motor production requiring active thermal regulation.
Direct fleet procurement contracts are displacing traditional dealer-network volumes for commercial solar e-bike deployment. Logistics operators in Berlin and Vienna now negotiate specification-built units with frame-integrated charging, bypassing retail markup. This channel rotation is most visible in Germany, where Kalkhoff Werke GmbH's 1,500-point dealer network faces margin compression from enterprise procurement teams demanding volume pricing and dedicated service agreements.
Europe Solar E-Bike Market Segmentation
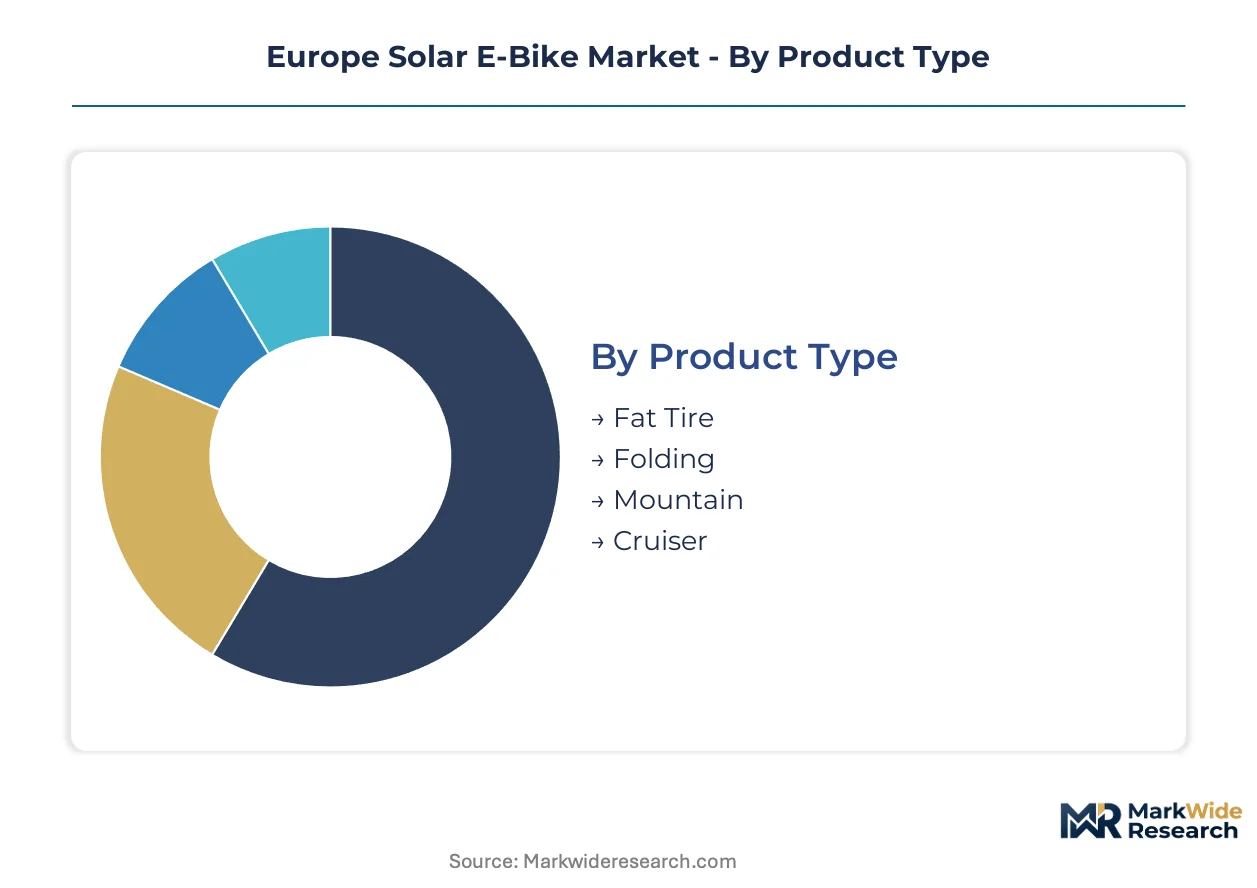
Product architecture and procurement channel choices determine margin capture and service model design across the Europe solar e-bike market. Segment boundaries are blurring as fleet operators demand specification-built units and photovoltaic integration shifts from bolt-on accessories to frame-embedded systems.
Product Type:
Frame geometry and wheel specification create a customization gradient from standardized commuter platforms to specialized terrain-optimized architectures.
- Mountain:Full-suspension frames accommodate larger battery packs and ruggedized solar charging arrays for off-grid trail access. Demand concentrates in Alpine regions of Austria and Switzerland where outdoor enthusiasts prioritize range independence over plug-in infrastructure.
- Folding:Hinge mechanisms and compact wheelbases sacrifice some photovoltaic surface area for storage efficiency in dense urban apartments. German and Dutch commuters in Berlin and Amsterdam drive volume as multi-modal transit integration becomes essential.
- Fat Tire:Oversized contact patches and reinforced frames support cargo loads across unstable surfaces like beach paths and snow-covered Nordic routes.
- Cruiser:Step-through geometries and relaxed riding positions target older demographics in Mediterranean retirement corridors.
Leading the category by volume: Folding. Growing fastest: Mountain.
Technology:
Component sophistication separates price tiers, with premium systems commanding margins through proprietary firmware and thermal engineering.
- Battery Management:Cell balancing algorithms and thermal regulation circuits differentiate reliability across temperature extremes from Finnish winters to Spanish summers. Bosch eBike Systems anchors this segment through Stuttgart-based firmware development for integrated drive systems.
- Solar Panel Integration:Flexible monocrystalline silicon lamination into carbon fiber tubes absorbs structural loads while generating supplemental charge. Copenhagen and Utrecht cargo fleets specify these architectures for routes exceeding 60 kilometers daily.
- Regenerative Braking:Hub motor inverters recover kinetic energy during descent, extending effective range in hilly topography.
- Smart Connectivity:GPS tracking and fleet management APIs enable logistics operators to monitor utilization and prevent theft across distributed delivery networks.
Highest margin capture sits with battery management. Steepest expansion trajectory: solar panel integration.
End User:
Procurement behavior diverges sharply between individual consumers seeking retail service and enterprise fleets negotiating direct manufacturer contracts.
- Delivery Services:Last-mile logistics operators in Berlin, Vienna, and Amsterdam specify frame-integrated charging and dedicated service agreements, bypassing traditional dealer markups. EU Green Deal emission mandates compress procurement timelines ahead of 2030 compliance deadlines.
- Commuters:Daily urban transport users prioritize reliability and theft protection over performance specifications, concentrating demand in German and Dutch cycling infrastructure corridors.
- Outdoor Enthusiasts:Weekend trail riders accept weight penalties for off-grid charging capability in remote Alpine and Pyrenean terrain.
- Recreational Riders:Casual users exhibit price sensitivity and seasonal usage patterns, favoring rental services over ownership in Mediterranean tourist economies.
Dominant revenue source: delivery services. Gaining share fastest: commuters as fuel costs rise.
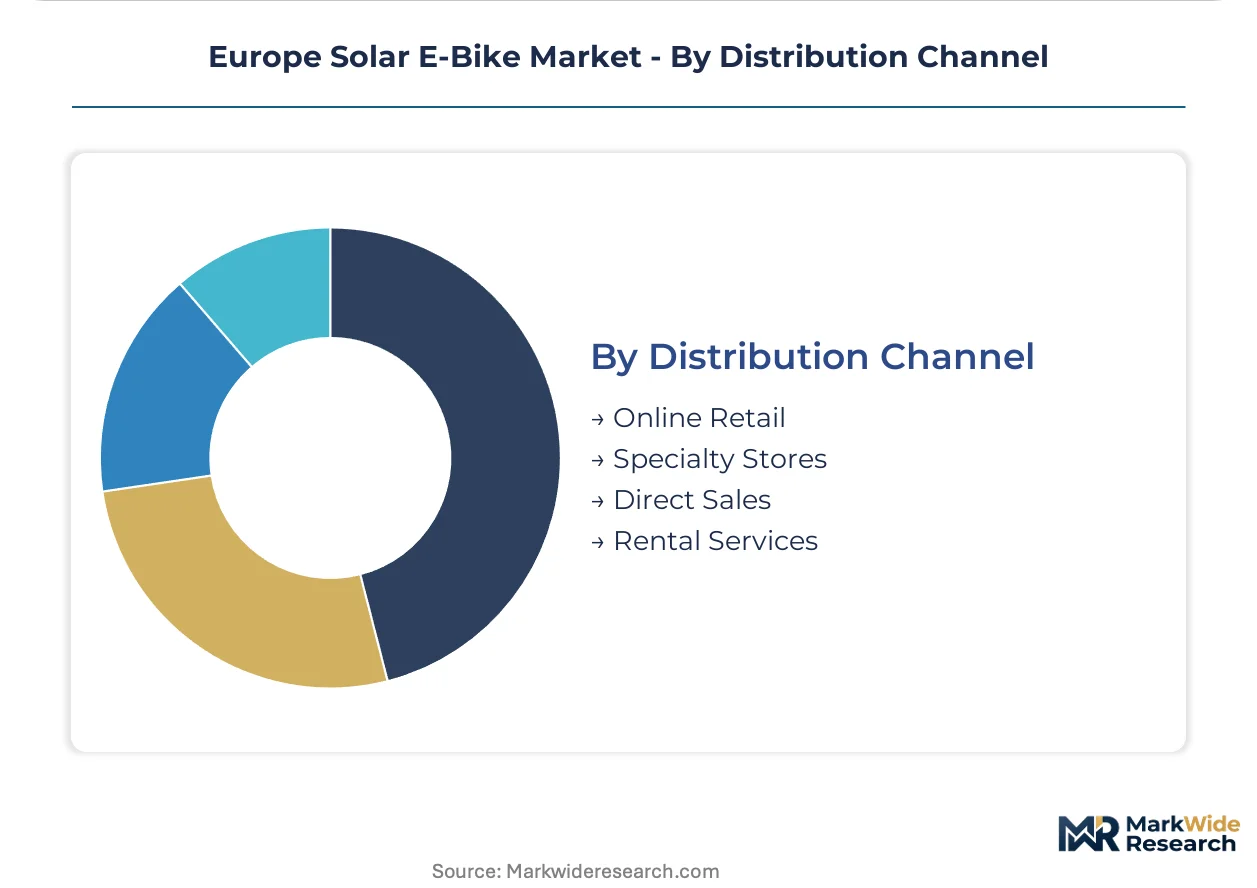
Distribution Channel:
Channel economics are rotating as enterprise procurement displaces retail volumes for commercial deployment.
- Direct Sales:Fleet operators negotiate specification-built units with volume pricing and captive service networks. This channel is compressing margins for established dealer networks in Germany.
- Specialty Stores:Technical consultation and test ride availability sustain relevance for individual consumers purchasing premium full-suspension platforms.
- Online Retail:Price transparency and convenience attract cost-sensitive commuter segments, though shipping complexity for lithium-ion batteries creates regulatory friction.
- Rental Services:Subscription models reduce ownership barriers for tourists and trial users in seasonal Mediterranean markets.
Fastest-growing channel: direct sales. Most margin pressure: specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany and the Netherlands, where dense cycling infrastructure and national purchase incentives for electric mobility converge to create the continent's most mature solar e-bike corridors.
Germany
Urban last-mile delivery fleets in Berlin and Hamburg are expanding procurement ahead of EU Green Deal emission deadlines. The KBA enforces CE marking compliance under the EU Machinery Directive for electrical system safety. Stuttgart anchors Bosch eBike Systems' integrated drive system dominance, while Munich-based Riese & Müller manufactures full-suspension solar e-bike platforms for premium segments.
Netherlands
Cargo fleet operators in Amsterdam and Utrecht specify frame-integrated photovoltaic architectures for daily routes exceeding 60 kilometers. National purchase incentives for electric mobility reduce acquisition costs for commercial buyers. Eindhoven's composite fabrication cluster supports lightweight solar cell lamination into carbon fiber frame tubes.
Denmark
Copenhagen's municipal logistics operators compress procurement timelines to meet 2030 commercial transport compliance deadlines. The Danish Environmental Protection Agency enforces REACH chemical compliance for solar panel semiconductor materials. The Øresund corridor concentrates fleet deployment expertise across urban planning and cycling infrastructure integration.
Austria
Outdoor enthusiasts in Alpine regions prioritize off-grid charging capability for remote trail access. The Federal Ministry for Climate Action oversees alignment with EU Green Deal emission standards for commercial transport. Tyrol's mountain tourism economy sustains demand for ruggedized solar charging arrays on full-suspension platforms.
Poland
Underpenetrated last-mile delivery markets in Warsaw present first-mover advantages for solar e-bike fleet operators. The Chief Inspectorate of Environmental Protection enforces RoHS restrictions on hazardous substances in electrical components. Silesia's emerging logistics hub attracts direct procurement contracts from international delivery services seeking Eastern European expansion.
Europe Solar E-Bike Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers commanding premium positioning while retail-channel assemblers face margin compression from direct fleet procurement. The vendor base organizes into three strategic archetypes: engineering-led integrated drive system developers, premium full-suspension platform manufacturers, and high-volume retail-channel assemblers with established dealer networks. Competitive moves concentrate on photovoltaic-integrated frame manufacturing partnerships and direct enterprise service agreements that bypass traditional markup structures.
Among German-based engineering specialists, Bosch eBike Systems and Riese & Müller exemplify the integrated system and premium platform archetypes respectively. Kalkhoff Werke GmbH represents the high-volume retail-channel model with extensive dealer network presence. These three entities occupy distinct competitive positions without direct segment overlap, allowing coexistence across price tiers and end-use applications.
| Leading Market Players |
|---|
| Accell Group |
| Giant Manufacturing Co. Ltd. |
| Trek Bicycle Corporation |
| Bosch eBike Systems |
| Yamaha Motor Corporation |
| Riese & Müller |
| Kalkhoff Werke GmbH |
| Derby Cycle |
| Specialized Bicycle Components, Inc. |
| Others |
Value Network & Pricing Analysis
Fleet procurement consolidation in Germany and the Netherlands is compressing retail margins and forcing frame manufacturers to absorb design responsibility from separate component suppliers, shifting margin capture toward integrated system providers and away from traditional dealer networks.
Pricing Analysis
Volume concentrates in standard commuter platforms while margin pools sit with battery management systems and frame-integrated photovoltaic architectures. Three-tier pricing structure across premium, standard, and economy levels separates Bosch-integrated full-suspension platforms from Kalkhoff retail-channel assemblers and direct-import economy units. Cost compression in the retail tier is intensifying because logistics operators in Berlin and Vienna now negotiate specification-built units with dedicated service agreements, bypassing dealer markup. Delivery services exhibit lowest price sensitivity due to EU Green Deal compliance deadlines, while recreational riders in Mediterranean markets show highest elasticity.
Supply Chain Analysis
EU battery passport traceability requirements and domestic-content preferences in German and Dutch procurement are reshaping sourcing patterns for cobalt and lithium disclosure. Photovoltaic wafer production draws from concentrated Asian supply, lithium iron phosphate cell manufacturing rests on Chinese and South Korean capacity, and carbon fiber composite fabrication centers on German and Dutch clusters. Single-source vulnerability in semiconductor wafer supply exposes European assemblers to logistics bottlenecks. Distribution runs through direct fleet procurement contracts displacing traditional dealer-network volumes for commercial deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated system providers as direct procurement compresses retail-channel margins and EU battery passport requirements force upstream disclosure investments that weaker assemblers cannot absorb.
For Market Incumbents: Extend firmware development capabilities in thermal management algorithms to differentiate reliability across Nordic winter and Mediterranean summer extremes. Secure captive supply of flexible monocrystalline silicon solar cells through partnerships with Eindhoven composite fabrication clusters. Frame-integrated photovoltaic manufacturing represents the critical lever for margin defense against direct procurement pressure. For New Entrants and Emerging Players: Polish municipal logistics operators present an underserved buyer archetype with compressed procurement timelines ahead of EU Green Deal deadlines. Target Warsaw and Krakow last-mile delivery fleets with specification-built cargo platforms featuring frame-embedded charging architectures. A direct enterprise service model bypassing retail markup offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with battery management firmware specialists given upcoming Brussels disclosure mandates for cobalt and lithium traceability. The five-to-ten-year viability window favors acquisition targets with established thermal regulation algorithms and cell balancing systems. Watch for EU extension of battery passport requirements to light electric vehicles as the inflection signal for upstream supply chain auditing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic-Integrated Frame Manufacturing | Convergence of lightweight composite fabrication and flexible solar cell lamination enables differentiated product architectures for cargo fleets. |
| Battery Passport Compliance Investment | Upstream disclosure of cobalt and lithium sourcing positions early auditors for premium procurement contracts under Brussels traceability rules. |
| Direct Fleet Procurement Partnerships | Bypassing traditional dealer markups captures volume pricing and dedicated service agreements with Berlin and Vienna logistics operators. |
| Thermal Management Firmware Development | Scarce engineering talent in cell balancing algorithms differentiates reliability across Finnish winter and Spanish summer temperature extremes. |
| Eastern European Logistics Expansion | Underpenetrated last-mile delivery markets in Warsaw and Bucharest present first-mover advantages for solar e-bike fleet deployment. |
Research Methodology
EU regulatory filings, ECHA REACH compliance databases, and KBA vehicle type-approval records formed the secondary backbone, cross-referenced with primary interviews with fleet procurement managers at Amsterdam and Berlin logistics operators, battery management firmware engineers at Stuttgart engineering centers, and composite fabrication specialists at Eindhoven manufacturing clusters. Bottom-up unit shipment estimates from frame manufacturers and top-down value projections from dealer network revenue disclosures were triangulated against Green Deal implementation timelines.
Historical trendline analysis of lithium iron phosphate adoption curves and photovoltaic integration migration patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, battery chemistry tier, procurement channel, and regional cycling infrastructure density. CAGRs were derived from fitted growth curves adjusted for EU commercial transport mandate compliance deadlines. Forecast inputs incorporated fleet electrification program announcements and national purchase incentive policy trajectories.
Revisions become necessary when semiconductor wafer supply disruptions intensify, REACH chemical compliance costs escalate beyond smaller manufacturer absorption capacity, or Brussels accelerates battery passport implementation timelines. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and lithium iron phosphate cost parity achievement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Solar Car Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
Nordic E-Bike Market