
 Hybrid E-Scooter Market | 2026-2036
Hybrid E-Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid E-Scooter Market Foresight
Direct-to-consumer online channels is fragmenting as traditional powersports dealerships and micromobility subscription platforms compete for rider relationships. Honda anchors its position through captive engine-manufacturing expertise and established Asian distribution networks. Yamaha differentiates via integrated motor-control systems developed for its electric motorcycle portfolio. Segway competes aggressively on price in the commuter tier while leveraging its robotics heritage for software-defined ride dynamics.
Hybrid e-scooters combine an internal combustion engine or range-extending generator with an electric drivetrain, typically employing a 2-4 kWh lithium-ion pack alongside a compact petrol motor to eliminate range anxiety while retaining zero-emission capability in urban zones. The primary commercial purpose centers on fleet operators and individual riders who face charging infrastructure gaps or require extended daily range beyond pure-electric alternatives. Commuter configurations currently dominate volume shipments due to municipal permit schemes and employer subsidy programs, while off-road variants sustain higher per-unit margins through specialized suspension and reinforced frame architectures. Fast charging infrastructure is concentrating investment as fleet operators demand sub-one-hour turnaround times for commercial deployment.
FCC certification requirements govern wireless connectivity modules in US-bound units, while EU-type approval under L-category vehicle directives mandates specific braking and lighting standards across member states. India's Automotive Research Association enforces localization thresholds under the PLI scheme that shape battery sourcing decisions for manufacturers targeting that market. Stakeholders must monitor how divergent subsidy phase-out schedules across these jurisdictions will reshape cost-competitiveness of hybrid versus pure-electric alternatives.
Market Dynamics
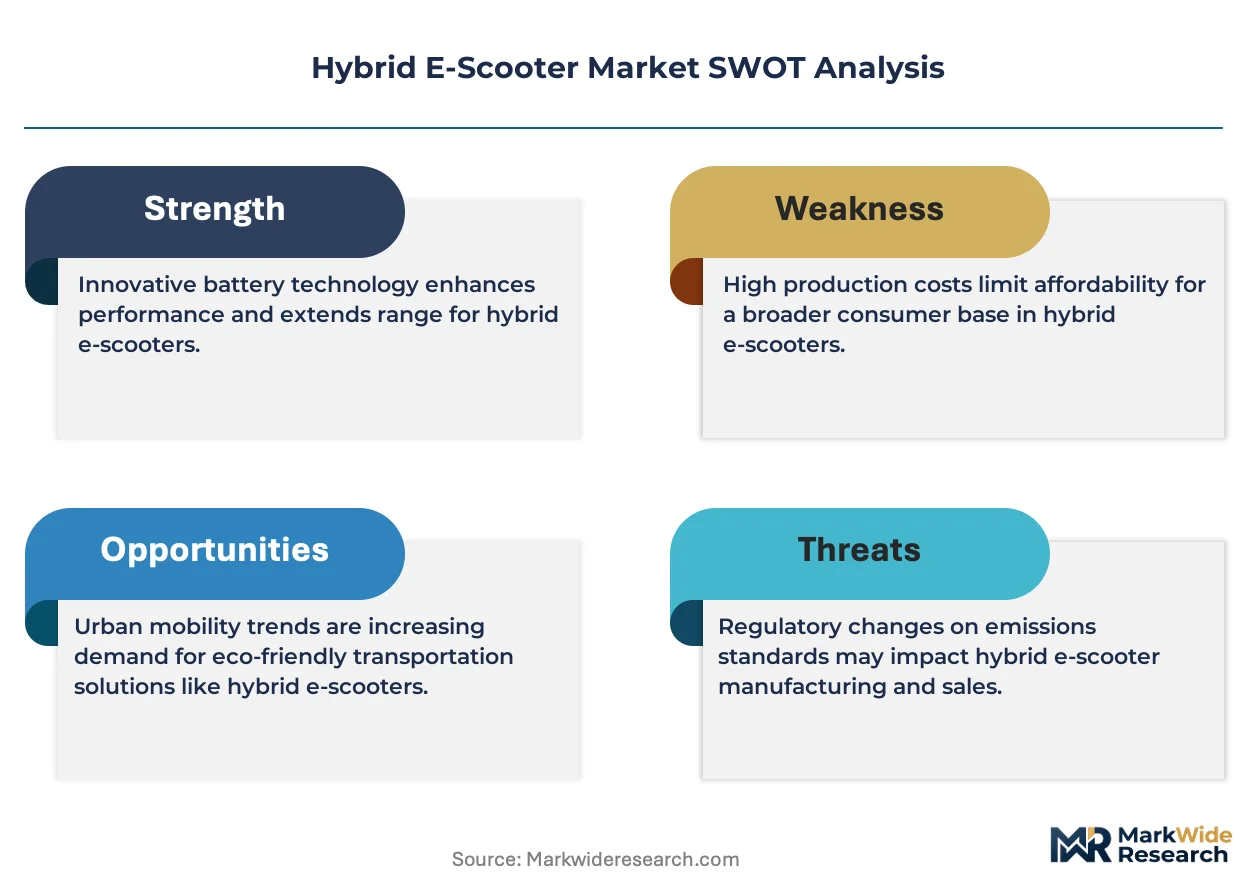
Dual-powertrain architecture adoption is accelerating as fleet operators confront charging infrastructure gaps in dense Asian megacities while municipal zero-emission zones expand coverage. This structural tension between range requirements and clean-air mandates is redirecting engineering resources across the supply base.
Growth Catalysts
- FAME II subsidy regime:India's production-linked incentive scheme reduces battery pack costs for domestic assembly operations, accelerating hybrid unit deployment in Mumbai and Bangalore last-mile fleets.
- Petrol-electric drivetrain integration:Advances in compact generator synchronization enable sub-50cc range extenders to eliminate range anxiety without sacrificing urban zero-emission capability.
- Southeast Asian grid instability:Unreliable electricity supply in Jakarta, Manila, and Ho Chi Minh City creates persistent demand for dual-powertrain solutions among delivery platform contractors.
Market Restraints
- Lithium carbonate price volatility:Cathode material cost swings compress margin buffers for 2-4 kWh pack configurations, forcing manufacturers toward smaller battery capacities.
- Dual-certification burden:EU-type approval under L-category directives plus Euro 5+ emission compliance for the combustion component doubles homologation timelines and engineering overhead.
- Pure-electric substitution pressure:Swappable battery networks deployed by Gogoro and competitors in Taiwan and South Korea erode the hybrid value proposition in covered service areas.
Strategic Opportunities
- Indonesian archipelago logistics:Island-hopping delivery corridors with intermittent grid access represent an underpenetrated geography where range-extended units outcompete battery-electric alternatives.
- Employer mobility subsidy programs:Corporate commuter benefit schemes in Germany and the Netherlands are expanding eligibility to include hybrid two-wheelers, opening B2B procurement channels.
- Vehicle-to-load integration:Converging power electronics and bidirectional charging hardware enable mobile power source applications for outdoor service contractors and emergency response fleets.
Industry Challenges
- Powertrain calibration expertise:The shortage of engineers proficient in both internal combustion mapping and motor-control algorithms extends development cycles and inflates R&D payrolls.
- FCC modular certification:Wireless connectivity modules for fleet telematics require separate approval pathways that delay US market entry by 4-6 months relative to EU-type approval timelines.
- Dual-supply-chain coordination:Sourcing both precision-engineered engine components and lithium-ion cells forces manufacturers to manage two fundamentally different supplier relationships with mismatched payment terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid E-Scooter Market |
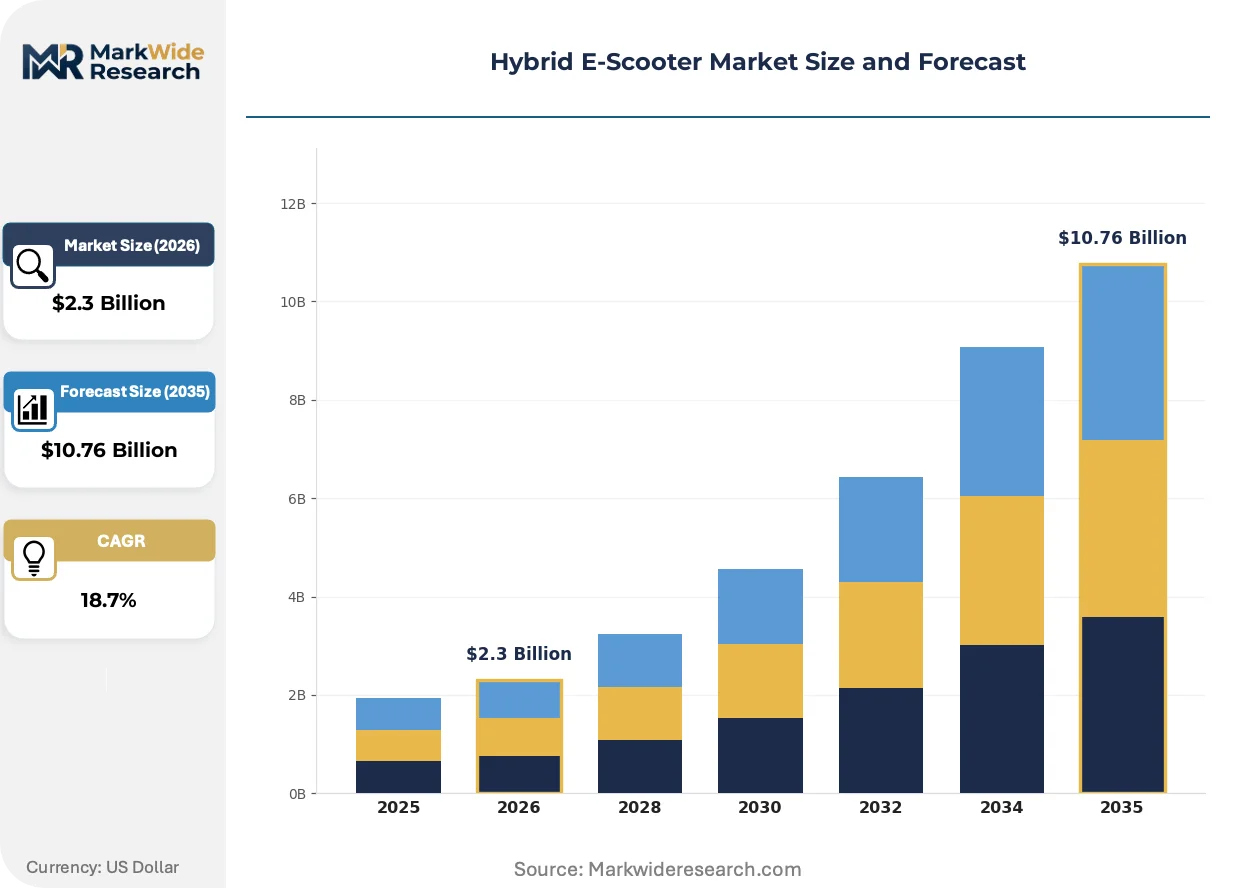
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $10.76 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Off-Road, Commuter, Heavy-Duty End User: Urban Commuters, Delivery Services, Rentals, Tour Operators Battery Technology: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Charging Method: Standard Charging, Fast Charging, Solar Charging, Regenerative |
| Companies Covered | Suzuki, Navee, Honda, Apollo, Kaabo, Yamaha, Segway, Ultraviolet, TVS Motor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid E-Scooter Market Shifts & Advancements
Software-defined ride dynamics and predictive energy management are displacing hardware-centric differentiation as the primary competitive battleground. Engineering investment is concentrating on algorithms that optimize powertrain switching rather than mechanical refinement.
Digital twin simulation of thermal management systems is virtualizing prototype testing cycles for hybrid powertrain integration. Tier-1 suppliers in Japan and South Korea are adopting cloud-based validation platforms that compress development timelines from 18 months to under 12 months. This virtualization is enabling faster iteration on generator-electric motor coupling strategies without physical mule builds.
EU Green Deal implementation is tightening embodied carbon disclosure requirements for automotive supply chains. Manufacturers must now document lifecycle emissions for both battery cell production and compact engine manufacturing, with L-category vehicle directives mandating third-party verification. Southeast Asian exporters targeting European fleet operators are restructuring supplier audits to capture upstream metallurgy and cathode active material provenance.
Subscription-based micromobility platforms are unbundling vehicle ownership from access, with delivery aggregators in São Paulo and Mexico City negotiating fleet-as-a-service contracts that include maintenance and energy costs. This procurement model shift transfers residual value risk to OEMs and their financing partners while locking in multi-year volume commitments. Brazilian logistics platforms are piloting hybrid units under these arrangements to test route viability before capital deployment.
Hybrid E-Scooter Market Segmentation
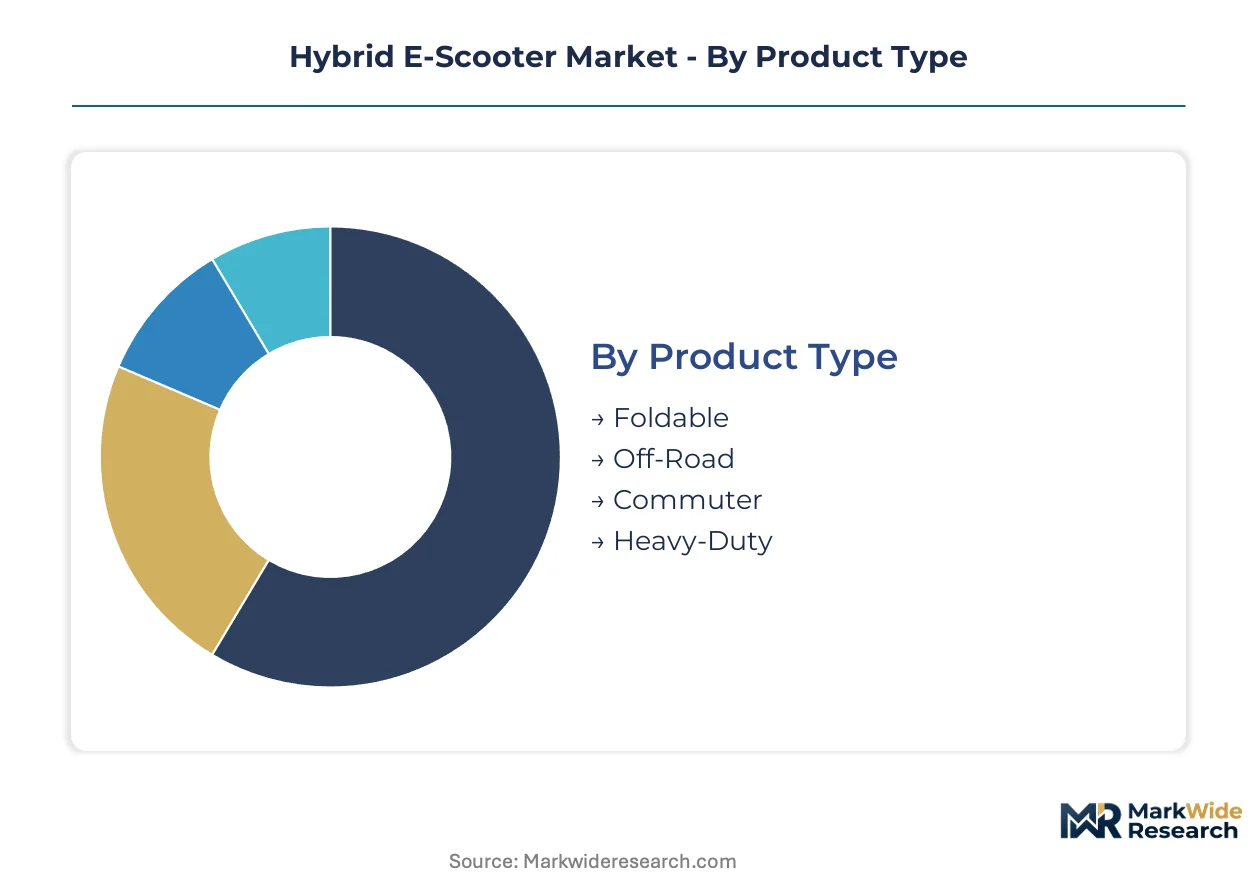
Hybrid e-scooter segmentation reveals how dual-powertrain architectures map onto divergent use cases and infrastructure realities. Product configuration, end-user economics, battery chemistry trade-offs, and charging modality collectively determine unit economics and deployment feasibility across metropolitan and fleet contexts.
Product Type:
Mature commuter platforms anchor volume while emerging heavy-duty variants redefine commercial durability standards.
- Commuter:Municipal permit schemes in Jakarta and employer subsidy programs in Germany concentrate procurement of sub-50cc range-extended units optimized for daily urban circuits. These configurations balance zero-emission zone compliance with petrol backup for charging infrastructure gaps.
- Off-Road:Reinforced frame architectures and specialized suspension command premium positioning through outdoor service contractors and adventure tourism operators in Indonesia's archipelago logistics corridors.
- Foldable:Compact stowage dimensions suit multi-modal transit integration in dense Asian megacities where riders combine scooter segments with rail or bus networks.
- Heavy-Duty:Extended-range generators and reinforced load-bearing structures serve last-mile delivery fleets in São Paulo negotiating steep topography with commercial payload requirements.
Commuter configurations handle the majority of throughput; heavy-duty variants are expanding most quickly on share as fleet operators professionalize procurement specifications.
End User:
Customer type stratification follows margin structure, with B2B channels capturing superior lifetime value against transactional consumer purchases.
- Delivery Services:Platform contractors in Mumbai and Mexico City drive fleet-scale procurement under subscription-based micromobility arrangements that bundle maintenance and energy costs into per-kilometer pricing.
- Urban Commuters:Individual riders in Ho Chi Minh City and Bangalore select hybrid units primarily for grid instability resilience, prioritizing petrol backup over pure-electric alternatives despite higher acquisition cost.
- Rentals:Micromobility subscription platforms in São Paulo negotiate multi-year volume commitments that transfer residual value risk to OEM financing partners while locking in route viability testing periods.
- Tour Operators:Adventure tourism providers in Indonesian island-hopping corridors deploy range-extended units where intermittent grid access precludes battery-electric deployment across dispersed geographies.
Delivery services dominate procurement volume; tour operators claim the steepest expansion trajectory as geographic underpenetration yields first-mover advantages.
Battery Technology:
Cost tier alignment governs chemistry selection, with premium lithium-ion configurations separating from legacy alternatives on performance density and cycle life.
- Lithium-Ion:2-4 kWh packs with nickel-manganese-cobalt cathodes deliver the energy density and fast-charge compatibility that fleet operators in Taiwan and South Korea demand for sub-one-hour turnaround protocols.
- Solid-State:Emerging ceramic electrolyte architectures from Japanese and South Korean tier-1 suppliers promise enhanced thermal stability for tropical climates, though manufacturing scale remains constrained.
- Nickel-Metal Hydride:Mature chemistry persists in price-sensitive commuter tiers where energy density penalties are acceptable against lower cathode material cost exposure.
- Lead-Acid:Lowest acquisition cost positions this chemistry for informal rental markets in secondary Southeast Asian cities where battery replacement frequency is tolerated against capital constraints.
Lithium-ion configurations absorb the dominant share of engineering investment; solid-state development is climbing fastest on technical priority rankings.
Charging Method:
Infrastructure availability and fleet utilization rates dictate modality preference, with speed and energy source independence as competing optimization targets.
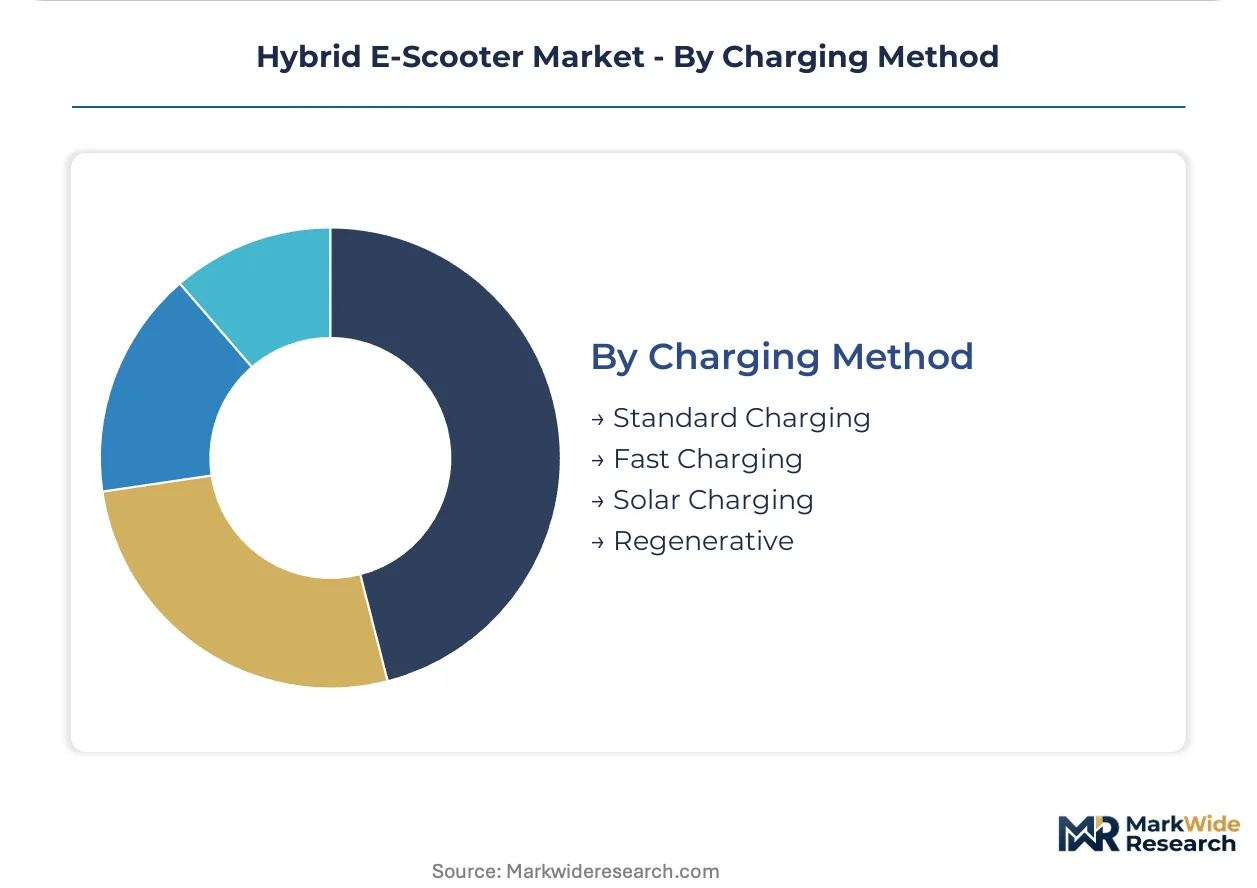
- Fast Charging:DC infrastructure deployment by fleet operators in São Paulo and Mexico City enables sub-one-hour turnaround that supports commercial vehicle utilization above twelve hours daily.
- Regenerative:Kinetic recovery systems integrated into braking architectures extend effective range in stop-start urban environments like Jakarta and Manila without infrastructure dependency.
- Standard Charging:Overnight AC protocols suit individual commuters with predictable daily mileage below generator-assisted range thresholds.
- Solar Charging:Photovoltaic-integrated units serve outdoor service contractors and emergency response fleets requiring complete grid independence in remote Indonesian corridors.
Fast charging commands the largest capital deployment; regenerative systems are gaining specification fastest as software-defined energy management advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Dutch corporate procurement channels while Indonesian fleet operators negotiate on thinner margins. This asymmetry shapes manufacturer prioritization of certification investments and subsidy navigation across markets.
India
Mumbai and Bangalore last-mile delivery fleets drive procurement volume under FAME II subsidy arrangements that reduce battery pack costs for domestic assembly. The Automotive Research Association enforces localization thresholds under the PLI scheme that reshape battery sourcing decisions. Manufacturing clusters in Tamil Nadu and Gujarat concentrate hybrid unit production for export to Southeast Asian markets.
Germany
Employer mobility subsidy programs in Berlin and Munich expand eligibility to hybrid two-wheelers, opening B2B procurement channels with superior lifetime value. KBA administers L-category vehicle directives that mandate specific braking and lighting standards for EU-type approval. The Baden-Württemberg industrial corridor hosts engineering centers developing compact generator synchronization systems.
Indonesia
Island-hopping delivery corridors across the archipelago create persistent demand for range-extended units where intermittent grid access precludes battery-electric deployment. The national energy ministry regulates fuel subsidy allocations that indirectly affect hybrid operating economics. Javanese manufacturing zones near Surabaya assemble units for domestic distribution and regional export.
United States
FCC certification requirements for wireless connectivity modules govern US-bound fleet telematics, adding 4-6 month approval delays relative to EU timelines. California Air Resources Board zero-emission zone pilots in Los Angeles and San Francisco create regulatory tension with range requirements. Southwest distribution networks concentrate inventory for last-mile delivery platform contractors.
Vietnam
Ho Chi Minh City grid instability drives individual rider preference for petrol backup despite higher acquisition costs against pure-electric alternatives. The Ministry of Transport oversees vehicle registration categories that determine access to municipal permit schemes. Mekong Delta logistics corridors deploy hybrid units for agricultural supply chain connectivity where charging infrastructure remains sparse.
Hybrid E-Scooter Market Competitive Landscape
Captive engine manufacturers and integrated motor-control specialists split the market between mechanical refinement and software-defined differentiation. The vendor base concentrates around three strategic archetypes: legacy powersports conglomerates with captive manufacturing expertise, robotics-heritage entrants competing on software-defined ride dynamics, and regional assemblers optimizing for subsidy-heavy procurement channels. Dominant competitive moves include backward integration into precision-engineered generator components and geographic expansion through fleet-as-a-service partnership structures.
Among legacy powersports conglomerates, Honda and Yamaha anchor the mechanical refinement tier through established Asian distribution networks and integrated powertrain development. Segway occupies a position within the software-centric archetype, leveraging robotics heritage for algorithmic energy management. TVS Motor represents the regional specialist model, concentrating procurement relationships with Indian fleet operators navigating FAME II incentive structures.
| Leading Market Players |
|---|
| Suzuki |
| Navee |
| Honda |
| Apollo |
| Kaabo |
| Yamaha |
| Segway |
| Ultraviolet |
| TVS Motor |
| Others |
Supply & Pricing Matrix
Lithium carbonate price volatility compresses margin buffers for 2-4 kWh pack configurations, forcing manufacturers toward smaller battery capacities while simultaneously widening spreads between premium configured-to-order fleet units and standard commuter SKUs. This feedstock instability cascades through procurement decisions, tethering pricing tier differentiation to cathode material sourcing flexibility and generator component localization.
Pricing Analysis
Configured-to-order pricing for heavy-duty fleet units commands substantial premiums over standard commuter configurations due to reinforced frame architectures and extended-range generator synchronization. Three-tier pricing structure across premium, standard, and economy levels separates certification-grade fleet equipment from municipal permit-scheme commuter models and informal rental-market entry units. Cost compression in the economy tier is intensifying because lead-acid chemistry persists in price-sensitive secondary cities. Delivery services and platform contractors exhibit highest price sensitivity due to per-kilometer operating economics, while tour operators in Indonesian archipelago corridors accept premium positioning for grid-independence capability.
Supply Chain Analysis
Upstream feedstock concentration in Chilean lithium brine operations, Indonesian nickel laterite mining, and Chinese cathode active material processing anchors cell cost structures for 2-4 kWh configurations. Precision-engineered generator components draw from Japanese and German industrial clusters, while lithium-ion cell assembly concentrates in South Korea and China. Single-source vulnerability in refined cobalt supply from the DRC exposes margin buffers to geopolitical disruption. Distribution runs through established Asian powersports dealer networks for consumer channels and direct fleet-as-a-service partnerships for B2B procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain calibration expertise shortage extends development cycles and inflates R&D payrolls, concentrating competitive advantage among organizations with captive combustion-engineering and motor-control algorithm capabilities.
For Market Incumbents: Build captive generator-manufacturing expertise to defend against pure-electric substitution pressure from swappable battery networks in Taiwan and South Korea. Secure dual-certification engineering capacity for simultaneous EU-type approval and FCC modular certification to compress US market entry timelines. Expand backward integration into precision-machined range-extender components to capture margin otherwise surrendered to Tier-1 suppliers in Japan and South Korea. For New Entrants and Emerging Players: Indonesian island-hopping delivery corridors with intermittent grid access represent the most penetrable entry point for range-extended units against battery-electric alternatives. Employer mobility subsidy programs in Germany and the Netherlands offer B2B procurement channels with superior lifetime value against transactional consumer sales. Pursue fleet-as-a-service partnership structures that transfer residual value risk to financing partners while locking in multi-year volume commitments from São Paulo logistics platforms. For Investors and Strategic Acquirers: EU Green Deal implementation reshapes the acquisition landscape by mandating third-party lifecycle emissions verification for L-category vehicle supply chains. Five-to-ten-year viability hinges on software-defined energy management capabilities displacing hardware-centric differentiation. Target acquisition candidates with cloud-based digital twin validation platforms and bidirectional charging hardware integration. Monitor Gogoro network expansion coverage maps as the critical signal for hybrid value proposition erosion versus pure-electric substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Generator Synchronization System Development | Compact sub-50cc range extenders eliminate range anxiety while preserving urban zero-emission capability for Jakarta and Manila fleets. |
| FCC Modular Certification Investment | Wireless connectivity approval for fleet telematics reduces US market entry delays relative to EU-type approval timelines. |
| Digital Twin Thermal Management Platform | Cloud-based validation compresses hybrid powertrain development cycles from eighteen months to under twelve months. |
| Vehicle-to-Load Hardware Integration | Bidirectional charging enables mobile power source applications for outdoor service contractors and emergency response fleets. |
| Archipelago Logistics Partnership Structure | Fleet-as-a-service contracts in Indonesian corridors transfer residual value risk while testing route viability before capital deployment. |
Research Methodology
Operator-level perspectives from fleet procurement managers at Mumbai and São Paulo delivery platforms, powertrain engineering leads at Japanese and South Korean Tier-1 suppliers, and regulatory affairs specialists navigating FAME II and EU-type approval pathways anchored the qualitative base. Secondary validation drew from Automotive Research Association localization threshold documentation, KBA L-category vehicle directive filings, and FCC equipment authorization databases. Bottom-up unit economics modeling for commuter, heavy-duty, and off-road configurations triangulated against top-down market sizing from production cluster output in Tamil Nadu, Gujarat, and Javanese manufacturing zones.
Scenario-bracketing around lithium carbonate price volatility bands and Euro 5+ emission compliance phase-out schedules structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, end-user archetype, battery chemistry tier, and charging modality preference. CAGRs were derived from elasticity-adjusted adoption curves for fleet operators versus individual commuters. Industry-specific forecast inputs incorporated employer mobility subsidy program expansion eligibility in Germany and the Netherlands, plus Gogoro network coverage density as a pure-electric substitution threshold indicator.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot pricing, Indonesian fuel subsidy allocations, or EU Green Deal implementation pace would shift the trajectory. Forecasts reflect documented assumptions regarding FAME II continuation and FCC certification timeline stability. Cross-checking against IEA critical minerals supply projections and ASEAN automotive production databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
New Zealand E-Bike Market