
 Solar Car Market | 2026-2036
Solar Car Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Car Market Insights
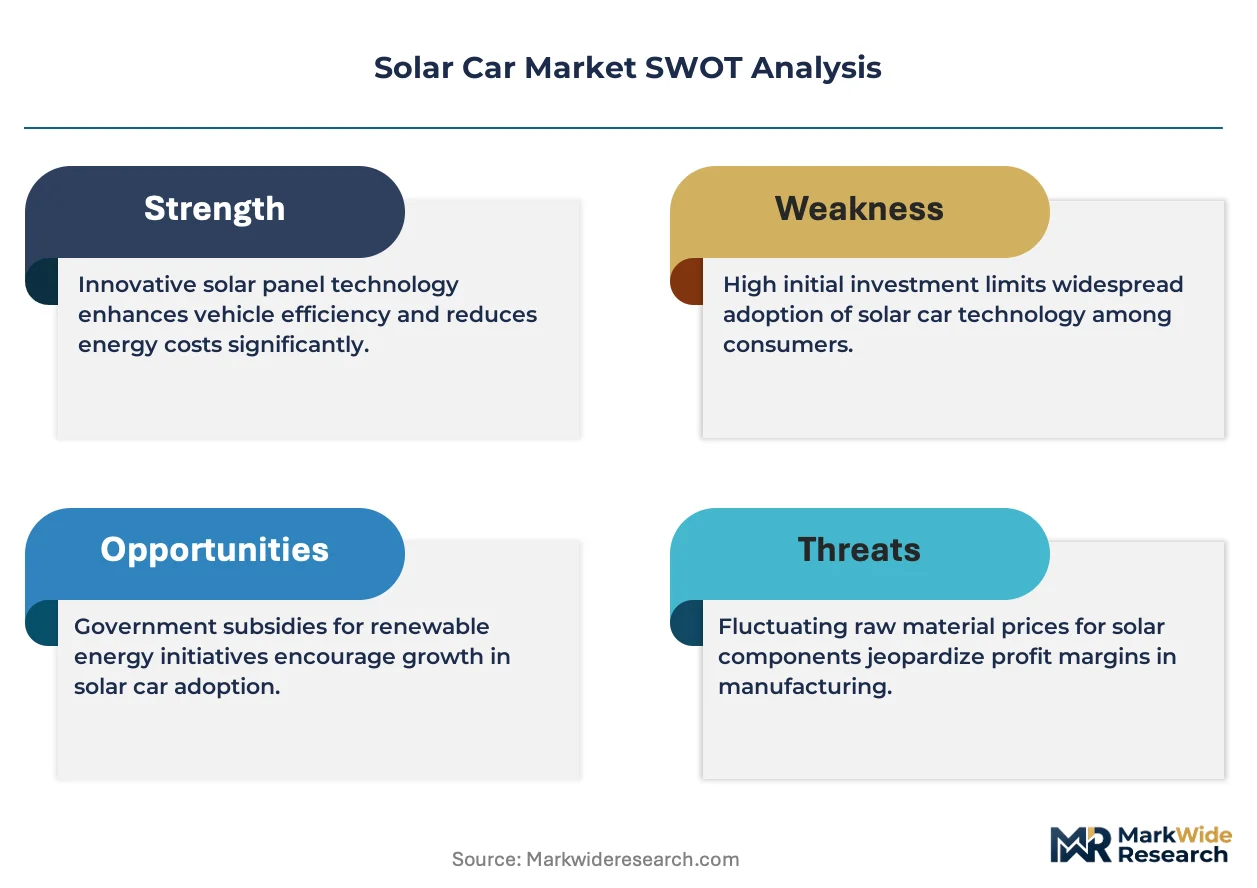
Asset-light leasing and project finance for solar vehicle fleets is fragmenting the competitive landscape by lowering capital barriers for new entrants. Sono Motors leverages integrated solar bodywork to differentiate its commercial vehicle offerings. Lightyear Technologies anchors its position through aerodynamic efficiency paired with high-yield panel surfaces. Toyota Motor Corporation sustains R&D intensity across hybrid-solar architectures spanning multiple vehicle classes.
A solar car integrates photovoltaic cells into vehicle body panels to convert sunlight into electrical energy for propulsion or auxiliary power, typically achieving conversion efficiencies between twenty and twenty-six percent depending on cell chemistry. These vehicles serve commercial and consumer markets seeking reduced grid dependency and lower lifetime energy costs. Passenger cars dominate current deployment volumes while commercial vehicles command stronger margin pools due to fleet-scale procurement and total cost of ownership calculations. Monocrystalline panel technology leads in efficiency metrics though thin-film alternatives gain traction where weight reduction and curved surface conformity matter more than peak output.
Germany's KBA enforces type-approval standards that shape solar panel mounting safety and electromagnetic compatibility for road vehicles. Japan's METI channels funding toward next-generation mobility technologies including solar-assisted platforms through its green innovation programs. The EU Green Deal and associated CO2 fleet targets push automakers to explore solar range extension as a compliance pathway. Stakeholders must monitor how regulatory treatment of solar-derived kilometers affects vehicle classification and incentive eligibility across jurisdictions.
Market Dynamics
Thin-film photovoltaic integration is compressing the energy yield-to-weight ratio, forcing chassis designers to reallocate surface area budgets toward maximum solar capture rather than aesthetic contours.
Growth Catalysts
- EU Green Deal CO2 fleet targets:Automakers in Germany, France, and Italy face binding emission ceilings that solar range extension helps satisfy without full powertrain redesign.
- Fleet-scale procurement in urban logistics:Last-mile delivery operators across the Netherlands and Japan calculate total cost of ownership advantages from reduced grid charging frequency.
- Monocrystalline efficiency gains:Laboratory advances pushing conversion rates toward the upper bound of twenty-six percent expand viable deployment geographies with lower insolation profiles.
Market Restraints
- Indium and gallium supply concentration:Thin-film manufacturing depends on rare earth elements concentrated in Chinese processing facilities, creating input cost volatility.
- KBA type-approval timelines:Germany's Federal Motor Transport Authority mandates electromagnetic compatibility testing that extends certification cycles for integrated solar bodywork.
- Weight penalty of structural integration:Encapsulation layers and reinforcement requirements add mass that partially offsets energy harvest gains.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic solar vehicle manufacturing incentives align with the country's dual carbon goals and charging infrastructure gaps.
- Vehicle-to-grid integration:Bidirectional charging protocols enable solar-equipped fleets to sell excess generation back to utilities during peak demand windows.
- Curved surface conformity in commercial vans:Flexible thin-film architectures unlock roof and sidewall deployment on boxy logistics vehicles previously unsuited to rigid panels.
Industry Challenges
- Photovoltaic thermal management engineering:Cell efficiency degrades at elevated temperatures, requiring cooling system integration that competes for packaging space.
- Multi-jurisdiction homologation complexity:Divergent electromagnetic standards between Japan's METI protocols and EU CE marking force redundant testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Car Market |
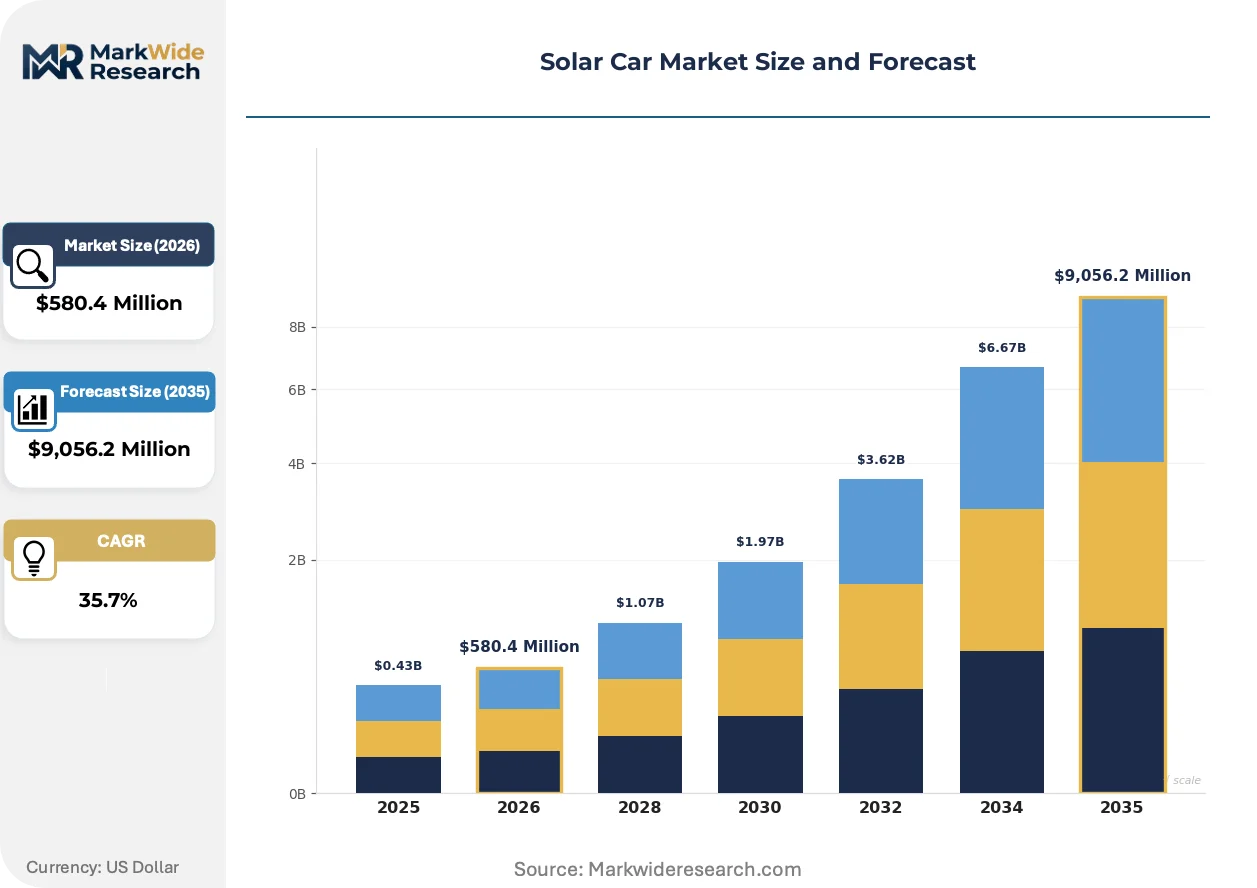
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $9,056.2 Million |
| CAGR (2026 – 2036) | 35.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Buses Panel Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Power Output: Less than 50kW, 50kW - 100kW, 100kW - 200kW, More than 200kW Battery Type: Lithiun-ion, Lead Acid, Nickel-metal Hydride, Others |
| Companies Covered | Sono Motors, Lightyear Technologies, Aptera Motors, Toyota Motor Corporation, Ford Motor Company, Hyundai Motor Company, Mahindra and Mahindra, Fisker Inc., Venturi Automobiles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Car Market Trends and Innovations
Solar vehicle engineering is abandoning the aftermarket retrofit model in favor of ground-up architectural integration, embedding photovoltaics into structural composites rather than superficial appliqués.
Perovskite-silicon tandem cells are virtualizing the efficiency ceiling for vehicle-integrated photovoltaics. Toyota and Hyundai's supplier networks are piloting these stacks for 2026 model year integration. The technology is virtualizing the traditional trade-off between surface area and range extension, enabling meaningful energy contribution from hood and trunk lid deployments previously dismissed as marginal.
Japan's METI green innovation funding channels direct subsidies toward solar-assisted mobility platforms through its next-generation vehicle program. The industrial consequence is a concentration of pilot fleet deployments in Kansai and Kanto prefectures. Commercial van operators there are responding by trialing solar range extension as a compliance pathway ahead of 2030 carbon neutrality commitments for corporate fleets.
Fleet managers are consolidating procurement authority away from decentralized regional units toward centralized sustainability offices with power purchase agreement expertise. The direct sales channel is displacing traditional dealer networks for commercial solar vehicle transactions. This concentration is most visible in Germany's Mittelstand logistics sector, where family-owned operators now negotiate directly with Sono Motors and Lightyear Technologies for fifty-plus unit contracts.
Solar Car Market Segmentation
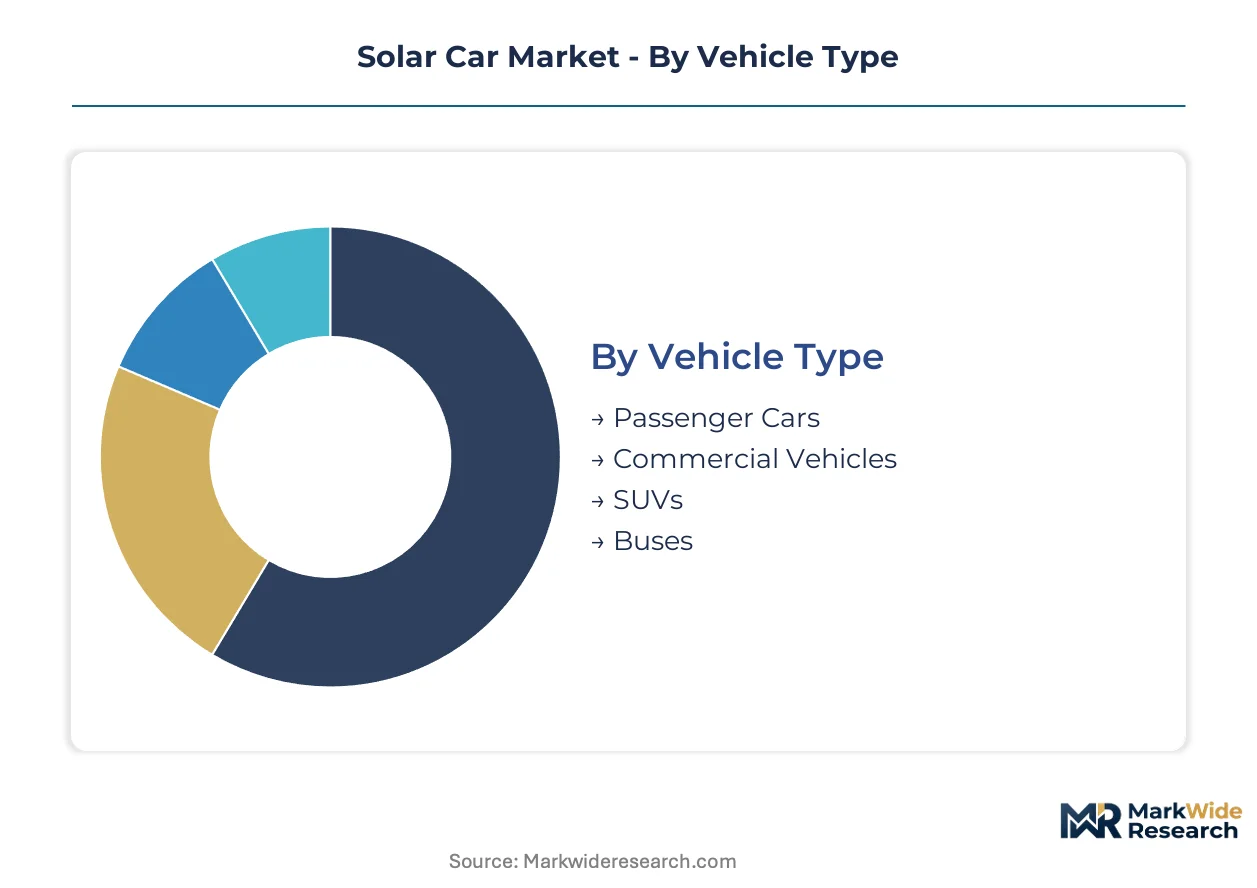
Solar car segmentation reveals how photovoltaic integration strategies diverge across vehicle architectures and energy system designs. Procurement patterns in Germany, Japan, and the Netherlands demonstrate that segment selection directly determines regulatory pathway, supply chain partner, and total cost of ownership calculus.
Vehicle Type:
Application context shapes solar surface area budgets, aerodynamic constraints, and fleet-scale procurement economics across mobility platforms.
- Passenger Cars:Hood, roof, and trunk lid deployments maximize energy harvest within aesthetic and drag coefficient limits. German consumer demand concentrates here as KBA type-approval frameworks mature for integrated bodywork designs.
- Commercial Vehicles:Box van and light truck architectures offer expansive flat roofs for high-yield panel arrays. Fleet operators in Dutch urban logistics calculate total cost of ownership advantages from reduced charging frequency.
- SUVs:Larger surface areas accommodate higher wattage installations, though elevated ride heights complicate aerodynamic optimization.
- Buses:Extensive roof real estate supports substantial photovoltaic arrays, with Japanese transit authorities piloting solar range extension for intercity routes.
Passenger cars command the established base. The steepest expansion runs through commercial vehicles.
Panel Technology:
Cell chemistry selection trades conversion efficiency against weight, flexibility, and supply chain concentration in vehicle-integrated photovoltaic systems.
- Monocrystalline:Laboratory advances push conversion rates toward twenty-six percent, expanding viable deployment geographies with lower insolation profiles. German manufacturers prioritize this technology for premium passenger applications.
- Thin-Film:Flexible architectures conform to curved body panels while compressing energy yield-to-weight ratios. Indium and gallium supply concentration in Chinese processing facilities creates input cost volatility.
- Polycrystalline:Lower manufacturing costs suit price-sensitive fleet procurement, though efficiency gaps limit range extension contribution.
- Bifacial:Dual-sided energy capture from reflected light enhances output in high-albedo environments, with Japanese test fleets evaluating urban deployment viability.
Monocrystalline technology anchors current production volumes. Thin-film alternatives are climbing the fastest as weight-critical applications multiply.
Power Output:
Motor rating tiers align with vehicle mass, duty cycle intensity, and auxiliary load requirements across solar-assisted mobility platforms.
- Less than 50kW:Compact urban runabouts and micro-mobility platforms leverage low power draws to maximize solar contribution share.
- 50kW - 100kW:Standard passenger car and light commercial applications balance performance with photovoltaic-assisted range extension.
- 100kW - 200kW:Premium passenger vehicles and medium-duty logistics trucks require substantial battery buffers alongside solar supplementation.
- More than 200kW:Heavy commercial and high-performance applications where solar serves auxiliary systems rather than primary propulsion.
The 50kW - 100kW bracket holds the dominant installed base. Below-50kW systems are expanding most quickly as urban congestion pricing accelerates compact vehicle demand.
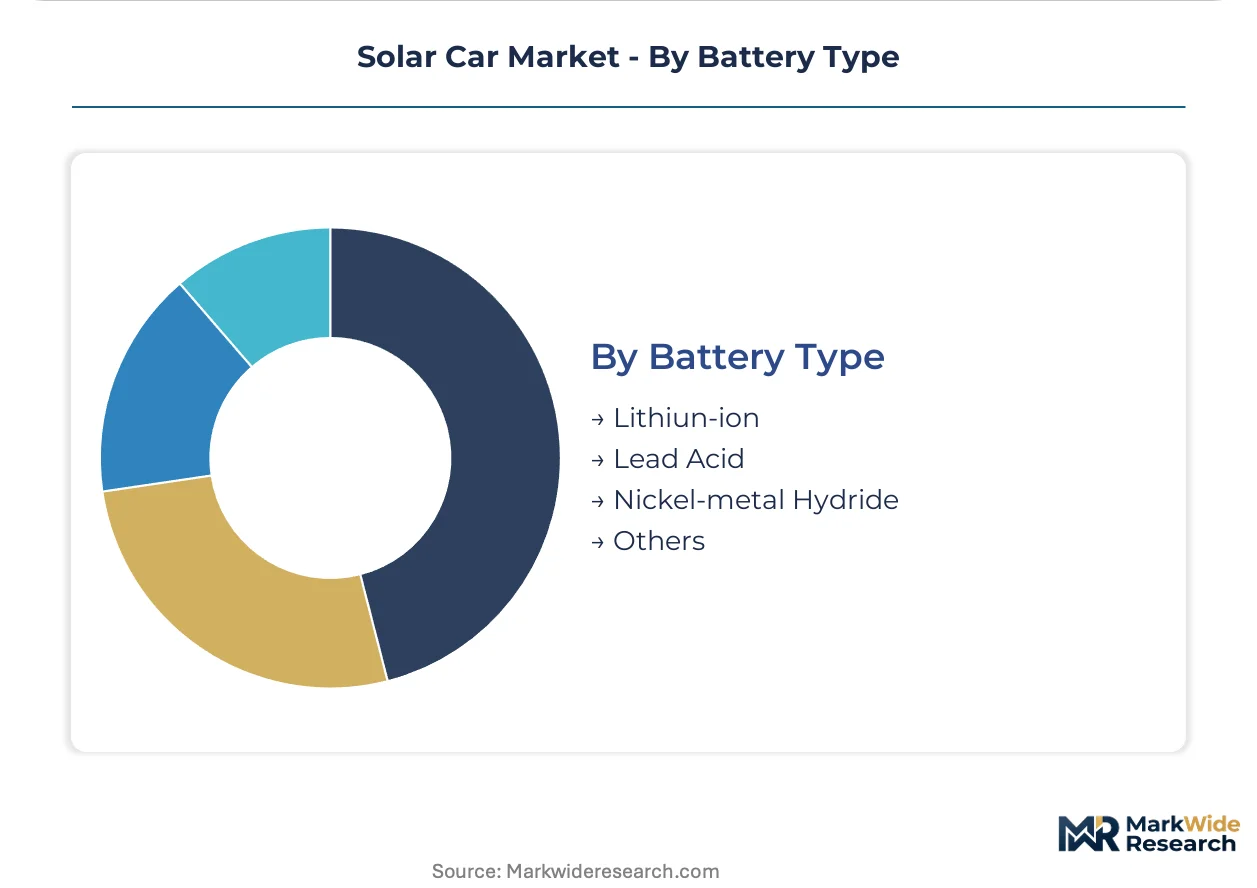
Battery Type:
Energy storage chemistry determines charge acceptance rates, thermal management complexity, and lifecycle economics in solar-hybrid architectures.
- Lithium-ion:Dominant chemistry for solar vehicle integration, offering high energy density and rapid charge acceptance from intermittent photovoltaic generation.
- Lead Acid:Limited to auxiliary power and legacy fleet conversions where capital constraints outweigh energy density requirements.
- Nickel-metal Hydride:Toyota's hybrid-solar architectures sustain R&D investment in this chemistry for thermal stability in extreme climates.
- Others:Emerging solid-state and sodium-ion chemistries under evaluation for next-generation solar vehicle platforms.
Lithium-ion systems command the established base. Alternative chemistries are gaining share fastest as supply diversification priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing power through KBA type-approval maturity while India's PLI scheme compresses manufacturing costs for export-bound solar vehicle components. This asymmetry redistributes value capture toward regulatory gatekeepers and away from pure production economies.
Germany
Fleet operators in the Mittelstand logistics sector drive commercial vehicle procurement through direct manufacturer negotiations. The KBA enforces electromagnetic compatibility testing that extends certification timelines for integrated solar bodywork. Stuttgart and Munich anchor R&D clusters where Sono Motors and Lightyear Technologies maintain engineering facilities.
Japan
Corporate fleet carbon neutrality commitments for 2030 accelerate pilot deployments of solar-assisted commercial vans. METI channels direct subsidies toward next-generation mobility platforms through its green innovation program. Kansai and Kanto prefectures concentrate test fleet operations as logistics operators trial range extension ahead of regulatory deadlines.
Netherlands
Urban logistics operators calculate total cost of ownership advantages from reduced grid charging frequency in dense municipal delivery zones. EU Green Deal CO2 fleet targets push commercial vehicle procurement toward self-sufficient mobility platforms. Rotterdam and Amsterdam host concentrated pilot programs for last-mile solar-assisted delivery fleets.
India
Charging infrastructure gaps in tier-2 and tier-3 cities create demand for grid-independent commercial vehicle solutions. The PLI scheme for advanced chemistry cells subsidizes domestic solar vehicle manufacturing capacity. Gujarat and Tamil Nadu industrial corridors attract component assembly investments aligned with dual carbon goals.
United States
California's zero-emission vehicle mandates and federal IRA clean vehicle credits reshape fleet procurement mathematics for solar-assisted platforms. NHTSA safety standards govern photovoltaic integration into structural body panels. The San Francisco Bay Area and Southern California host development clusters for aerodynamic solar vehicle architectures.
Solar Car Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying photovoltaic cells, power electronics, and lightweight chassis materials. The market structure fragments across asset-light leasing intermediaries, integrated OEM programs, and pure-play solar vehicle developers. Three archetypes dominate: aerodynamic efficiency optimizers, fleet-scale commercial vehicle suppliers, and hybrid-solar architecture incumbents. Competitive moves concentrate on strategic partnerships for charging infrastructure access and technology licensing for curved-surface panel integration.
Within the integrated solar bodywork tier, Sono Motors and Lightyear Technologies exemplify divergent technical approaches to vehicle-integrated photovoltaics. Toyota Motor Corporation occupies a position bridging conventional hybrid architectures with solar range extension programs. These three entities represent the spectrum from pure-play solar-first engineering to incumbent automaker portfolio diversification.
| Leading Market Players |
|---|
| Sono Motors |
| Lightyear Technologies |
| Aptera Motors |
| Toyota Motor Corporation |
| Ford Motor Company |
| Hyundai Motor Company |
| Mahindra and Mahindra |
| Fisker Inc. |
| Venturi Automobiles |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor absorbs volatile indium and gallium shipping costs, compressing margins for thin-film panel integrators while amplifying price spreads between configured-to-order commercial fleets and standard passenger variants.
Pricing Analysis
Configured-to-order commercial van deployments command substantial premiums over standard passenger configurations due to fleet-scale customization requirements and KBA electromagnetic certification tiers. Price differentiation separates premium integrated bodywork from standard retrofit architectures, with monocrystalline-equipped vehicles occupying the top tier. Cost compression in thin-film segments is intensifying because indium supply volatility feeds through to panel pricing. Fleet procurement offices exhibit lowest price sensitivity, while individual consumer buyers in Germany and Japan demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for indium and gallium-dependent thin-film manufacturers. Photovoltaic cell production concentrates in China, South Korea, and Japan, with Germany anchoring downstream chassis integration and KBA certification. Raw material flows draw from Australian gallium refining, Chinese indium processing, and South Korean silicon wafer production. Single-source vulnerability in rare earth element purification creates systemic exposure. Distribution runs through direct manufacturer-to-fleet contracts rather than traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar vehicle platforms are approaching an interoperability inflection where bidirectional charging protocols and vehicle-to-grid standards determine ecosystem lock-in, with Japan's METI green innovation program accelerating this shift through subsidized pilot architectures.
For Market Incumbents: Harden defensive positions through captive supply of monocrystalline wafers and accelerated KBA type-approval investments. Toyota's hybrid-solar R&D intensity demonstrates how incumbent scale can absorb thin-film supply shocks. Prioritize backward integration into gallium refining partnerships to offset Chinese processing concentration.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 commercial logistics corridors where PLI-subsidized battery assembly meets charging infrastructure gaps. Curved-surface thin-film conformity for box van sidewalls represents the most penetrable technical white space. Pursue direct fleet procurement relationships bypassing established dealer networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive suppliers with stranded photovoltaic integration capabilities and dormant KBA certification pathways. Long-term viability hinges on vehicle-to-grid revenue stream maturation rather than hardware margins alone. Monitor METI subsidy renewal trajectories as the inflection signal for Japanese market depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Bodywork Integration | Ground-up architectural embedding replaces retrofit models, tightening KBA electromagnetic compliance requirements. |
| Thin-Film Supply Agreement | Long-term indium and gallium offtake contracts buffer against Chinese processing concentration volatility. |
| Bidirectional Charging Protocol | Vehicle-to-grid interoperability unlocks auxiliary revenue streams for fleet operators during peak demand windows. |
| Curved Surface Conformity R&D | Flexible panel architectures expand deployable surface area on commercial van sidewalls and hood contours. |
| Direct Fleet Procurement Channel | Centralized sustainability offices displace dealer networks, compressing transaction costs for fifty-plus unit contracts. |
Research Methodology
The analysis maps monocrystalline passenger applications, thin-film commercial deployments, and hybrid-solar architectures, each validated through fleet procurement directors, KBA certification engineers, METI program officers, and photovoltaic supply chain managers. Primary fieldwork combined structured interviews with Tier 1 supplier procurement leads and OEM platform engineers, cross-referenced against secondary validation from EU Green Deal regulatory filings, METI green innovation disbursement records, and vehicle production registration databases. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Fixed assumptions held technology conversion efficiency trajectories and KBA certification timeline parameters constant, while varying PLI scheme uptake rates and fleet carbon neutrality commitment pacing across the projection horizon. Segmentation dimensions modeled include vehicle class, panel technology chemistry, power output tier, and regional regulatory cluster. CAGRs derived from installed base growth rates and average selling price evolution, with specific inputs from charging infrastructure gap indices and rare earth element price volatility bands.
Sensitivities concentrate around METI subsidy renewal decisions, EU Green Deal CO2 fleet target stringency adjustments, and indium supply disruption scenarios. Forecasts reflect documented assumptions about technology maturation curves and fleet procurement cycle timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Electric Moped Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market