
 Light Electric Vehicle Market | 2026-2036
Light Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Light Electric Vehicle Market Outlook
Fleet operators is rotating toward light electric vehicles for urban logistics, displacing individual consumer purchases as the dominant buyer archetype. NIU Technologies dominates the smart e-scooter segment through connected-vehicle platforms and direct-to-fleet sales channels. Yadea Technology Group Co Ltd anchors mass-market e-bike production with integrated battery manufacturing and expansive dealer networks across Asia. Continental AG competes in powertrain components, supplying motor controllers and battery management systems to multiple LEV OEMs.
A light electric vehicle encompasses electrically powered two- and three-wheel transport with motor ratings typically below four kilowatts and operating speeds restricted to urban road limits, designed for short-distance mobility and cargo carriage. E-bikes lead product type volume due to lower price points and minimal licensing barriers, while solid-state battery technology attracts R&D investment for energy density gains. E-scooters concentrate margin pools in rental services, where asset utilization rates and subscription pricing offset higher per-unit depreciation. Delivery services represent the fastest-expanding target audience segment, driven by e-commerce fulfillment density and curbside drop mandates.
The EPA enforces emissions standards that indirectly accelerate LEV adoption by restricting internal-combustion alternatives in dense urban zones, while the EU F-Gas Regulation shapes thermal management system design for battery cooling circuits. India's CEA mandates charger interoperability standards that determine market access for imported hardware. Stakeholders must monitor how fragmented charging infrastructure certification across jurisdictions affects cross-border product deployment and service network economics.
Market Dynamics
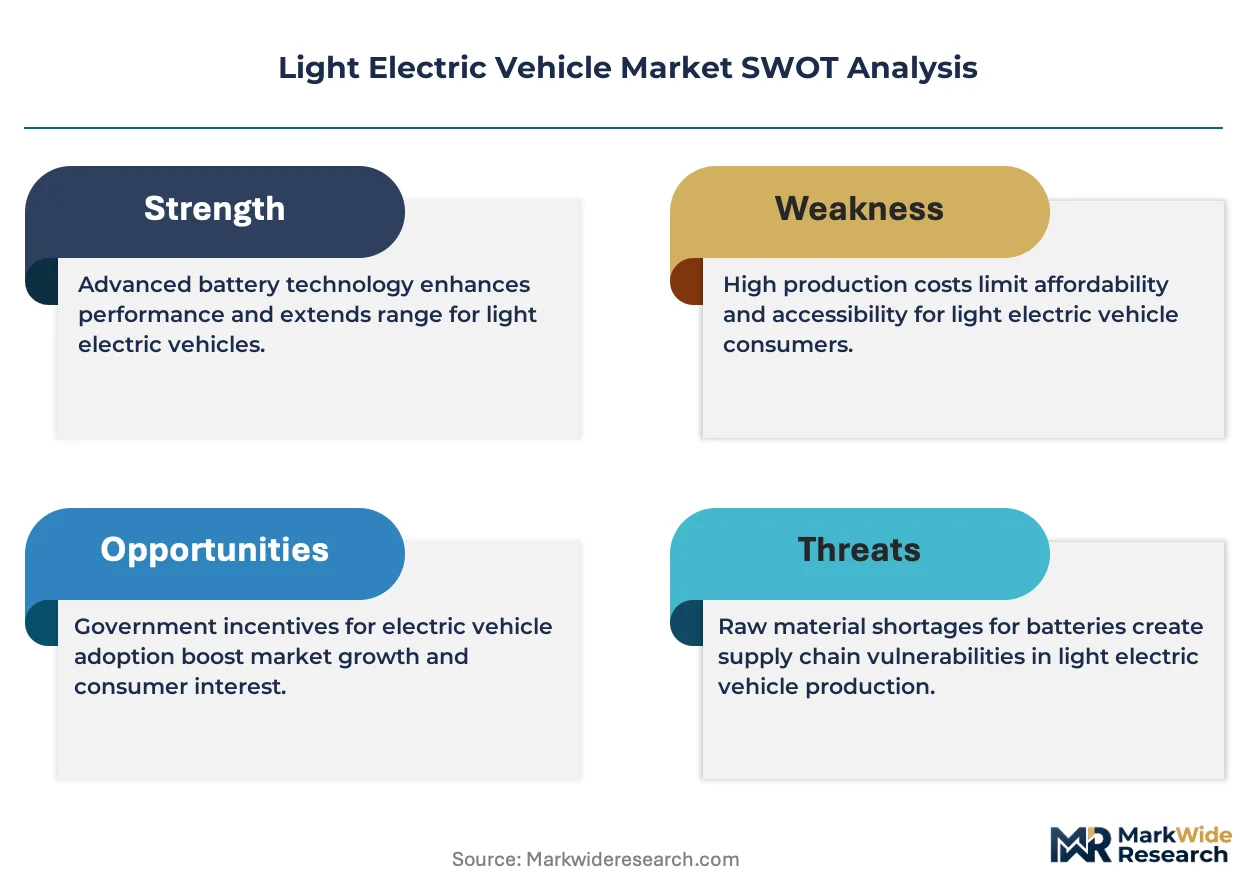
Fleet procurement of e-cargo bikes and compact electric vans is displacing individual consumer purchases as the dominant demand vector, while battery chemistry regulations in the European Union and China's GB standards tighten certification requirements for cell safety.
Growth Catalysts
- Last-mile logistics densification:E-commerce fulfillment networks in India, Germany, and the Netherlands are expanding e-cargo bike fleets to meet curbside drop mandates and congestion pricing exemptions.
- FAME scheme subsidies:India's two-wheeler electrification targets accelerate domestic manufacturing scale-up through production-linked incentives and charger interoperability mandates under CEA authority.
- Solid-state battery R&D:Energy density gains from ceramic electrolyte architectures promise extended range for urban delivery routes without thermal runaway risks.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for NMC and LFP cell chemistries create margin compression for integrated battery producers.
- Charger certification fragmentation:Divergent CEA interoperability standards in India, EPA emissions-adjacent restrictions in the United States, and EU F-Gas thermal management rules complicate cross-border hardware deployment.
- Internal combustion substitution in rural corridors:Petrol-powered two-wheelers retain total cost of ownership advantages where electricity grid reliability remains intermittent.
Strategic Opportunities
- Sub-Saharan African urban corridors:Kenya, Nigeria, and Rwanda present underpenetrated demand for solar-charged e-motorcycles in motorcycle-taxi economies.
- Battery-as-a-service models:Swappable powertrain architectures decouple vehicle purchase from energy storage capital expenditure, lowering fleet operator entry barriers.
- Connected-vehicle platform convergence:Integration of telematics, predictive maintenance, and route optimization software creates recurring revenue streams beyond hardware sales.
Industry Challenges
- Battery management system firmware certification:ISO 26262 functional safety validation timelines extend product development cycles by 8-14 months.
- Thermal engineering talent scarcity:Specialized expertise in liquid cooling circuit design and F-Gas-compliant refrigerant selection concentrates in German and Japanese automotive supplier clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Electric Vehicle Market |
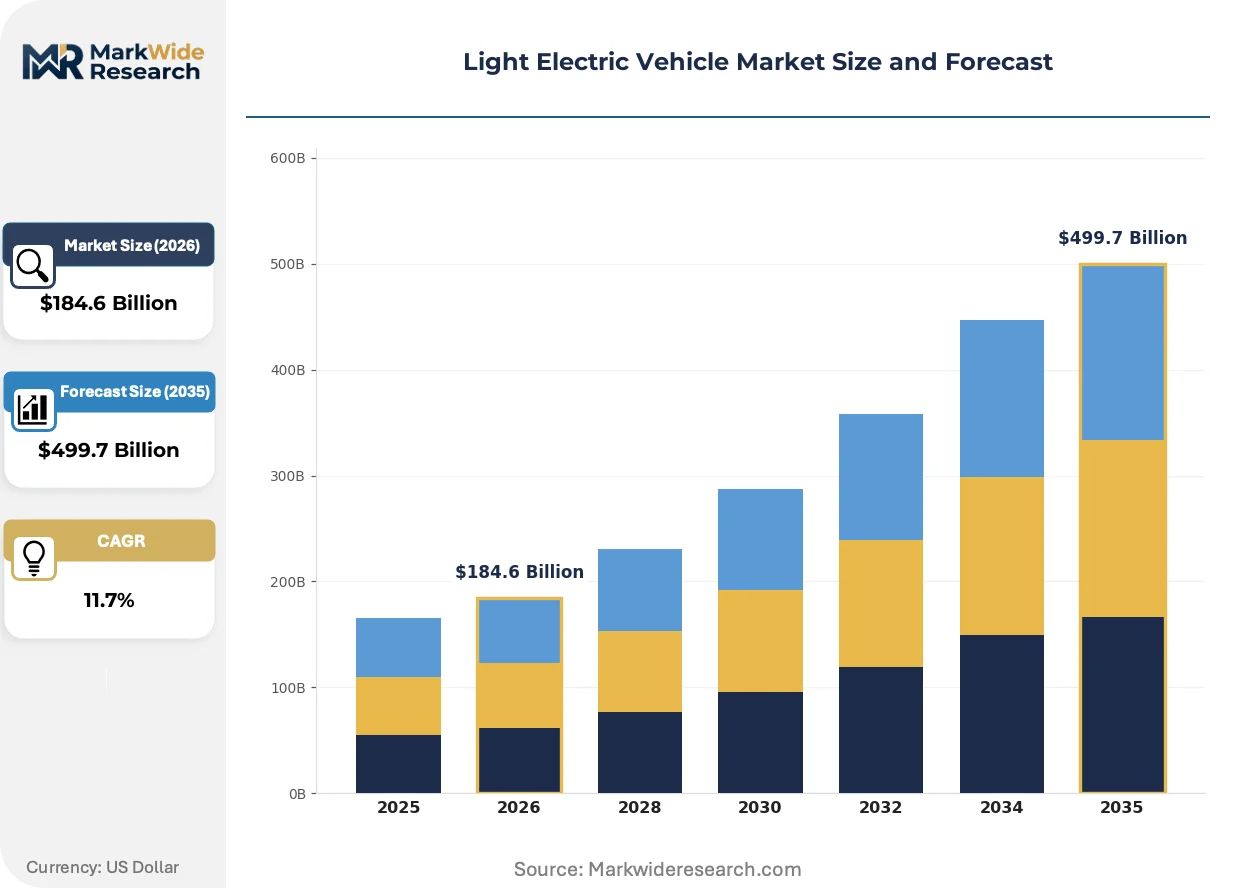
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $499.7 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-Scooters, E-Bikes, E-Mopeds, E-Motorcycles Battery Technology: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Solid-State Charging Infrastructure: Home Chargers, Public Charging Stations, Fast Chargers, Wireless Charging Target Audience: Urban Commuters, Recreational Users, Delivery Services, Rental Services |
| Companies Covered | Accelerated Systems Inc., Addax Motors, Aisin Corporation, Alke, Columbia Vehicle Group Inc., Continental AG, Crystalyte Motors, NIU Technologies, Yadea Technology Group Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Electric Vehicle Market Strategic Shifts
Battery chemistry and thermal management architectures are actively reshaping competitive differentiation, while procurement patterns and regulatory compliance timelines compress product development cycles.
Solid-state battery technology is bifurcating the powertrain supplier landscape. Ceramic electrolyte cells eliminate liquid electrolyte fire risks while enabling 400+ Wh/kg energy density. Premium fleet operators in the Netherlands and Denmark are pilot-testing solid-state packs for refrigerated e-cargo applications. The technology is bifurcating vendor tiers into integrated cell producers versus pack assemblers dependent on external supply.
The EU F-Gas Regulation is forcing redesign of battery thermal management circuits. Restrictions on hydrofluorocarbon refrigerants mandate adoption of CO2-based or phase-change cooling systems for high-discharge-rate applications. German and French OEMs are retooling assembly lines to accommodate heavier, more complex cooling hardware. E-scooter rental fleets operating in Mediterranean climates face the steepest compliance cost escalation.
Direct-to-fleet sales channels are eroding traditional dealer network economics. Large logistics operators in India and Germany now specify vehicles through procurement tenders that bundle hardware, software, and maintenance subscriptions. NIU Technologies and similar platform-native vendors capture margin pools that previously accrued to regional distributors. This channel shift concentrates most visibly in metropolitan last-mile delivery verticals where asset utilization rates determine total cost of ownership calculations.
Light Electric Vehicle Market Segmentation
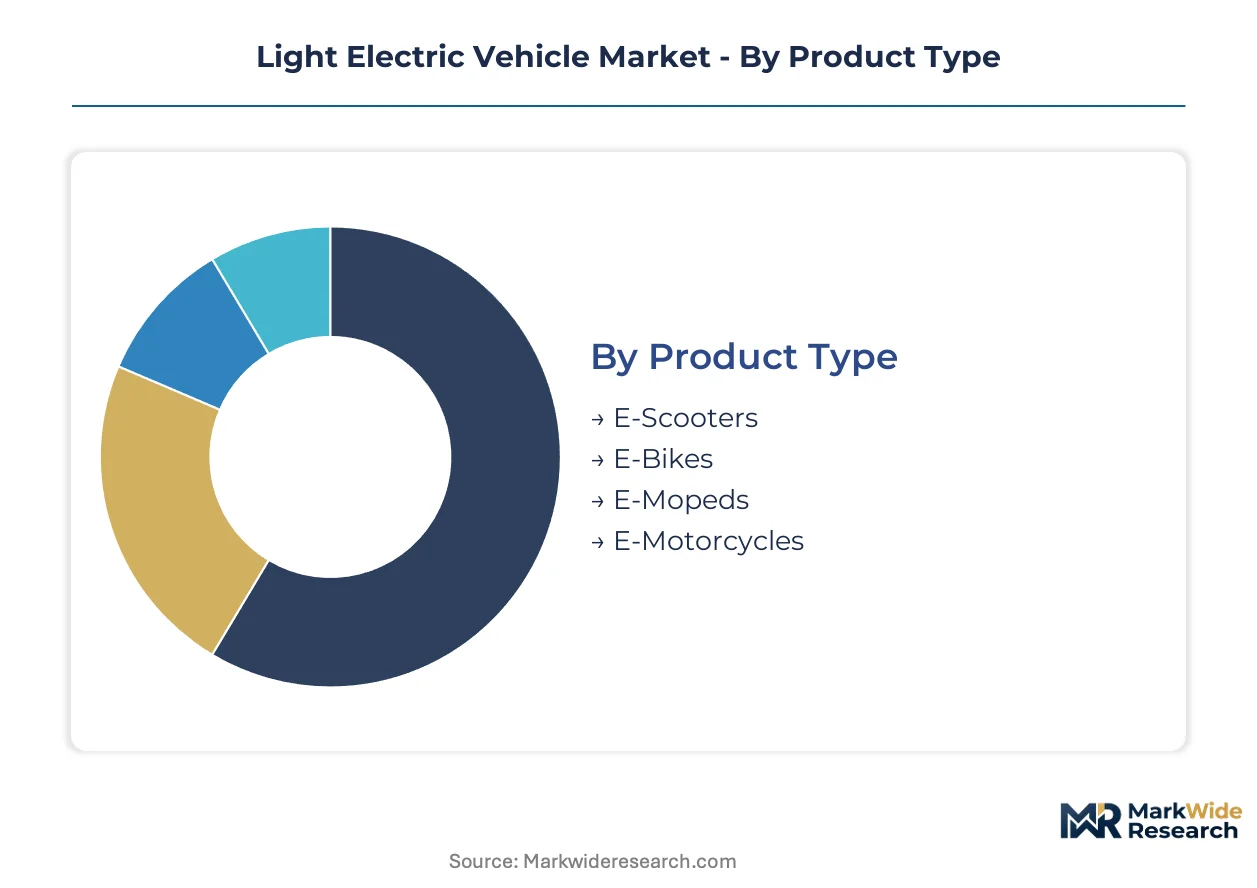
Segmentation in the Light Electric Vehicle Market determines which product configurations align with distinct procurement channels and total cost of ownership models. Fleet operators, individual consumers, and rental platforms each demand different performance specifications and service bundling that reshape manufacturing priorities.
Product Type:
Channel-mix dynamics concentrate e-bike volume through dealer networks while e-scooters flow disproportionately through direct-to-fleet tenders and rental platform contracts.
- E-Scooters:Compact standing platforms with sub-4kW motors and foldable frames dominate urban rental fleets. Demand concentrates in Mediterranean metropolitan networks where congestion pricing exemptions and curbside drop mandates from Barcelona to Milan accelerate procurement.
- E-Bikes:Pedal-assist bicycles with 250W-750W motors and removable battery packs lead consumer channel volume. Germany and the Netherlands anchor demand through employer subsidy programs and cycle highway infrastructure investments.
- E-Mopeds:Step-through frames with 2kW-4kW motors and integrated storage compartments serve gig economy delivery workers in Indian and Southeast Asian urban corridors.
- E-Motorcycles:Higher-speed two-wheelers with 3kW-11kW motors target enthusiast segments and emerging motorcycle-taxi electrification in Kenya and Nigeria.
E-Bikes dominate installed base through minimal licensing friction. E-Scooters are where expansion concentrates fastest in rental and fleet verticals.
Battery Technology:
Cost tier stratification separates premium solid-state pilots from mass-market lithium-ion deployments, with lead acid persisting only in price-sensitive entry segments.
- Lithium-Ion:NMC and LFP cell chemistries deliver 150-250 Wh/kg energy density with established manufacturing scale. NCA variants serve premium e-motorcycle segments where range anxiety shapes purchasing decisions.
- Solid-State:Ceramic electrolyte architectures eliminate thermal runaway risks while enabling 400+ Wh/kg density. Pilot deployments in refrigerated Dutch e-cargo fleets validate cold-chain logistics applications.
- Lead Acid:Mature flooded and AGM designs persist in Indian price-tier e-mopeds where FAME scheme subsidies offset total cost disadvantages.
- Nickel-Metal Hydride:Legacy chemistry retains niche presence in hybrid transition platforms and markets with restricted lithium supply chain access.
Lithium-Ion dominates installed base through manufacturing maturity and supply chain depth. Solid-State is where expansion concentrates among premium fleet operators prioritizing safety certification.
Charging Infrastructure:
Application context determines infrastructure priority: residential garages anchor consumer ownership models while public networks enable rental and fleet utilization economics.
- Home Chargers:Level 1 and Level 2 AC units with 1.4kW-7.2kW output serve individual owners in Germany and the Netherlands where dwelling access rates exceed 70 percent.
- Public Charging Stations:Curbside and parking-integrated AC points with standardized connectors support mixed-use urban environments. India's CEA interoperability mandates determine hardware certification pathways for imported equipment.
- Fast Chargers:DC rapid systems with 50kW+ output concentrate at logistics depots and commercial hubs where fleet turnaround time determines asset utilization.
- Wireless Charging:Inductive pad systems with automated alignment enable rental fleet automation and reduced vandalism exposure in high-turnover deployments.
Home Chargers dominate installed base through consumer ownership prevalence. Public Charging Stations are where expansion concentrates as fleet procurement displaces individual purchasing.
Target Audience:
Customer type segmentation reveals diverging margin structures: delivery services extract value through utilization rates while recreational users absorb premium pricing for performance differentiation.
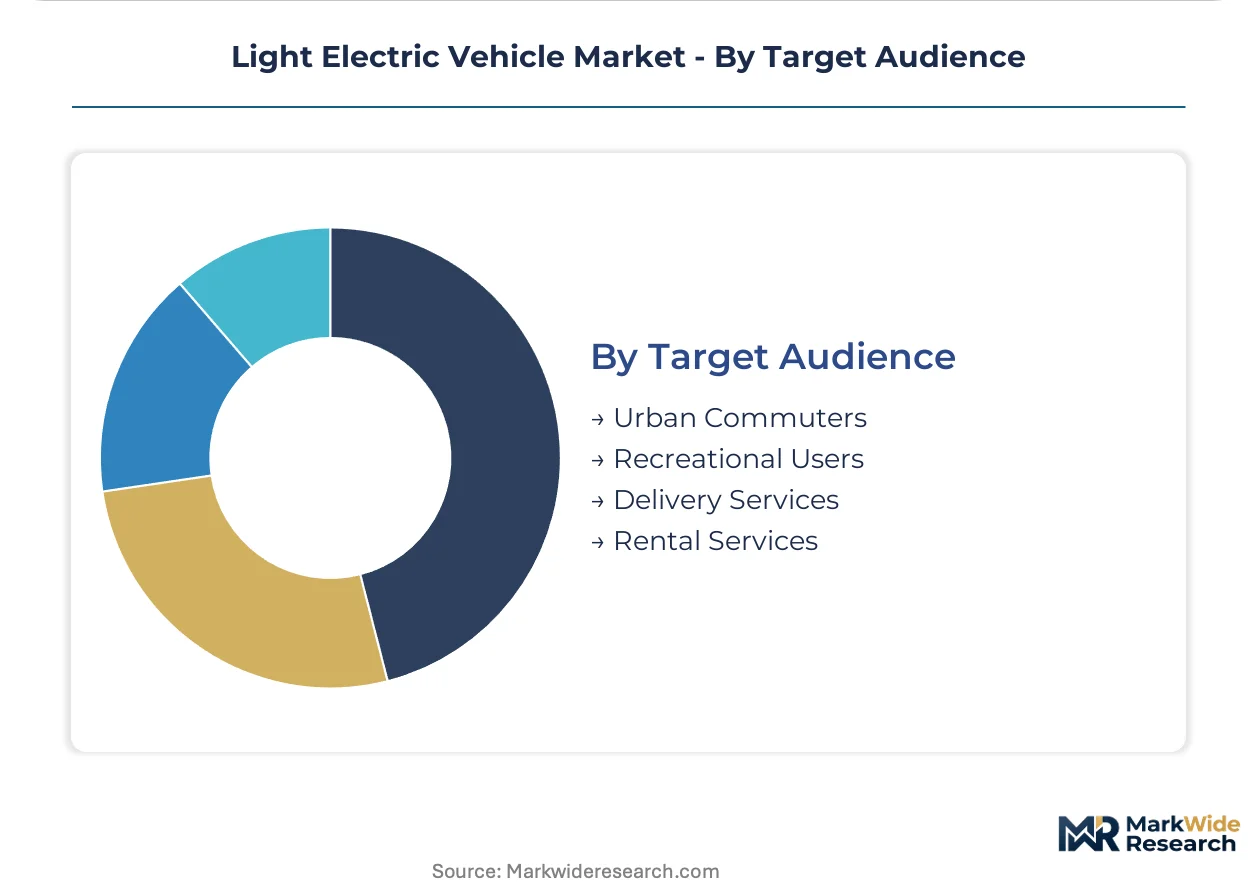
- Delivery Services:Fleet operators with route optimization requirements and maintenance subscription bundling. Last-mile logistics densification in Indian and German metropolitan corridors drives e-cargo bike procurement at scale.
- Urban Commuters:Individual purchasers with multimodal integration needs and employer subsidy eligibility. Netherlands cycle-to-work tax incentives and German company bike leasing programs anchor demand.
- Rental Services:Platform operators with telematics integration and predictive maintenance requirements. Mediterranean climate fleets face steepest EU F-Gas Regulation compliance cost escalation.
- Recreational Users:Enthusiast segments with performance-tier preferences and accessory customization demand. E-motorcycle segments in developed markets capture highest per-unit margins.
Urban Commuters dominate installed base through historical consumer channel prevalence. Delivery Services are where expansion concentrates as e-commerce fulfillment density accelerates fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports battery cells and complete light electric vehicle powertrains to India, Germany, and the Netherlands, establishing the dominant trade-flow corridor shaping procurement economics across three continents.
China
Domestic manufacturing scale-up under MIIT dual carbon goals supplies global LEV component demand. GB standards for cell safety certification create export qualification thresholds that determine market access for battery pack integrators. The Yangtze River Delta cluster around Shanghai anchors e-bike and e-scooter final assembly capacity serving European and Southeast Asian buyers.
India
FAME scheme production-linked incentives accelerate two-wheeler electrification targets through 2030. CEA charger interoperability mandates determine hardware certification pathways for imported equipment from Chinese suppliers. The Maharashtra-Gujarat industrial corridor concentrates domestic e-moped and e-motorcycle assembly operations serving last-mile delivery fleets.
Germany
Employer bike leasing programs and cycle highway infrastructure investments sustain e-bike consumer channel volume. KBA type-approval requirements and EU F-Gas thermal management regulations compress product development timelines for battery cooling systems. The Baden-Württemberg supplier cluster around Stuttgart concentrates motor controller and battery management system engineering talent.
Netherlands
Congestion pricing exemptions and curbside drop mandates for urban logistics accelerate e-cargo bike fleet procurement. Cycle-to-work tax incentives anchor individual purchaser demand alongside employer subsidy schemes. The Randstad metropolitan network around Amsterdam-Rotterdam-Utrecht pilots solid-state battery deployments for refrigerated urban delivery applications.
United States
EPA emissions standards indirectly accelerate LEV adoption by restricting internal-combustion alternatives in dense urban zones. IRA clean vehicle credits shape fleet operator total cost of ownership calculations for electrified logistics assets. California's Advanced Clean Trucks regulation and associated waivers establish the regulatory template adopted by fourteen additional states for light commercial vehicle electrification timelines.
Light Electric Vehicle Market Competitive Environment
Player mix skews toward integrated battery producers and platform-native vendors with direct-to-fleet sales channels. Market structure concentrates margin pools in component supply and connected-vehicle software rather than hardware assembly alone. Two strategic archetypes dominate: vertically integrated Asian manufacturers with captive cell production, and European automotive suppliers specializing in powertrain electronics. Competitive moves center on backward integration into battery cell manufacturing and geographic expansion through fleet procurement tender participation.
Within the integrated manufacturing tier, Yadea Technology Group Co Ltd and NIU Technologies exemplify platform-native vendors with direct-to-fleet channel control. Continental AG occupies a position among European automotive suppliers anchoring powertrain component supply to multiple LEV OEMs. These three entities represent the dominant competitive archetypes: mass-market scale manufacturing, connected-vehicle platform specialization, and Tier 1 component supply respectively.
| Leading Market Players |
|---|
| Accelerated Systems Inc. |
| Addax Motors |
| Aisin Corporation |
| Alke |
| Columbia Vehicle Group Inc. |
| Continental AG |
| Crystalyte Motors |
| NIU Technologies |
| Yadea Technology Group Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Ninety-day battery cell lead times from Chinese cathode suppliers concentrate pricing power among integrated manufacturers with captive cell production, while spot-market lithium carbonate exposure compresses margins for pack assemblers dependent on external supply. Fleet procurement contracts with 36-month service bundling now command 15-20% price premiums over transactional hardware sales, reshaping how OEMs allocate working capital between inventory and after-sales infrastructure.
Pricing Analysis
The lithium-ion-to-solid-state pricing gap stratifies the market into three performance tiers: legacy NMC/LFP packs anchor economy positioning, premium ceramic-electrolyte pilots command fleet-operator premiums, and mid-density silicon-anode variants capture standard-tier volume. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UN 38.3 and UL 2271 compliance tiers separate fleet-eligible hardware from consumer-channel products. Cost compression in the economy tier is intensifying because Indian FAME scheme subsidies sunset progressively, forcing price absorption by manufacturers without integrated cell production. Delivery services exhibit highest price sensitivity due to total cost of ownership calculations dominating procurement tenders, while refrigerated e-cargo fleet operators show lowest sensitivity where thermal runaway risk elimination justifies solid-state premiums.
Supply Chain Analysis
China and South Korea anchor global lithium-ion cell production, with the Yangtze River Delta cluster supplying NMC and LFP chemistry cells to Indian and European pack integrators. Raw material dependencies center on Chilean and Australian lithium spodumene, Indonesian nickel laterite, and DRC cobalt hydroxide—concentration that amplifies price volatility transmission through cathode precursor supply chains. Single-source vulnerability in ceramic electrolyte solid-state cell production concentrates with Japanese and Korean pilot lines, creating qualification bottlenecks for EU F-Gas Regulation-compliant thermal management systems. Distribution runs through direct-to-fleet tender channels for metropolitan logistics operators, bypassing traditional dealer networks that previously captured 12-18% margin layers in consumer e-bike markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected-vehicle platform subscriptions and predictive maintenance service bundles are expanding faster than hardware unit economics, transforming LEV vendor viability from manufacturing scale to software attach-rate engineering. Battery-as-a-service revenue streams now determine enterprise valuation multiples, with swappable architecture providers capturing recurring revenue pools that hardware-only competitors cannot replicate.
For Market Incumbents: Secure backward integration into LFP cell manufacturing through joint venture structures in the Maharashtra-Gujarat corridor, insulating margin pools from lithium carbonate spot volatility. Lock in exclusive fleet procurement relationships with German and Dutch last-mile logistics operators before EU F-Gas Regulation compliance costs escalate thermal management system redesign cycles. Prioritize ISO 26262 functional safety certification investment to extend product development timelines that deter mid-cap competitors without firmware validation expertise.
For New Entrants and Emerging Players: CEA interoperability fast-track certification for Indian public charging hardware creates immediate market access where imported equipment faces 8-14 month approval bottlenecks. Target Sub-Saharan African motorcycle-taxi electrification in Kenya and Rwanda, where solar-charged e-motorcycle demand outstrips supply from incumbent Asian exporters. Deploy battery-as-a-service go-to-market models that decouple vehicle purchase from energy storage capital expenditure, lowering fleet operator entry barriers against integrated manufacturers.
For Investors and Strategic Acquirers: Carve-out targets emerge from European automotive supplier divisions with stranded powertrain electronics expertise and LEV-adjacent motor controller engineering talent. Long-term viability across the projection horizon rests on software-defined vehicle platform ownership rather than hardware assembly margin capture. Monitor CEA charger interoperability mandate enforcement intensity as the inflection signal determining Chinese import market access and domestic Indian manufacturing scale-up velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term LFP offtake contracts with Yangtze River Delta producers lock in cathode cost visibility for Indian assembly operations. |
| Software-Defined Vehicle Investment | Telematics platform development creates recurring revenue streams beyond hardware sales for fleet operator retention. |
| Charging Infrastructure Partnership | CEA-compliant hardware certification partnerships accelerate Indian market access against fragmented interoperability standards. |
| Geographic Manufacturing Footprint | Maharashtra-Gujarat corridor assembly localization captures FAME scheme production-linked incentives for domestic e-moped output. |
| Platform Standardization | Swappable battery architecture convergence enables battery-as-a-service models that decouple vehicle purchase from energy storage capex. |
Study Parameters
Initial hypotheses were tested against primary input from LEV fleet procurement managers, battery pack engineering directors, CEA certification officers, and Tier 1 powertrain supplier executives and refined through secondary validation against MIIT production statistics, UN 38.3 dangerous goods filing databases, EU F-Gas Regulation implementation guidance, and Indian customs import records for e-two-wheeler components. Bottom-up triangulation across vehicle registration data and top-down reconciliation against cathode material demand forecasts ensured segmentation integrity across product type, battery technology, and target audience dimensions.
Variance decomposition across the projection horizon isolates volume sensitivity to fleet electrification mandates, pricing sensitivity to lithium carbonate futures curves, and technology adoption sensitivity to solid-state pilot validation timelines. Segmentation dimensions modeled span product type, battery chemistry tier, charging infrastructure category, and target audience archetype, with CAGRs derived from logistic diffusion curves fitted to historical e-scooter and e-bike penetration patterns in Germany and the Netherlands. Forecast inputs incorporate FAME scheme subsidy phase-out schedules and EU F-Gas Regulation compliance cost escalation assumptions for thermal management system redesign.
Underlying assumptions cover lithium carbonate price band stability, CEA interoperability mandate enforcement consistency, and solid-state cell manufacturing yield progression, with deviation risk concentrated in raw material supply disruption and regulatory timeline acceleration. Recalibration cycles align with material shifts in fleet procurement tender award patterns and battery chemistry certification standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market