
 High Performance Battery Electric Vehicle Market | 2026-2036
High Performance Battery Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Battery Electric Vehicle Market Insights
Chinese gigafactory operators is decoupling from legacy cobalt supply chains through direct offtake agreements with Indonesian nickel processors. Tesla leverages in-house 4680 cell production to reduce dependency on external cathode suppliers. BMW anchors its performance lineup around Gen6 round-cell architecture, while NIO differentiates through proprietary battery-swap infrastructure across premium urban corridors.
High performance battery electric vehicles integrate energy-dense lithium-ion or solid-state cell chemistries with thermal management systems sustaining sustained discharge rates above 4C for sub-four-second acceleration. Their primary commercial purpose is to deliver sports-car or supercar acceleration benchmarks alongside daily-driving range utility. Passenger cars command the dominant margin pool given luxury positioning and software monetization potential, while solid-state technology represents the fastest-advancing segment as manufacturers resolve ceramic-electrolyte manufacturing yield. Fleet operators constitute a concentrated demand node where total-cost-of-ownership advantages override upfront acquisition premiums.
China's MIIT enforces GB standards for battery safety and energy density that dictate cell architecture choices for vehicles sold domestically. The EU Green Deal and F-Gas Regulation compel European OEMs to eliminate refrigerants with high global warming potential from thermal management circuits, reshaping supplier qualification requirements. Stakeholders must monitor whether solid-state production scale-up timelines align with tightening cobalt due diligence rules under OECD frameworks.
Market Dynamics
Solid-state battery manufacturing yield improvements are compressing commercialization timelines and forcing incumbent lithium-ion suppliers to accelerate thermal management innovations to defend their installed base.
Growth Catalysts
- GB Standards Compliance:China's MIIT mandates for energy density and thermal runaway containment push domestic OEMs toward next-generation cell architectures that exceed legacy pack performance thresholds.
- Fleet Electrification Mandates:Logistics operators in premium corridors face tightening emissions frameworks that accelerate replacement cycles for internal combustion performance vehicles.
- Indonesian Nickel Processing:Direct offtake agreements with integrated nickel-cobalt refiners are decoupling cell producers from legacy supply chain bottlenecks.
Market Restraints
- Ceramic Electrolyte Manufacturing Defects:Solid-state cell producers face yield rates below commercial viability thresholds, constraining volume ramp.
- Cobalt Due Diligence Compliance:OECD frameworks impose traceability burdens that extend qualification timelines for Central African supply sources.
- High-Voltage Thermal Management Costs:Sustained 4C+ discharge rates require exotic cooling architectures that inflate bill-of-materials relative to mass-market EVs.
Strategic Opportunities
- Battery-Swap Infrastructure:Proprietary station networks in dense urban corridors eliminate range anxiety without requiring full solid-state maturation.
- F-Gas Regulation Alignment:EU thermal management suppliers capturing refrigerant transition mandates gain preferential qualification with European OEM performance lineups.
- Software Monetization Layers:Over-the-air performance tuning and subscription-based acceleration unlocks create recurring revenue streams atop hardware margins.
Industry Challenges
- Solid-State Process Engineering Talent Scarcity:Thin-film deposition and ceramic sintering expertise concentrates within semiconductor and aerospace sectors, requiring cross-industry recruitment.
- Multi-Chemistry Platform Integration:OEMs must maintain parallel development tracks for lithium-ion and solid-state architectures without fragmenting R&D capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Battery Electric Vehicle Market |
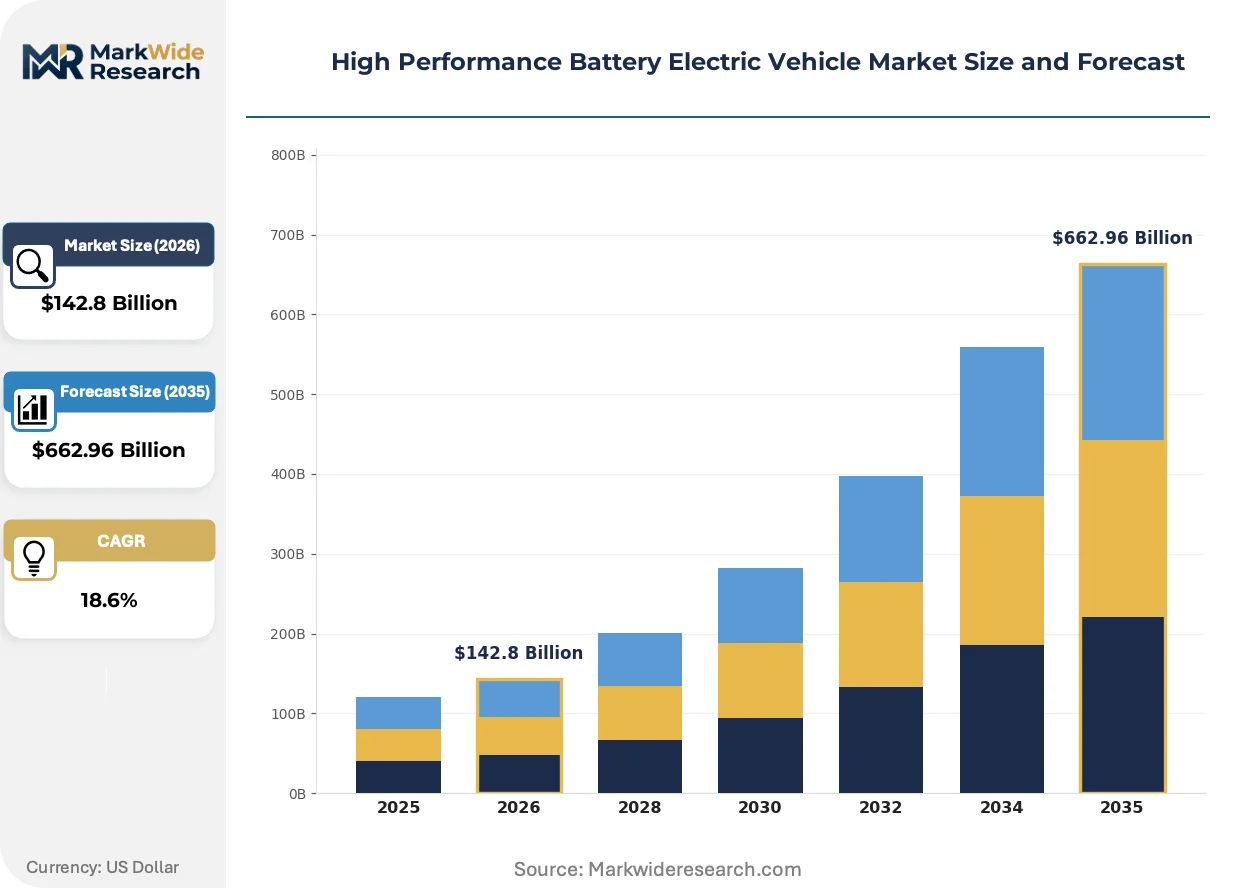
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $662.96 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Cars, Commercial Trucks, Buses, Motorcycles Technology: Lithium-Ion, Solid State, Lithium Polymer, Nickel-Metal Hydride End User: Private Owners, Fleet Operators, Government, Ride-Sharing Services Application: Urban Transportation, Long-Distance Travel, Logistics, Off-Road Driving |
| Companies Covered | Tesla, Porsche, BMW, Audi, Mercedes-Benz, Rivian, Lucid Motors, NIO, Polestar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Battery Electric Vehicle Market Trends and Innovations
Cell chemistry diversification and thermal architecture specialization are fragmenting the supplier landscape, creating openings for chemistry-agnostic pack integrators and software-defined battery management specialists.
Solid-state electrolyte technology is decentralizing the incumbent cathode-active-material supply hierarchy by enabling lithium-metal anodes that reduce cobalt and nickel loading requirements. Performance OEMs in Germany and South Korea are piloting 100-layer ceramic cell stacks for 2027 platform integration. This chemistry shift is decentralizing procurement power away from traditional NCM precursor suppliers toward solid-electrolyte and lithium-metal foil specialists.
The EU F-Gas Regulation is eliminating refrigerants with global warming potential above 150 from thermal management circuits, compelling suppliers to qualify CO2-based heat pumps and dielectric fluid architectures. European OEMs face redesign cycles for performance vehicle HVAC systems that compress supplier development timelines. High-performance BEVs with sustained track-capable discharge profiles are most exposed, driving accelerated partnerships with industrial refrigeration specialists.
Fleet operators are consolidating procurement decisions through captive leasing subsidiaries that internalize residual value risk and capture carbon credit monetization. This channel shift bypasses traditional dealer networks in premium logistics corridors across California and the Rhine-Ruhr industrial cluster. Direct OEM-fleet relationships are compressing sales cycles and forcing reconfiguration of after-sales service bundling toward uptime-guarantee contracts.
High Performance Battery Electric Vehicle Market Segmentation
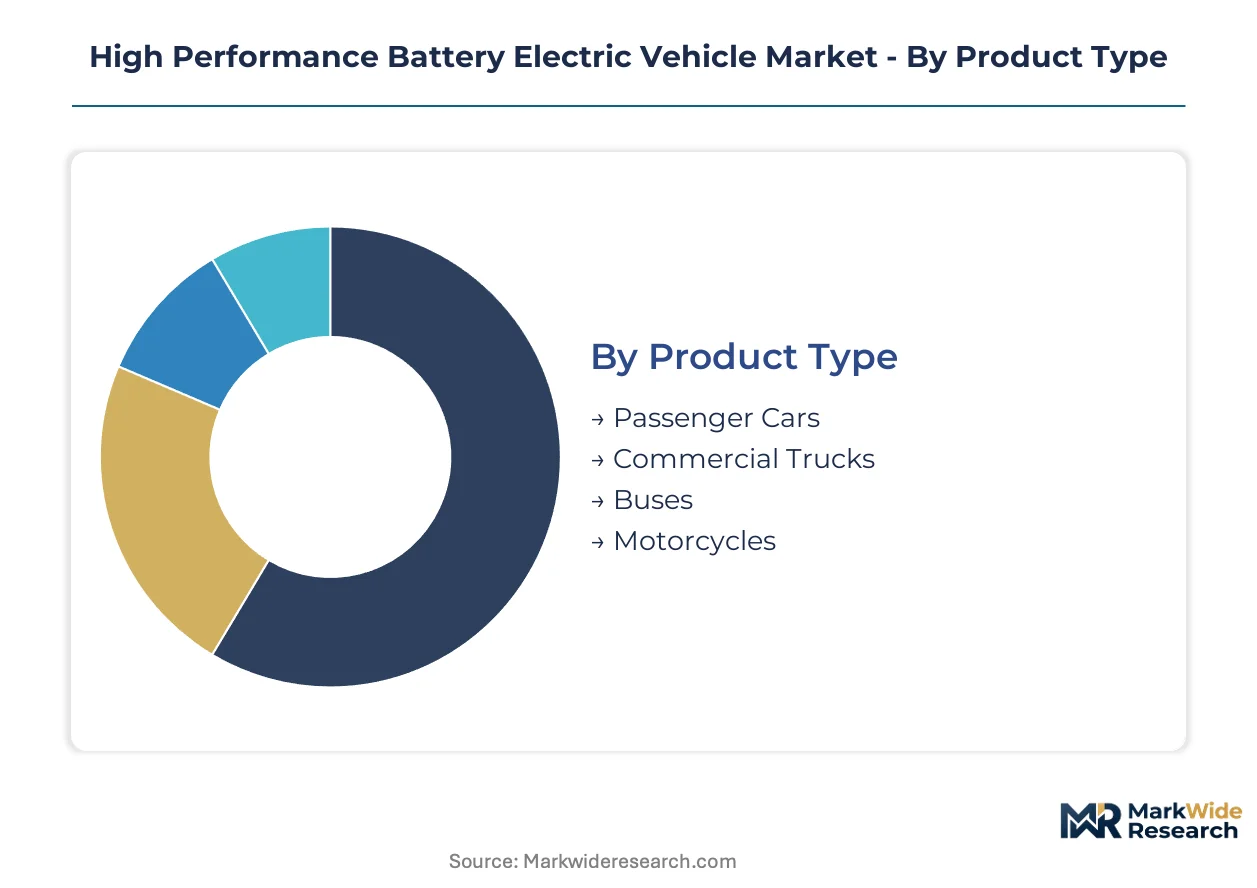
Segmentation in high performance battery electric vehicles reveals divergent engineering priorities across mobility modes. Thermal management specifications, discharge rate requirements, and duty cycle intensity vary substantially between passenger-focused and commercial applications.
Product Type:
Standalone platforms dominate volume, while embedded performance variants within multi-purpose architectures capture premium positioning.
- Passenger Cars:Energy-dense cell packs sustaining 4C+ discharge rates enable sub-four-second acceleration benchmarks. Demand clusters in China's tier-one cities and Germany's autobahn corridors where luxury OEMs monetize software-defined performance tiers.
- Commercial Trucks:Heavy-duty thermal architectures manage sustained high-load discharge for premium logistics routes. Fleet operators in California's Central Valley and the Rhine-Ruhr industrial cluster prioritize total-cost-of-ownership over upfront capital expenditure.
- Buses:High-floor battery configurations serve municipal transit authorities with predictable duty cycles.
- Motorcycles:Compact power-dense packs address urban last-mile delivery and enthusiast segments.
Volume placements concentrate in Passenger Cars; the faster expansion belongs to Commercial Trucks.
Technology:
Cost tiers separate mature chemistries from emerging architectures, with qualification timelines and manufacturing yield defining competitive access.
- Lithium-Ion:NCM and LFP variants deliver proven energy density above 250 Wh/kg with established supply chains. Chinese cell producers leverage Indonesian nickel offtake agreements to reduce cobalt exposure under OECD due diligence frameworks.
- Solid State:Ceramic electrolyte designs enable lithium-metal anodes with reduced nickel loading. South Korean and German OEMs pilot 100-layer cell stacks for platform integration, though manufacturing yield constraints limit near-term volume.
- Lithium Polymer:Pouch configurations serve niche applications requiring flexible form factors.
- Nickel-Metal Hydride:Legacy chemistry retains presence in cost-sensitive hybrid transitions.
Commercial traction centers on Lithium-Ion; Solid State claims the steepest expansion trajectory pending yield resolution.
End User:
Customer type determines procurement channel structure, with direct OEM relationships displacing traditional dealer networks in concentrated demand nodes.
- Private Owners:Individual purchasers prioritize acceleration benchmarks and brand prestige. China's HNWI demographic drives premium configuration uptake through direct manufacturer channels.
- Fleet Operators:Captive leasing subsidiaries internalize residual value risk and carbon credit monetization. Logistics consolidators in California and North Rhine-Westphalia compress sales cycles through uptime-guarantee contracts.
- Government:Municipal procurement mandates specify domestic content thresholds.
- Ride-Sharing Services:Platform operators optimize for charging infrastructure access and depreciation schedules.
Private Owners anchor current volume; Fleet Operators are gaining share fastest through electrification mandates.
Application:
Geography and duty cycle intensity segment thermal management requirements, with sustained discharge profiles demanding specialized cooling architectures.
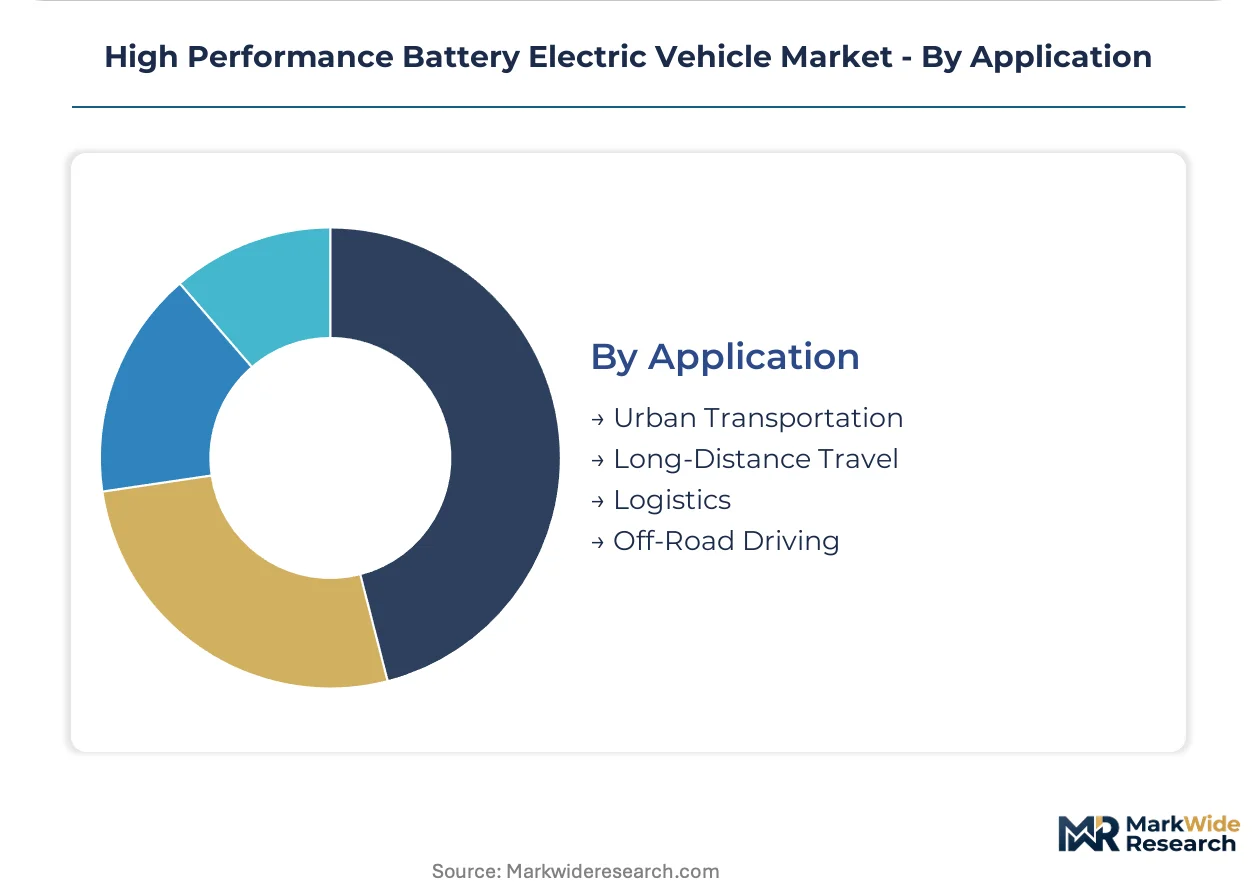
- Urban Transportation:Stop-start duty cycles with frequent acceleration events stress cell thermal stability. Battery-swap infrastructure in Shanghai and Shenzhen dense corridors eliminates range anxiety without full solid-state maturation.
- Long-Distance Travel:Sustained highway speeds require high-voltage thermal management with dielectric fluid or CO2-based heat pump architectures compliant with EU F-Gas Regulation.
- Logistics:Predictable depot-based charging supports heavy-duty cycle optimization.
- Off-Road Driving:Vibration-hardened packs address terrain stress with reinforced cell-to-pack structures.
Urban Transportation commands present installations; Long-Distance Travel exhibits the fastest climb as solid-state range thresholds mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel processing capacity anchors cell production geography, with integrated refineries in Sulawesi and Halmahera feeding cathode supply chains across three continents. Battery-grade nickel output from Morowali Industrial Park now exceeds legacy cobalt dependency thresholds for high-performance pack architectures.
China
Domestic OEMs and tier-one suppliers are building dedicated gigafactories for high-performance cell production in the Yangtze River Delta. MIIT enforces GB standards for battery safety and energy density that dictate cell architecture choices for vehicles sold domestically. Shanghai and Shenzhen dense corridors host proprietary battery-swap infrastructure eliminating range anxiety without full solid-state maturation.
Germany
Performance OEMs pilot 100-layer ceramic cell stacks for 2027 platform integration while anchoring lineups around Gen6 round-cell architecture. The EU Green Deal and F-Gas Regulation compel elimination of refrigerants with high global warming potential from thermal management circuits. The Rhine-Ruhr industrial cluster concentrates fleet operator procurement through captive leasing subsidiaries internalizing residual value risk.
United States
Logistics operators in California's Central Valley face tightening emissions frameworks accelerating replacement cycles for internal combustion performance vehicles. NHTSA safety standards and EPA emissions frameworks shape powertrain qualification timelines. Tesla leverages in-house 4680 cell production in Texas and Nevada to reduce dependency on external cathode suppliers.
South Korea
Battery producers face yield rates below commercial viability thresholds for solid-state ceramic electrolyte manufacturing. The country's national industrial regulator enforces cell safety certification protocols aligned with OECD due diligence frameworks. Seoul Capital Area and Busan-Ulsan corridors concentrate R&D partnerships between OEMs and solid-electrolyte specialists resolving ceramic sintering defects.
High Performance Battery Electric Vehicle Market Competitive Landscape
Global majors compete with regional champions across thermal management architecture and cell chemistry integration. The vendor base organizes around three tiers: vertically integrated cell producers controlling upstream material offtake, platform specialists monetizing software-defined performance tiers, and swap-infrastructure operators capturing recurring revenue from urban corridor density. Two dominant competitive moves are reshaping positioning: direct OEM-fleet relationships compressing sales cycles through uptime-guarantee contracts, and cross-industry recruitment of thin-film deposition talent from semiconductor sectors.
Within the vertically integrated tier, Tesla and NIO exemplify divergent infrastructure strategies—Tesla through in-house cylindrical cell production, NIO through proprietary swap-station networks. BMW anchors the European premium-performance archetype with round-cell platform standardization. These three occupy positions spanning North American, Chinese, and German industrial bases respectively, each representing a distinct competitive thesis on whether solid-state maturation or infrastructure density wins urban corridor deployment.
| Leading Market Players |
|---|
| Tesla |
| Porsche |
| BMW |
| Audi |
| Mercedes-Benz |
| Rivian |
| Lucid Motors |
| NIO |
| Polestar |
| Others |
Pricing and Supply Chain Analysis
Solid-state battery manufacturing yield improvements are compressing commercialization timelines and forcing incumbent lithium-ion suppliers to accelerate thermal management innovations to defend their installed base. This chemistry transition simultaneously reshapes cost economics and supply concentration by decentralizing procurement power away from traditional NCM precursor suppliers toward solid-electrolyte and lithium-metal foil specialists.
Pricing Analysis
Warranty and service bundling separates premium performance tiers from mass-market offerings, with uptime-guarantee contracts commanding substantial premiums over transactional sales. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service intensity, thermal management sophistication, and software-defined performance unlocks. Cost compression in the standard tier is intensifying because Chinese cell producers leverage Indonesian nickel offtake agreements to reduce cobalt exposure. Fleet operators exhibit highest price sensitivity given total-cost-of-ownership discipline, while private owners in China's tier-one cities show lowest sensitivity to upfront premiums.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta, Rhine-Ruhr industrial cluster, and Texas-Nevada corridor anchor hub-and-spoke patterns for cell and pack logistics. Geographic supply concentration centers on China, South Korea, and Indonesia for cathode-active materials and integrated nickel processing. Raw material dependencies rest on Indonesian nickel-cobalt refiners, lithium carbonate from South American salares, and ceramic electrolyte precursors. Single-source vulnerability in solid-state electrolyte manufacturing creates structural risk given yield rates below commercial thresholds. Distribution runs through direct OEM-fleet relationships that bypass traditional dealer networks in premium logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high performance battery electric vehicle market sits in a technology-transition phase as solid-state architectures displace legacy lithium-ion dominance in premium segments. This chemistry shift demands parallel platform strategies without fragmenting R&D capital allocation.
For Market Incumbents: Hedge solid-state maturation delays by maintaining Gen6 round-cell architecture production while recruiting thin-film deposition talent from semiconductor sectors. Accelerate thermal management partnerships with industrial refrigeration specialists to capture EU F-Gas Regulation compliance mandates before qualification windows close.
For New Entrants and Emerging Players: Proprietary battery-swap infrastructure offers a technology-first wedge into dense urban corridors where range anxiety persists without full solid-state maturation. Target captive fleet leasing subsidiaries in California's Central Valley and North Rhine-Westphalia through uptime-guarantee contracts that internalize residual value risk.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated OEMs seeking solid-electrolyte manufacturing capabilities. Long-term viability favors specialists resolving ceramic sintering defects and lithium-metal foil processing. Watch South Korean and German OEM pilot programs for 100-layer cell stack integration as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Direct offtake with Indonesian nickel processors decouples from legacy cobalt supply chains. |
| Software-Defined Vehicle Investment | Over-the-air performance tuning unlocks recurring revenue atop hardware margins. |
| Charging Infrastructure Partnership | Proprietary swap-station networks in Shanghai and Shenzhen corridors eliminate range anxiety. |
| Platform Standardization | Gen6 round-cell architecture reduces qualification burden across multiple vehicle lines. |
| Geographic Manufacturing Footprint | Yangtze River Delta gigafactories align with MIIT GB standards compliance requirements. |
Research Methodology
SEC filings, IHS Markit vehicle registration data, and OEM production disclosures formed the secondary backbone for this analysis. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator leasing directors, and solid-state electrolyte R&D directors combined with secondary validation. Bottom-up cell chemistry demand modeling and top-down automotive production forecasts enabled triangulation across the analysis window.
Historical trendline analysis of lithium-ion and solid-state manufacturing yield curves informed projection assumptions. Segmentation dimensions modeled include vehicle class, propulsion architecture, cell chemistry type, and regional production cluster. CAGRs were derived from installed base replacement cycles and fleet electrification mandate compliance timelines. Forecast inputs incorporated OECD due diligence framework implementation schedules and EU F-Gas Regulation phase-out deadlines.
Several conditions sit outside the modeled scope, including unannounced solid-state platform launches, abrupt cobalt supply disruptions, and retroactive tariff adjustments. Forecasts reflect documented assumptions regarding ceramic electrolyte yield improvement trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Global Electric Cars Market