
 Solar Software Market | 2026-2036
Solar Software Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Software Market Insights
Chinese inverter and module manufacturers is realigning supply chains toward software-integrated hardware bundles. Aurora Solar leverages proprietary shading engines and automated permitting workflows to differentiate its design platform for residential installers. GE Vernova sustains a dominant position in utility-scale asset performance management through its digital twin integration with grid control systems. Solstice anchors community solar subscriber management with regulatory compliance tools that streamline credit allocation across multiple state jurisdictions.
Solar software encompasses digital platforms that model photovoltaic system performance, manage operational data streams, and automate financial and regulatory reporting for distributed and utility-scale generation assets. These systems typically process irradiance measurements, module temperature coefficients, and inverter efficiency curves to forecast energy yield and detect performance degradation. Cloud-based deployment now leads adoption as utilities and independent power producers prioritize centralized fleet visibility and API-driven integration with wholesale market platforms. Management platforms represent the fastest-expanding segment, driven by rising complexity in multi-asset portfolios and the need for unified dashboards spanning energy management, performance optimization, and financial analysis functions.
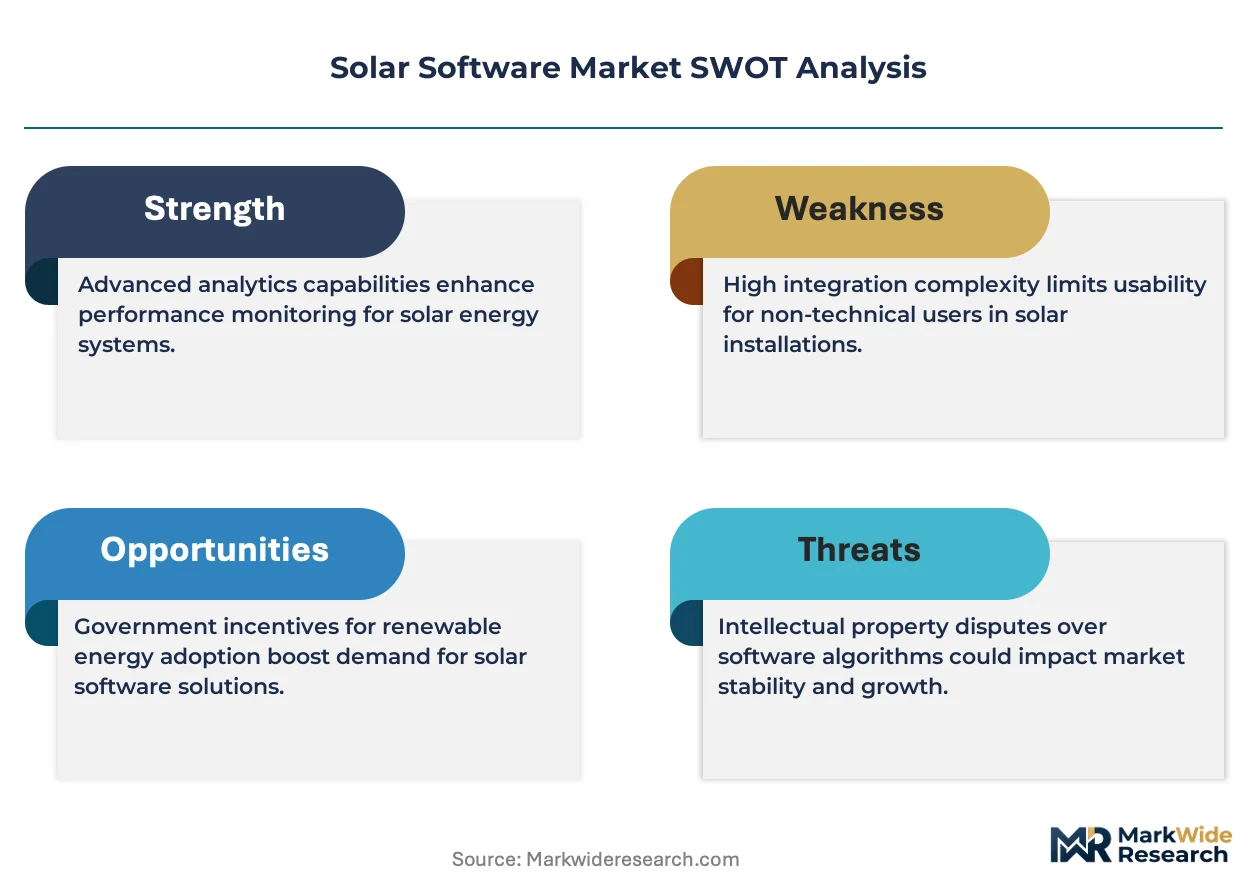
FERC Order 2222 and NERC CIP standards in the United States mandate granular telemetry and cybersecurity protocols for aggregated distributed energy resources participating in wholesale markets. The EU AI Act and GDPR impose algorithmic transparency and data governance requirements on predictive maintenance and automated forecasting tools deployed across European solar fleets. Stakeholders must monitor evolving interoperability standards between inverter OEMs and third-party software vendors, as proprietary data formats risk fragmenting the digital ecosystem and locking asset owners into single-supplier dependencies.
Market Dynamics
Cloud-based deployment of solar software is compressing installation timelines and forcing legacy on-premise vendors toward API-first architectures or obsolescence.
Growth Catalysts
- FERC Order 2222:United States wholesale market participation rules for aggregated distributed energy resources mandate telemetry standards that drive software procurement among independent power producers.
- Performance optimization algorithms:Machine learning models processing irradiance and temperature coefficient data enable predictive maintenance contracts that reduce operational expenditure for utility-scale fleet operators.
- Germany's Energiewende mandates:Distributed generation targets accelerate software adoption across commercial rooftop and utility segments for regulatory compliance and yield forecasting.
Market Restraints
- Proprietary inverter data formats:OEM-specific communication protocols fragment digital ecosystems and lock asset owners into single-supplier dependencies, raising switching costs.
- Cybersecurity compliance burden:NERC CIP standards impose granular telemetry and access control requirements that strain small developer IT budgets and extend procurement cycles.
- Interoperability gaps:IEEE 1547 interconnection rule variations across United States regional transmission organizations create software configuration complexity that delays grid connection approvals.
Strategic Opportunities
- Community solar subscriber management:Regulatory credit allocation tools streamline multi-state compliance for platforms serving the United States virtual net metering segment.
- Digital twin convergence:Integration of photovoltaic performance models with grid control systems enables real-time fleet optimization for transmission-connected assets.
- Automated permitting workflows:Jurisdiction-specific code compliance engines reduce soft costs for residential installers in fragmented United States municipal markets.
Industry Challenges
- Data science talent scarcity:Shortage of engineers combining photovoltaic physics expertise with machine learning deployment skills constrains predictive analytics product roadmaps.
- Legacy SCADA integration:Retrofit requirements for decades-old utility infrastructure delay cloud migration timelines and inflate professional services margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Software Market |
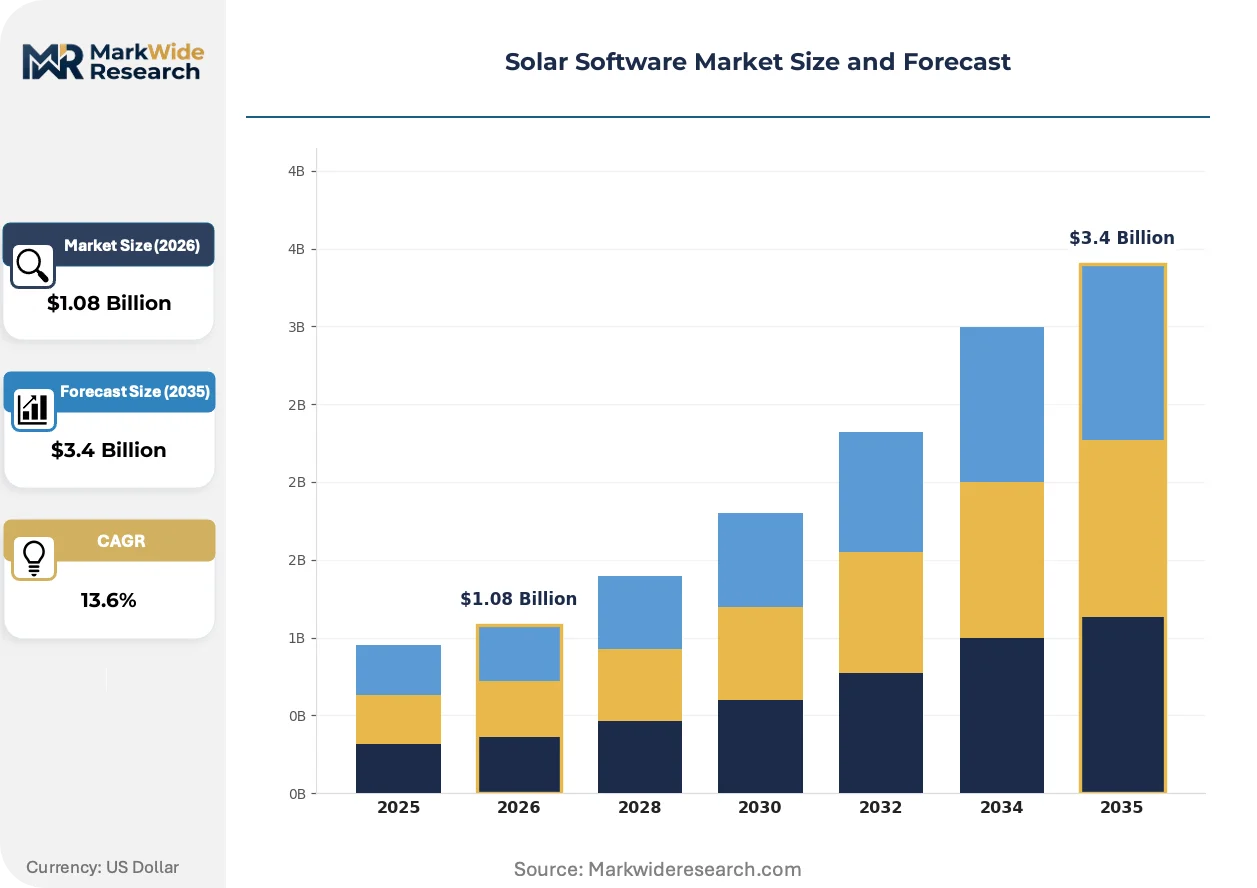
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $3.4 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Software, Design Tools, Management Platforms, Data Analytics End User: Residential Users, Commercial Enterprises, Utility Providers, Installers Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions Application: Energy Management, Performance Optimization, Reporting Tools, Financial Analysis |
| Companies Covered | GE Vernova, Techstack, Aurora Solar, Borrego Solar Systems, TTMS, Solstice, Landbase, 8minute Solar Energy, Sunbase Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Software Market Trends and Innovations
Artificial intelligence is penetrating solar software across design, operations, and financial forecasting functions, compressing decision cycles and displacing rule-based automation.
Machine learning-based shading analysis is automating rooftop suitability assessments that previously required manual drone surveys or satellite image interpretation. Residential installers in the United States and Germany are adopting these tools at accelerating rates to reduce customer acquisition costs. The technology is automating pre-sales engineering workflows that once consumed 40-60 hours per project.
The EU AI Act imposes algorithmic transparency and data governance requirements on predictive maintenance and automated forecasting tools deployed across European solar fleets. Industrial consequence includes mandatory documentation of training data provenance and model performance metrics for high-risk applications. Utility-scale asset managers in Germany and Spain are restructuring procurement specifications to prioritize explainable AI architectures.
Subscription-based pricing for design and permitting software is displacing perpetual license models among residential installer segments. Channel disruption concentrates in the United States, where venture-backed platforms bundle customer relationship management with automated proposal generation. California and Texas markets exhibit the fastest behavioral shift as installer consolidation creates demand for scalable, multi-user SaaS tools.
Solar Software Market Segmentation
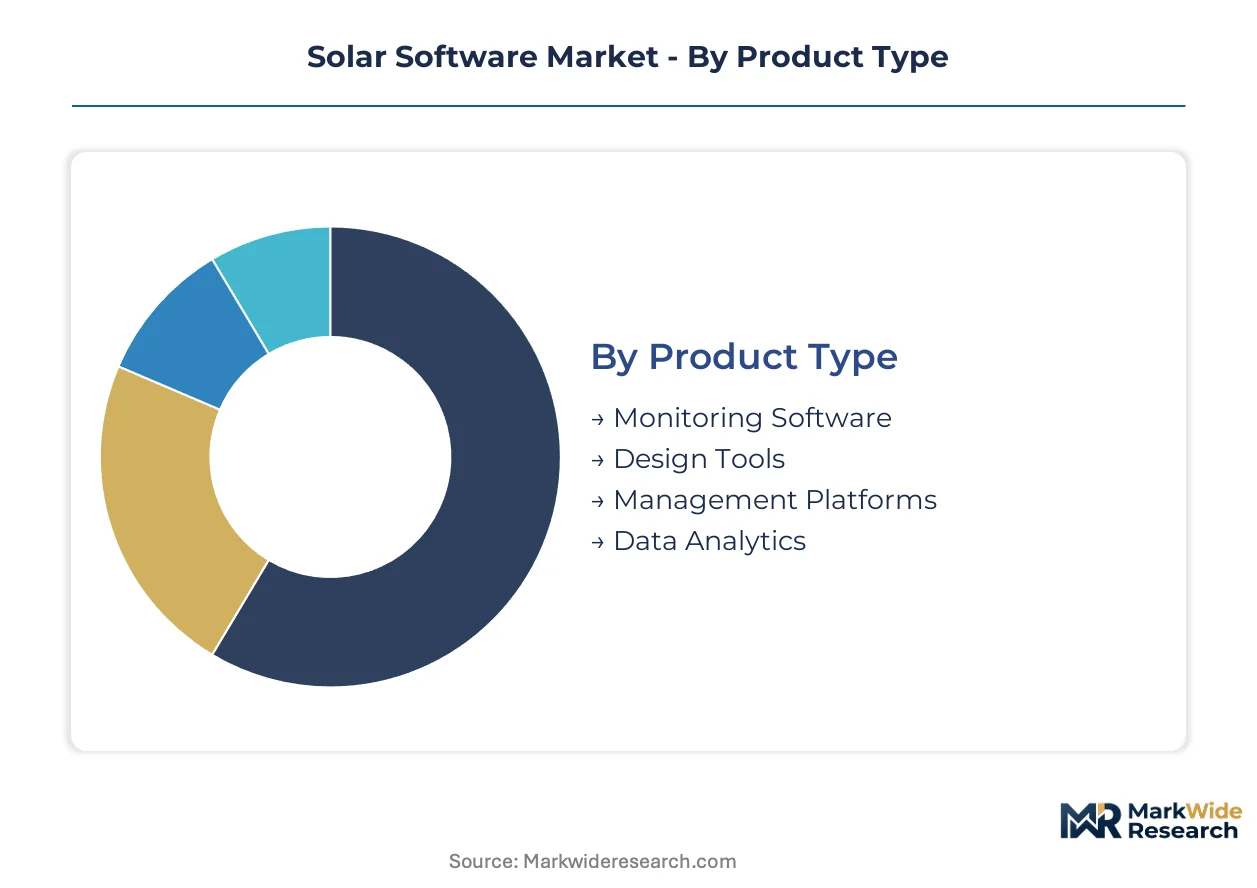
Solar software segments diverge sharply in integration depth. Standalone monitoring and design tools serve discrete workflows, while management platforms embed across operational stacks. Procurement patterns track this divide: point solutions dominate cost-conscious residential installers, unified suites capture utility-scale fleet operators seeking centralized command layers.
Product Type:
Integration depth separates standalone visualization layers from embedded operational systems that ingest SCADA streams and dispatch control signals.
- Monitoring Software:Real-time data acquisition platforms processing inverter telemetry, meteorological station feeds, and string-level current-voltage curves. Demand concentrates among utility providers in the United States seeking NERC CIP-compliant visibility into geographically dispersed assets. Cybersecurity certification requirements extend procurement cycles but lock in multi-year contracts.
- Management Platforms:Unified operational systems integrating energy management, work order dispatch, and financial reporting through API-connected modules. Commercial enterprises in Germany adopt these suites to satisfy Energiewende distributed generation mandates while consolidating vendor relationships. The segment commands premium pricing through workflow automation that compresses operational expenditure.
- Design Tools:Photovoltaic system modeling software incorporating shading engines, electrical string sizing, and structural load calculations.
- Data Analytics:Predictive algorithms processing historical performance data to forecast degradation curves and optimize maintenance scheduling.
Volume placements concentrate in Monitoring Software; the faster expansion belongs to Management Platforms.
End User:
Customer sophistication determines feature requirements, with procurement authority shifting from individual technicians to enterprise IT departments as scale increases.
- Utility Providers:Fleet-scale operators managing gigawatt portfolios across multiple interconnection zones. These buyers mandate FERC Order 2222 telemetry compliance and IEEE 1547 interconnection rule adherence, driving procurement of cloud-native platforms with wholesale market API integration. Procurement committees prioritize cybersecurity certifications and disaster recovery protocols over unit economics.
- Residential Users:Homeowners accessing mobile dashboards for production visibility and utility bill reconciliation. Demand clusters in United States states with virtual net metering policies, where subscriber management features determine platform selection. Price sensitivity favors freemium models with premium upgrades for battery storage integration.
- Commercial Enterprises:Corporate energy managers optimizing behind-the-meter solar plus storage configurations against time-of-use rate structures.
- Installers:Field technicians requiring permitting automation and proposal generation tools to compress customer acquisition timelines.
Utility Providers anchor current procurement volumes; Commercial Enterprises are climbing the fastest as electrification mandates expand addressable rooftops.
Deployment:
Infrastructure ownership models split between capital-intensive on-premise installations and operational-expense cloud subscriptions that externalize maintenance burden.
- Cloud-Based:Multi-tenant SaaS architectures delivering automatic updates, elastic compute for machine learning workloads, and centralized data lakes for fleet benchmarking. United States independent power producers favor this model to satisfy FERC telemetry mandates without internal IT expansion. API-first designs enable rapid integration with wholesale market platforms and grid operator systems.
- On-Premises:Air-gapped installations serving cybersecurity-critical infrastructure and jurisdictions with data sovereignty requirements. German utility operators deploy these configurations to satisfy GDPR localization mandates while maintaining operational continuity during internet outages. Higher upfront capital and professional services margins characterize this segment.
- Hybrid:Edge-compute architectures processing time-sensitive control loops locally while streaming aggregated data to cloud analytics layers.
- Mobile Solutions:Native applications enabling field technicians to access schematics, submit commissioning documentation, and receive alert notifications.
Cloud-Based deployments dominate new contract signings; Hybrid architectures are gaining share fastest as latency-sensitive control applications proliferate.
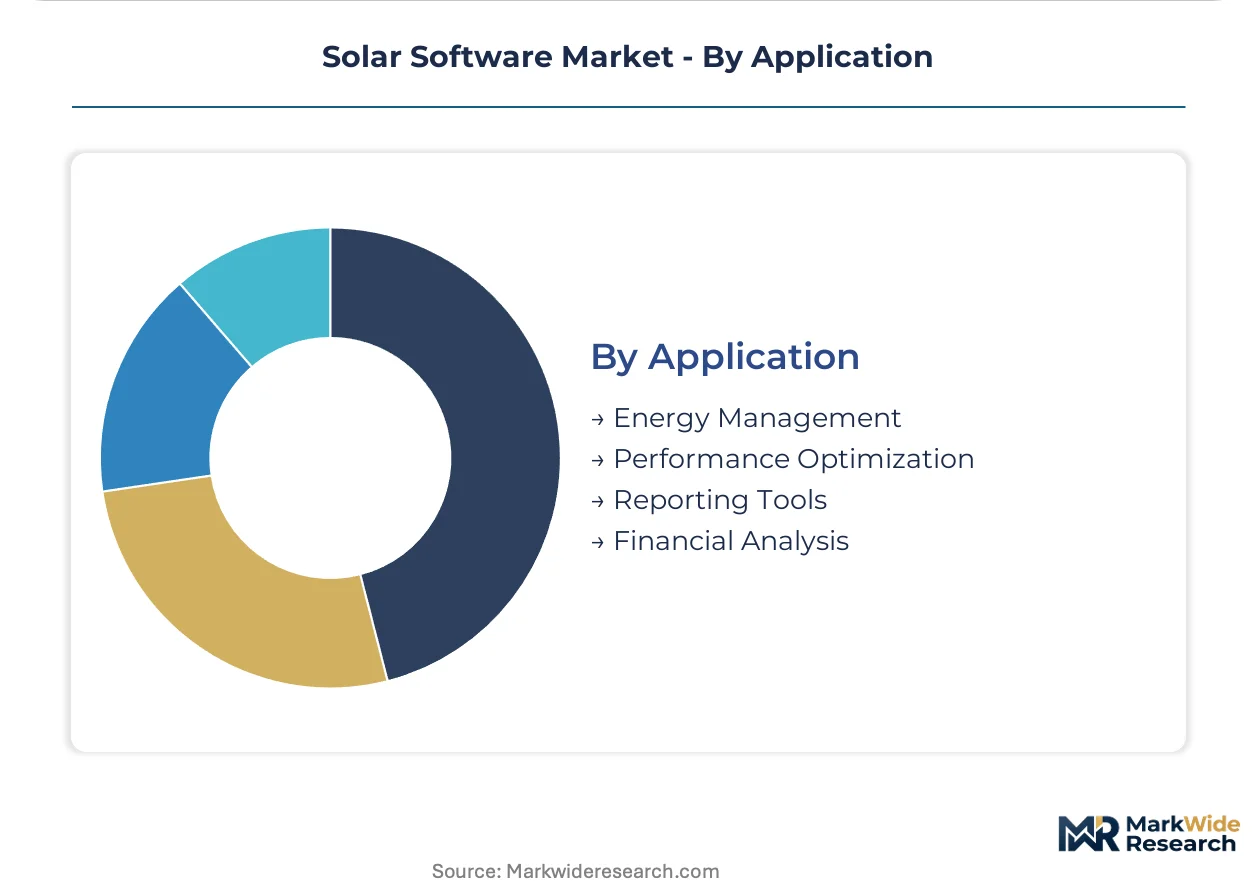
Application:
Functional purpose separates operational technology stacks from business intelligence layers, with convergence accelerating as asset managers seek unified decision environments.
- Performance Optimization:Algorithmic systems adjusting inverter setpoints, curtailment schedules, and storage dispatch to maximize revenue stack capture. Utility-scale fleet operators in Spain deploy these tools to navigate wholesale market volatility and grid constraint periods. Machine learning models processing satellite-derived irradiance forecasts enable sub-hourly optimization cycles.
- Energy Management:Real-time control systems balancing on-site generation, storage, and flexible loads against utility rate structures and demand charge minimization. Commercial enterprises in California integrate these platforms with building automation systems to satisfy Title 24 energy code compliance. The application commands integration depth that favors incumbent building management system vendors.
- Reporting Tools:Automated generation of regulatory compliance documentation, investor reporting, and sustainability disclosure filings.
- Financial Analysis:Cash flow modeling, tax credit optimization, and power purchase agreement valuation engines.
Energy Management commands current installation volumes; Performance Optimization shows the steepest expansion trajectory as merchant solar exposure increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors software development for photovoltaic fleet management, while German engineering clusters drive precision modeling tools for distributed generation systems.
United States
FERC Order 2222 mandates telemetry standards for aggregated distributed energy resources, compelling independent power producers to procure cloud-native platforms. NERC CIP cybersecurity requirements strain small developer IT budgets while locking in multi-year contracts for certified vendors. California's Title 24 energy codes accelerate adoption of building-integrated solar management systems across commercial rooftops in Los Angeles and San Diego metro areas.
Germany
Energiewende distributed generation targets and commercial rooftop mandates compress procurement timelines for performance optimization suites. The EU AI Act imposes algorithmic transparency requirements on predictive maintenance tools deployed across Bavarian and North Rhine-Westphalian solar fleets. Munich and Stuttgart engineering clusters concentrate development of digital twin platforms for utility-scale asset management.
China
Dual carbon goals and centralized procurement by state-owned utilities drive demand for fleet-scale monitoring systems. MIIT data localization requirements favor domestic cloud providers for critical infrastructure deployments. Yangtze River Delta technology corridors in Shanghai and Hangzhou anchor machine learning development for irradiance forecasting algorithms serving provincial grid operators.
Spain
Merchant solar exposure and wholesale market volatility accelerate procurement of sub-hourly performance optimization tools. Grid constraint periods in the Iberian Peninsula require algorithmic curtailment scheduling to maximize revenue stack capture. Madrid and Barcelona host specialized vendors integrating satellite-derived forecasting with transmission-connected asset control systems.
Australia
Behind-the-meter solar plus storage configurations face time-of-use rate optimization pressures across commercial and residential segments. The country's national energy regulator mandates interoperability standards that favor API-first platform architectures. Sydney and Melbourne technology clusters concentrate development of mobile-native solutions for field technician workflows.
Solar Software Market Competitive Landscape
Global majors compete with regional champions across deployment architecture and integration depth, producing a tiered structure where cloud-native platforms capture utility-scale procurement while specialized vendors serve installer workflows. The vendor base separates into three strategic archetypes: industrial conglomerates with grid control heritage, venture-backed SaaS platforms targeting residential workflows, and vertically integrated hardware-software bundles from inverter manufacturers. Competitive moves concentrate on API-first architectural transitions and strategic partnerships with wholesale market platforms.
Within the utility-scale asset management tier, GE Vernova anchors digital twin integration with transmission control systems. Aurora Solar occupies a position exemplifying design automation platforms that compress pre-sales engineering cycles for residential installers. Solstice represents the regulatory compliance specialist archetype, streamlining multi-state credit allocation for community solar subscriber management.
| Leading Market Players |
|---|
| GE Vernova |
| Techstack |
| Aurora Solar |
| Borrego Solar Systems |
| TTMS |
| Solstice |
| Landbase |
| 8minute Solar Energy |
| Sunbase Data |
| Others |
Pricing and Supply Chain Analysis
Cloud-native SaaS architectures are displacing on-premise perpetual licenses and simultaneously collapsing customer acquisition costs while concentrating development talent in Silicon Valley and Berlin engineering clusters. This technology transition compresses pricing power for legacy vendors while rewarding API-first platforms with recurring revenue premiums.
Pricing Analysis
Warranty and service bundling separates premium management platforms from stripped-down monitoring tiers. Subscription-based SaaS pricing dominates utility-scale procurement, with price differentiation anchored in cybersecurity certification grade and FERC Order 2222 compliance depth. Cost compression in residential installer segments intensifies as venture-backed platforms subsidize customer acquisition through freemium entry points. Small independent power producers exhibit highest price sensitivity; utility providers with NERC CIP mandates accept premium pricing for certified disaster recovery protocols.
Supply Chain Analysis
Single-source vulnerability sits with Chinese inverter OEMs supplying proprietary communication protocols that fragment interoperability. Software development concentrates in the United States, Germany, and China, with cloud infrastructure drawing from hyperscaler networks anchored in Virginia, Frankfurt, and Shanghai. Supply chain risk centers on tariff exposure for hardware-integrated bundles crossing Pacific trade routes. Distribution runs through direct enterprise sales for utility-scale suites and channel partnerships for residential installer tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where inverter manufacturers are pursuing downstream software control to lock asset owners into captive ecosystems. Hardware-software bundling represents the decisive lever reshaping competitive boundaries.
For Market Incumbents: Extend API-first architectures to neutralize hardware bundling threats from Chinese inverter OEMs. Deepen cybersecurity certification moats around NERC CIP-compliant monitoring suites to defend against venture-backed SaaS entrants. Consolidate procurement relationships with United States independent power producers facing FERC Order 2222 telemetry mandates.
For New Entrants and Emerging Players: Mid-sized commercial enterprises in Germany's Energiewende compliance gap represent an underserved buyer archetype with unmet workflow automation needs. Community solar subscriber management across fragmented United States state jurisdictions offers white-space expansion with regulatory credit allocation as the decisive go-to-market wedge.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized regulatory compliance platforms given escalating multi-state credit allocation complexity. Long-term viability favors vendors with explainable AI architectures satisfying EU AI Act transparency mandates. Watch algorithmic transparency enforcement intensity across German and Spanish utility-scale fleets as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables rapid FERC Order 2222 telemetry compliance without internal IT expansion. |
| Acquisition of Regulatory Compliance Specialist | Accelerates multi-state credit allocation capabilities for community solar portfolios. |
| Strategic Partnership with Wholesale Market Platform | Unlocks real-time dispatch optimization for transmission-connected merchant solar assets. |
| Product Launch: Explainable AI Maintenance Suite | Addresses EU AI Act algorithmic transparency mandates across German and Spanish fleets. |
| Geographic Expansion into German Commercial Segment | Captures Energiewende distributed generation mandate acceleration in Bavaria and North Rhine-Westphalia. |
Research Methodology
SEC filings, FERC project development databases, and IEA renewable energy reports formed the secondary backbone for market sizing and competitive positioning. Primary interviews with utility planning officers, independent power producer project developers, solar EPC contractors, and grid operator integration specialists validated demand assumptions and procurement timelines. Bottom-up and top-down triangulation cross-checked segment-level penetration rates against aggregate fleet deployment data.
Bottom-up modeling anchored forecasts in individual project economics and software procurement patterns across deployment scales. Segmentation dimensions included deployment architecture, end-user sophistication tier, integration complexity depth, and regional regulatory framework cluster. CAGRs were derived from fitted adoption curves incorporating FERC Order 2222 implementation pace and EU AI Act compliance timelines. Forecast inputs encompassed hyperscaler infrastructure expansion rates and inverter OEM software bundling intensity.
Revisions become necessary when NERC CIP enforcement intensity shifts, EU AI Act transparency requirements expand, or inverter OEM proprietary protocol adoption accelerates beyond interoperability coalition traction. Forecasts reflect documented assumptions about regulatory implementation schedules and technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
United States Solar Microinverter Market