
 Europe Smart Government Market | 2026-2036
Europe Smart Government Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Government Market Insights
Modular service bundling is realigning how European public sector buyers evaluate vendor proposals. Capgemini leverages its systems integration depth to anchor large-scale digital transformation contracts across French and Benelux agencies. Siemens competes through captive hardware-software stacks that dominate urban infrastructure segments. Sopra Steria specializes in citizen-facing portals, sustaining renewal rates through deep compliance expertise with French administrative protocols.
Smart government denotes the digitization of public administration through networked sensors, cloud-native service platforms, and algorithmic decision-support systems operating at municipal to supranational scale. These configurations integrate IoT telemetry with AI-driven analytics to optimize resource allocation, emergency response, and constituent service delivery across heterogeneous legacy IT estates. E-government services retain the largest revenue share where back-office modernization contracts carry extended implementation timelines and sticky maintenance revenue. Cloud computing infrastructure represents the fastest-expanding technology layer as agencies migrate from on-premise data centers to sovereign European cloud frameworks. Smart city solutions command premium pricing where vendors bundle operational technology with long-term performance guarantees on energy, mobility, and public safety outcomes.
GDPR enforcement by national data protection authorities and the EU AI Act's risk-classification framework constrain algorithmic deployment in benefits administration and law enforcement applications. REACH chemical protocols and the EU Green Deal's decarbonization mandates shape procurement criteria for IoT hardware and data center energy profiles. Stakeholders must monitor how the European Commission's interoperability governance evolves, since future standard-setting will determine which vendor ecosystems gain preferential access to cross-border public sector frameworks.
Market Dynamics
The EU AI Act's risk-classification framework is forcing municipal procurement officers to restructure vendor evaluation criteria around algorithmic accountability and data sovereignty requirements.
Growth Catalysts
- GDPR enforcement:National data protection authorities in Germany, France, and Spain impose substantial penalties for non-compliance, compelling agencies to upgrade legacy data architectures with privacy-by-design systems.
- Federal-state coordination:Germany's standardized smart city reference architectures create scalable procurement templates that neighboring Benelux and Nordic municipalities adopt with minimal adaptation.
- Cloud migration:Sovereign European cloud frameworks from Gaia-X compliant providers enable sensitive workload migration without jurisdictional data exposure risks.
Market Restraints
- Legacy system interdependence:Decades-old COBOL-based administrative cores in French and Italian agencies create technical debt that fragments modernization timelines and inflates integration costs.
- Semiconductor supply concentration:IoT sensor and edge computing hardware depends on concentrated Asian foundry capacity, exposing municipal infrastructure projects to delivery volatility.
- REACH chemical protocols:Restrictions on rare earth processing and battery component chemistry limit domestic European manufacturing options for smart street furniture and environmental monitoring equipment.
Strategic Opportunities
- Eastern European catch-up:Polish and Romanian municipal governments lag Western counterparts in e-service penetration, creating first-mover advantages for vendors offering turnkey citizen portal platforms.
- EU Green Deal procurement mandates:Decarbonization criteria embedded in public tender specifications favor vendors bundling energy-efficient data centers with long-term carbon accounting dashboards.
- AI-edge convergence:Federated learning architectures combined with 5G municipal networks enable real-time traffic and emergency response optimization without centralized data pooling.
Industry Challenges
- Cybersecurity certification bottlenecks:The EU Cybersecurity Act's Common Criteria evaluation timelines extend 12-18 months for critical infrastructure software, delaying contract commencement.
- Interoperability governance uncertainty:The European Commission's evolving standard-setting for cross-border data exchange creates procurement hesitation as agencies await definitive technical specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Government Market |
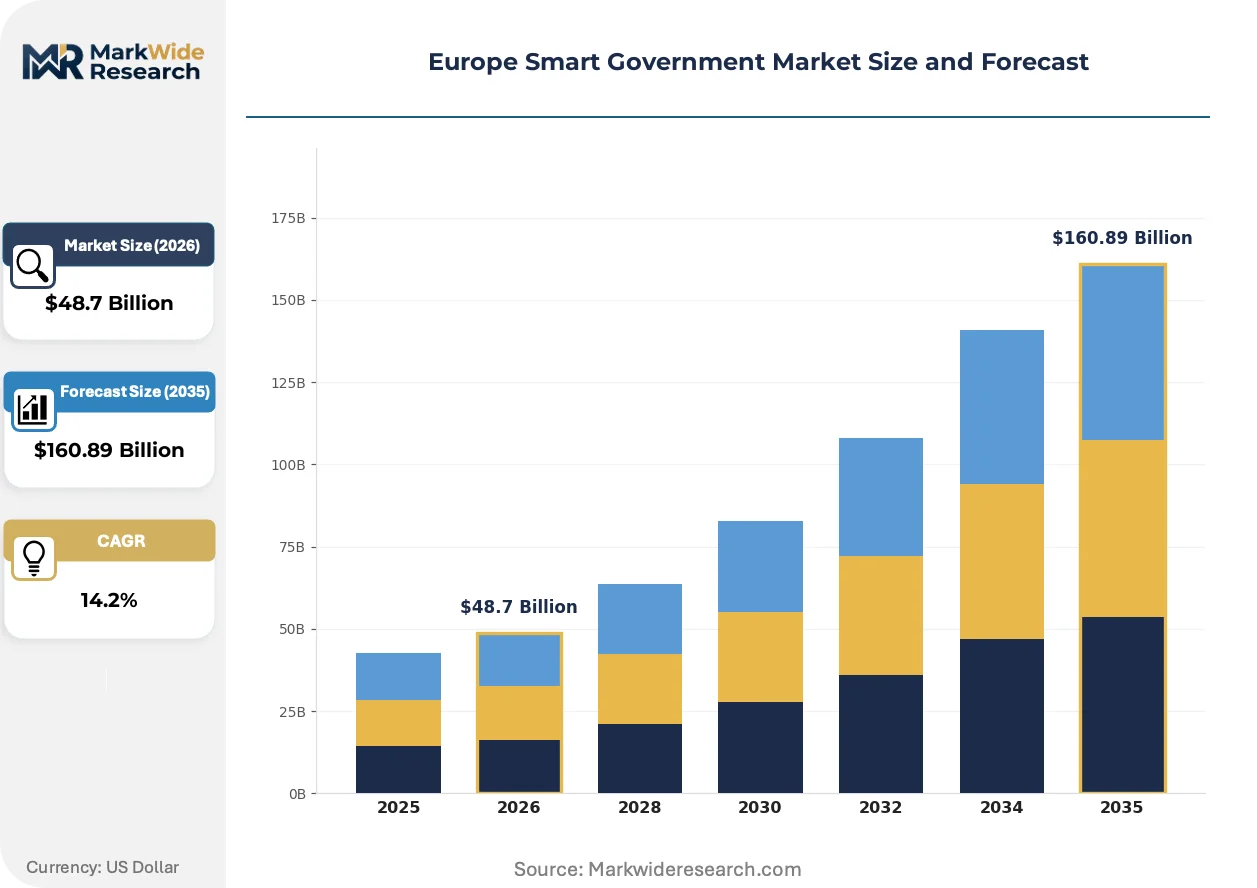
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: E-Government, Smart City Solutions, Citizen Engagement Platforms, Integrated Services End User: Government Agencies, Local Authorities, Public Institutions, Non-Profit Organizations Technology: IOT, Cloud Computing, AI, Blockchain Application: Urban Planning, Waste Management, Public Safety, Transportation |
| Companies Covered | Siemens, Schneider Electric, Bosch, Capgemini, Atos, Sopra Steria, Accenture, Ericsson, Nokia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Government Market Trends and Innovations
Algorithmic decision-support systems are migrating from pilot programs to operational deployment across benefits administration and urban planning functions, restructuring how public agencies allocate technical personnel and capital budgets.
Digital twin platforms for urban infrastructure is electrifying municipal operations by creating real-time simulation environments for traffic flow, energy grid load, and emergency response scenarios. German cities including Hamburg and Munich deploy these systems for flood prediction and transit optimization. The technology compresses planning cycles from multi-year studies to quarterly scenario iterations.
REACH chemical protocols and the EU Green Deal's embodied carbon requirements are reshaping hardware procurement specifications for IoT deployments. Municipal tender documents now mandate lifecycle environmental product declarations for sensor networks and data center equipment. French regional governments lead implementation, with Ile-de-France requiring carbon footprint thresholds for all smart city infrastructure awards.
Subscription-based service delivery is displacing perpetual license models in citizen-facing portal contracts. Spanish municipal consortiums pioneered pooled procurement of SaaS engagement platforms, with Andalusian and Catalan regional governments consolidating vendor relationships. This consolidation reduces per-capita licensing costs while increasing switching friction through embedded workflow customization.
Europe Smart Government Market Segmentation
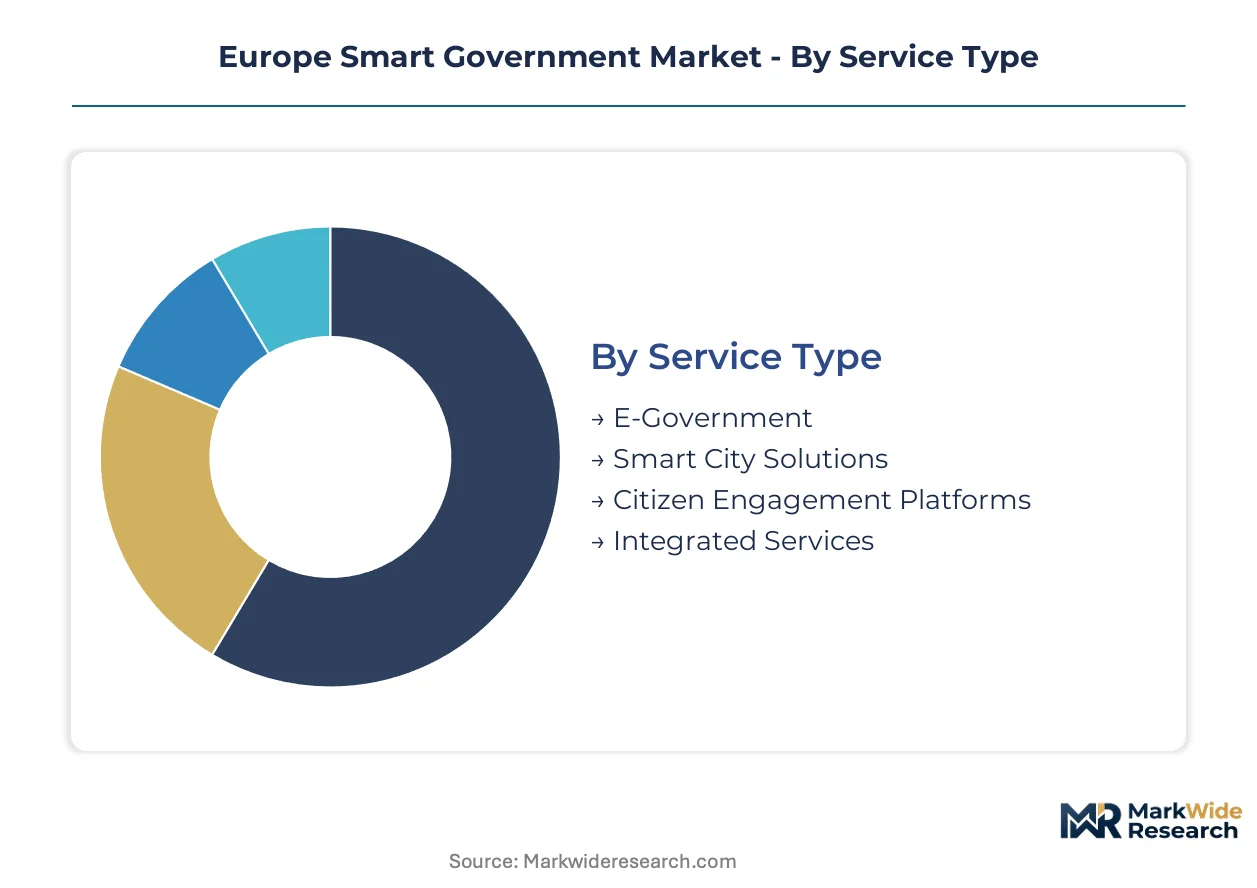
European public sector procurement cycles favor modular, interoperable solutions that minimize legacy system disruption. Segmentation reveals how vendors align service portfolios with distinct buyer risk appetites and compliance obligations across the region.
Service Type:
Upgrade cycles vary sharply by contract structure, with perpetual-license replacements lagging SaaS transitions by three to five years in most national markets.
- E-Government:Back-office digitization spanning tax administration, benefits processing, and document management. German federal agencies drive consolidation through standardized procurement frameworks that neighboring Austria and Switzerland adopt with localization.
- Smart City Solutions:Integrated urban infrastructure combining IoT sensors, traffic management, and energy optimization. Spanish municipalities including Barcelona and Madrid bundle operational technology with twenty-year performance guarantees on carbon reduction targets.
- Citizen Engagement Platforms:Digital service portals for permit applications, tax payments, and constituent feedback.
- Integrated Services:End-to-end transformation contracts combining software, hardware, and change management.
Volume placements concentrate in E-Government; the faster expansion belongs to Smart City Solutions.
End User:
Buyer sophistication stratifies procurement complexity, with national agencies demanding enterprise-grade security certifications that municipal offices often waive.
- Government Agencies:National ministries and regulatory bodies operating classified systems. France's ANSSI cybersecurity mandates force these buyers toward sovereign cloud providers with Common Criteria EAL4+ certifications, extending vendor qualification timelines.
- Local Authorities:Municipal and regional governments delivering frontline services. Polish and Romanian city governments represent the steepest expansion trajectory as EU cohesion funds finance first-generation digital infrastructure.
- Public Institutions:Universities, hospitals, and utilities with hybrid public-private governance.
- Non-Profit Organizations:Social service providers contracting for grant management and beneficiary tracking.
Contract value clusters with Government Agencies; Local Authorities deliver the broadest addressable base.
Technology:
Deployment maturity separates proven infrastructure from experimental layers, with procurement officers weighting operational track records against innovation premiums.
- IOT:Sensor networks for environmental monitoring, infrastructure health, and occupancy tracking. REACH chemical protocols restrict battery chemistry and rare earth sourcing, forcing hardware vendors toward modular, replaceable component designs.
- Cloud Computing:Sovereign European frameworks from Gaia-X compliant providers. German federal-state coordination on reference architectures accelerates cross-border standardization, reducing adaptation costs for Benelux and Nordic implementations.
- AI:Algorithmic decision-support for benefits eligibility, fraud detection, and predictive maintenance.
- Blockchain:Distributed ledger applications for document verification and supply chain transparency.
Deployment scale favors Cloud Computing; AI applications gain share fastest as the EU AI Act clarifies compliance pathways.
Application:
Use-case specificity determines integration depth, with safety-critical systems demanding higher assurance levels than administrative automation.
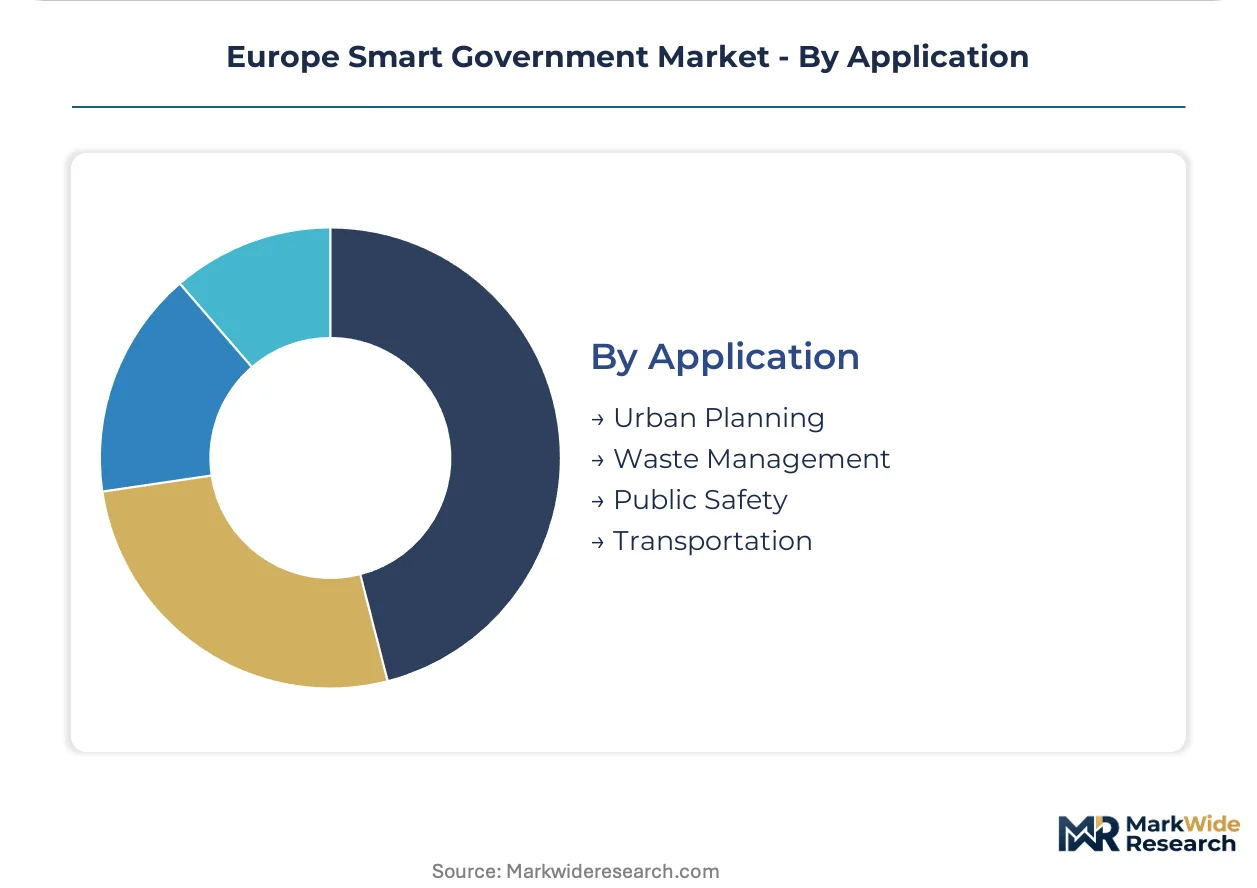
- Urban Planning:Digital twin simulations for zoning, transit routing, and flood prediction. Hamburg and Munich deploy these systems for real-time scenario modeling that compresses multi-year studies into quarterly iterations.
- Public Safety:Emergency response optimization and predictive policing. GDPR enforcement by German and French data protection authorities constrains facial recognition deployment, limiting vendor addressable scope.
- Waste Management:Sensor-optimized collection routing and landfill monitoring.
- Transportation:Intelligent traffic systems and multimodal mobility platforms.
Capital allocation tilts toward Urban Planning; Public Safety commands the highest per-project margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gaia-X federated data infrastructure initiative anchors smart government investment concentration across northwestern Europe, creating compliant cloud corridors that channel procurement toward sovereign European providers.
Germany
Federal-state coordination on standardized smart city reference architectures accelerates scalable procurement templates. The EU AI Act's risk-classification framework shapes algorithmic deployment criteria in benefits administration. Hamburg and Munich operate digital twin platforms for flood prediction and transit optimization.
France
ANSSI cybersecurity mandates force national agencies toward sovereign cloud providers with Common Criteria EAL4+ certifications. GDPR enforcement by CNIL imposes substantial penalties for non-compliance, compelling privacy-by-design system upgrades. Ile-de-France regional governments mandate carbon footprint thresholds for smart city infrastructure awards.
Spain
Andalusian and Catalan regional governments consolidate vendor relationships through pooled SaaS procurement of citizen engagement platforms. Municipal consortiums pioneer subscription-based service delivery models. Barcelona and Madrid bundle operational technology with twenty-year performance guarantees on carbon reduction targets.
United Kingdom
Post-Brexit regulatory divergence creates procurement hesitation as agencies await definitive technical specifications for cross-border data exchange. Government Digital Service frameworks emphasize interoperability governance. Greater London Authority deploys integrated mobility platforms combining IoT sensors with real-time traffic management.
Poland
EU cohesion funds finance first-generation digital infrastructure in municipal governments lagging Western European e-service penetration. National cloud strategies align with Gaia-X compliance requirements. Warsaw and Krakow emerge as testbeds for turnkey citizen portal platforms targeting Eastern European catch-up demand.
Europe Smart Government Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement channels. Systems integrators anchor large-scale transformation contracts while hardware-software stack vendors dominate urban infrastructure segments. Three archetypes prevail: captive technology conglomerates, compliance-specialized IT services firms, and sovereign cloud infrastructure providers. Competitive moves concentrate on strategic partnerships with municipal consortiums and portfolio diversification into AI-edge convergence applications.
Within the systems integration tier, Capgemini and Sopra Steria occupy positions shaped by deep administrative protocol expertise. Siemens anchors the captive hardware-software stack segment through urban infrastructure dominance. These three exemplify how vendor selection criteria increasingly weight algorithmic accountability and data sovereignty compliance alongside technical capability.
| Leading Market Players |
|---|
| Siemens |
| Schneider Electric |
| Bosch |
| Capgemini |
| Atos |
| Sopra Steria |
| Accenture |
| Ericsson |
| Nokia |
| Others |
Pricing and Supply Chain Analysis
Cloud-native service migration across European public agencies is compressing infrastructure costs while concentrating procurement power among Gaia-X compliant providers. Sovereign data framework mandates from the EU AI Act simultaneously reshape vendor qualification economics and lock in preferred supplier relationships for compliant infrastructure stacks.
Pricing Analysis
Short lead-time premiums dominate municipal procurement, with agencies paying 15-25% markups for rapid deployment of GDPR-compliant citizen portals versus standard-cycle implementations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, where Common Criteria EAL4+ systems command substantial premiums over baseline CE-marked alternatives. Price erosion runs through economy-tier SaaS subscriptions as Spanish and Polish municipal consortiums consolidate volumes through pooled procurement frameworks. Local authorities in Eastern Europe exhibit highest price sensitivity, while German federal agencies prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries supplying edge computing hardware for municipal IoT deployments. European smart government infrastructure draws from concentrated Asian supply bases in Taiwan, South Korea, and China for sensor chipsets, battery components, and networking equipment. Rare earth processing dependencies for environmental monitoring equipment create exposure to REACH chemical protocol restrictions on battery chemistry. Distribution runs through systems integrators like Capgemini and Sopra Steria who bundle hardware procurement with long-term service contracts, insulating end-users from direct supply volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework transforms compliance capability into a durable barrier-to-entry moat, privileging vendors with pre-certified algorithmic systems and established data governance protocols.
For Market Incumbents: Anticipate margin compression from sovereign cloud providers expanding into application layers by hardening vertical integration into edge computing hardware and federated learning infrastructure. Fortify position through exclusive partnerships with German federal-state reference architecture programs, creating switching costs for municipal buyers. Prioritize Common Criteria certification investments ahead of EU Cybersecurity Act enforcement timelines. For New Entrants and Emerging Players: Capture first-mover advantages in Polish and Romanian municipal markets where EU cohesion funds finance greenfield digital infrastructure absent legacy system entanglement. Target turnkey citizen portal platforms with embedded GDPR compliance modules, addressing the steepest capability gap in Eastern European local authorities. Deploy SaaS-native delivery models with rapid implementation cycles to outpace incumbent systems integrators on speed-to-value metrics. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified IT services conglomerates seeking compliance-specialized capabilities. Long-term viability hinges on regulatory certification depth rather than technology differentiation alone, favoring targets with established ANSSI or BSI security validations. Monitor European Commission interoperability governance announcements as inflection signals for vendor ecosystem reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Gaia-X Compliance Certification | Unlocks sovereign cloud procurement channels for sensitive government workloads across Germany and France. |
| Digital Twin Platform Integration | Compresses urban planning cycles for Hamburg and Munich municipal clients through real-time simulation capabilities. |
| Eastern European Geographic Expansion | Captures EU cohesion fund flows into Polish and Romanian first-generation digital infrastructure deployments. |
| AI-Edge Convergence R&D Investment | Enables federated learning architectures that satisfy GDPR data localization requirements for benefits administration. |
| Strategic Partnership with Municipal Consortiums | Secures multi-year SaaS revenue streams through Andalusian and Catalan pooled procurement frameworks. |
Research Methodology
Document review covered EU regulatory filings, national procurement databases, and vendor contract disclosures, complemented by interviews with municipal CIOs, systems integration executives, and data protection officers. Secondary validation drew from Gaia-X framework documentation, EDPB enforcement action records, and European Commission interoperability governance proposals. Bottom-up project pipeline analysis triangulated against top-down public sector IT spending forecasts across the analysis window.
Historical deployment timelines cross-referenced against expert panel inputs on regulatory implementation pacing shaped the analytical framework. Modeled dimensions span service type, end-user tier, technology layer, and application domain, with particular weighting for GDPR compliance status and sovereign cloud certification. CAGRs derived from segment-level growth rate reconciliation with aggregate market trajectory constraints, incorporating EU AI Act phase-in schedules and cohesion fund disbursement patterns as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to European Commission standard-setting decisions and semiconductor supply chain reconfiguration. Outcomes reflect assumptions around regulatory enforcement intensity and public sector budget continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Legaltech Market
Digital Solutions
Ediscovery Solution Market
Digital Solutions
Database Management Platform Market
Digital Solutions
France ICT Market
Digital Solutions
Cloud Monetization Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
US Customer Communication Management (CCM) Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Virtual Desktop Infrastructure (VDI) Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
IT Operations Management Market