
 US Customer Communication Management (CCM) Market | 2026-2036
US Customer Communication Management (CCM) Market Size, Share, and Industry Trends Forecast 2026-2036
US Customer Communication Management (CCM) Market Analytics
Texas data center expansion is rewriting where CCM infrastructure gets deployed. OpenText Corporation anchors its North American cloud operations through Dallas-Fort Worth facilities. Quadient SA specializes in high-volume print-to-digital migration tools for regulated industries. Smart Communications Inc. competes on API-first architecture for real-time customer engagement.
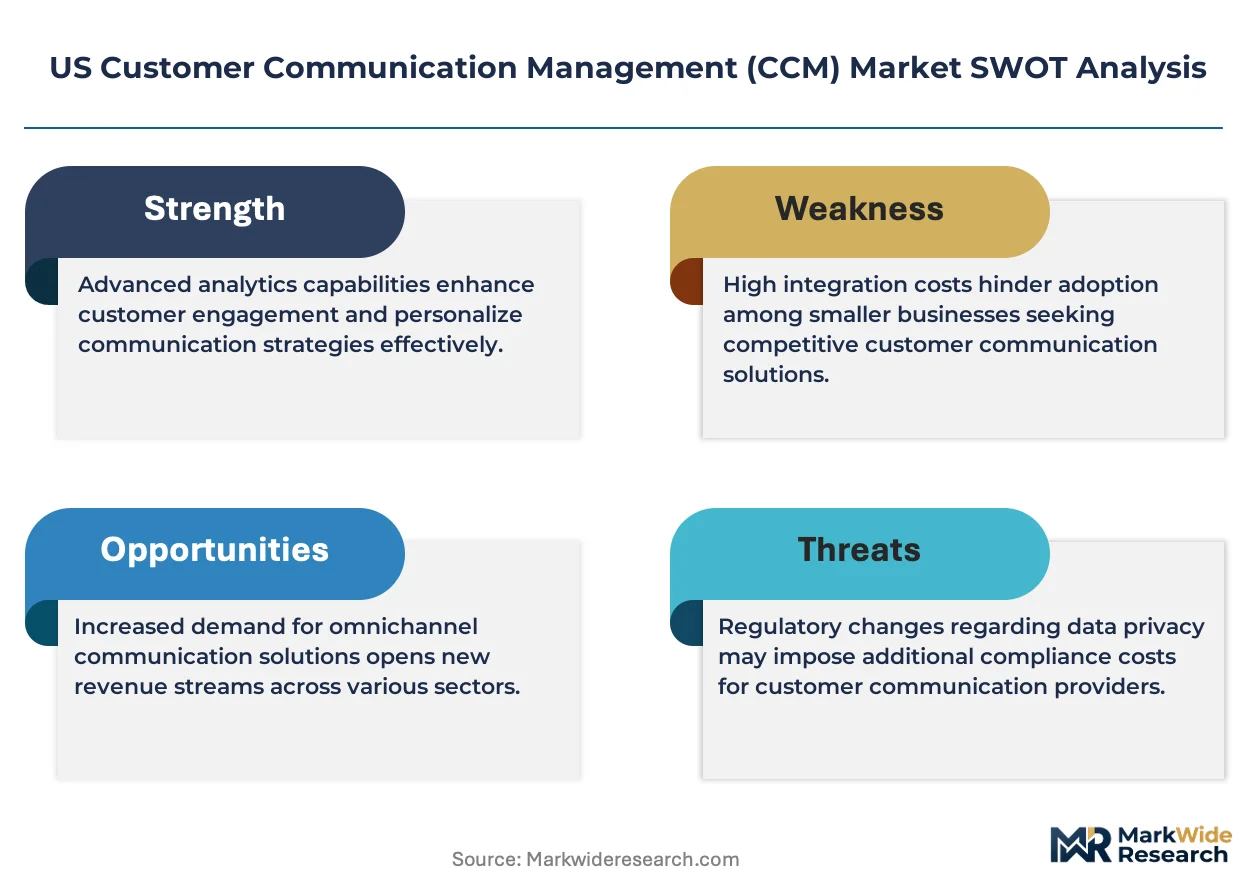
Customer Communication Management encompasses software platforms that orchestrate the creation, delivery, storage, and retrieval of outbound communications across channels including print, email, SMS, and social media, typically integrating with core business systems through standardized APIs to ensure template governance and regulatory compliance. The primary purpose is to enable organizations to maintain consistent, personalized, and legally defensible customer interactions at scale. Cloud-based and SaaS deployment models are capturing the fastest expansion as insurers and banks retire mainframe-dependent legacy stacks. On-premise installations persist among federal agencies and defense contractors with stringent data sovereignty requirements. Enterprise customer types generate the deepest margin pools due to multi-year implementation contracts and professional services attach rates.
FCC rules on robocalling and caller ID authentication under STIR/SHAKEN protocols are reshaping how CCM platforms handle voice-adjacent outbound channels. HIPAA requirements from HHS and state-level insurance regulations from NAIC-member commissioners mandate audit trails for every patient or policyholder touchpoint. Stakeholders must evaluate whether their current CCM stack can absorb emerging AI-generated content governance standards before enforcement timelines crystallize.
Market Dynamics
HIPAA Privacy Rule enforcement and HHS guidance on electronic health information are forcing healthcare providers to replace legacy mainframe-dependent communication stacks with cloud-native CCM platforms that deliver audit-ready patient engagement.
Growth Catalysts
- HIPAA mandates:Healthcare providers face escalating penalties for non-compliant patient communications. The HHS Office for Civil Rights is prioritizing enforcement against organizations lacking secure electronic health information exchange capabilities.
- STIR/SHAKEN protocols:FCC robocalling rules require authenticated caller ID for voice-adjacent outbound channels. Financial services firms in the Northeast belt are upgrading CCM infrastructure to maintain contact center effectiveness.
- California health-tech corridor:Concentrated demand from Kaiser Permanente, Sutter Health, and digital health startups is creating localized vendor ecosystem density and implementation expertise.
Market Restraints
- Data center concentration risk:Texas facilities dominate North American cloud infrastructure deployment. OpenText and other hyperscalers' Dallas-Fort Worth concentration creates regional weather and grid vulnerability exposure.
- Federal data sovereignty requirements:Defense contractors and intelligence agencies maintain on-premise CCM installations. The cost premium versus cloud alternatives constrains vendor addressable market expansion.
- Legacy system entrenchment:COBOL-dependent policy administration systems at major insurers resist API integration. Print-to-digital migration tools face extended implementation timelines.
Strategic Opportunities
- AI-generated content governance:Emerging standards for synthetic media disclosure and bias auditing will create compliance tooling demand. Vendors positioning early capture implementation services attach rates.
- API-first architecture convergence:Real-time customer engagement requirements are pulling CCM platforms toward event-driven integration with CRM and core banking systems. Smart Communications' technical approach is becoming table stakes.
- State-level insurance regulation harmonization:NAIC-member commissioners are aligning audit trail requirements across member states. Multi-state insurers seek unified CCM deployments reducing jurisdictional fragmentation costs.
Industry Challenges
- Mainframe integration complexity:Core policy and claims systems at legacy insurers resist real-time API connectivity. Professional services margins erode during extended data mapping and transformation projects.
- Template governance talent scarcity:Legal-technical hybrid professionals who understand both regulatory defensibility and document composition logic command premium compensation. Vendor bench depth limits implementation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Customer Communication Management (CCM) Market |
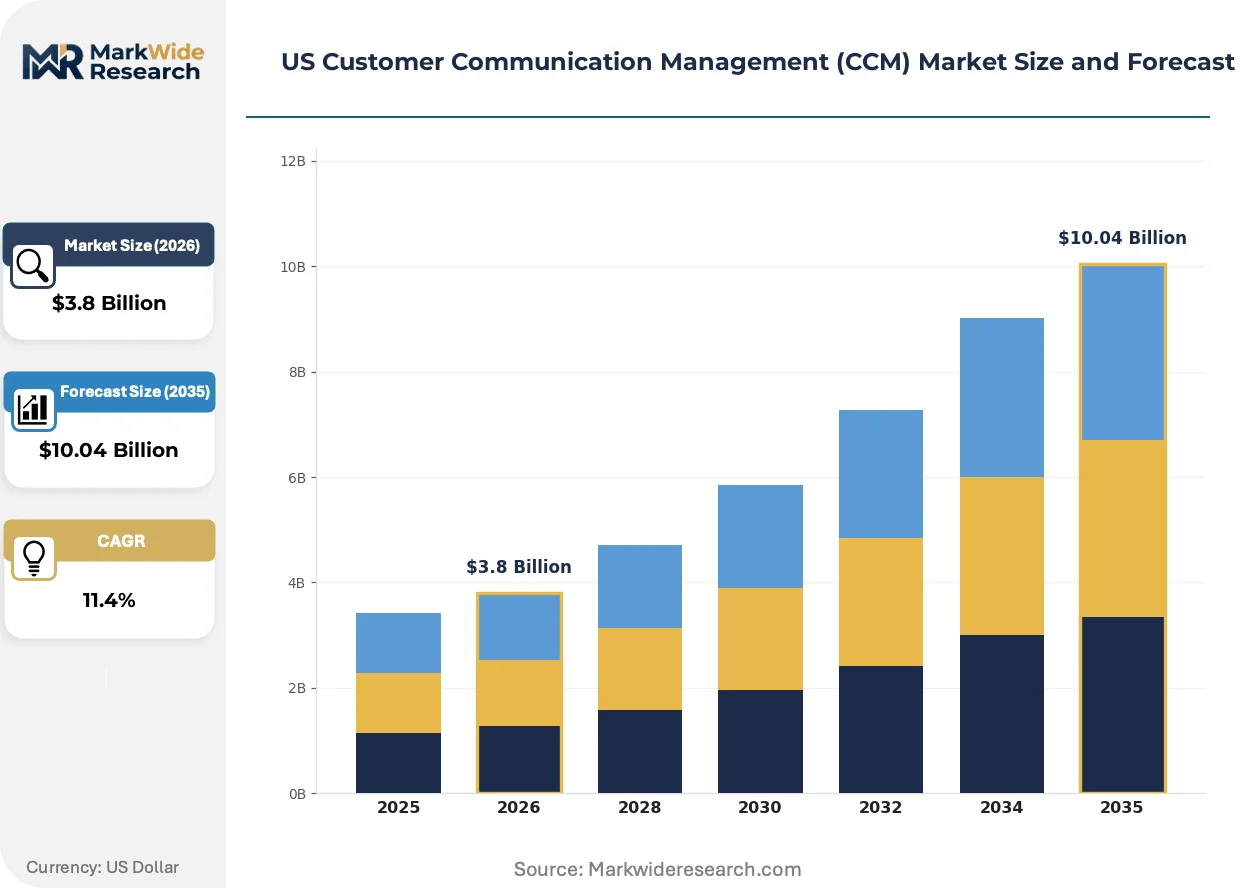
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS Industry Vertical: Banking, Insurance, Healthcare, Retail Customer Type: Small Business, Mid-Market, Enterprise, Government Communication Type: Email, SMS, Print, Social Media |
| Companies Covered | Quadient SA, OpenText Corporation, Smart Communications Inc., Messagepoint Inc., Cincom Systems, Inc., Doxim Inc., Sefas Innovation Inc., Pitney Bowes Inc., Topdown Systems Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Customer Communication Management (CCM) Market Evolving Landscape
Generative AI capabilities are embedding into CCM platforms, creating tension between personalization scale and regulatory defensibility. Vendors race to build governance layers that satisfy emerging AI disclosure requirements.
Natural language generation for patient and policyholder communications is hybridizing template-based output with dynamic content assembly. Healthcare providers in California's health-tech corridor are piloting these capabilities for appointment reminders and care gap alerts. The technology is compressing time-to-content-deployment from weeks to hours while introducing new liability exposure around hallucinated medical guidance.
HHS guidance on information blocking and the 21st Century Cures Act interoperability mandates are reshaping CCM data architecture requirements. Healthcare providers must now enable patient-directed data export through standardized APIs. Organizations with cloud-native CCM stacks are responding faster than those maintaining on-premise installations with custom integration layers.
Subscription pricing for CCM capabilities is displacing perpetual license models among mid-market insurers and regional health systems. Buyers prefer operational expenditure treatment and demand automatic feature updates. This shift is most visible in the Northeast financial services belt, where banks retiring legacy document composition systems prioritize SaaS deployment to accelerate decommissioning timelines.
US Customer Communication Management (CCM) Market Segmentation
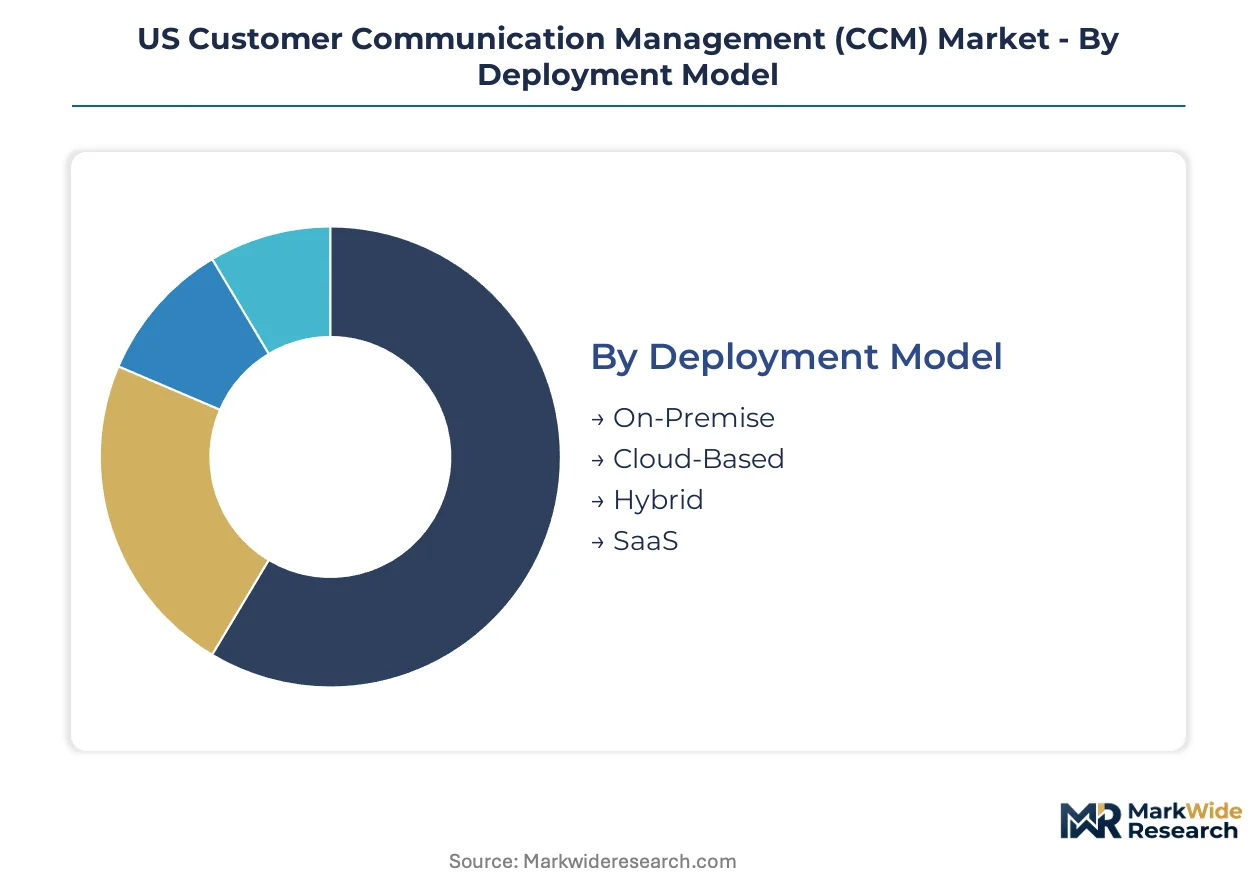
US CCM segmentation reveals how deployment choices, regulatory exposure, and customer scale reshape vendor go-to-market priorities. Each dimension carries distinct margin profiles and implementation complexity that determine competitive positioning.
Deployment Model:
Mature on-premise installations coexist with emerging cloud-native architectures as federal data sovereignty requirements fragment adoption timelines.
- On-Premise:Defense contractors and intelligence agencies mandate air-gapped installations for classified patient and policyholder communications. Texas data center concentration risk—exemplified by OpenText's Dallas-Fort Worth facilities—drives secondary site redundancy planning among federal buyers.
- Cloud-Based:Healthcare providers in California's health-tech corridor accelerate migration to meet HIPAA audit trail mandates. Kaiser Permanente and Sutter Health deployments demonstrate how cloud-native stacks compress patient engagement system upgrade cycles from years to quarters.
- Hybrid:Northeast financial services firms blend on-premise core systems with cloud burst capacity for seasonal document volume spikes.
- SaaS:Regional health systems and mid-market insurers prefer operational expenditure treatment with automatic feature updates.
Cloud-Based handles the majority of new throughput; SaaS is gaining share fastest among buyers retiring legacy mainframe stacks.
Industry Vertical:
Cost tier differentiation separates regulated industries with compliance-driven RFP cycles from retail sectors prioritizing speed-to-deployment.
- Banking:Northeast financial services belt institutions—concentrated in Boston and New York—upgrade CCM infrastructure to maintain STIR/SHAKEN authenticated caller ID compliance. FCC robocalling rules force voice-adjacent channel reinvestment.
- Insurance:NAIC-member state commissioners' harmonized audit trail requirements pull multi-state carriers toward unified platform deployments. COBOL-dependent policy administration systems resist API integration, extending professional services timelines.
- Healthcare:HIPAA Privacy Rule enforcement and HHS information blocking guidance demand patient-directed data export capabilities.
- Retail:API-first architecture requirements for real-time customer engagement drive faster procurement cycles with lighter governance overhead.
Insurance carries the deepest implementation backlog; Healthcare is expanding most quickly as penalties for non-compliant patient communications escalate.
Customer Type:
Volume concentration determines whether vendors pursue high-touch enterprise contracts or automated mid-market onboarding.
- Enterprise:Multi-year implementation contracts with professional services attach rates above software license value. Template governance talent scarcity—legal-technical hybrid professionals—limits vendor bench depth and constrains delivery velocity.
- Government:Federal agencies maintain on-premise installations despite cloud cost premiums, prioritizing data sovereignty over operational efficiency.
- Mid-Market:Subscription pricing displacement of perpetual licenses accelerates decommissioning timelines for legacy document composition systems.
- Small Business:Self-service configuration tools with pre-built regulatory templates reduce implementation dependency.
Enterprise absorbs the largest professional services capacity; Mid-Market is climbing the fastest as SaaS pricing normalizes.
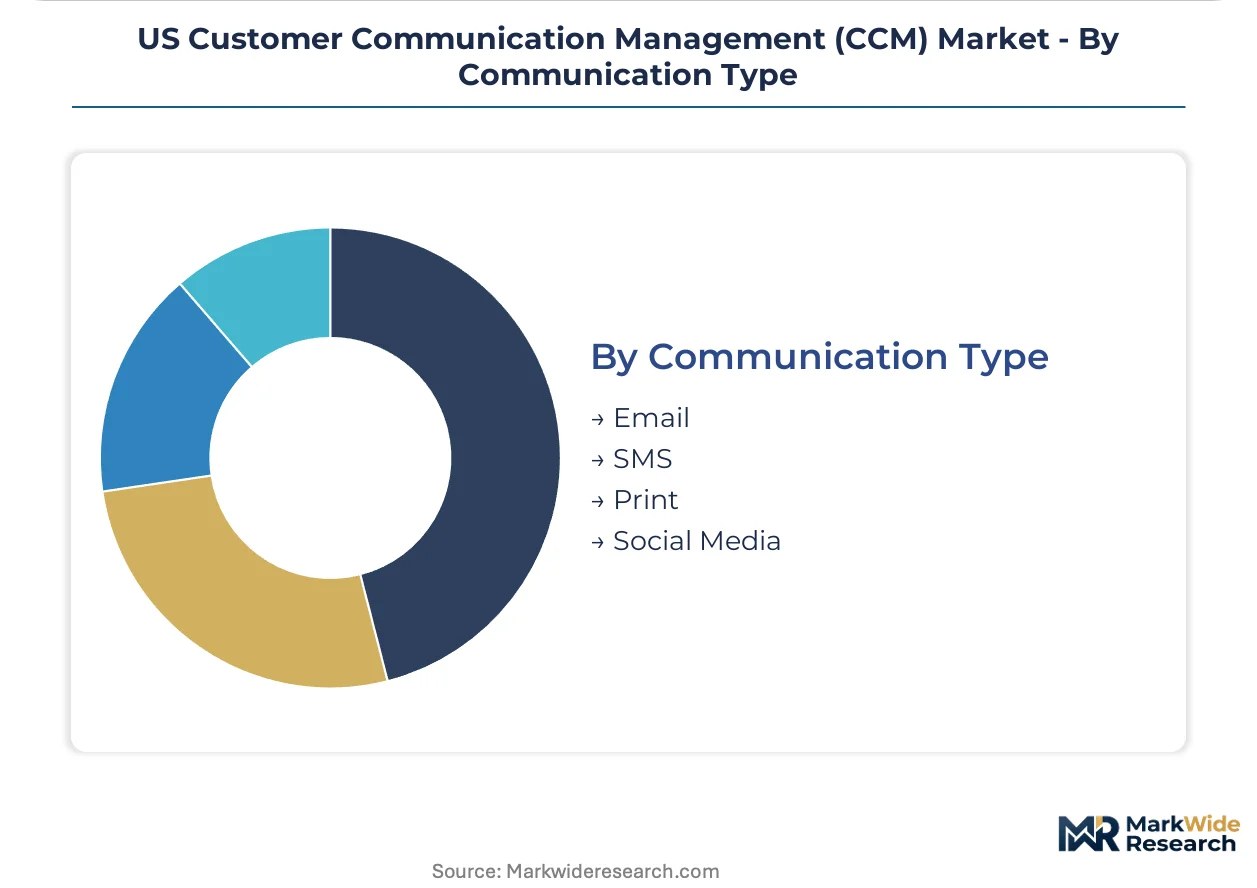
Communication Type:
Application urgency varies by channel maturity and regulatory audit requirements.
- Email:Remains the default patient and policyholder touchpoint with established template governance protocols.
- SMS:Appointment reminders and care gap alerts in California health systems pilot natural language generation for dynamic content assembly.
- Print:Quadient SA specializes in high-volume print-to-digital migration tools for regulated industries with legacy output dependencies.
- Social Media:Emerging AI-generated content governance standards create compliance tooling demand before enforcement timelines crystallize.
Email maintains the broadest footprint; SMS shows the steepest expansion trajectory as healthcare providers prioritize mobile-first patient engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas data center concentration dominates North American CCM infrastructure deployment, with hyperscaler facilities clustering in Dallas-Fort Worth. This geographic pattern creates regional vulnerability exposure while shaping vendor site selection strategies for healthcare and financial services workloads.
California
Kaiser Permanente and Sutter Health drive concentrated demand in the health-tech corridor spanning San Francisco to San Diego. HIPAA Privacy Rule enforcement from HHS accelerates cloud-native stack adoption. Los Angeles and San Diego health systems pilot natural language generation for patient appointment workflows.
Texas
Dallas-Fort Worth anchors OpenText Corporation's North American cloud operations with multi-facility redundancy planning. FCC STIR/SHAKEN compliance requirements pull regional financial services firms toward authenticated caller ID infrastructure. Austin's digital health startup density creates secondary implementation expertise clusters.
Northeast Corridor
Boston and New York financial institutions upgrade CCM systems to maintain contact center effectiveness under robocalling regulations. NAIC-member state commissioners' harmonized audit trail requirements unify multi-state carrier deployments. Hartford insurance legacy system migrations extend professional services timelines.
Mid-Atlantic
Federal agencies and defense contractors in Northern Virginia and Maryland mandate air-gapped on-premise installations for classified communications. Data sovereignty requirements override cloud cost efficiency calculations. Baltimore healthcare systems balance HHS interoperability mandates against legacy infrastructure constraints.
Pacific Northwest
Seattle's enterprise software ecosystem supports API-first architecture adoption for real-time customer engagement platforms. Subscription pricing displacement accelerates among mid-market insurers retiring document composition systems. Portland regional health systems evaluate hybrid deployment models for seasonal volume spikes.
US Customer Communication Management (CCM) Market Competitive Landscape
Enterprise platform specialists and vertical-focused solution providers split the market between multi-year implementation contracts and rapid-deployment SaaS offerings. The vendor base organizes around three strategic archetypes: legacy document composition incumbents with mainframe integration expertise, cloud-native challengers with API-first architectures, and print-to-digital migration specialists serving regulated industries. Competitive moves concentrate on M&A activity targeting template governance capabilities and strategic partnerships with core system vendors.
Within the enterprise platform tier, OpenText Corporation and Quadient SA exemplify divergent specialization strategies. OpenText anchors North American operations through Texas-based cloud infrastructure. Quadient occupies a position serving high-volume regulated output requirements. Smart Communications Inc. represents the API-first architecture approach that is becoming baseline for real-time engagement procurement.
| Leading Market Players |
|---|
| Quadient SA |
| OpenText Corporation |
| Smart Communications Inc. |
| Messagepoint Inc. |
| Cincom Systems, Inc. |
| Doxim Inc. |
| Sefas Innovation Inc. |
| Pitney Bowes Inc. |
| Topdown Systems Corporation |
| Others |
Value Network & Pricing Analysis
Texas data center concentration risk determines both the premium tier spreads for redundant infrastructure and the geographic shape of vendor supply networks. HIPAA compliance mandates and FCC STIR/SHAKEN enforcement create regulatory chokepoints that compress margins for non-compliant tiers while rewarding certified deployments.
Pricing Analysis
HIPAA dictates the pricing tier structure across the US CCM landscape, separating audit-ready cloud-native platforms from legacy on-premise installations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and professional services attach rates. Cost compression in the mid-market tier is intensifying because subscription pricing models displace perpetual licenses. Regional health systems exhibit highest price sensitivity; federal agencies with data sovereignty mandates show least sensitivity.
Supply Chain Analysis
Export-control restrictions on advanced encryption and AI acceleration hardware limit component flows into domestic CCM infrastructure buildouts. Supply chains draw from Taiwan for semiconductor components, Ireland for EU data residency compliance hardware, and domestic Texas facilities for final assembly. Dependencies center on specialized server-grade processors, high-availability storage arrays, and API gateway appliances. Single-source vulnerability concentrates in Texas hyperscaler campuses. Distribution runs through direct vendor engagement for enterprise accounts and cloud marketplaces for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the US CCM market as HIPAA enforcement and AI governance standards create specialized compliance niches that reward focused expertise over broad platform coverage.
For Market Incumbents: Build regulatory certification moats through early investment in AI-generated content governance tooling and template audit capabilities. Acquire template governance talent pools to address bench depth constraints. Expand professional services capacity in California's health-tech corridor to capture Kaiser Permanente and Sutter Health upgrade cycles. For New Entrants and Emerging Players: Build out API-first architecture specialization targeting mid-market insurers retiring COBOL-dependent policy systems. Focus penetration on Northeast financial services belt institutions seeking STIR/SHAKEN compliance without full platform replacement. Pursue channel partnerships with core banking system vendors to accelerate procurement cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical specialists with regulatory workflow expertise. Long-term viability hinges on cloud-native deployment share expansion and AI governance tooling integration. Target acquisition archetypes include print-to-digital migration specialists and template governance platform developers. Monitor HHS enforcement velocity on information blocking penalties as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Layer Development | Positions vendors ahead of HHS synthetic media disclosure mandates for patient communications. |
| Template Governance Platform Acquisition | Addresses talent scarcity constraining implementation velocity at enterprise accounts. |
| API-First Architecture Partnership | Accelerates real-time CRM integration for Northeast financial services belt institutions. |
| Texas Data Center Redundancy Buildout | Mitigates regional weather and grid vulnerability exposure for federal agency workloads. |
| HIPAA Compliance Certification Program | Creates defensible differentiation against non-certified competitors in healthcare vertical. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with healthcare CIOs, insurance IT procurement officers, CCM platform engineers, and federal agency contracting officers. Secondary validation drew from HHS enforcement bulletins, FCC STIR/SHAKEN implementation reports, NAIC state commissioner guidance, SEC vendor filings, and hospital procurement databases. Bottom-up deployment model sizing was triangulated against top-down vertical spending estimates.
Calibration across the analysis window employed deployment model, customer scale tier, vertical regulatory exposure, and geographic cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs included HIPAA penalty escalation schedules, cloud migration velocity at California health systems, and mainframe decommissioning timelines at Hartford insurers.
Stress conditions across HHS enforcement intensity, Texas grid reliability events, and AI governance standard crystallization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and vendor consolidation velocity. Material shifts in federal data sovereignty policy or HIPAA penalty structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cheque Scanner Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Consent Management Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
Europe Online Dating Services Market
Digital Solutions
Smart Signage Market
Digital Solutions
Digital Library Software Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Middle East and Africa Digital Signage Market