
 Computer Aided Engineering Market | 2026-2036
Computer Aided Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Aided Engineering Market Intelligence
Aftermarket service revenue is tilting toward subscription-based platform licensing as vendors pursue recurring income streams. Siemens Digital Industries Software leverages its hardware-software integration to anchor long-term enterprise contracts. Dassault Systèmes competes through vertical industry specialization, while Altair Engineering Inc. differentiates via pay-per-use cloud simulation models.
Computer aided engineering encompasses computational methods for simulating physical phenomena, product behavior, and manufacturing processes using numerical solvers, mesh discretization, and high-performance computing clusters to predict stress, thermal, and fluid dynamics outcomes before physical prototyping. Its primary industrial purpose is reducing design iteration cycles, material waste, and certification risk across complex engineered systems. Finite element analysis commands the largest installed base among product types due to decades of structural engineering reliance, while cloud-based deployment represents the fastest-expanding technology dimension as enterprises migrate workloads away from capital-intensive on-premises clusters. Multibody dynamics holds concentrated demand within automotive OEMs for vehicle kinematics and durability testing.
The US Federal Aviation Administration mandates simulation-based certification pathways for aircraft structural integrity, directly expanding demand for validated analysis tools. Germany's KBA and the EU Machinery Directive enforce digital twin and stress-testing documentation requirements that elevate CAE from optional to compulsory in European manufacturing. China's MIIT promotes indigenous industrial software development through standards harmonization with GB frameworks, reshaping vendor market access conditions. Stakeholders must monitor how sovereign cloud mandates and cross-border data governance fragment previously unified engineering software procurement patterns.
Market Dynamics
Cloud-native simulation architectures are compressing CAE deployment cycles from months to hours, forcing incumbent vendors to restructure licensing models around consumption-based metering rather than perpetual seat sales.
Growth Catalysts
- EU Machinery Directive mandates:European manufacturers must document stress-testing and digital twin validation for machinery certification, elevating CAE from optional to compulsory in industrial equipment supply chains.
- Automotive electrification:Battery pack thermal management and crashworthiness simulation now dominate OEM R&D spending, with multibody dynamics workloads expanding for electric vehicle platform development.
- High-performance computing democratization:GPU-accelerated solvers and containerized deployment are extending advanced simulation access to mid-tier engineering consultancies previously priced out of on-premises clusters.
Market Restraints
- Specialized talent scarcity:Mesh generation expertise and multiphysics solver configuration skills command premium compensation, constraining enterprise scaling of simulation teams.
- Data sovereignty fragmentation:China's MIIT cloud localization requirements and EU GDPR cross-border transfer restrictions are bifurcating engineering data architectures, raising compliance overhead for multinational deployments.
- Legacy license lock-in:Decades of accumulated finite element analysis model libraries in proprietary formats create substantial switching costs for enterprises evaluating alternative solver platforms.
Strategic Opportunities
- India industrial software localization:The country's PLI scheme for manufacturing and BIS standards harmonization are creating entry points for CAE vendors establishing domestic cloud infrastructure partnerships.
- Generative design convergence:Integration of topology optimization with additive manufacturing process simulation is opening new service revenue streams in aerospace component qualification workflows.
- AI-augmented preprocessing:Machine learning-based mesh adaptation and boundary condition prediction are reducing manual setup time, enabling vendors to capture value through automated simulation pipelines.
Industry Challenges
- Certification timeline compression:FAA and EASA validation requirements for simulation-based airworthiness evidence demand extensive correlation studies against physical test data, extending product qualification schedules.
- Multiphysics integration complexity:Coupling structural, thermal, and fluid dynamics solvers across heterogeneous software stacks requires specialized systems engineering expertise that remains scarce in most industrial organizations.
- Cross-functional workflow friction:Design engineers and simulation specialists operate in disconnected toolchains, creating iteration delays as geometric changes propagate through manual handoff processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Aided Engineering Market |
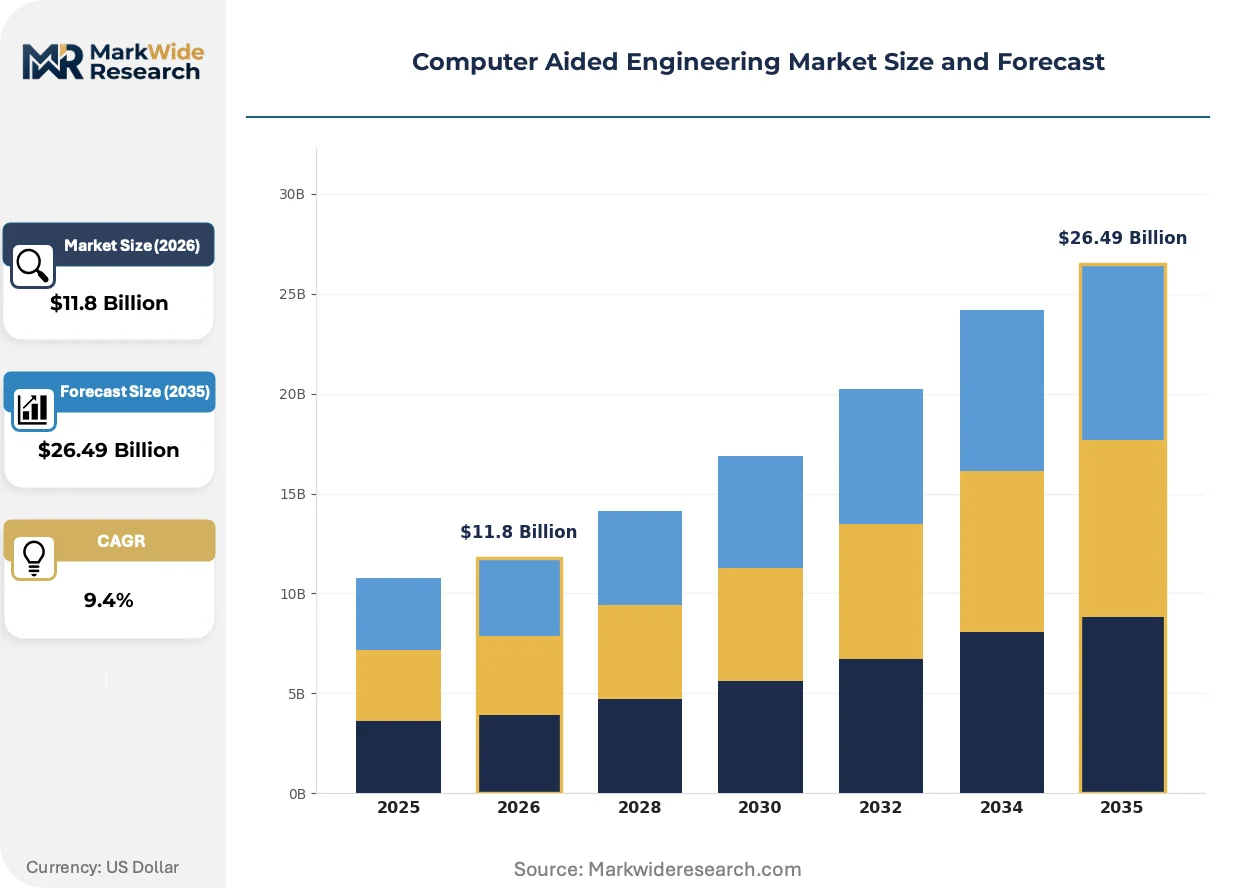
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Finite Element Analysis, Computational Fluid Dynamics, Multibody Dynamics, Optimization Tools Technology: On-Premises, Cloud-Based, Hybrid, Simulation Software End User: Aerospace, Automotive OEMs, Electronics, Construction Application: Structural Analysis, Thermal Analysis, Fluid Flow Simulation, Design Validation |
| Companies Covered | ANSYS Inc., Dassault Systèmes, Siemens Digital Industries Software, Altair Engineering Inc., Autodesk Inc., Bentley Systems Inc., ESI Group, Hexagon AB, AVEVA Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Aided Engineering Market Strategic Shifts & Innovations
Artificial intelligence and sovereign data requirements are restructuring how engineering organizations access, validate, and monetize simulation capabilities across distributed teams and regulatory jurisdictions.
Physics-informed neural networks are accelerating parametric sweeps by orders of magnitude compared with traditional finite element solvers. Automotive OEMs in Germany and Japan are deploying these surrogate models for early-stage design space exploration. The technology is rendering obsolete the trade-off between simulation fidelity and turnaround time that previously forced coarse mesh approximations.
CSRD sustainability disclosure rules now require documented lifecycle assessment for industrial machinery placed on the European market. Manufacturers must trace embodied carbon through material selection and manufacturing process simulation, embedding CAE into environmental compliance workflows. Heavy equipment producers are responding by integrating material databases with structural optimization tools to demonstrate regulatory alignment.
Engineering teams are consolidating vendor relationships around integrated platform subscriptions that bundle solver access with cloud compute credits. Discrete software procurement through departmental purchase orders is giving way to enterprise-wide agreements negotiated by central IT and procurement functions. This concentration is most pronounced in German automotive and US aerospace supply chains, where supplier tiering requirements enforce platform standardization across extended enterprise networks.
Computer Aided Engineering Market Segmentation
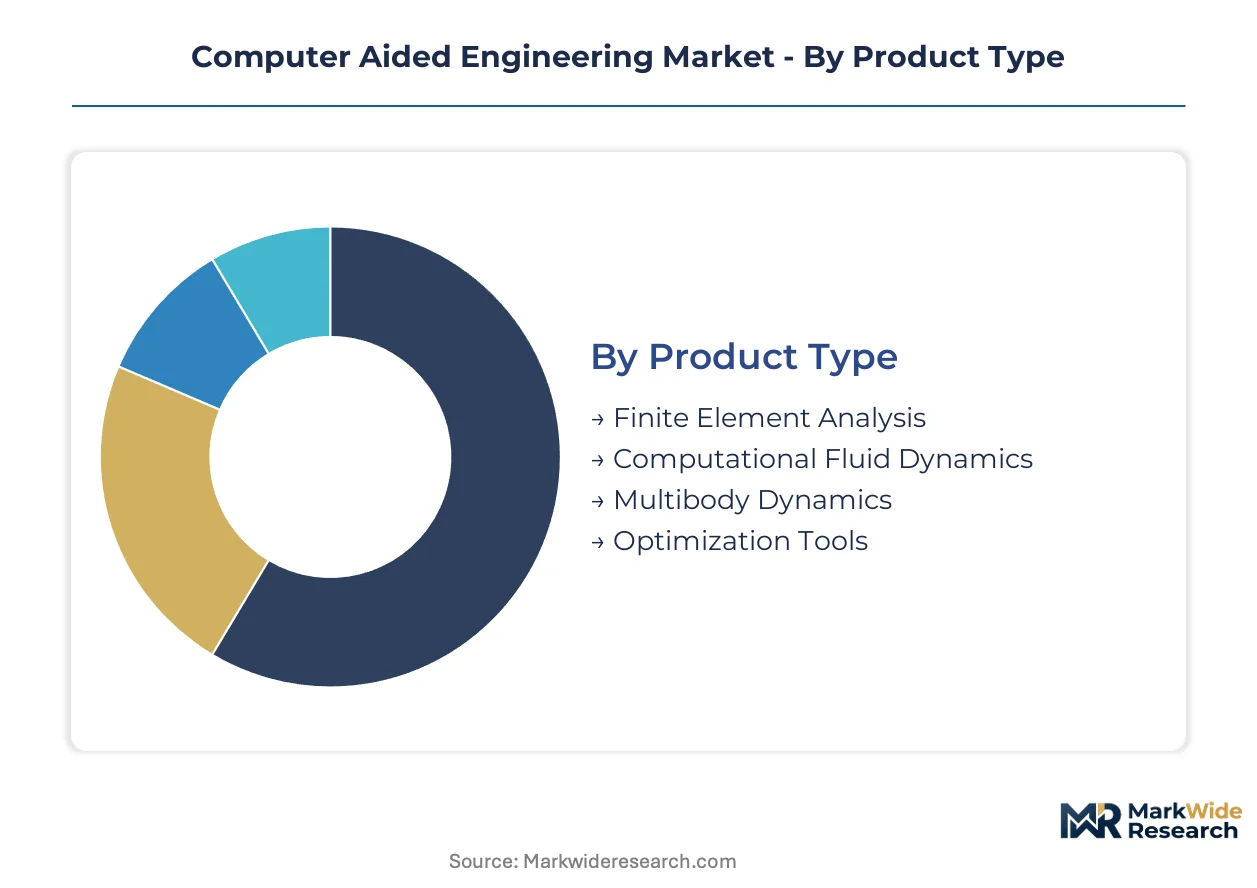
CAE market segmentation reveals how solver technologies, deployment architectures, and industry-specific validation requirements create distinct procurement patterns across engineering organizations. Understanding these dimensions exposes where platform consolidation concentrates versus where specialized point solutions retain pricing power.
Product Type:
Cost tier differentiation across solver categories reflects decades of accumulated expertise barriers and end-user workflow entrenchment.
- Finite Element Analysis:Mesh-based structural solvers dominate capital-intensive industries requiring stress, vibration, and deformation modeling under mechanical loads. Aerospace manufacturers in the US and Germany maintain the deepest installed bases, driven by FAA and EASA mandates for documented fatigue life prediction.
- Computational Fluid Dynamics:Navier-Stokes solvers simulate turbulent flow, heat transfer, and aerodynamic performance across Reynolds number regimes. Automotive OEMs concentrate procurement here for powertrain thermal management and vehicle aerodynamics optimization.
- Multibody Dynamics:Rigid and flexible body kinematics solvers for mechanism motion and load path analysis. Concentrated demand from vehicle suspension and robotics developers.
- Optimization Tools:Topology and parametric design exploration algorithms. Expanding adoption in additive manufacturing process chains.
Finite Element Analysis holds installed capacity. Optimization Tools is rotating up the share rankings.
Technology:
Deployment architecture choices determine capital intensity, IT staffing requirements, and data residency compliance exposure.
- Cloud-Based:Containerized solver access with consumption-based metering eliminates on-premises cluster procurement. German automotive suppliers and US aerospace tier-1s are migrating here fastest, constrained by EU GDPR and China MIIT data localization requirements that fragment global engineering data architectures.
- On-Premises:Dedicated HPC clusters with perpetual licensing remain entrenched where IT security policies or sovereign cloud mandates prohibit external data transfer. Defense contractors and classified program suppliers maintain this posture.
- Hybrid:Mixed deployment with sensitive preprocessing on-premises and burst compute in cloud. Emerging standard for multinational engineering teams.
- Simulation Software:Standalone solver licenses without bundled compute infrastructure. Mid-tier consultancies prefer this for client-specific hardware flexibility.
On-Premises retains legacy footprint. Cloud-Based is climbing the fastest among new procurement decisions.
End User:
Customer type segmentation maps regulatory compliance intensity and product liability exposure against simulation maturity.
- Automotive OEMs:Full-vehicle crashworthiness, NVH, and battery thermal runaway simulation dominate R&D spending. Electrification is forcing solver stack consolidation as platforms multiply variants.
- Aerospace:Airframe structural integrity and propulsion system certification under FAA and EASA simulation-based pathways. Correlation studies against physical test data extend qualification timelines.
- Electronics:PCB thermal cycling, signal integrity, and semiconductor packaging stress analysis. Shorter product lifecycles compress simulation turnaround requirements.
- Construction:Structural steel and concrete performance under seismic and wind loads. Building information modeling integration is elevating CAE from specialized consultant tool to standard design workflow.
Automotive OEMs anchor current procurement volume. Electronics is gaining share fastest as thermal constraints intensify.
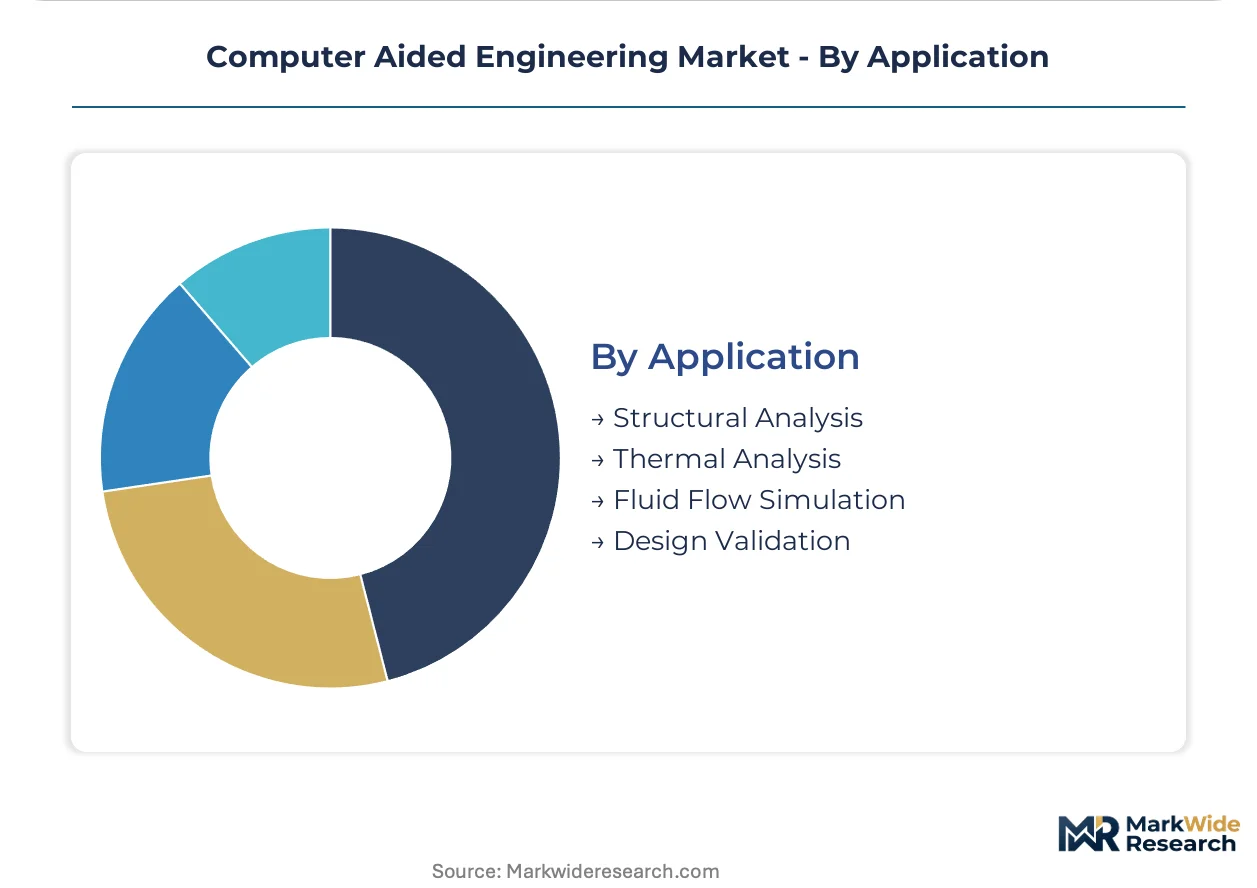
Application:
Functional use case segmentation tracks how simulation penetrates sequential product development phases from concept through certification.
- Structural Analysis:Stress, strain, and deformation prediction under static and dynamic mechanical loading. Universal requirement across heavy machinery, automotive, and aerospace supply chains.
- Thermal Analysis:Steady-state and transient heat transfer modeling. Battery pack developers and power electronics manufacturers drive specialized solver procurement here.
- Fluid Flow Simulation:Internal and external aerodynamics, HVAC performance, and process equipment design. HVAC manufacturers and turbomachinery producers concentrate demand.
- Design Validation:Correlation of simulation predictions against physical prototype testing for regulatory submission. Medical device and aerospace certification workflows require documented validation protocols.
Structural Analysis maintains broadest penetration. Thermal Analysis is rotating up the share rankings with electrification priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-tier engineering consultancies in India and Southeast Asia exhibit acute price sensitivity to simulation software procurement, whereas German automotive OEMs and US aerospace contractors absorb premium licensing costs without volume elasticity due to regulatory compliance mandates.
Germany
KBA certification requirements for vehicle structural validation and EU Machinery Directive stress-testing documentation compel industrial equipment manufacturers to maintain perpetual CAE licenses. Stuttgart and Munich anchor dense automotive supplier networks where simulation-driven design cycles compress product development timelines.
United States
FAA simulation-based certification pathways for airframe structural integrity expand demand for validated analysis tools among commercial aviation manufacturers. Seattle and Wichita aerospace clusters sustain concentrated procurement of finite element analysis suites for fatigue life prediction workflows.
China
MIIT cloud localization requirements and GB standards harmonization reshape vendor market access conditions for multinational software providers. Shanghai and Shenzhen electronics manufacturers drive thermal analysis solver procurement for semiconductor packaging stress evaluation.
India
PLI scheme incentives for manufacturing and BIS standards harmonization create entry points for CAE vendors establishing domestic cloud infrastructure partnerships. Pune and Bengaluru engineering services hubs migrate toward pay-per-use simulation models to reduce capital expenditure.
Japan
METI industrial digitalization initiatives promote indigenous solver development while automotive electrification accelerates multibody dynamics workloads for electric vehicle platform engineering. Toyota City and Nagoya manufacturing belts concentrate battery thermal management simulation demand.
Computer Aided Engineering Market Key Industry Players
Capability concentration sits with specialized solver developers possessing decades of accumulated mesh generation expertise; scale advantage sits with diversified industrial software conglomerates leveraging hardware-software integration for long-term enterprise contracts. The vendor base stratifies across three tiers: integrated platform providers, vertical specialists, and cloud-native challengers. Dominant competitive moves include restructuring licensing models around consumption-based metering and pursuing strategic partnerships with hyperscale cloud providers to secure sovereign data residency compliance.
Within the integrated platform tier, ANSYS Inc. and Siemens Digital Industries Software exemplify archetypes pursuing enterprise-wide subscription consolidation. Dassault Systèmes occupies a position representing vertical industry specialization strategies. These three anchors demonstrate how incumbent vendors defend installed bases against cloud-native challengers through bundling solver access with compute credits and compliance documentation services.
| Leading Market Players |
|---|
| ANSYS Inc. |
| Dassault Systèmes |
| Siemens Digital Industries Software |
| Altair Engineering Inc. |
| Autodesk Inc. |
| Bentley Systems Inc. |
| ESI Group |
| Hexagon AB |
| AVEVA Group plc |
| Others |
Cost & Logistics Intelligence
Overcapacity in cloud compute infrastructure across Germany and the United States is compressing solver access margins while simultaneously accelerating vendor migration toward consumption-based metering models. This utilization dynamic forces CAE providers to bundle compute credits with software licenses, reshaping how engineering teams procure simulation capacity.
Pricing Analysis
Aftermarket service revenue from extended support contracts and training subscriptions now drives lifetime value for CAE vendors pursuing recurring income streams. Three-tier pricing structure across premium, standard, and economy levels segments buyers by validation rigor, with aerospace OEMs absorbing premium costs for FAA-correlated solvers while mid-tier consultancies gravitate toward pay-per-use cloud models. Pricing pressure stems from open-source alternatives and GPU-accelerated competitors entering mesh generation workflows. Electronics manufacturers exhibit highest price sensitivity due to compressed product lifecycles, whereas German automotive OEMs demonstrate inelastic demand driven by KBA certification mandates.
Supply Chain Analysis
Upstream feedstock for CAE software development concentrates specialized engineering talent pools in Germany, the United States, and India. Proprietary mesh generation algorithms and multiphysics solver cores draw from decades of accumulated academic research, GPU semiconductor supply from Taiwan and South Korea, and hyperscale cloud infrastructure from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability around NVIDIA GPU architectures for accelerated computing creates concentration risk for vendors dependent on CUDA-optimized workflows. Distribution runs through direct enterprise sales teams for perpetual licenses and hyperscaler marketplaces for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computer Aided Engineering sits in an early-cycle expansion phase as physics-informed neural networks displace traditional finite element workflows for preliminary design exploration. Regulatory mandates from FAA, EASA, and EU Machinery Directive are embedding simulation into compulsory certification pathways, extending addressable market penetration beyond voluntary R&D adoption.
For Market Incumbents: Pre-empt cloud-native challengers by restructuring perpetual license portfolios into consumption-metered platform subscriptions bundled with sovereign data residency compliance. Acquire specialized multiphysics solver boutiques to close capability gaps in battery thermal runaway simulation demanded by automotive electrification programs. Anchor enterprise accounts through hardware-software integration contracts that raise switching costs. For New Entrants and Emerging Players: Mid-market engineering consultancies in India and Southeast Asia represent the most penetrable entry point for pay-per-use simulation models that bypass capital-intensive on-premises procurement barriers. Cloud-native GPU-accelerated solvers for electronics thermal analysis offer whitespace unguarded by entrenched FEA incumbents. Pursue hyperscaler marketplace distribution to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-deployed simulation software as containerized architectures eliminate dedicated HPC cluster procurement. Target acquisition profiles center on specialized mesh generation boutiques with automotive OEM validation credentials and physics-informed neural network startups with demonstrated solver acceleration. Monitor FAA and EASA correlation study backlog as inflection indicator for validation-services revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundles solver access with cloud compute credits and compliance documentation for German automotive OEMs. |
| Strategic Partnership | Hyperscaler alliances secure sovereign data residency for EU GDPR and China MIIT localization mandates. |
| Acquisition of Specialist Firm | Mesh generation boutiques close multiphysics capability gaps in battery thermal management workflows. |
| Product Launch | Physics-informed neural networks accelerate parametric sweeps for early-stage design space exploration. |
| Geographic Expansion | Domestic cloud infrastructure partnerships in India capture PLI scheme manufacturing incentives. |
Research Approach
A standing panel of CAE software product managers, automotive OEM simulation directors, aerospace certification engineers, and hyperscaler cloud solution architects provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against SEC 10-K filings, FAA certification databases, EU Machinery Directive implementation guidance, and hyperscaler capex disclosures. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate vendor revenue disclosures anchored market sizing.
Scenario-bracketing framed analytical approaches across the projection horizon, modeling solver technology segmentation, deployment architecture migration patterns, end-user industry regulatory intensity, and geographic data sovereignty requirements. CAGRs derived from fitted adoption curves incorporating cloud migration velocity, electrification-driven thermal analysis demand, and AI-augmented preprocessing penetration rates. Forecast inputs included GPU compute cost decline trajectories and correlation study timeline compression for simulation-based certification pathways.
Practitioners should monitor sovereign cloud mandate expansion, open-source solver maturity, and GPU supply chain concentration for early signals of forecast revision. Material shifts in FAA or EASA validation requirements, cross-border data governance fragmentation, or breakthrough physics-informed neural network accuracy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Smart Signage Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Global E-Passport and E-Visa Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Revenue Management Software Market