
 France ICT Market | 2026-2036
France ICT Market Size, Share, and Industry Trends Forecast 2026-2036
France ICT Market Foresight
The boundary between software infrastructure and artificial intelligence is narrowing as French enterprises embed machine learning into core operational systems. Dassault Systèmes leverages its 3D experience platform to anchor industrial digital twin deployments across aerospace and automotive clients. Orange Business competes through sovereign cloud offerings that address data localization requirements. Capgemini specializes in hybrid integration services that bridge legacy systems with modern API architectures.
France ICT encompasses information and communication technology systems, software, and services enabling data processing, transmission, and storage across enterprise and public environments, typically operating through layered architectures spanning physical infrastructure, virtualization, and application interfaces. The sector serves industrial automation, financial transaction processing, and citizen service delivery. Cloud Computing dominates enterprise spending as organizations migrate from capital-intensive on-premises estates. Cybersecurity captures expanding budget allocations following France's national security directives for critical infrastructure operators. Artificial Intelligence represents the fastest-growing technology segment, though deployment remains concentrated among large enterprises with dedicated data science capabilities.
ANSM and CNIL enforce France's health data and privacy frameworks, while EU AI Act compliance obligations reshape product development cycles for domestic software vendors. The country's national cybersecurity agency, ANSSI, mandates certification standards for operators of vital importance, directly influencing procurement specifications. Stakeholders must weigh sovereign cloud requirements against interoperability costs when architecting multi-country deployments.
Market Dynamics
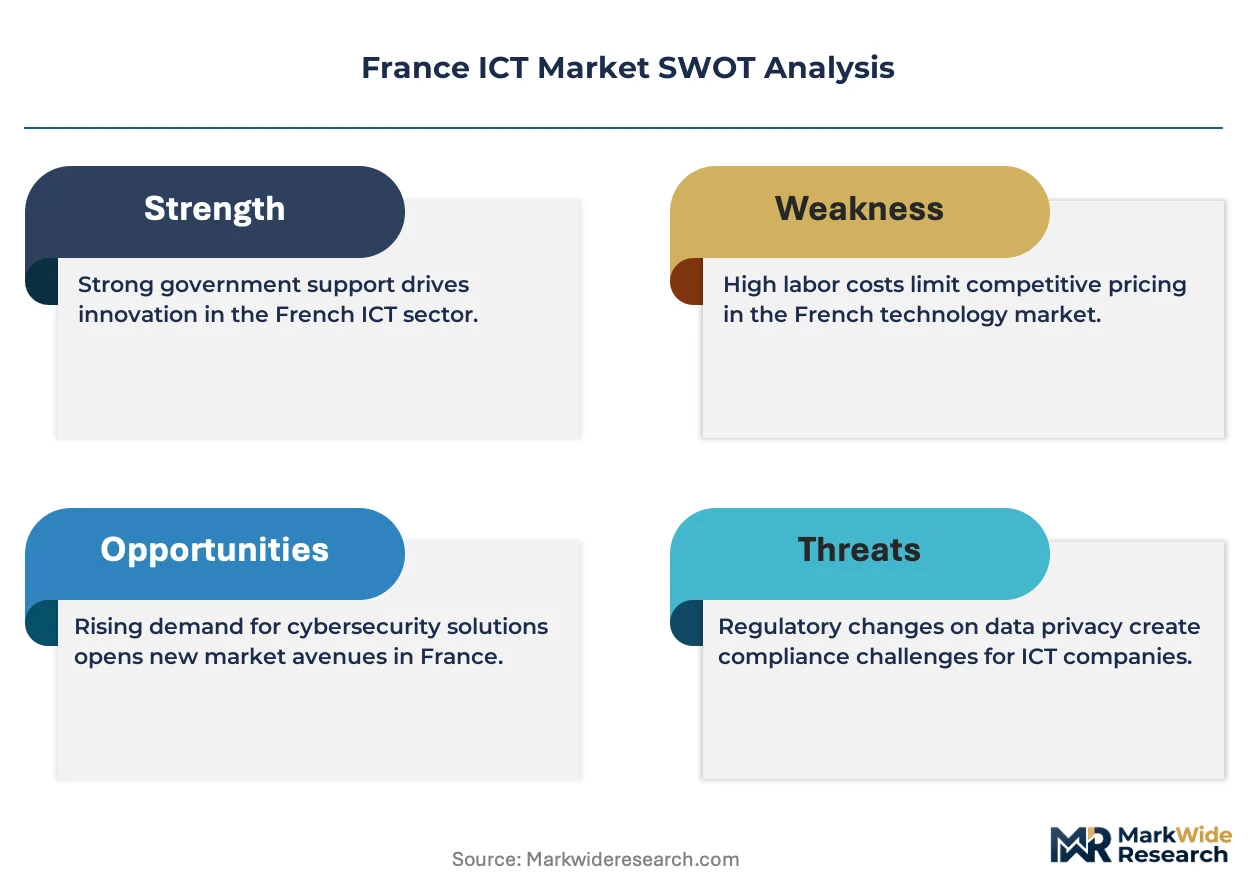
France ICT operates under sovereign data imperatives where ANSSI certification requirements and EU AI Act compliance obligations compress procurement cycles while elevating security architecture to board-level priority.
Growth Catalysts
- France 2030 Investment Plan:Public sector cloud migration mandates allocate substantial capital toward modernizing citizen service delivery platforms and inter-agency data interoperability frameworks.
- EU AI Act:Compliance-driven procurement creates structured demand pathways for domestic vendors offering auditable machine learning pipelines and explainable algorithmic systems.
- Paris-Saclay Technology Cluster:Concentrated research-industry collaboration accelerates commercialization of quantum computing and advanced semiconductor applications.
Market Restraints
- Semiconductor Input Volatility:Memory and processor component costs fluctuate with Asian foundry capacity constraints, compressing hardware margin structures for French systems integrators.
- Sovereign Cloud Fragmentation:Data localization requirements fragment vendor ecosystems, forcing redundant infrastructure investments that duplicate functionality across national boundaries.
- Legacy System Technical Debt:COBOL and mainframe architectures in banking and insurance sectors resist API-native integration, extending modernization timelines.
Strategic Opportunities
- CNIL-Compliant Health Data Platforms:ANSM interoperability frameworks enable secure secondary use of clinical datasets for pharmaceutical research and predictive diagnostics.
- Edge-AI Convergence:Integration of on-device inference with 5G network slicing creates low-latency industrial automation deployments for manufacturing clients.
- Sophia Antipolis Cybersecurity Specialization:Underpenetrated mid-market manufacturing in Provence-Alpes-Côte d'Azur presents channel expansion potential for managed detection services.
Industry Challenges
- Certified Security Architect Scarcity:ANSSI-qualified personnel shortages delay deployment timelines for operators of vital importance in energy and transport sectors.
- Hybrid Integration Complexity:API gateway deployment across SAP and Salesforce estates demands specialized DevOps capabilities that French enterprises struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France ICT Market |
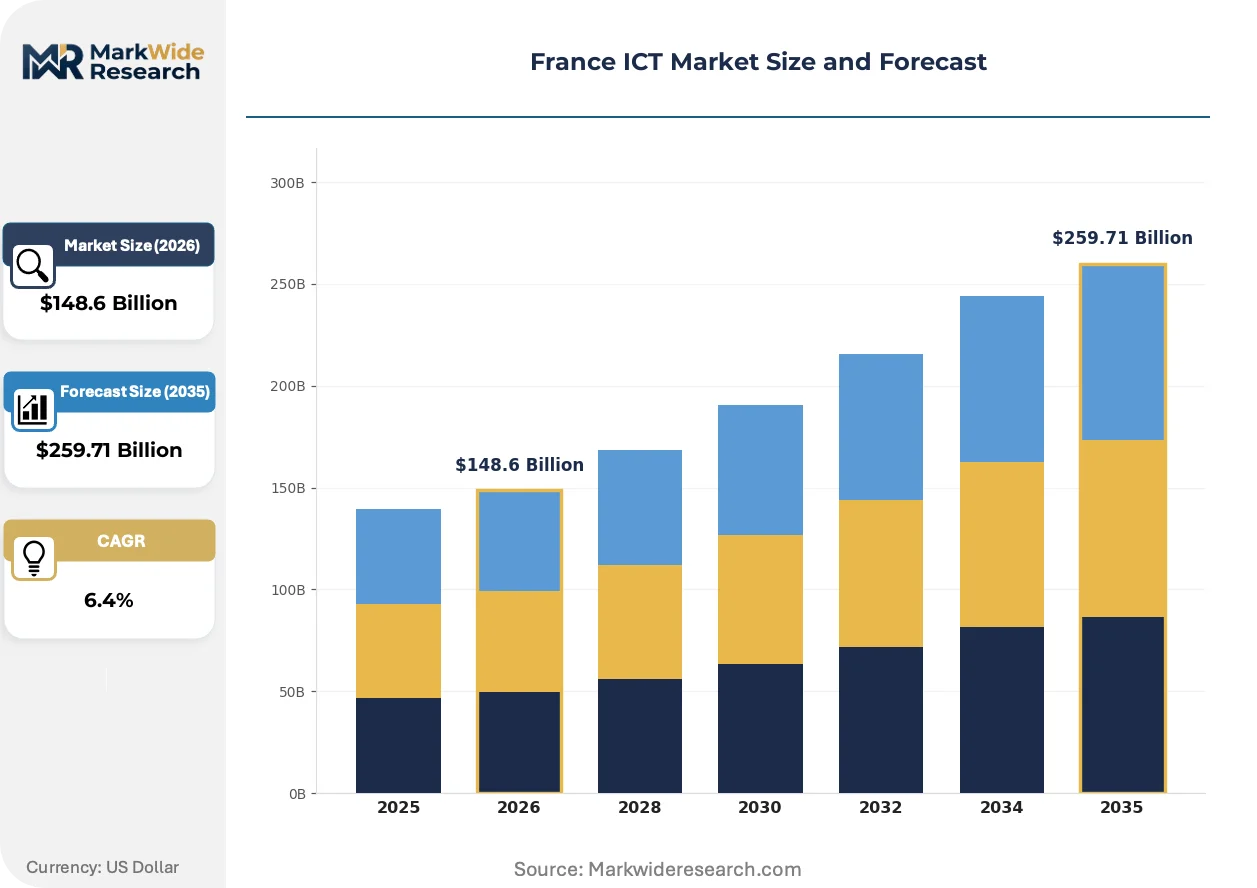
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $259.71 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Cybersecurity, Big Data Analytics, Artificial Intelligence, Blockchain, Edge Computing Application: Smart Cities, E-Government, Financial Services, Telecommunications, Manufacturing Automation, Education Technology End User: SMEs, Public Sector Agencies, Financial Institutions, Telecommunication Providers, Educational Institutions, Automotive Suppliers Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises, Community Cloud, Multi-Cloud |
| Companies Covered | Datadog, Dataiku, Dassault Systèmes, Atos, Orange Business, Capgemini, Mistral AI, Alten, Sopra Steria Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France ICT Market Shifts & Advancements
Operational technology and information technology architectures are converging as French industrial firms deploy sensor networks that feed directly into enterprise resource planning systems.
Industrial edge computing is migrating from on-premises server rooms to distributed factory-floor nodes. Automotive and aerospace manufacturers in Hauts-de-France embed GPU-accelerated inference engines directly beside production lines. Latency-sensitive quality control applications compress decision cycles from minutes to milliseconds, eliminating round-trip dependencies on centralized cloud infrastructure.
EU AI Act risk classification tiers reshape software development workflows for French vendors. High-risk systems in recruitment, credit scoring, and medical devices face conformity assessment obligations before market entry. Domestic developers restructure product roadmaps to embed technical documentation and human oversight mechanisms from design phase inception.
Subscription-based infrastructure consumption displaces perpetual licensing in enterprise software procurement. Mid-market manufacturers in Occitanie and Grand Est favor usage-metered platform access over capital-intensive on-premises deployments. Channel partners respond with managed service wrappers that bundle implementation, training, and tier-one support into predictable operational expenditures.
France ICT Market Segmentation
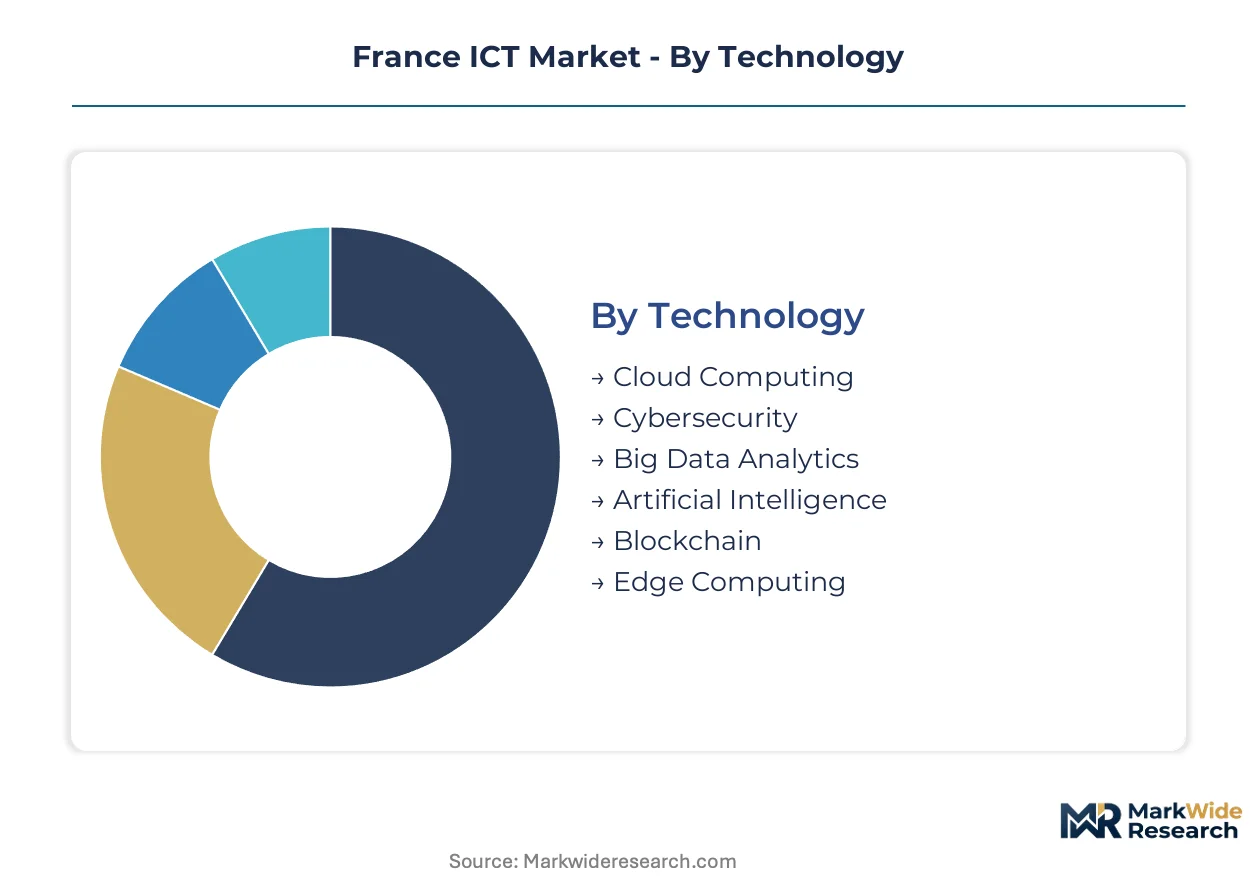
Segmentation reveals how France ICT demand fragments across sovereign cloud mandates, EU AI Act compliance tiers, and legacy modernization imperatives. Procurement patterns diverge sharply between ANSSI-certified operators of vital importance and mid-market manufacturers seeking metered platform access.
Technology:
Cost tier differentiation separates capital-intensive infrastructure from operationalized service consumption across French enterprise budgets.
- Cloud Computing:Virtualized compute, storage, and networking resources delivered through subscription models. Paris-Saclay technology cluster anchors sovereign cloud deployments for defense and aerospace clients facing ANSSI data localization mandates.
- Cybersecurity:Network security, endpoint protection, and threat detection systems. Energy and transport operators of vital importance drive demand for certified security architectures under France's national security directives, though ANSSI-qualified personnel shortages compress deployment timelines.
- Big Data Analytics:Distributed processing frameworks for structured and unstructured datasets at scale.
- Artificial Intelligence:Machine learning pipelines and explainable algorithmic systems subject to EU AI Act conformity assessments.
- Blockchain:Distributed ledger infrastructure for transactional verification and supply chain provenance.
- Edge Computing:GPU-accelerated inference engines deployed beside production lines in Hauts-de-France manufacturing facilities.
Cloud Computing commands the established base. The steepest expansion runs through Artificial Intelligence.
Application:
Application segmentation tracks where public investment mandates intersect with private sector automation imperatives across French regions.
- Smart Cities:Sensor networks, traffic management systems, and citizen-facing digital services. Bordeaux and Lyon metropolitan authorities allocate France 2030 capital toward interoperable urban data platforms.
- E-Government:Inter-agency data exchange frameworks and citizen service delivery portals. Public sector cloud migration mandates under France 2030 accelerate procurement of auditable systems for tax, social security, and permit processing.
- Financial Services:Real-time transaction processing and regulatory reporting infrastructure.
- Telecommunications:5G network slicing and core infrastructure for low-latency industrial applications.
- Manufacturing Automation:Industrial IoT integration with enterprise resource planning systems.
- Education Technology:Learning management systems and digital credential verification platforms.
E-Government captures sovereign investment flows. Manufacturing Automation gains share fastest as industrial edge deployments proliferate.
End User:
Customer type determines procurement complexity, with ANSSI certification requirements filtering vendor eligibility for critical infrastructure operators.
- SMEs:Mid-market manufacturers in Occitanie and Grand Est favor usage-metered platform access over capital-intensive on-premises estates, driving channel partner managed service wrappers.
- Public Sector Agencies:Central and regional government bodies subject to France 2030 cloud migration timelines and interoperability frameworks.
- Financial Institutions:Banking and insurance sectors grappling with COBOL technical debt and API-native integration demands.
- Telecommunication Providers:Network operators deploying 5G infrastructure with edge-AI convergence capabilities.
- Educational Institutions:Universities and research centers within Paris-Saclay cluster commercializing quantum computing applications.
- Automotive Suppliers:Component manufacturers embedding sensor networks into enterprise resource planning systems.
Public Sector Agencies anchor procurement volume. SMEs climb the fastest as subscription infrastructure consumption displaces perpetual licensing.
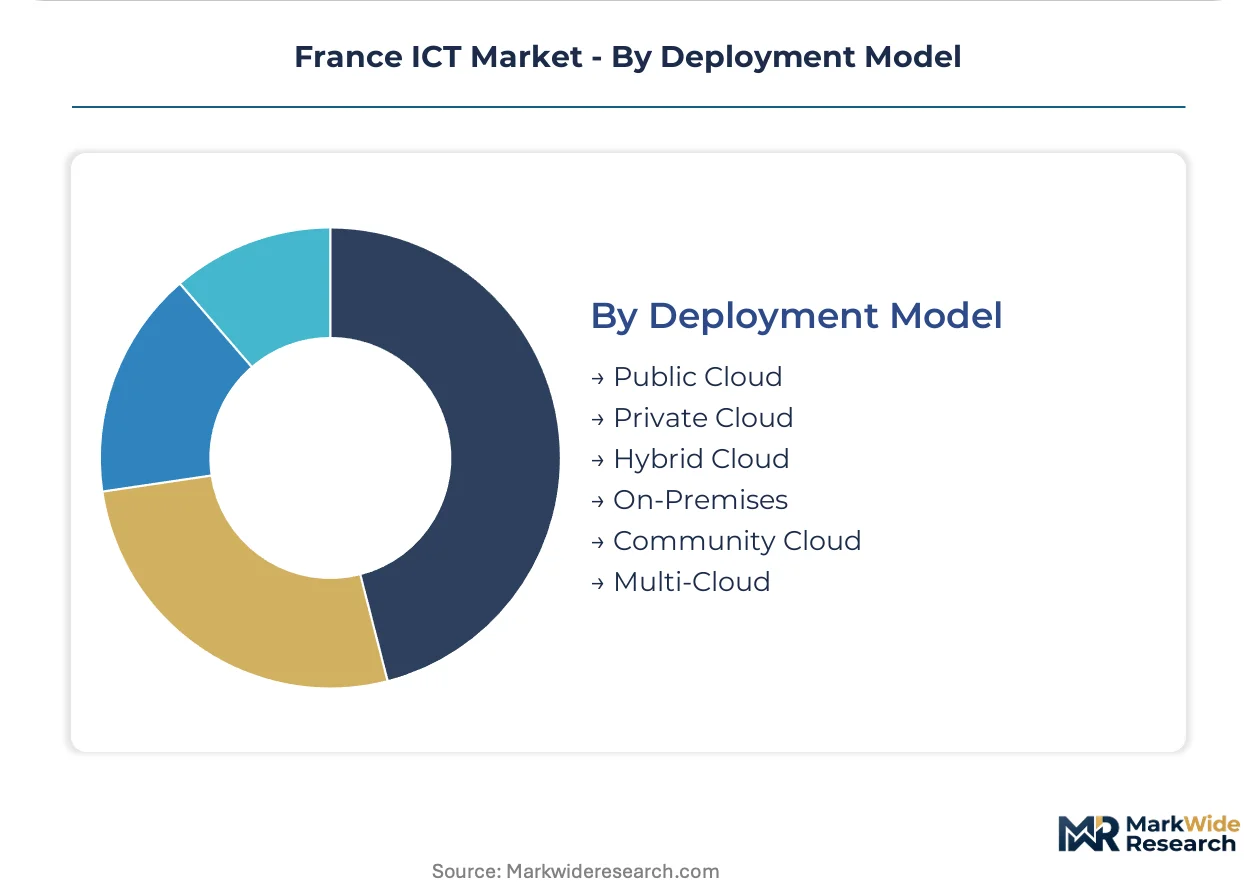
Deployment Model:
Deployment architecture reflects tension between data localization requirements and interoperability costs in multi-country enterprise configurations.
- Public Cloud:Shared infrastructure operated by hyperscale providers. Sovereign cloud fragmentation forces redundant investments as data localization requirements duplicate functionality across national boundaries.
- Private Cloud:Single-tenant environments dedicated to individual organizations. Orange Business and domestic vendors compete through sovereign offerings addressing CNIL compliance and ANSSI certification specifications.
- Hybrid Cloud:Integrated public-private architectures bridging legacy systems with modern API frameworks.
- On-Premises:Capital-intensive owned infrastructure resisting migration in banking and insurance mainframe estates.
- Community Cloud:Shared infrastructure for specific industry verticals or regulatory jurisdictions.
- Multi-Cloud:Distributed workloads across heterogeneous provider environments to mitigate vendor concentration risk.
Hybrid Cloud dominates enterprise architecture decisions. Multi-Cloud expands most quickly as organizations distribute workloads to satisfy competing sovereign requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public sector agencies and defense contractors concentrate procurement authority in Île-de-France, while industrial automation demand radiates toward peripheral manufacturing basins. Regional specialization patterns reflect France 2030 investment allocations and ANSSI certification requirements.
Île-de-France
Central government ministries and defense procurement agencies drive sovereign cloud contracts. ANSSI mandates data localization for operators of vital importance. Paris-Saclay technology cluster anchors quantum computing research commercialization and advanced semiconductor development.
Auvergne-Rhône-Alpes
Industrial software vendors serve pharmaceutical and chemical process automation. EU AI Act conformity assessments reshape medical device software development cycles. Lyon metropolitan authorities deploy smart city sensor networks using France 2030 interoperability frameworks.
Provence-Alpes-Côte d'Azur
Sophia Antipolis technology park hosts cybersecurity specialists and telecom R&D centers. ANSSI certification requirements filter vendor eligibility for regional energy infrastructure operators. Mid-market manufacturing in the corridor presents channel expansion potential for managed detection services.
Hauts-de-France
Automotive and aerospace manufacturers embed GPU-accelerated edge inference engines beside production lines. EU AI Act risk classification tiers govern quality control algorithm deployments. Lille metropolitan area attracts logistics technology providers serving cross-border Benelux commerce.
Occitanie
Mid-market manufacturers favor usage-metered platform access over capital-intensive on-premises estates. CNIL compliance frameworks shape health data platform architectures for Montpellier biomedical research clusters. Subscription infrastructure consumption displaces perpetual licensing among regional SMEs.
France ICT Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages concentrate in systems integration and sovereign cloud delivery. The vendor base separates into three strategic archetypes: platform-native specialists with embedded AI capabilities, legacy systems integrators bridging mainframe estates, and infrastructure operators with data localization certifications. Dominant competitive moves include vertical capability acquisitions and strategic partnerships with hyperscale providers.
Within the platform-native tier, Dassault Systèmes and Dataiku exemplify archetypes anchored in industrial digital twin deployments and machine learning pipeline commercialization respectively. Orange Business occupies a position representing sovereign cloud infrastructure operators addressing ANSSI localization mandates. These three entities sit within distinct competitive vectors—industrial software, AI/ML platforms, and certified infrastructure—rather than direct substitution relationships.
| Leading Market Players |
|---|
| Datadog |
| Dataiku |
| Dassault Systèmes |
| Atos |
| Orange Business |
| Capgemini |
| Mistral AI |
| Alten |
| Sopra Steria Group |
| Others |
Supply & Pricing Matrix
Rotterdam-Paris freight corridor cost volatility shapes margin structures for French systems integrators sourcing GPU accelerators and memory modules from Asian foundries, compressing hardware margins while amplifying price differentiation between ANSSI-certified sovereign offerings and standard commercial deployments.
Pricing Analysis
Cost-plus contracts with quarterly indexation to DRAM and NAND spot markets dominate procurement between French integrators and semiconductor distributors. Pricing stratifies across premium, standard, and economy tiers based on ANSSI certification grade and after-sales service bundling. Cost compression in mid-market hardware tiers is intensifying because memory component shortages from Taiwanese foundries are squeezing margin structures. SMEs in Occitanie and Grand Est exhibit highest price sensitivity, while defense contractors in Île-de-France accept premium positioning for data localization guarantees.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for French ICT hardware procurement. Component sourcing concentrates in Taiwan, South Korea, and China for advanced semiconductors, memory modules, and GPU accelerators. Supply chains draw from specialized foundries for 7nm and 5nm process nodes, high-bandwidth memory stacks, and silicon photonics interconnects. Single-source vulnerability around TSMC's leading-edge capacity creates concentration risk for AI training hardware. Distribution runs through authorized distributors serving systems integrators and direct hyperscale procurement channels for enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France ICT sits in early-cycle expansion as EU AI Act compliance deadlines force enterprise procurement of auditable machine learning infrastructure ahead of enforcement timelines.
For Market Incumbents: Entrench sovereign cloud positioning through accelerated ANSSI certification investments for edge-AI hardware portfolios. Deepen channel control over mid-market manufacturers in peripheral regions by acquiring regional managed service providers. Threat substitution from Mistral AI and other domestic foundation model developers demands defensive API integration partnerships to preserve platform stickiness.
For New Entrants and Emerging Players: Mid-market manufacturing in Hauts-de-France and Provence-Alpes-Côte d'Azur represents the most penetrable entry point for edge inference solutions. CNIL-compliant health data platforms for Montpellier biomedical clusters offer second white-space anchor. Go-to-market execution should route through channel partners already holding ANSSI-certified security architect relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial software divisions lacking AI-native capabilities. Long-term viability centers on vertical integration into sovereign cloud infrastructure and proprietary model training capacity. Signal to watch: ANSSI certification backlog clearance rates as inflection indicator for deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | ANSSI qualification unlocks procurement eligibility for operators of vital importance in energy and transport. |
| Edge-AI Hardware Integration | GPU-accelerated inference engines beside production lines in Hauts-de-France manufacturing capture latency-sensitive automation demand. |
| EU AI Act Compliance Platform | Technical documentation and human oversight mechanisms embedded from design phase accelerate conformity assessment pathways. |
| Hybrid Integration Services | API gateway deployment across SAP and Salesforce estates bridges legacy technical debt with modern architectures. |
| Channel Partner Acquisition | Regional managed service providers in Occitanie and Grand Est extend reach to subscription-preferring SME manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANSSI certification registries, EU AI Act implementation guidance, and hyperscaler capex disclosures. Interviews with CTOs at aerospace manufacturers, IT procurement officers in regional health clusters, platform engineers at sovereign cloud operators, and channel partners serving mid-market industrial clients informed demand segmentation. Secondary validation drew from CNIL enforcement actions, France 2030 investment allocation documents, and semiconductor trade flow data. Bottom-up deployment sizing and top-down macroeconomic alignment ensure cross-verified outputs.
Forecast inputs include technology adoption curves across cloud, cybersecurity, and AI segments; regional procurement authority concentration; and compliance-driven replacement cycles. Modeling spans deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derive from penetration rate trajectories anchored to France 2030 milestone timelines and EU regulatory enforcement schedules. Specific inputs capture ANSSI certification pipeline velocity and edge-AI manufacturing deployment rates.
Macroeconomic conditions sit as an overlay; deviation in eurozone interest rate trajectories and Asian foundry capacity expansion would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and sovereign cloud procurement mandates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Molecular Information Systems Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Service Mesh Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Service Fulfillment Market