
 European Digital Transaction Management Software Market | 2026-2036
European Digital Transaction Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
European Digital Transaction Management Software Market Insights
API-first architecture is rewriting how digital transaction platforms embed into enterprise workflows. DocuSign Inc. leverages extensive partner integrations to anchor its position across European financial services. Adobe Inc. sustains competitive density through document cloud specialization and creative-to-contract workflow continuity. Namirial SpA dominates qualified trust service provision under eIDAS, particularly within Italian and DACH public-sector procurement channels.
European Digital Transaction Management Software encompasses electronic signatures, document management, workflow automation, and compliance tracking delivered through cloud, on-premises, hybrid, or mobile architectures with cryptographic integrity and audit-trail immutability. The technology stack orchestrates end-to-end transaction execution from identity verification through archival retrieval, primarily serving healthcare, financial services, retail, and government sectors where regulatory attestation and non-repudiation carry legal weight. Electronic signatures command the largest revenue pool as baseline eIDAS compliance becomes table stakes for cross-border commerce, while workflow automation represents the fastest-expanding segment as enterprises seek to collapse approval cycles in procurement and HR onboarding. Cloud-based deployment absorbs disproportionate new investment relative to legacy on-premises installations, though hybrid configurations persist in German automotive and French defense supply chains where data residency requirements fragment infrastructure decisions.
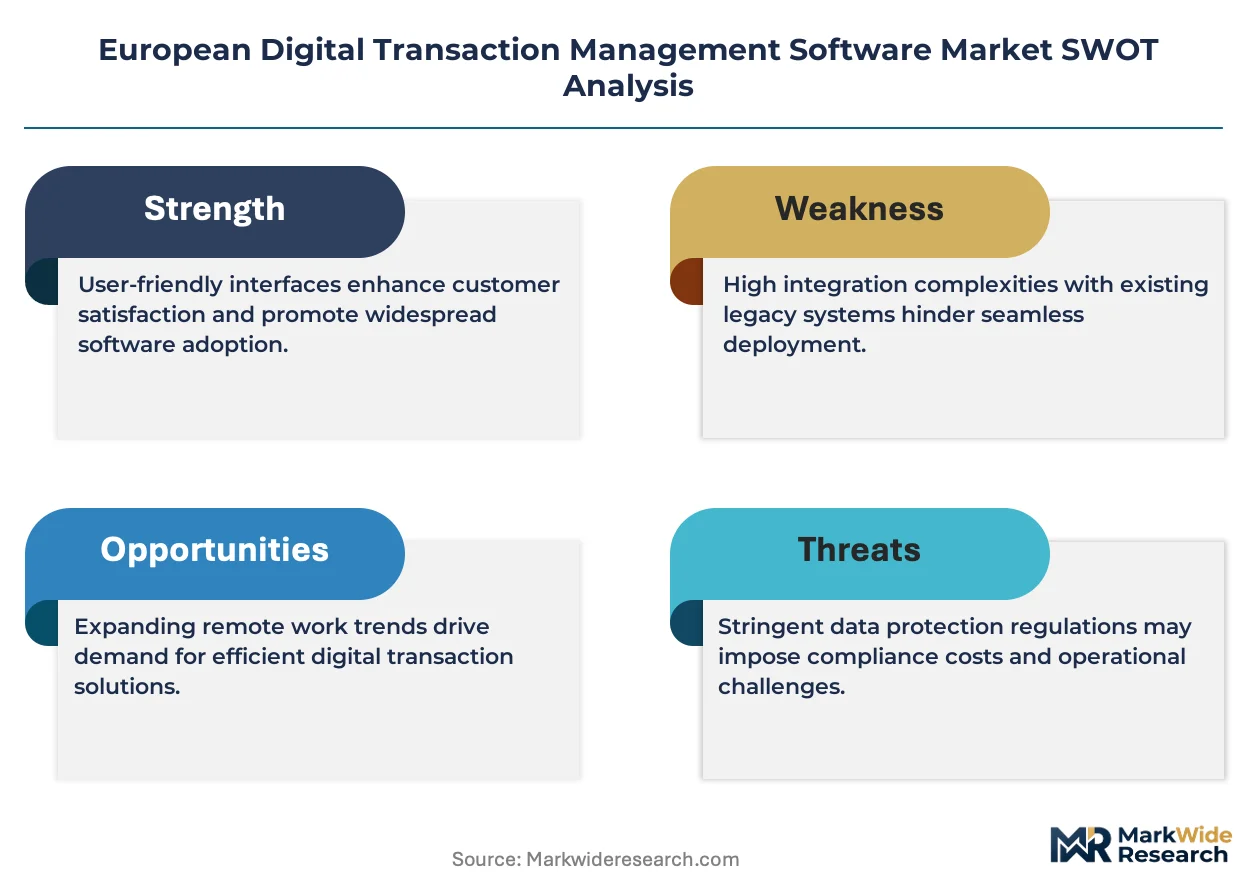
eIDAS 2.0, GDPR, and the EU AI Act collectively shape product roadmaps by mandating qualified electronic signatures, governing biometric data processing in identity verification, and requiring algorithmic transparency in automated contract-review tools. The European Banking Authority and national competent authorities layer sector-specific guidance onto payment-service and insurance-distribution workflows, tightening audit standards for digital origination. Vendors must monitor how the EU Green Deal's paperless-transaction mandates intersect with emerging CSRD disclosure requirements, as enterprise buyers increasingly bundle sustainability reporting into procurement criteria for software contracts.
Market Dynamics
Cloud-native e-signature platforms are compressing deployment cycles across European banking infrastructure, forcing incumbent vendors to rearchitect legacy stacks around API-first interoperability or cede procurement contracts to agile competitors.
Growth Catalysts
- eIDAS 2.0 qualified signature mandates:The updated framework compels cross-border transaction providers to embed enhanced identity verification, expanding addressable market for trust-service vendors in German and Italian public procurement.
- Mittelstand digitization wave:Mid-tier German manufacturers are replacing paper-based supply-chain contracting with automated workflow platforms to compress procurement approval cycles and reduce administrative overhead.
- Biometric identity verification:Facial recognition and liveness detection technologies are hardening non-repudiation guarantees for high-value financial transactions, particularly in loan origination workflows.
Market Restraints
- Data residency fragmentation:French defense and German automotive supply chains mandate on-premise or sovereign-cloud deployment, inflating infrastructure costs and complicating vendor scale economics.
- GDPR biometric processing constraints:Strict consent requirements and purpose limitation rules throttle deployment velocity for AI-powered identity verification tools in healthcare and financial services.
- Legacy system integration debt:Core banking platforms running decades-old COBOL architectures resist API connectivity, forcing expensive middleware layers that erode cloud-native cost advantages.
Strategic Opportunities
- CSRD-aligned paperless mandates:The EU Green Deal's sustainability disclosure requirements are bundling digital transaction adoption into enterprise ESG procurement criteria, creating regulatory tailwind for cloud-based document platforms.
- Healthcare interoperability gaps:Underpenetrated hospital networks in Spain and Portugal lack integrated e-signature and clinical workflow systems, presenting whitespace for specialized health-tech vendors.
- AI-Act automated contract review:Algorithmic transparency requirements for high-risk AI applications are converging with contract analytics tools, opening new product categories for explainable clause-extraction engines.
Industry Challenges
- Qualified trust-service provider certification timelines:eIDAS accreditation processes stretch 18-24 months, delaying market entry for new entrants and freezing competitive dynamics in national procurement channels.
- Cross-border cryptographic standard harmonization:Divergent national implementations of advanced electronic signature formats create interoperability failures that fragment pan-European transaction flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Digital Transaction Management Software Market |
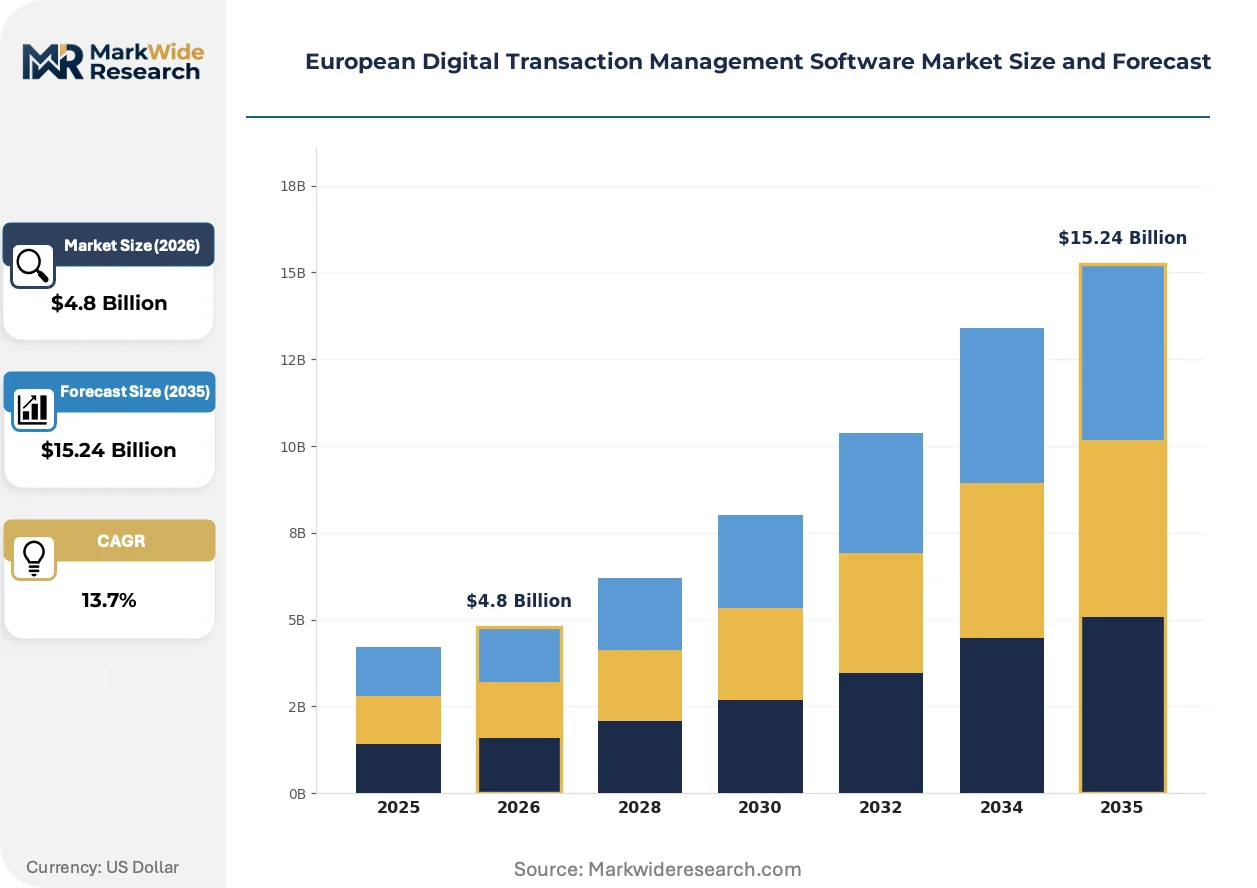
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Signatures, Document Management, Workflow Automation, Compliance Tracking End User: Healthcare, Financial Services, Retail, Government Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | DocuSign Inc., Adobe Inc., Namirial SpA, Nintex Group Pty Ltd, Kofax Inc., OneSpan, Entrust Datacard Corporation, PandaDoc, eOriginal Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Digital Transaction Management Software Market Trends and Innovations
API-first architecture is dissolving the boundary between transaction management and core enterprise software, embedding signature and workflow capabilities directly into ERP, CRM, and procurement systems rather than operating as standalone applications.
Serverless signing infrastructure is rendering obsolete the traditional three-tier deployment model of on-premise hardware, dedicated middleware, and client-side applications. Nordic banks and Dutch insurance distributors are migrating transaction volumes to function-as-a-service architectures within eighteen-month windows. This compression is eliminating capital-intensive data center commitments and reducing time-to-production for new workflow configurations from quarters to weeks.
The EU AI Act's risk-classification framework for automated decision-making is forcing algorithmic auditability into contract lifecycle management tools. Vendors must now document training data provenance and model drift for clause-extraction engines deployed in financial services and public-sector procurement. German and French legal-tech providers are responding by modularizing AI components into separately certifiable subsystems that can be isolated or substituted without platform-wide recertification.
Subscription fatigue among enterprise buyers is fragmenting procurement authority away from centralized IT departments toward line-of-business owners with departmental budget autonomy. Chief procurement officers in Benelux manufacturing and Iberian retail are unbundling enterprise-wide digital transaction contracts into smaller, function-specific purchases evaluated on monthly recurring cost per user rather than total contract value. This behavioral shift rewards vendors with granular pricing transparency and rapid self-service onboarding over those relying on complex enterprise sales cycles.
European Digital Transaction Management Software Market Segmentation
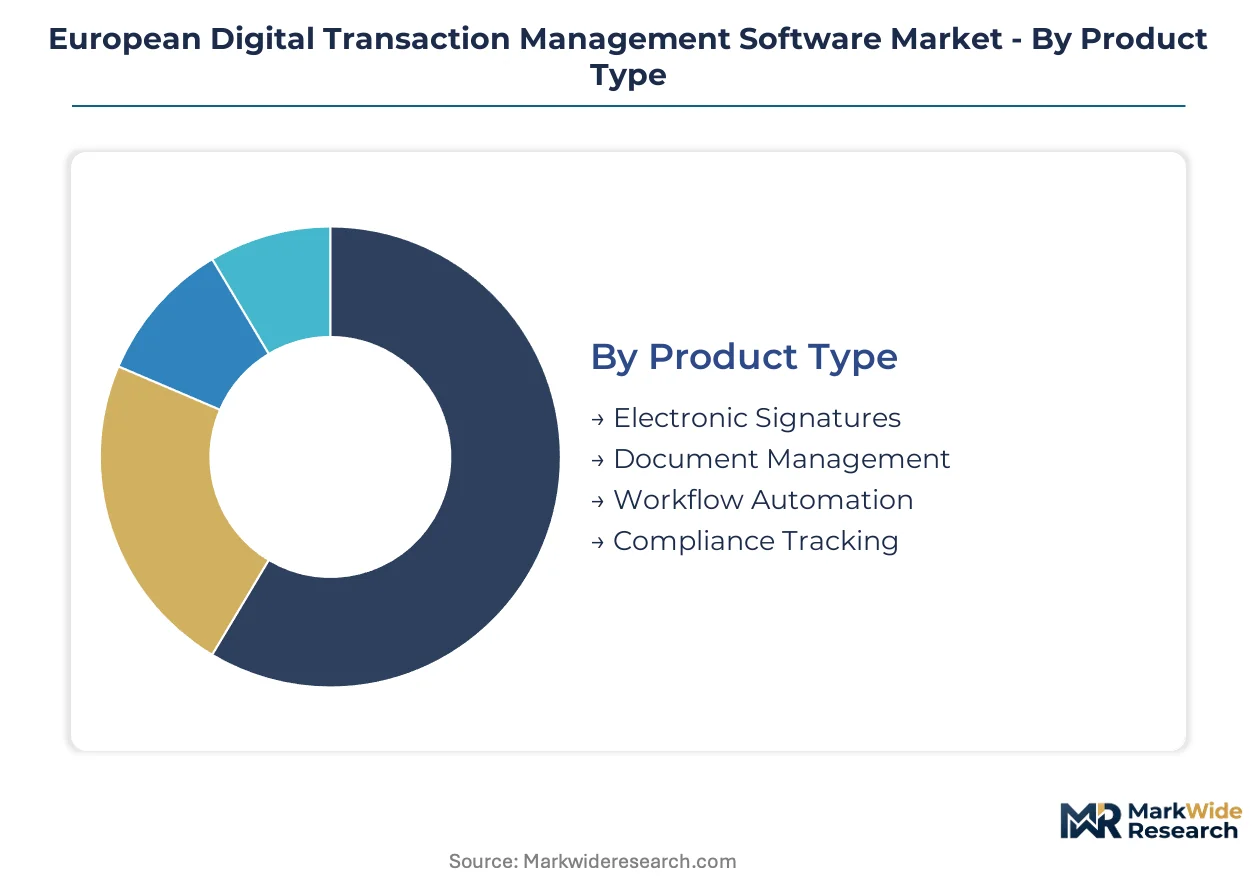
Segmentation reveals how regulatory pressure and infrastructure legacy fragment procurement patterns across European enterprises. Cycle times vary dramatically by deployment model and service intensity, with cloud-native implementations compressing from quarters to weeks while qualified trust-service certifications stretch eighteen to twenty-four months.
Product Type:
Electronic signatures turn over fastest as baseline eIDAS compliance becomes procurement table stakes, while compliance tracking cycles slow where national accreditation gates apply.
- Electronic Signatures:Cryptographic integrity mechanisms with audit-trail immutability anchor cross-border commerce. German Mittelstand manufacturers and Italian public-sector channels drive concentration as qualified signature mandates harden legal enforceability.
- Workflow Automation:Approval-cycle compression engines integrate with ERP and procurement systems. Benelux manufacturing and Iberian retail buyers prioritize this segment to collapse administrative overhead in supply-chain contracting.
- Document Management:Centralized repositories with version control and retrieval capabilities serve healthcare networks in Spain and Portugal where clinical workflow integration remains underpenetrated.
- Compliance Tracking:Audit-trail generation and regulatory attestation modules face extended sales cycles due to eIDAS accreditation requirements and national implementation divergence.
Electronic signatures anchors the volume base while workflow automation gains share at the steepest rate.
End User:
Cost tiers stratify sharply, with financial services absorbing premium pricing for biometric identity verification while retail squeezes vendors on per-seat economics.
- Financial Services:Loan origination and customer onboarding workflows demand qualified electronic signatures with liveness detection. GDPR biometric processing constraints and EU AI Act algorithmic transparency requirements throttle deployment velocity in German and French banking channels.
- Healthcare:Clinical documentation and patient consent management require HIPAA-equivalent data protection with interoperability across hospital networks. Spanish and Portuguese facilities present whitespace where integrated e-signature systems remain scarce.
- Government:Public procurement mandates under eIDAS 2.0 compel qualified trust-service provision, concentrating demand in Italian and DACH national channels where Namirial SpA dominates accreditation.
- Retail:High-volume, low-margin transaction processing prioritizes API-first cloud deployment with granular per-user pricing, fragmenting procurement authority toward departmental buyers.
Financial services commands the premium tier while healthcare presents the largest untapped expansion corridor.
Deployment:
Volume concentrates in cloud-native architectures, though margin pools fragment where data residency mandates force hybrid or sovereign configurations.
- Cloud-Based:Function-as-a-service architectures eliminate capital-intensive data center commitments. Nordic banks and Dutch insurance distributors complete migrations within eighteen-month windows, compressing time-to-production for workflow reconfiguration.
- Hybrid:Split infrastructure accommodates data residency requirements without full on-premise burden. German automotive supply chains deploy this model to satisfy fragmented national regulations while preserving cloud economics.
- On-Premises:Dedicated hardware installations persist in French defense supply chains where sovereign-cloud mandates override cost optimization.
- Mobile:Native application deployment supports field-based signature capture in logistics and construction workflows where desktop access proves impractical.
Cloud-based deployment absorbs disproportionate new investment while hybrid configurations defend margin in regulated verticals.
Service Type:
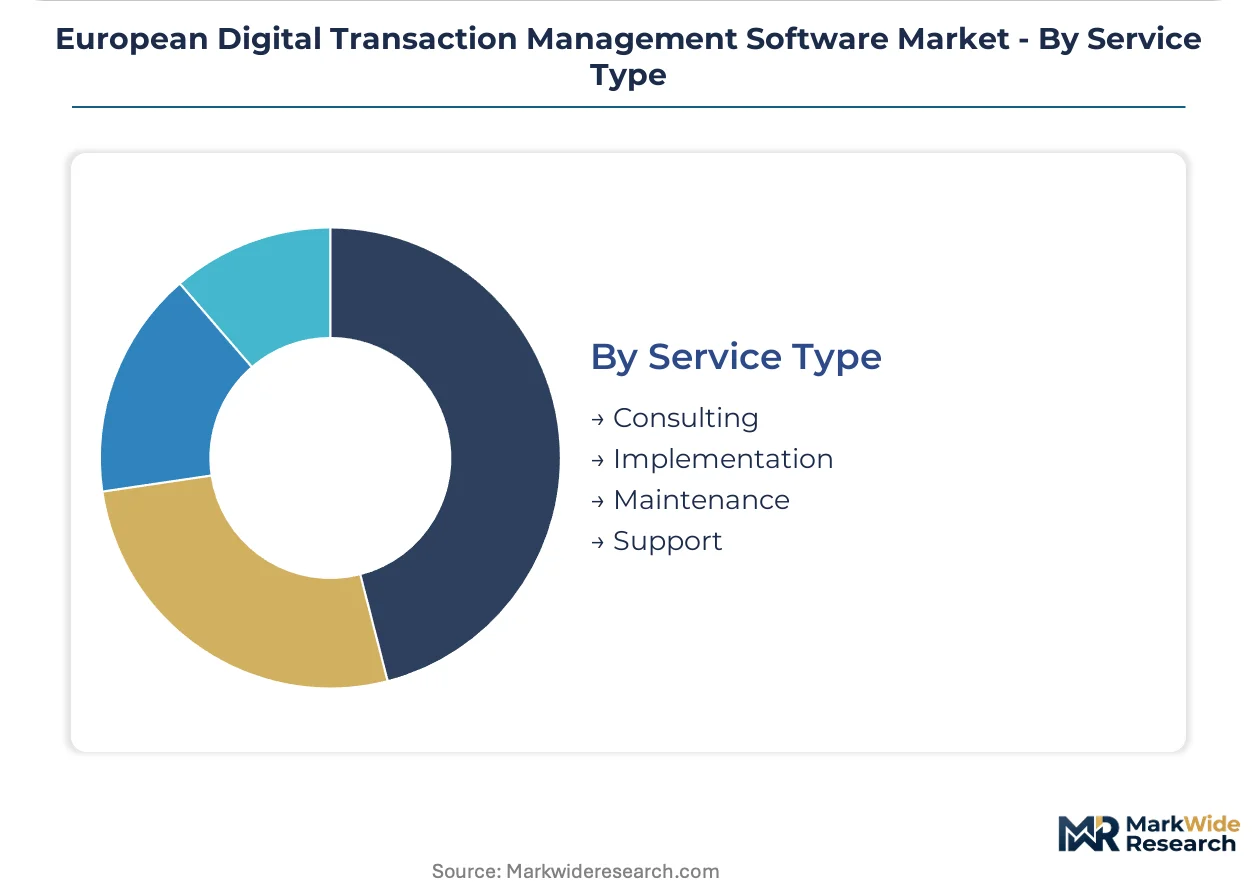
Customer maturity determines service mix, with early-stage buyers demanding implementation intensity and established accounts shifting toward maintenance optimization.
- Implementation:System integration and workflow configuration services face elongated cycles where legacy COBOL banking platforms resist API connectivity, forcing expensive middleware layers.
- Consulting:Regulatory navigation and change-management advisory concentrate in eIDAS 2.0 transition periods and EU AI Act compliance preparation.
- Support:Technical assistance and troubleshooting contracts stabilize as cloud-native platforms mature and self-service capabilities expand.
- Maintenance:Update management and security patching services generate recurring revenue streams with lower delivery cost intensity than implementation.
Implementation services dominate early customer relationships while maintenance contracts expand fastest among mature installed bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports digital transaction management solutions to Austrian and Swiss banking networks, establishing a cross-border corridor for qualified electronic signature infrastructure. This trade pattern concentrates vendor investment in German-speaking compliance frameworks. National procurement channels diverge sharply under eIDAS 2.0 implementation timelines.
Germany
Mittelstand manufacturers digitize procurement and supply-chain contracting at scale. The eIDAS 2.0 framework compels qualified signature adoption for cross-border commerce. Stuttgart and Munich automotive clusters deploy hybrid cloud configurations to satisfy data residency requirements while preserving workflow automation economics.
Italy
Public-sector procurement mandates drive demand for qualified trust-service provision. The national digital identity system (SPID) integration requirements harden technical specifications. Rome and Milan concentrate vendor accreditation activity where eIDAS certification timelines stretch competitive dynamics.
France
Defense supply chains mandate sovereign-cloud deployment for document management platforms. GDPR biometric processing constraints throttle AI-powered identity verification velocity. Paris and Toulouse aerospace clusters resist full cloud migration despite cost pressures from legacy system integration debt.
Netherlands
Dutch insurance distributors compress deployment cycles through serverless signing infrastructure adoption. The EU AI Act algorithmic transparency requirements shape automated contract-review procurement criteria. Amsterdam fintech clusters complete cloud-native migrations within accelerated eighteen-month windows.
Spain
Underpenetrated hospital networks lack integrated e-signature and clinical workflow systems. The national health service interoperability frameworks create whitespace for specialized health-tech vendors. Madrid and Barcelona medical research institutions pilot document management platforms with HIPAA-equivalent data protection standards.
European Digital Transaction Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Incumbent platforms with extensive partner integration networks anchor financial services contracts. Specialized trust-service providers dominate public-sector procurement channels under eIDAS accreditation requirements. Agile cloud-native vendors compress deployment cycles through API-first architectures. Competitive moves concentrate on strategic partnerships with ERP vendors and geographic expansion into underpenetrated healthcare verticals.
Within the trust-service provider tier, Namirial SpA occupies a position exemplifying qualified signature dominance under eIDAS frameworks. DocuSign Inc. and Adobe Inc. represent the platform-scale archetype, anchoring enterprise workflow automation across banking and retail sectors. These three entities collectively illustrate how regulatory accreditation and partner ecosystem breadth determine competitive positioning in fragmented national procurement channels.
| Leading Market Players |
|---|
| DocuSign Inc. |
| Adobe Inc. |
| Namirial SpA |
| Nintex Group Pty Ltd |
| Kofax Inc. |
| OneSpan |
| Entrust Datacard Corporation |
| PandaDoc |
| eOriginal Inc. |
| Others |
Pricing and Supply Chain Analysis
Regulatory accreditation chokepoints under eIDAS 2.0 determine both pricing tier spreads and supply chain shape, compressing margins for unqualified vendors while concentrating premium capture among trust-service providers with national certification.
Pricing Analysis
Cloud-native API architectures command premium subscription tiers against legacy on-premise installations and emerging serverless configurations. Pricing stratifies across qualified signature certification levels, deployment complexity, and biometric identity verification bundling. Cost compression in mid-market SaaS tiers intensifies as departmental buyers fragment procurement authority toward per-seat economics. Retail and logistics segments exhibit highest price sensitivity; financial services and government channels absorb premium positioning for compliance-grade functionality.
Supply Chain Analysis
Upstream cryptographic hardware and identity verification SDKs feed from German, Dutch, and Estonian technology clusters. Cloud infrastructure draws from hyperscaler regions in Ireland, Frankfurt, and Amsterdam, while specialized trust-service components source from Italian and DACH accreditation hubs. Single-source vulnerability concentrates in qualified signature hardware security modules and biometric liveness detection algorithms. Distribution runs through direct enterprise sales, ERP-embedded marketplaces, and systems integrator channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of eIDAS-qualified engineering talent and eighteen-month certification timelines constrain competitive entry, amplifying returns for vendors with established trust-service infrastructure and forcing latecomers toward acquisition or partnership pathways.
For Market Incumbents: Pre-empt API-first challengers by embedding signature workflows directly into SAP and Oracle procurement modules, tightening channel control. Accelerate backward integration into biometric identity verification SDKs to defend margin against modular disaggregation. Prioritize eIDAS 2.0 pre-certification investments to freeze out competitors during transition windows. For New Entrants and Emerging Players: Build out specialized health-tech offerings for Spanish and Portuguese hospital networks where clinical workflow integration remains underpenetrated. Target serverless signing infrastructure for Nordic insurance distributors seeking compressed deployment cycles. Lead with GDPR-compliant biometric processing as a differentiated go-to-market angle against legacy platforms. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors accredited trust-service providers with established DACH public-sector relationships. Long-term viability hinges on eIDAS certification moats and ERP ecosystem embedding depth. Monitor EU AI Act enforcement velocity as the critical inflection signal for automated contract-review tool valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding e-signature APIs into SAP Ariba procurement workflows captures Mittelstand manufacturing demand. |
| Acquisition of Specialist Firm | Consolidating biometric identity verification vendors hardens non-repudiation guarantees for banking origination. |
| Strategic Partnership | Aligning with Namirial SpA accelerates eIDAS qualified trust-service accreditation for Italian public procurement. |
| Product Launch | Serverless signing infrastructure targets Dutch insurance distributors completing eighteen-month cloud migrations. |
| Geographic Expansion | Establishing Madrid and Barcelona operations addresses whitespace in Spanish hospital network digitization. |
Research Methodology
A standing panel of chief procurement officers, trust-service compliance leads, ERP integration specialists, and healthcare IT directors provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews combined with eIDAS regulatory filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and hospital procurement database analysis. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across deployment models, verticals, and national regulatory clusters.
Scenario-bracketing anchored projections across the analysis window, modeling electronic signature adoption curves, workflow automation penetration rates, and qualified trust-service certification timelines. Segmentation dimensions spanned product type, end-user vertical, deployment architecture, and service intensity. CAGRs derived from regression analysis against historical digitization velocity and regulatory mandate implementation schedules, incorporating EU Green Deal paperless-transaction compliance trajectories and CSRD disclosure requirement bundling effects.
Stress conditions across eIDAS 2.0 accreditation delays, GDPR biometric processing enforcement variance, and cloud infrastructure cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Mittelstand digitization momentum and cross-border cryptographic standard harmonization progress. Cross-checking against European Banking Authority digital origination guidance and national competent authority audit standards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Core Graphics Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
Qatar ICT Market
Digital Solutions
France ICT Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
EHS Software Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Cheque Scanner Market