
 Ediscovery Solution Market | 2026-2036
Ediscovery Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Ediscovery Solution Market Foresight
SEC enforcement guidelines and the EU AI Act are restructuring the cost-of-entry calculus for ediscovery vendors, forcing heavier investment in audit trails and explainable AI. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise deployments across regulated industries. IBM Corporation competes through Watson Discovery's natural language processing capabilities in complex litigation. Relativity US, LLC dominates the review workspace segment with a channel model that extends through law firm partnerships.
Ediscovery solutions encompass software and services for identifying, collecting, processing, reviewing, and producing electronically stored information in legal proceedings, typically handling petabyte-scale data volumes with metadata preservation and chain-of-custody documentation. Their primary purpose centers on reducing review costs and accelerating case timelines while meeting court-admissible evidence standards. Cloud-based deployment leads the market as corporates migrate away from capital-intensive on-premise infrastructure, while legal hold solutions represent the fastest-growing solution type amid proactive compliance programs. Document review captures the deepest margin pools due to attorney-hour substitution economics.
The SEC, EU AI Act framework, and Federal Rules of Civil Procedure collectively shape product roadmaps, mandating defensible deletion policies and algorithmic transparency in predictive coding. HIPAA and GDPR overlay additional constraints when health records or personal data enter litigation holds. Stakeholders must monitor regulatory divergence between US federal discovery standards and emerging EU algorithmic accountability requirements when architecting cross-border data governance.
Market Dynamics
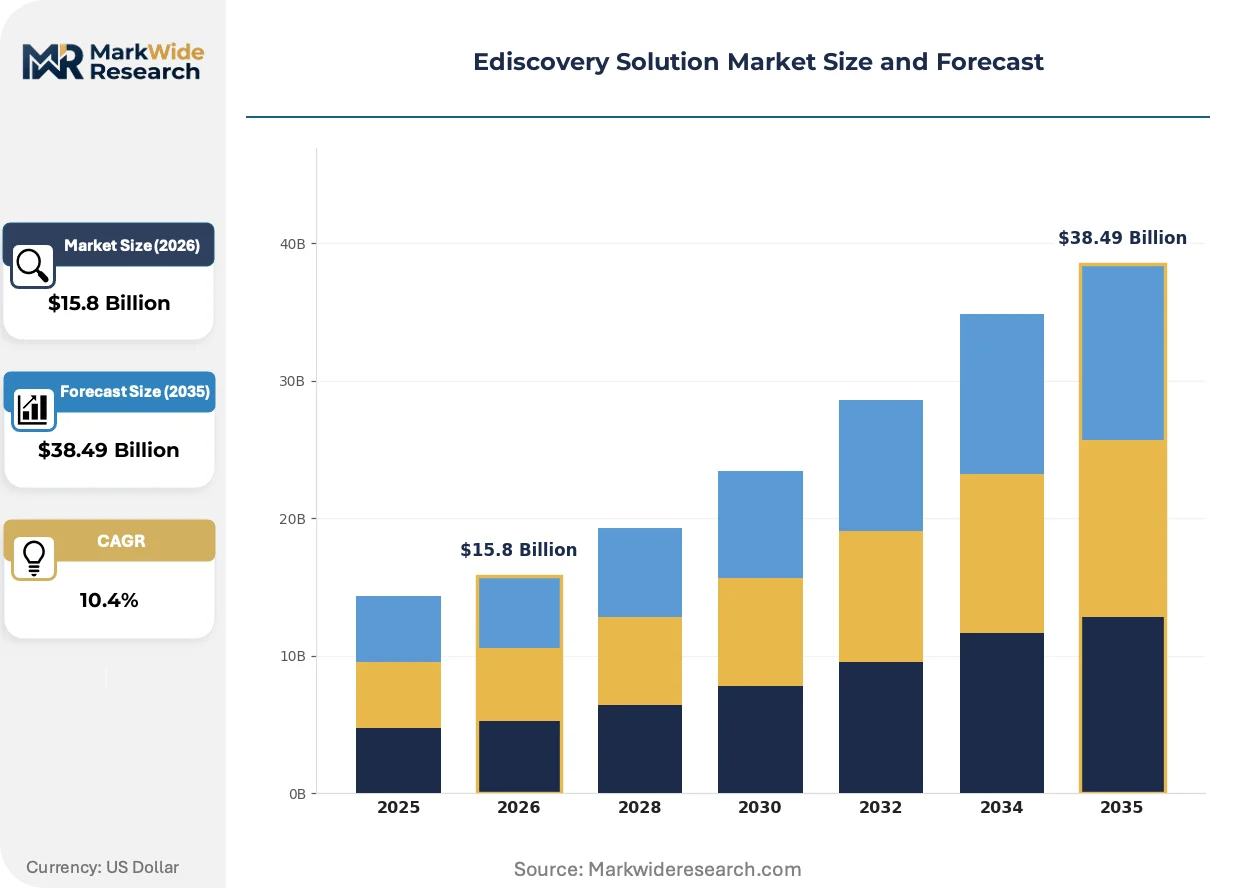
Cloud migration is compressing infrastructure ownership cycles while the EU AI Act and SEC enforcement guidelines force algorithmic auditability into product roadmaps. Vendors must now engineer explainable AI pipelines alongside petabyte-scale processing architectures.
Growth Catalysts
- EU AI Act compliance mandates:Automated document review tools require transparent decision trails, expanding demand for audit-ready platforms across multinational legal departments.
- Corporate legal departments:General counsel offices are retiring on-premise servers for elastic cloud capacity to handle litigation holds without capital deployment.
- Federal Rules of Civil Procedure:Rule 37(e) sanctions for spoliation drive investment in defensible deletion and legal hold automation.
Market Restraints
- Cloud concentration risk:Three hyperscalers control the underlying infrastructure for most deployments, creating single-point-of-failure exposure.
- Technical limitation:Optical character recognition accuracy degrades below commercial thresholds for handwritten documents and degraded scans.
- Regulatory friction:GDPR data residency requirements conflict with US discovery obligations, forcing costly jurisdictional data segmentation.
Strategic Opportunities
- Underpenetrated mid-market law firms:Firms with 50-200 attorneys lack dedicated ediscovery staff, creating whitespace for managed service bundles.
- Technology convergence:Large language models paired with predictive coding engines enable semantic search beyond keyword matching.
- SEC whistleblower program expansion:Surging enforcement actions generate sustained demand for proactive investigation platforms.
Industry Challenges
- Forensic investigator talent scarcity:Certified computer examiners command premium compensation, constraining service scaling.
- Legacy system integration friction:Mainframe-based enterprise content management systems resist API connectivity for automated collection.
- Cross-border data governance complexity:Divergent national blocking statutes impede unified review workflows for multijurisdictional matters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ediscovery Solution Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $38.49 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Managed Service End User: Corporates, Law Firms, Government Agencies, Financial Institutions Solution Type: Data Processing, Litigation Support, Document Review, Legal Hold Integration Level: APIs, Third-Party Tools, In-House Solutions, Others |
| Companies Covered | Microsoft Corporation, IBM Corporation, Relativity US, LLC, OpenText Corporation, DISCO, Inc., Nuix Limited, Exterro, Inc., KLDiscovery Inc., Epiq Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ediscovery Solution Market Shifts & Advancements
Generative AI is rewriting document review economics while regulatory pressure on algorithmic accountability intensifies. Platform architectures are converging around API-first design and continuous active learning.
Continuous active learning protocols are consolidating attorney review workflows by prioritizing statistically significant document batches. Corporate legal departments and large law firms are deploying these engines across terabyte-scale matters within 90-day implementation windows. The technology is consolidating review team structures from linear senior-junior attorney hierarchies into smaller validation-focused pods.
The EU AI Act risk classification framework is restructuring vendor development priorities by mandating human oversight interfaces for high-risk automated decision systems. Ediscovery platforms must now embed explanation modules that trace classification logic to specific training data subsets. European corporate legal teams are demanding these capabilities ahead of US counterparts, creating a two-speed compliance market.
Subscription pricing models are displacing per-matter transaction structures across mid-market buyers. Law firms with predictable litigation volume are negotiating annual platform licenses that bundle processing, hosting, and review seats. This shift is most visible in the United States, where Am Law 200 firms face pressure to convert variable discovery costs into fixed operational expenses for client rate predictability.
Ediscovery Solution Market Segmentation
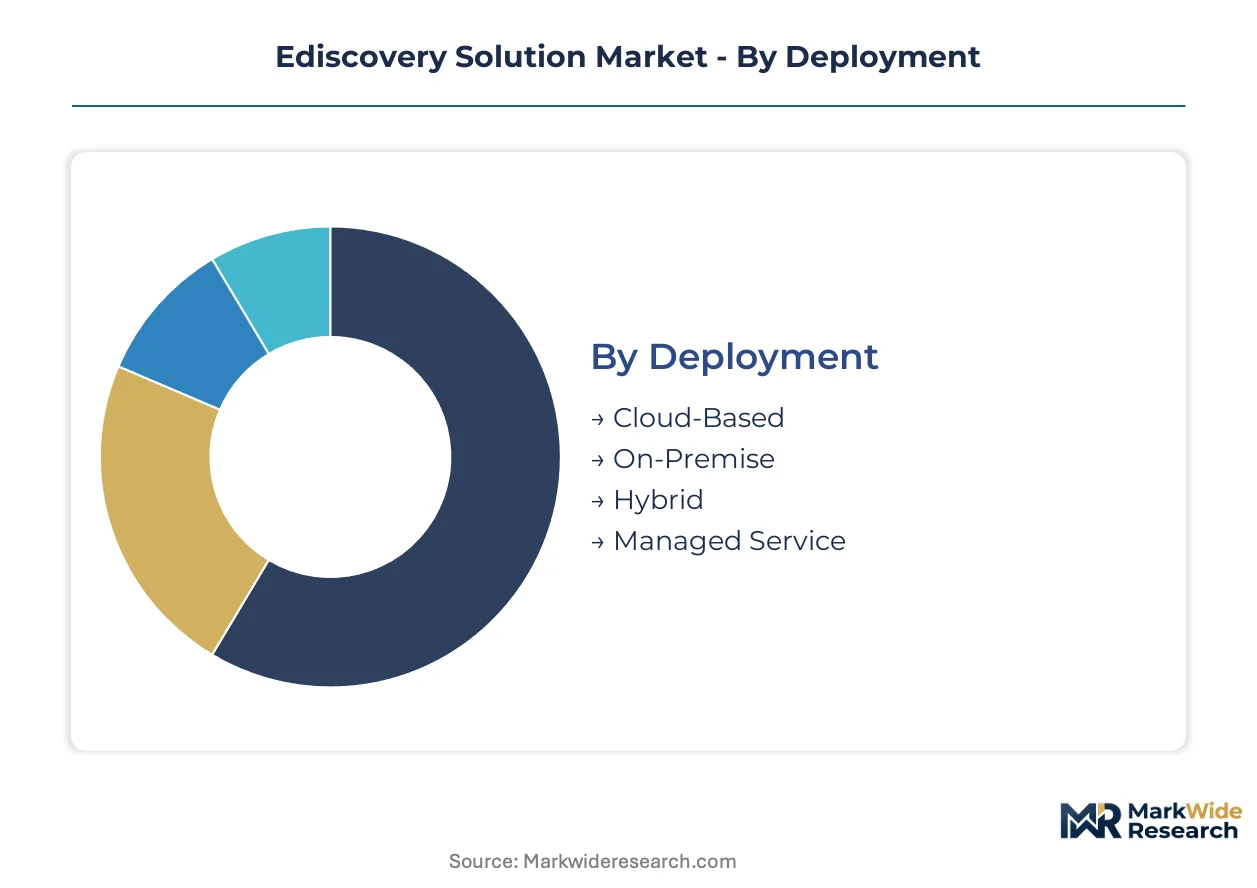
Ediscovery solution segmentation reveals how deployment architecture, user sophistication, and integration depth reshape procurement patterns. Buyers optimize across total cost of ownership, regulatory exposure, and matter velocity when selecting configuration tiers.
Deployment:
The customization-to-standardization spectrum spans from fully managed service bundles to self-operated on-premise infrastructure, with hybrid configurations occupying the middle ground for firms navigating data residency constraints.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for petabyte-scale processing without capital deployment. Corporates in the United States dominate consumption, driven by SEC enforcement timelines that compress matter initiation windows.
- Managed Service:Providers assume operational responsibility for collection through production, embedding defensible workflows and chain-of-custody documentation. Mid-market law firms with 50-200 attorneys favor this model to substitute fixed fees for variable attorney hours.
- On-Premise:Dedicated hardware installations within client data centers preserve maximum control over sensitive matter data. Defense contractors and classified government workstreams mandate this architecture for air-gapped security requirements.
- Hybrid:Split deployments process active matters in cloud environments while archiving completed cases to on-premise storage. European multinationals deploy this pattern to reconcile GDPR data residency with US discovery obligations.
Leading the category by volume: Cloud-Based. Expanding most quickly: Managed Service.
End User:
Procurement sophistication varies sharply across this category, from centralized legal operations teams to distributed agency counsel with constrained technical staffing.
- Corporates:General counsel offices deploy enterprise-wide platforms with legal hold automation and predictive coding engines. Technology and healthcare sectors concentrate demand due to HIPAA overlay requirements and IP litigation frequency.
- Law Firms:Am Law 200 practices negotiate annual platform licenses bundling processing, hosting, and review seats. Client rate predictability pressures are converting variable discovery costs into fixed operational expenses.
- Government Agencies:Federal and state entities mandate FedRAMP-authorized infrastructure with audit trails satisfying public records statutes. Procurement cycles extend 18-24 months due to security clearance and appropriations requirements.
- Financial Institutions:Banks and asset managers face overlapping SEC, CFTC, and state regulatory examination regimes. Whistleblower program expansion is sustaining investment in proactive investigation platforms.
Dominant by procurement value: Corporates. Steepest expansion trajectory: Financial Institutions.
Solution Type:
Margin concentration follows the attorney-hour substitution curve, with review automation capturing the deepest pools and hold management gaining share through proactive compliance programs.
- Document Review:Continuous active learning engines prioritize statistically significant batches, consolidating senior-junior attorney hierarchies into validation-focused pods. Terabyte-scale deployments complete implementation within 90-day windows.
- Legal Hold:Automated notification, acknowledgment, and preservation workflows reduce spoliation exposure under Federal Rules of Civil Procedure Rule 37(e). Corporate legal departments are retiring manual spreadsheet tracking for integrated hold management.
- Data Processing:ETL pipelines normalize hundreds of file formats while preserving metadata and embedded objects. De-duplication and near-deduplication algorithms compress review populations by 40-60 percent before attorney eyes touch documents.
- Litigation Support:Case management modules coordinate deadlines, custodian interviews, and production specifications across distributed legal teams. Court-admissible evidence standards mandate embedded quality assurance protocols.
Highest margin capture: Document Review. Gaining share fastest: Legal Hold.
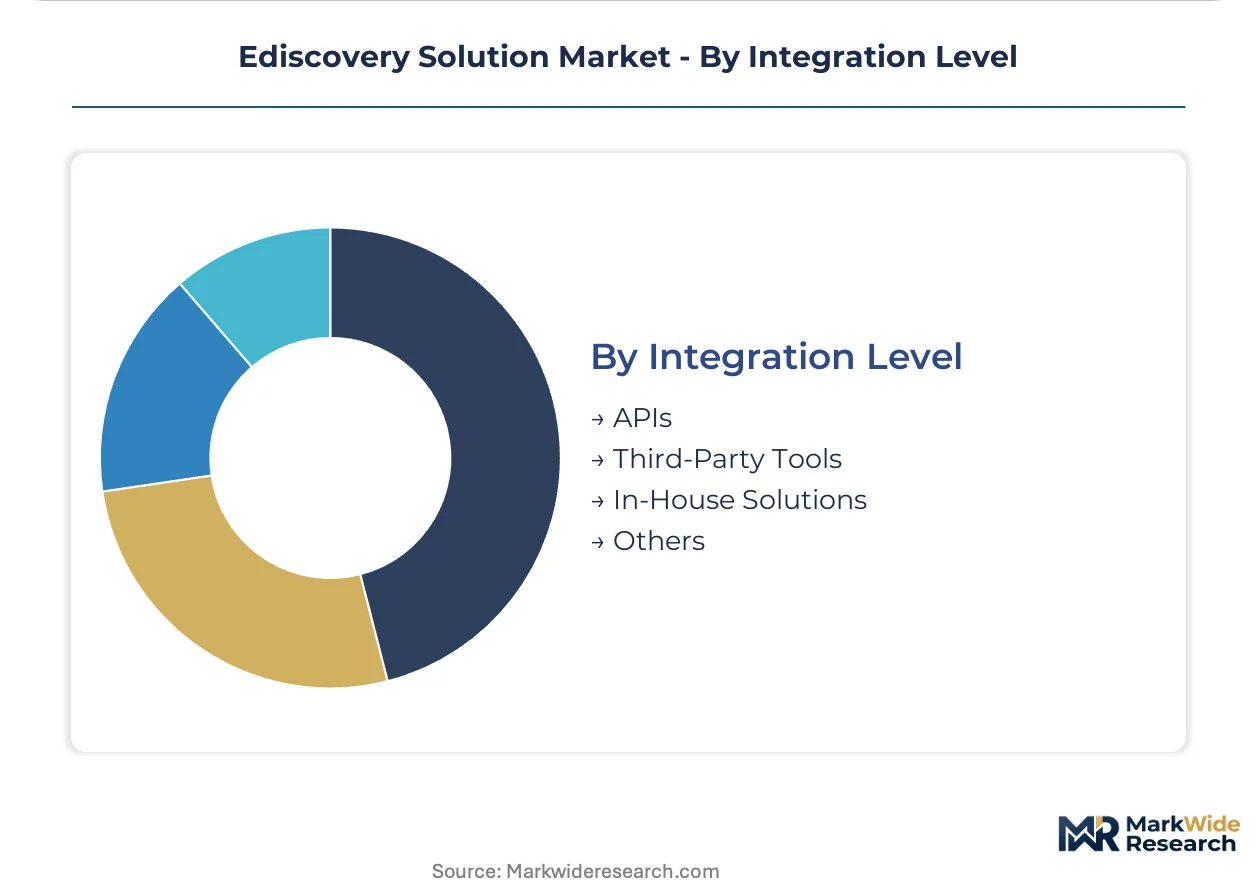
Integration Level:
Connectivity depth determines workflow friction, with API-first architectures displacing manual export-import cycles and custom development absorbing specialized requirements.
- APIs:RESTful interfaces enable real-time data exchange between ediscovery platforms and enterprise content management systems. Modern architectures embed continuous active learning feedback loops without batch processing delays.
- Third-Party Tools:Pre-built connectors to Microsoft 365, Slack, and Salesforce accelerate collection from dominant collaboration platforms. Relativity and other workspace providers maintain certification programs for partner integrations.
- In-House Solutions:Custom-developed modules address proprietary data formats or specialized review protocols. Pharmaceutical companies deploy these for clinical trial document workflows with FDA submission requirements.
- Others:Manual export-import via standardized load files persists for legacy systems resisting API connectivity. Mainframe-based enterprise content management systems in regulated industries drive continued reliance on this pattern.
Deployment concentration: APIs. Fastest connectivity adoption: Third-Party Tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States legal departments consume the deepest ediscovery platform volumes, while European regulatory divergence and Asia-Pacific data localization rules fragment deployment architectures across multinational corporations.
United States
Federal litigation volume and SEC enforcement timelines compress matter initiation windows for corporate legal teams. The Federal Rules of Civil Procedure Rule 37(e) spoliation sanctions mandate defensible deletion policies. New York and Washington D.C. legal markets anchor the highest concentration of Am Law 200 firms negotiating annual platform licenses.
Germany
GDPR data residency requirements drive hybrid cloud deployments among automotive and industrial conglomerates. The EU AI Act risk classification framework mandates human oversight interfaces for automated document review. Frankfurt's financial services cluster sustains demand for proactive investigation platforms amid BaFin examination regimes.
United Kingdom
Magic Circle firms and London-based litigation funders prioritize elastic cloud capacity for cross-border arbitration matters. The UK Information Commissioner's Office enforcement posture shapes retention and deletion protocols. The City of London insurance and banking complex generates sustained matter volume for managed service providers.
Japan
Corporate legal departments at electronics and automotive manufacturers adopt cloud-based platforms for US-facing litigation. METI guidelines on data governance influence vendor selection criteria. Tokyo's concentrated headquarters economy drives enterprise-wide platform deployments across keiretsu-affiliated groups.
Australia
Class action litigation expansion and royal commission inquiries sustain platform investment among corporate legal teams. The Australian Information Commissioner enforcement activity elevates defensible hold management priorities. Sydney and Melbourne legal markets concentrate demand for managed service bundles among mid-market practices.
Ediscovery Solution Market Competitive Landscape
United States-based vendors anchor the enterprise platform tier; European specialists hold compliance-forward positioning. The vendor base splits between hyperscale cloud providers with legal vertical extensions and pure-play workspace platforms with channel-dependent distribution. Three strategic archetypes dominate: infrastructure-backed suites, review-centric workspaces, and managed service bundlers. Competitive moves concentrate on API ecosystem expansion and subscription pricing model conversion.
Within the infrastructure-backed tier, Microsoft Corporation exemplifies cloud-native deployment scale, while IBM Corporation occupies a position in natural language processing integration. Relativity US, LLC anchors the review workspace segment through law firm channel partnerships. These three vendors represent distinct competitive vectors: hyperscale platform extension, AI service layering, and vertical workflow specialization.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Relativity US, LLC |
| OpenText Corporation |
| DISCO, Inc. |
| Nuix Limited |
| Exterro, Inc. |
| KLDiscovery Inc. |
| Epiq Systems, Inc. |
| Others |
Supply & Pricing Matrix
Horizontal integration through hyperscale cloud partnerships anchors supply positioning for ediscovery vendors while compressing infrastructure ownership cycles into subscription economics. This integration choice concentrates pricing power among three infrastructure providers and forces pure-play software vendors into margin-diluting channel arrangements.
Pricing Analysis
Volume concentration in cloud-based deployments splits margin capture between hyperscale infrastructure providers and software layer vendors. Three-tier pricing structure across enterprise, mid-market, and managed service levels differentiates by integration depth and legal hold automation sophistication. Pricing pressure stems from SEC enforcement timelines compressing procurement cycles and forcing faster implementation concessions. Mid-market law firms with 50-200 attorneys exhibit highest price sensitivity due to fixed-fee client pressures, while financial institutions accept premium tiers for proactive investigation capabilities.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale corporate demand while law firm partnerships distribute through managed service bundlers. Infrastructure supply concentrates in United States, Ireland, and Singapore data center clusters to satisfy GDPR and data residency requirements. Component dependencies include GPU compute instances for predictive coding, optical character recognition engines for degraded document processing, and API middleware for enterprise content management connectivity. Single-source vulnerability in hyperscaler concentration creates failover risk during peak litigation hold windows. Distribution runs through certified channel partners with legal domain expertise and defensible workflow documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU AI Act compliance mandates is forcing subscale vendors toward acquisition or managed service pivots as audit trail investments exceed standalone R&D budgets.
For Market Incumbents: Anchor defensible market position through backward integration into legal hold automation and continuous active learning engine development. Acquire mid-market managed service providers to capture 50-200 attorney firm relationships before competitors consolidate this whitespace. Threat substitution from large language model-native entrants demands accelerated explainable AI roadmap investment to maintain enterprise credibility. For New Entrants and Emerging Players: The pricing gap between Relativity-dominated premium workspaces and entry-level cloud processing tools creates entry space for semantic search-native platforms targeting corporate legal departments with 90-day implementation guarantees. White-space concentrates in financial services proactive investigation platforms and European GDPR-compliant hybrid deployments. Go-to-market should emphasize API-first architecture with pre-built Microsoft 365 and Slack connectors to bypass legacy integration friction. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler platform extension and private equity roll-up of regional managed service providers. Five-to-ten year viability favors vendors with FedRAMP authorization and EU AI Act-ready explanation modules already deployed. Signal to monitor: SEC whistleblower program expansion rates as demand inflection for proactive investigation platforms.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Pre-built connectors to Microsoft 365 and Slack accelerate collection from dominant collaboration platforms. |
| Explainable AI Module Development | EU AI Act mandates human oversight interfaces for high-risk automated document review systems. |
| Managed Service Bundle Launch | Mid-market law firms substitute fixed fees for variable attorney hours through operational outsourcing. |
| FedRAMP Authorization Pursuit | Government agency procurement cycles require security clearance for federal and state entity deployments. |
| Continuous Active Learning Integration | Terabyte-scale matters complete implementation within compressed windows, consolidating review team structures. |
Research Methodology
Document review covered SEC enforcement guidelines, EU AI Act implementation drafts, and Federal Rules of Civil Procedure amendments, complemented by interviews with general counsel at technology and healthcare corporates, litigation support directors at Am Law 200 firms, ediscovery platform product managers, and forensic investigators with certified computer examiner credentials. Secondary validation drew from hyperscaler capex disclosures, legal technology trade publications, and court filing analytics databases. Bottom-up segment sizing triangulated against top-down legal spend allocation models.
Cross-reference between historical matter volume patterns and expert panel input on cloud migration timelines shaped the analytical framework across deployment architecture, end user sophistication, and solution type dimensions. CAGRs derived from elasticity-adjusted adoption curves and regulatory compliance deadline clustering. Forecast inputs included SEC examination frequency projections and EU AI Act enforcement phase transitions.
Inputs from corporate legal department procurement officers were available through the study window; gaps in mid-market law firm technology spending disclosure introduce uncertainty bands around managed service adoption trajectories. Forecasts reflect assumptions on regulatory divergence persistence and hyperscaler pricing stability. Periodic stress-testing of base assumptions against SEC enforcement priority shifts and EU AI Act interpretation guidance is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Kuwait ICT Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Dataops Platform Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Data Integration Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Master Data Management Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Mobile Campaign Management Platform Market