
 Connected Stadium Solution Market | 2026-2036
Connected Stadium Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Stadium Solution Market Analytics
Enterprise-grade Wi-Fi 6E and sub-6 GHz 5G specification tiers is unwinding legacy distributed antenna system architectures across major venue portfolios. Cisco Systems leverages its Meraki and Catalyst platforms to anchor campus-style deployments in North American arenas. Ericsson competes through its radio system integration muscle, particularly in European football venues requiring dense-sector 5G. Nokia Corporation specializes in private wireless implementations, extending its Digital Automation Cloud into stadium environments where low-latency edge compute controls video replay and security orchestration.
Connected stadium solutions encompass integrated networking, compute, and sensor infrastructure purpose-built for high-density spectator environments, typically supporting 50,000 to 100,000 concurrent client devices with sub-50 millisecond latency for real-time video and transactional applications. The primary commercial purpose centers on monetizing fan dwell time through frictionless commerce, immersive replay, and targeted sponsorship activation while hardening physical security through AI-video convergence. Wi-Fi 6 and 5G technology segments command the largest installed base, though edge computing represents the fastest-expanding margin pool as venues internalize content delivery and analytics processing. Fan engagement applications currently absorb the majority of new capital allocation, while security solutions embed deeper into municipal emergency response frameworks, tightening procurement standards.
The FCC governs spectrum licensing and unlicensed band rules that directly shape radio refresh timelines and vendor qualification criteria for US stadium builds. ETSI and 3GPP standards frame interoperability mandates that equipment suppliers must satisfy for multi-operator neutral-host architectures, particularly across European venues subject to national telecom regulator enforcement. Stakeholders must weigh capital intensity against operating model flexibility, as venue owners face a structural choice between managed service dependencies and in-house network operations competencies.
Market Dynamics
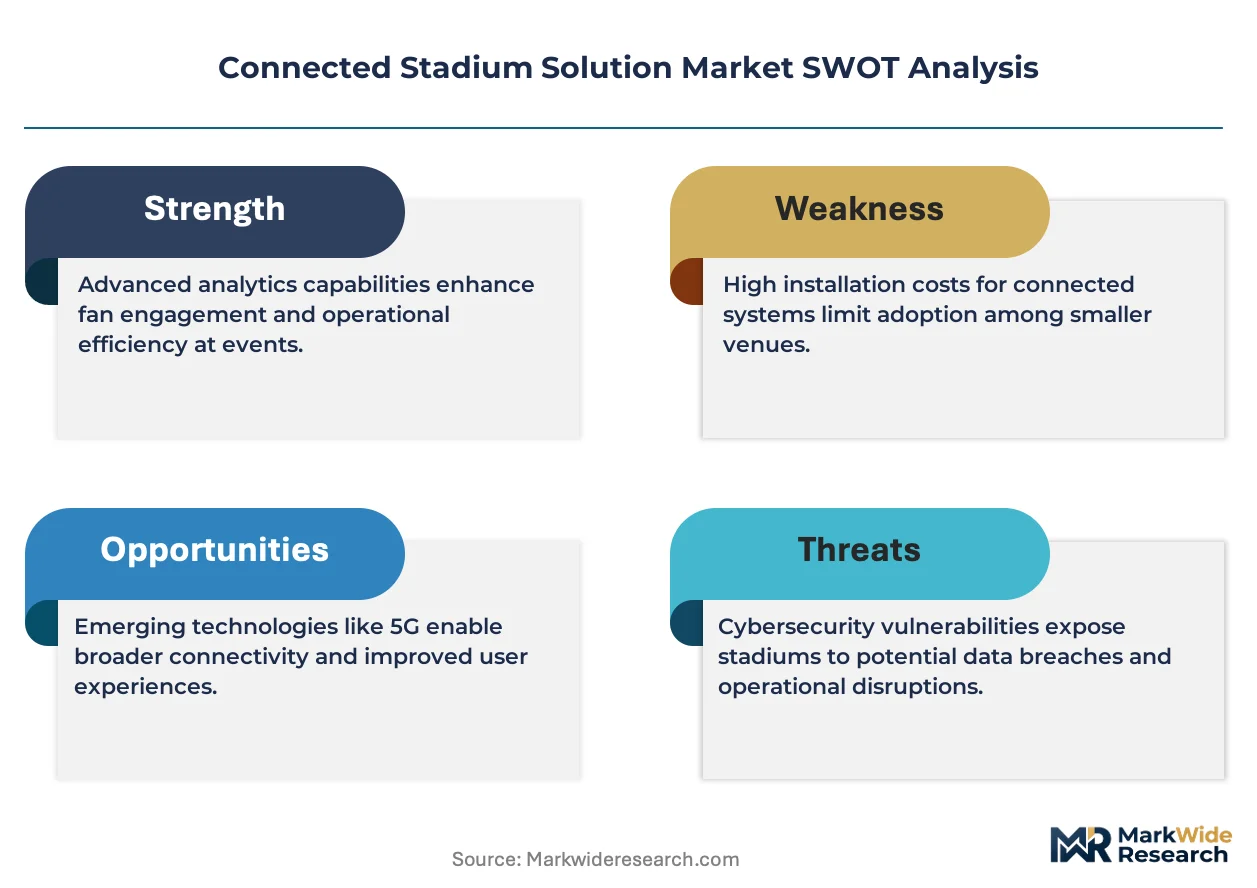
Venue owners face a forced architectural pivot as Wi-Fi 6E and sub-6 GHz 5G specifications unwind legacy distributed antenna system architectures, compelling wholesale infrastructure replacement across major arena portfolios.
Growth Catalysts
- Spectrum liberalization:The FCC's unlicensed Wi-Fi band allocations accelerate refresh cycles for aging neutral-host networks in American football and baseball venues.
- Fan monetization pressure:Professional sports franchises expand technology budgets to capture dwell-time revenue through frictionless commerce and immersive replay.
- Edge compute integration:Low-latency processing requirements for video replay and security orchestration pull private wireless deployments into stadium environments.
Market Restraints
- Radio frequency complexity:Dense-sector 5G implementations demand specialized integration expertise that concentrates among a limited vendor set.
- Capital intensity:Campus-style deployments require simultaneous investment in switching, compute, and sensor infrastructure with extended payback horizons.
- Standard fragmentation:ETSI and 3GPP interoperability mandates create qualification bottlenecks for multi-operator architectures in European venues.
Strategic Opportunities
- Municipal emergency integration:AI-video convergence for physical security tightens procurement standards and embeds stadium networks into city response frameworks.
- Content delivery internalization:Venues building in-house edge processing capabilities capture analytics margin pools previously ceded to cloud providers.
- Service model bifurcation:Managed network services and in-house operations competencies present divergent paths for owner-operator margin structures.
Industry Challenges
- Skill scarcity:Neutral-host architecture design and multi-operator coordination require RF engineering talent that outpaces supply in many markets.
- Legacy system entanglement:Existing distributed antenna installations constrain physical pathways for new fiber and power distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Stadium Solution Market |
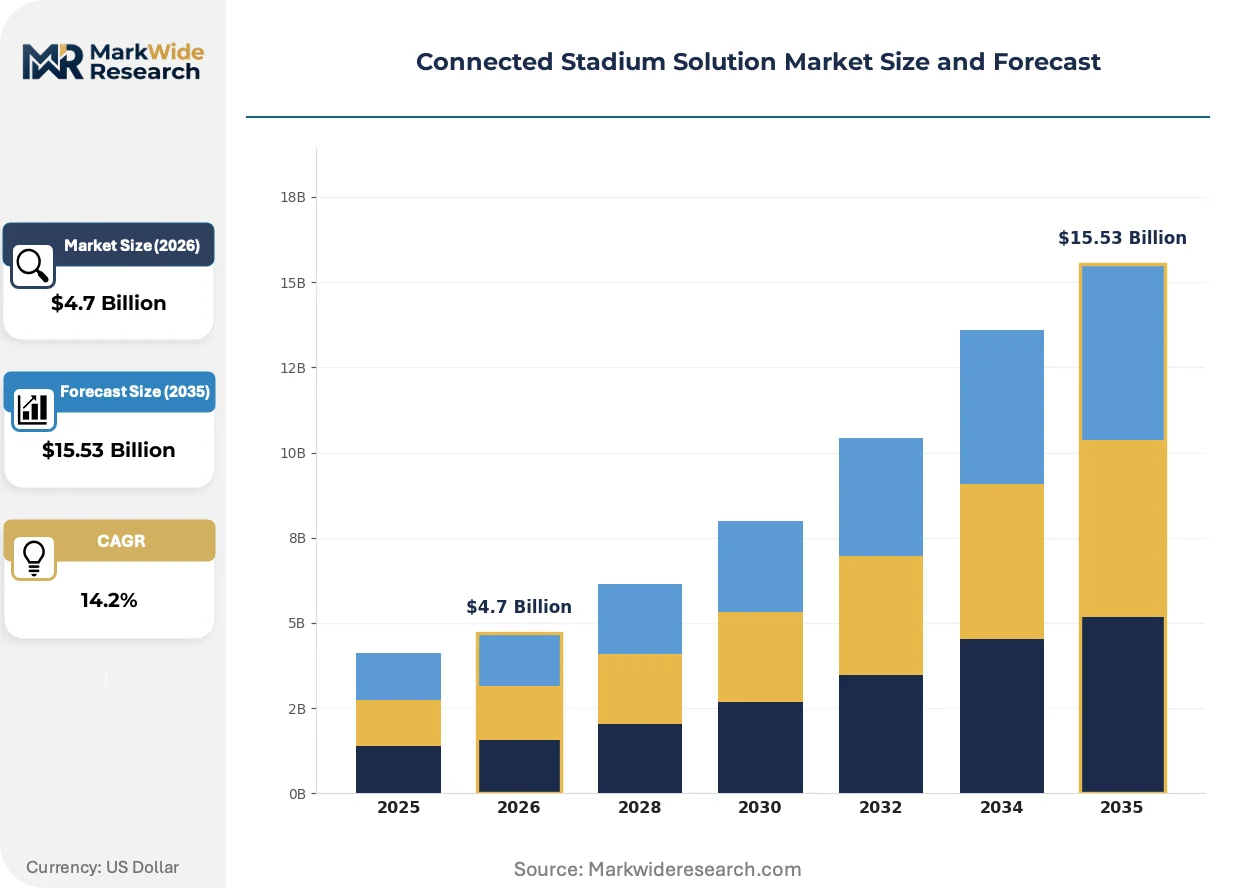
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 5G, Wi-Fi 6, Edge Computing, IoT Sensors End User: Event Organizers, Sports Teams, Venue Owners, Fans Application: Ticketing Systems, Fan Engagement, Security Solutions, Video Analytics Service Type: Integration Services, Maintenance, Consulting, Data Analytics |
| Companies Covered | Ericsson, CommScope Holding Company, Cisco Systems, AT&T, Verizon Communications, Huawei Technologies, Nokia Corporation, Samsung Electronics, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Stadium Solution Market Evolving Landscape
Network architecture decisions in spectator venues are converging around three simultaneous shifts: radio technology succession, regulatory timing pressure, and procurement model experimentation.
Wi-Fi 6E is supplanting previous-generation wireless standards in high-density spectator environments. NFL and MLB venues undergoing network overhauls are adopting the extended 6 GHz spectrum to support 50,000 to 100,000 concurrent client devices. This succession compresses refresh timelines and collapses the installed base of legacy equipment faster than originally projected.
ETSI interoperability mandates are reshaping equipment qualification criteria for European football venues subject to national telecom regulator enforcement. Multi-operator neutral-host architectures must satisfy 3GPP specifications that add certification layers and extend procurement cycles. Dense-sector 5G deployments in Germany and Spain face particular scrutiny under these frameworks.
After-sales service unbundling is fragmenting traditional vendor relationships in North American arena builds. Venue owners are separating hardware acquisition from ongoing network operations, creating openings for specialized managed service providers. This pattern is most visible in United States markets where capital constraints push owners toward operational expenditure models.
Connected Stadium Solution Market Segmentation
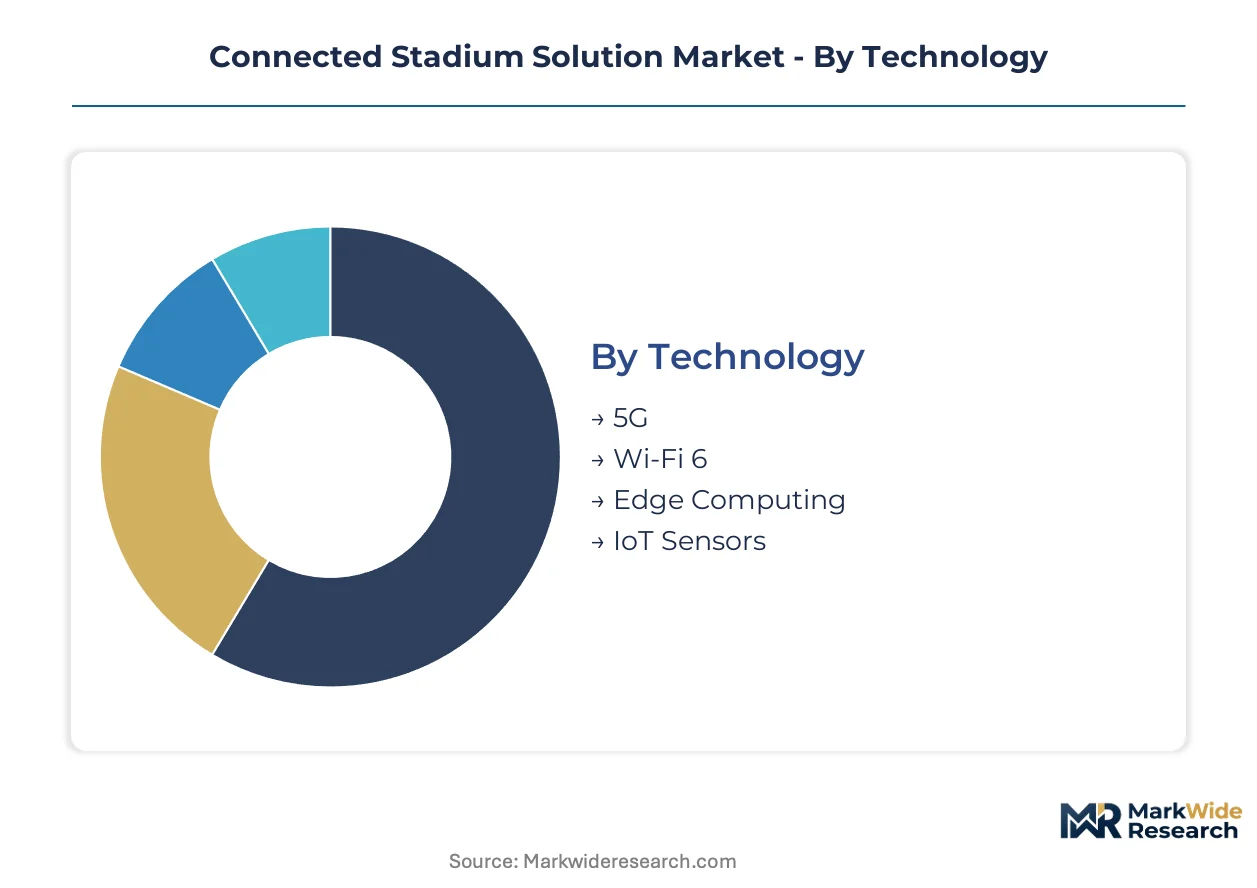
Connected stadium solutions fragment across technology generations, stakeholder priorities, and operational workflows. Each segmentation axis reveals distinct procurement patterns and margin structures that vendors must navigate.
Technology:
Geographic adoption spreads unevenly, with North American venues leading on unlicensed spectrum deployments while European markets emphasize licensed 5G integration.
- 5G:Sub-6 GHz and mmWave radio systems deliver dedicated bandwidth slices for ultra-reliable low-latency communications. Demand concentrates in German and Spanish football venues where national telecom regulators enforce dense-sector neutral-host mandates under ETSI frameworks.
- Wi-Fi 6:The 6 GHz extended spectrum standard supports 50,000 to 100,000 concurrent client devices with OFDMA scheduling. NFL and MLB venues in the United States dominate procurement, driven by FCC unlicensed band allocations that accelerate refresh cycles.
- Edge Computing:On-premise processing nodes reduce round-trip latency for video replay and security orchestration.
- IoT Sensors:Environmental and occupancy monitoring devices feed real-time crowd management systems.
Wi-Fi 6 holds the largest share; momentum sits with Edge Computing.
End User:
Procurement authority varies sharply by contract structure, with some stakeholders controlling capital budgets while others influence operational specifications.
- Venue Owners:Balance sheet holders make architectural decisions on infrastructure ownership versus managed service dependencies. United States arena portfolios favor operational expenditure models that separate hardware acquisition from ongoing network operations.
- Sports Teams:Franchise technology budgets expand to capture dwell-time revenue through frictionless commerce and immersive replay experiences.
- Event Organizers:Temporary tenancy arrangements create demand for rapid-deployment connectivity kits.
- Fans:End-consumer expectations for seamless mobile experiences indirectly shape technical specifications through satisfaction metrics.
Venue Owners command the dominant budget share; Sports Teams are gaining procurement influence fastest.
Application:
Functional requirements diverge between revenue-generating fan-facing systems and cost-center security infrastructure.
- Fan Engagement:Mobile applications delivering augmented replay, concession ordering, and seat-upgrading functionality. NFL venues prioritize these investments to monetize spectator dwell time through targeted sponsorship activation.
- Security Solutions:AI-video convergence for physical access control and crowd anomaly detection. Municipal emergency response frameworks in the United States embed stadium networks into city-wide command structures.
- Ticketing Systems:Contactless entry and dynamic pricing platforms reduce gate friction.
- Video Analytics:Player-tracking and broadcast augmentation tools serve internal production teams.
Fan Engagement absorbs the majority of new capital; Security Solutions embed most deeply into regulatory compliance frameworks.
Service Type:
Delivery models are bifurcating between integrated turnkey contracts and unbundled specialist engagements.
- Integration Services:Multi-vendor system orchestration spanning radio, switching, and compute layers. European football venues require particular expertise to satisfy 3GPP interoperability mandates for multi-operator architectures.
- Data Analytics:Fan behavior processing and predictive maintenance algorithms. Venue owners building in-house capabilities capture margin pools previously ceded to cloud providers.
- Maintenance:Post-warranty hardware support and software patch management.
- Consulting:Network design and RF engineering advisory for greenfield developments.
Integration Services represents the largest revenue pool; Data Analytics climbs the fastest as venues internalize content delivery capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based infrastructure vendors export connectivity hardware and integration services to stadium operators across Germany, the United Kingdom, and Japan, where venue modernization cycles lag North American refresh timelines by two to three years.
United States
NFL and MLB franchises drive procurement of Wi-Fi 6E infrastructure to support 50,000 to 100,000 concurrent devices. The FCC's unlicensed spectrum allocations for the 6 GHz band compress replacement cycles for aging neutral-host networks. Dallas-Fort Worth and Los Angeles metropolitan clusters host the densest concentration of venue technology deployments undergoing simultaneous 5G and Wi-Fi overhauls.
Germany
Bundesliga football venues require dense-sector 5G implementations under national telecom regulator enforcement of ETSI interoperability mandates. The country's Federal Network Agency (Bundesnetzagentur) imposes certification layers that extend procurement cycles for multi-operator neutral-host architectures. Munich and Dortmund industrial corridors concentrate system integration expertise for stadium-specific radio deployments.
United Kingdom
Premier League clubs expand technology budgets to capture dwell-time revenue through frictionless commerce and immersive replay experiences. Ofcom governs spectrum licensing rules that shape equipment qualification criteria for neutral-host builds. London metropolitan venues lead procurement volume, with Manchester and Liverpool clusters following in network modernization investment.
Spain
La Liga football stadiums face particular scrutiny under ETSI and 3GPP specification requirements for multi-operator architectures. The country's national telecom regulator enforces dense-sector 5G mandates that concentrate vendor selection among qualified integration specialists. Madrid and Barcelona urban cores anchor the majority of private wireless deployment activity for video replay and security orchestration.
Japan
Nippon Professional Baseball venues and J-League football stadiums import campus-style networking architectures from North American deployment patterns. METI industrial policy frameworks influence spectrum allocation timing for venue-specific 5G implementations. Tokyo-Yokohama and Osaka-Kobe metropolitan clusters concentrate demand for edge computing nodes that reduce latency for real-time video processing.
Connected Stadium Solution Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and service model dimensions. The vendor base concentrates among telecommunications equipment manufacturers, enterprise networking platforms, and systems integration houses with stadium-specific deployment expertise. Three archetypes dominate: radio infrastructure specialists, campus networking platforms, and private wireless integrators. Competitive moves center on unbundling hardware acquisition from managed service dependencies, and on building in-house edge computing capabilities that capture analytics margin pools.
Within the telecommunications infrastructure tier, Ericsson and Nokia Corporation exemplify European-headquartered equipment vendors with radio system integration muscle for dense-sector 5G deployments. Cisco Systems occupies a position among enterprise networking platforms, anchoring campus-style Wi-Fi 6E implementations through Meraki and Catalyst product lines. Huawei Technologies sits within the same competitive set, though its geographic footprint concentrates outside North American markets due to procurement restrictions. These three entities represent divergent strategic postures on spectrum licensing alignment, managed service bundling, and edge compute integration depth.
| Leading Market Players |
|---|
| Ericsson |
| CommScope Holding Company |
| Cisco Systems |
| AT&T |
| Verizon Communications |
| Huawei Technologies |
| Nokia Corporation |
| Samsung Electronics |
| Hewlett Packard Enterprise |
| Others |
Value Network & Pricing Analysis
Wi-Fi 6E radio module substitution for legacy DAS components is redrawing component sourcing maps from distributed antenna specialists toward semiconductor foundries, compressing hardware margins while concentrating procurement leverage among Cisco, Ericsson, and Nokia.
Pricing Analysis
Wi-Fi 6E infrastructure commands a 40-60% premium over Wi-Fi 5 equivalents, while sub-6 GHz 5G macro equipment sits 25-35% above prior-generation radio hardware. Project-based contracting dominates stadium builds, with price differentiation driven by certification tier (FCC Part 15 compliance vs. ETSI EN 301 893) and after-sales service bundling. Cost compression in legacy DAS replacement cycles is intensifying because venue owners unbundle hardware acquisition from managed services. Sports franchises with expanded technology budgets show the least price sensitivity, while municipal-owned venues face the tightest capital constraints.
Supply Chain Analysis
Just-in-time inventory strategies prevail for radio access network hardware, though strategic stockpiling of 6 GHz spectrum-certified chipsets has emerged among US integrators anticipating FCC allocation bottlenecks. Component sourcing concentrates in Taiwan, South Korea, and the United States for baseband processors and RF front-end modules. Raw material dependencies span gallium nitride substrates, high-purity silicon carbide, and specialized printed circuit board laminates. Single-source vulnerability in 6 GHz power amplifier supply creates exposure. Distribution runs through authorized value-added resellers and direct OEM contracts to venue owners and systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected stadium solution market sits at an inflection where FCC spectrum liberalization and Wi-Fi 6E refresh cycles are compressing decade-long infrastructure amortization schedules into five-year replacement windows.
For Market Incumbents: Consolidate RF engineering talent pools through targeted acquisition of neutral-host architecture specialists in Dallas-Fort Worth and Los Angeles clusters, where venue modernization timelines are most compressed. Deepen backward integration into edge compute hardware to capture analytics margin pools previously ceded to cloud providers, defending against hyperscaler encroachment into stadium environments. For New Entrants and Emerging Players: Differentiate on managed service unbundling, targeting US municipal-owned venues with operational expenditure models that separate hardware procurement from ongoing network operations. White-space opportunity concentrates in mid-tier MLB markets undergoing simultaneous security and fan engagement upgrades, with go-to-market traction through specialized RF engineering advisory services. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors private wireless integration specialists with stadium-specific deployment expertise and existing Bundesliga or La Liga reference contracts. Long-term viability hinges on capturing recurring revenue streams from edge computing and data analytics services rather than one-time hardware sales. The signal to watch is venue owner willingness to internalize network operations competencies versus outsource to managed service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Private Wireless Integration | Enables low-latency video replay and security orchestration in European football venues under ETSI mandates. |
| Edge Computing Deployment | Captures analytics margin pools from cloud providers by internalizing content delivery within stadium environments. |
| Managed Service Unbundling | Creates operational expenditure pathways for capital-constrained municipal venue owners in US markets. |
| Spectrum Certification Investment | Accelerates FCC Part 15 and ETSI EN 301 893 qualification timelines for 6 GHz Wi-Fi 6E hardware. |
| RF Engineering Talent Acquisition | Addresses skill scarcity in neutral-host architecture design and multi-operator coordination. |
Research Methodology
A standing panel of stadium technology directors, RF engineering consultants, venue procurement officers, and sports franchise IT executives provided ongoing calibration across primary interviews and secondary validation. Secondary sources encompassed FCC spectrum allocation filings, ETSI interoperability standards documentation, SEC 10-K disclosures from listed infrastructure vendors, and venue operator capital expenditure announcements. Bottom-up equipment shipment analysis and top-down venue modernization budget triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across technology generation, stakeholder procurement authority, application workflow, and service delivery model. CAGRs were derived from equipment replacement cycle compression and venue technology budget expansion trajectories. Forecast inputs incorporated FCC unlicensed band allocation timing and Bundesnetzagentur certification cycle extensions.
Forecasts assume regulatory continuity in FCC Part 15 rules and ETSI EN 301 893 frameworks; material policy shifts would require re-modeling. Revision becomes warranted when venue owner procurement model preferences cross thresholds toward in-house network operations competencies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
Retail Warehouse Management Systems Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
System Integration Market
Digital Solutions
Global Application Container Market