
 Enterprise Asset Management (EAM) Market | 2026-2036
Enterprise Asset Management (EAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Asset Management (EAM) Market Foresight
Cloud infrastructure is decoupling EAM software economics from traditional perpetual-license models. IBM Maximo leverages deep integration with industrial IoT protocols to anchor its position in heavy-asset sectors. SAP EAM sustains competitive density through embedded ERP connectivity that spans procurement and maintenance workflows. AVEVA EAM specializes in engineering-centric deployments where asset lifecycle data merges with design-origin documentation.
Enterprise Asset Management comprises integrated software systems that track physical asset performance, schedule preventive maintenance, and optimize total cost of ownership across operational lifecycles. Modern platforms incorporate digital twin architectures, real-time sensor ingestion, and predictive analytics engines that process equipment degradation signals before failure events occur. Cloud-based deployment leads segment expansion as utilities and manufacturers retire capital-intensive server footprints, while IoT-enabled technology layers capture the fastest growth trajectory by converting raw operational data into actionable maintenance triggers. Maintenance Management solutions occupy the deepest margin pools due to recurring service contracts and regulatory audit dependencies.
The EU CSRD and REACH frameworks impose granular asset-level emissions tracking that EAM platforms must support for market access. The US EPA and OSHA enforce equipment integrity standards that drive systematic inspection logging and corrective-action documentation within these systems. Japan's METI promotes smart factory standards that align with JIS-certified maintenance protocols. Stakeholders must monitor how AI governance requirements from the EU AI Act reshape algorithmic predictive maintenance certifications.
Market Dynamics
Cloud-native architectures are severing EAM economics from perpetual-license dependency, forcing incumbent vendors to rebuild revenue models around consumption-based pricing while utilities and manufacturers accelerate retirement of capital-intensive server footprints.
Growth Catalysts
- EU CSRD emissions mandates:Asset-level sustainability disclosure rules compel European utilities to replace legacy on-premise systems with platforms capable of granular carbon tracking and audit-ready documentation.
- Industrial IoT protocol maturation:OPC UA and MQTT standardization enables seamless sensor-to-software data pipelines that feed predictive maintenance algorithms in heavy manufacturing.
- Japan METI smart factory standards:JIS-certified maintenance protocols drive systematic digitization of asset lifecycle management among precision manufacturers.
Market Restraints
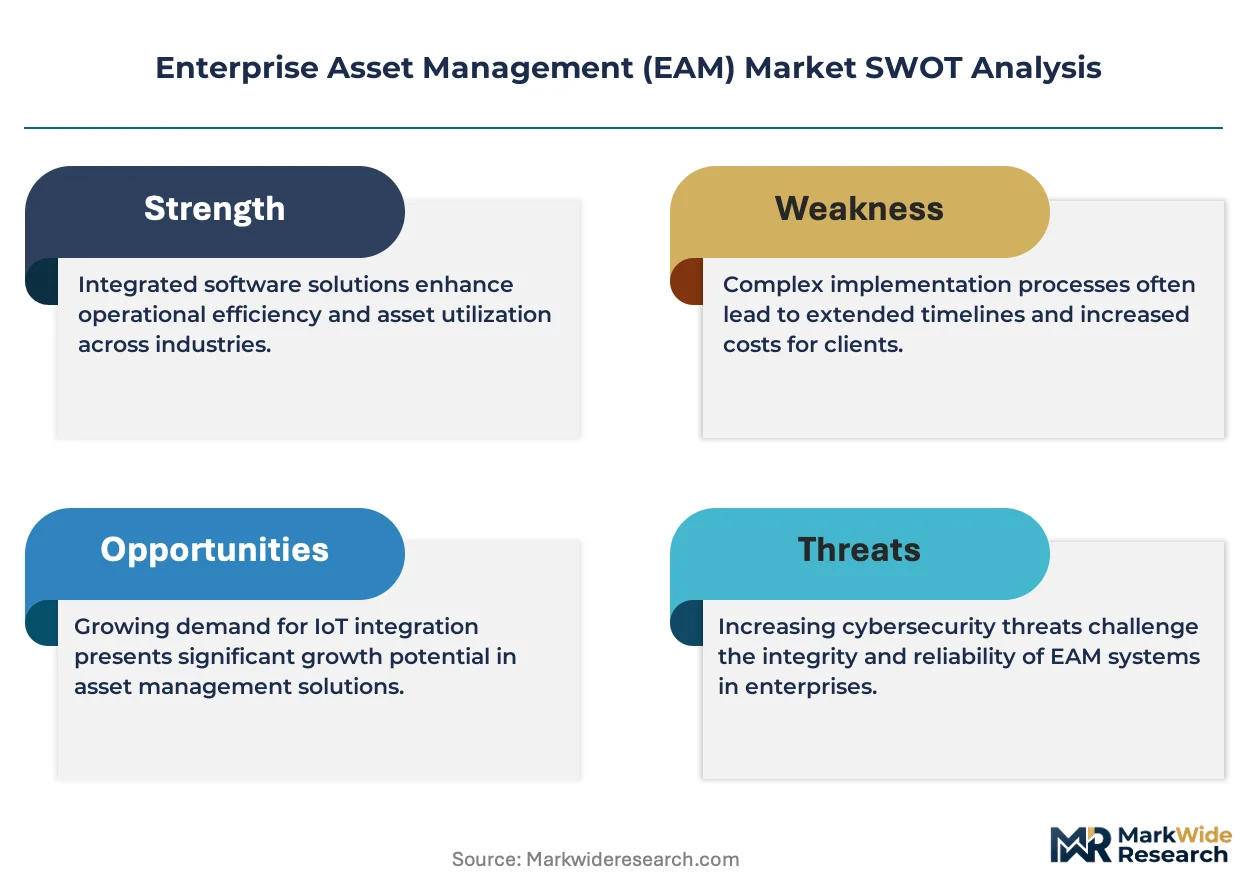
- Legacy system technical debt:Decades-old CMMS installations embed irreplaceable operational knowledge in undocumented configurations, creating migration friction that extends implementation timelines.
- Specialized workforce scarcity:Shortage of technicians proficient in both industrial equipment mechanics and cloud platform administration constrains deployment velocity.
- Data sovereignty fragmentation:Divergent national cloud residency requirements force vendors to maintain redundant infrastructure footprints, elevating operational complexity.
Strategic Opportunities
- Small-to-mid manufacturer underpenetration:Tier-two and tier-three industrial operators in Germany and Japan remain dependent on spreadsheet-based maintenance scheduling, presenting conversion potential.
- Digital twin convergence with EAM:Engineering simulation platforms merging with operational asset data create unified lifecycle visibility from design through decommissioning.
- US IRA clean energy incentives:Tax credits for grid modernization and renewable asset deployment accelerate utility investment in resilient, cloud-based management infrastructure.
Industry Challenges
- OT-IT integration complexity:Convergence of operational technology networks with enterprise IT systems exposes industrial control environments to cybersecurity vulnerabilities requiring segmented architecture redesign.
- Algorithmic maintenance certification gaps:Absence of standardized validation frameworks for AI-driven predictive models creates liability uncertainty when automated recommendations override human judgment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Asset Management (EAM) Market |
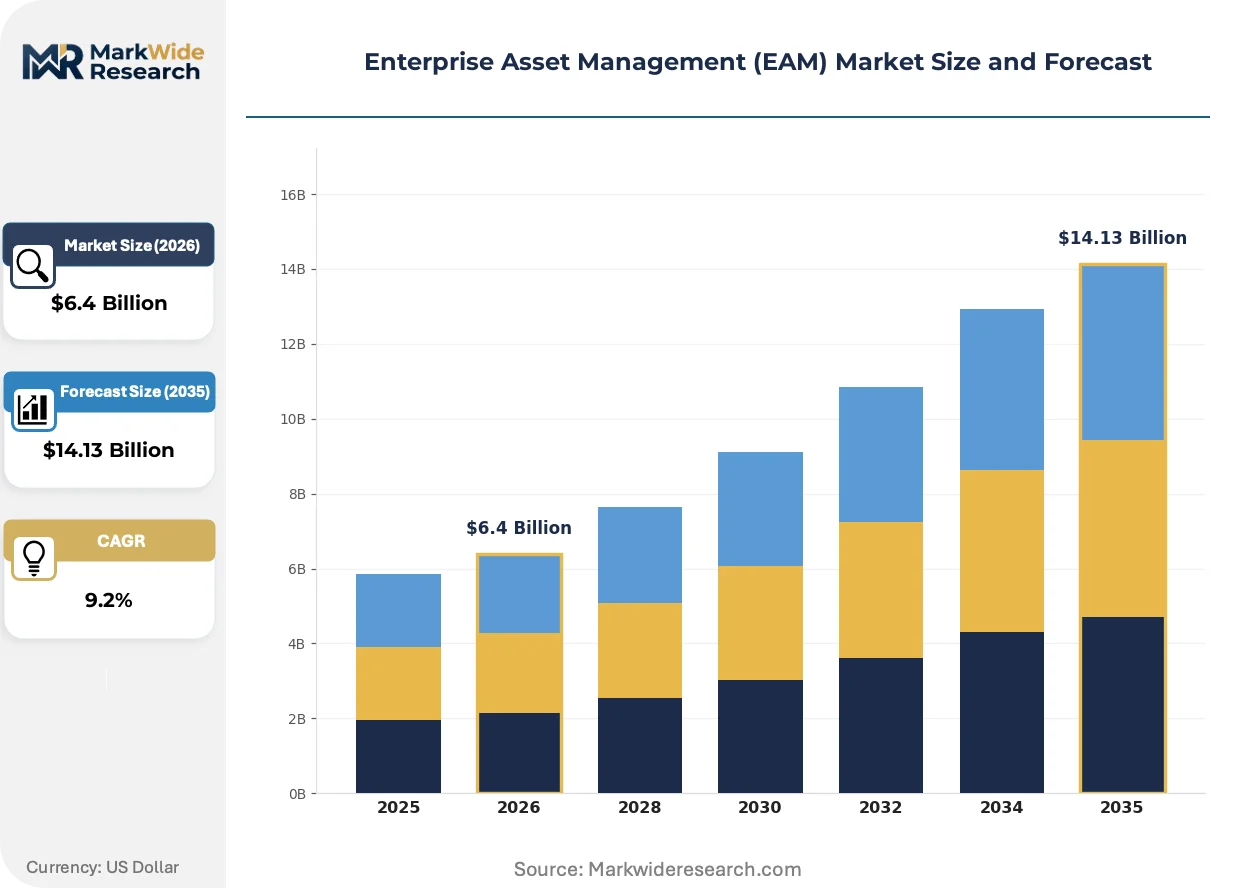
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $14.13 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Manufacturers, Utilities, Healthcare, Transportation Solution: Maintenance Management, Inventory Control, Asset Tracking, Procurement Technology: IoT, AI, Machine Learning, Big Data |
| Companies Covered | Oracle EAM Cloud, AVEVA EAM, IBM Maximo, AssetWorks, IFS Ultimo, SAP EAM, Dynamics 365 Business Central, ABB Lumada, Infor EAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Asset Management (EAM) Market Shifts & Advancements
Predictive capabilities are migrating from diagnostic dashboards to autonomous action triggers, compressing the interval between anomaly detection and maintenance intervention while reshaping how asset reliability teams structure workflows.
Digital twin technology is integrating physics-based simulation with real-time operational data streams to generate degradation forecasts that anticipate equipment failure weeks before traditional threshold alerts trigger. Power utilities in the United States and Germany are deploying these capabilities at scale, embedding predictive models directly into work order generation systems that automatically schedule technician dispatch and spare parts procurement. This convergence is compressing maintenance planning cycles from quarterly to continuous, forcing organizational restructuring around data science competencies.
REACH and EU CSRD disclosure frameworks mandate asset-level chemical inventory tracking and emissions documentation that EAM platforms must support for continued market access in Europe. Industrial manufacturers face expanded audit obligations requiring immutable maintenance logs that trace every spare part origin and disposal pathway. Chemical processing and energy generation facilities bear the heaviest compliance burden, investing in blockchain-anchored recordkeeping to satisfy regulator evidentiary standards.
Subscription pricing models are displacing perpetual licenses across mid-market manufacturing buyers who prioritize operational expenditure predictability over capital ownership. Channel partners in Japan and the United States are restructuring compensation around customer lifetime value metrics rather than upfront license margins, aligning vendor and buyer incentives around implementation success and user adoption rates. This shift concentrates competitive advantage on vendors with demonstrable onboarding velocity and training infrastructure depth.
Enterprise Asset Management (EAM) Market Segmentation
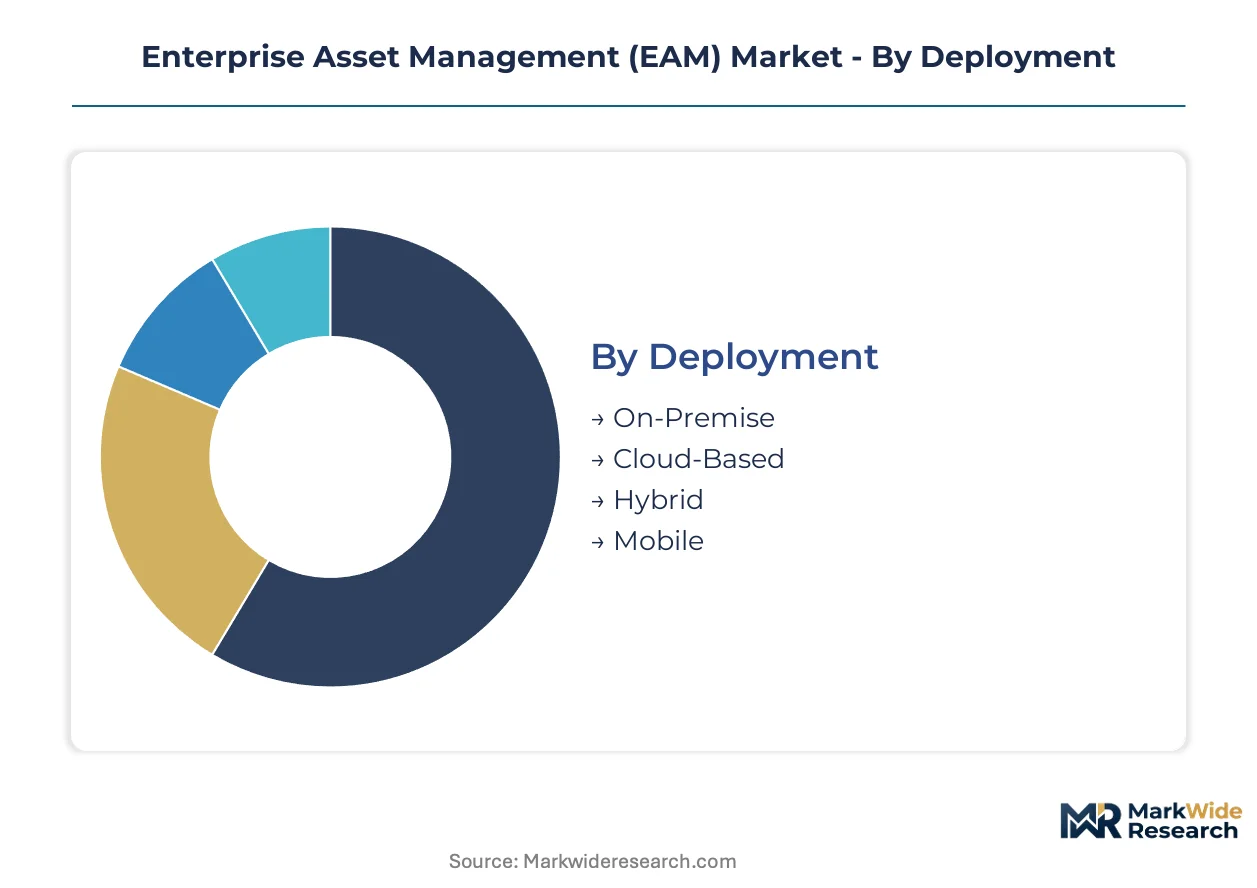
Deployment architecture determines total cost of ownership and compliance readiness for EAM buyers. Solution specialization separates recurring revenue platforms from transactional software sales. Technology layers differentiate predictive capabilities from basic record-keeping functionality.
Deployment:
IT capital allocation preferences now pivot on subscription predictability versus infrastructure control.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance burdens while enabling automatic regulatory updates for CSRD emissions tracking. German utilities and US manufacturers prioritize these platforms to satisfy audit documentation mandates without dedicated security staff.
- On-Premise:Air-gapped installations persist in defense and nuclear sectors where data sovereignty requirements override cost considerations. Japanese precision manufacturers maintain these configurations to satisfy JIS-certified maintenance protocol verification.
- Hybrid:Sensitive operational data remains local while analytics workloads shift to cloud infrastructure. Chemical processors in the United States deploy this model to balance EPA inspection readiness with computational scalability.
- Mobile:Field technician applications synchronize work orders and sensor alerts across distributed asset networks. Transportation fleet operators leverage these capabilities for roadside maintenance dispatch.
Volume sits with Cloud-Based platforms; growth tilts toward Hybrid configurations bridging legacy and modern infrastructure.
End User:
Asset intensity and regulatory exposure shape procurement priorities across vertical markets.
- Utilities:Grid infrastructure modernization programs demand platforms integrating SCADA data streams with predictive degradation models. US power providers facing FERC reliability standards invest heavily in these capabilities.
- Manufacturers:Smart factory initiatives in Japan and Germany require seamless connectivity between production equipment and maintenance scheduling systems.
- Healthcare:Medical device calibration tracking and Joint Commission audit documentation drive specialized compliance modules.
- Transportation:Fleet availability metrics and DOT inspection logging prioritize mobile-first work order management.
Manufacturers generate the deepest installation base; utilities command the steepest expansion trajectory as renewable asset portfolios multiply.
Solution:
Functional depth correlates directly with customer lifetime value and switching costs.
- Maintenance Management:Preventive scheduling algorithms and technician dispatch optimization form the core revenue engine. Recurring service contracts and regulatory audit dependencies sustain margin pools above other solution categories.
- Inventory Control:Spare parts availability forecasting minimizes production downtime through predictive stocking algorithms.
- Asset Tracking:Real-time location monitoring and utilization analytics support capital planning decisions.
- Procurement:Supplier performance scoring and contract lifecycle management integrate with ERP financial workflows.
Maintenance Management anchors current revenue; Inventory Control gains share fastest as supply chain resilience priorities intensify.
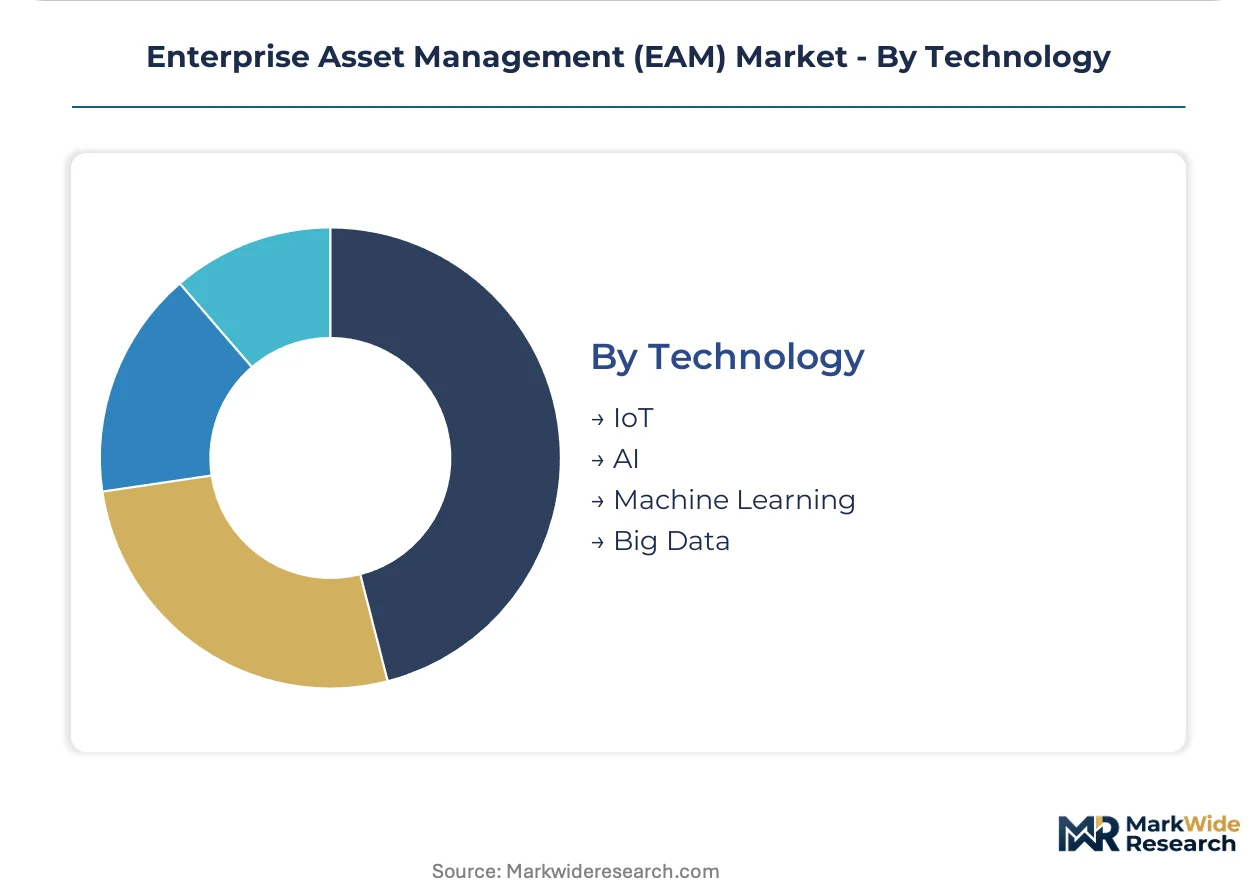
Technology:
Algorithmic sophistication separates premium platform tiers from commodity record-keeping tools.
- IoT:OPC UA and MQTT protocol standardization enables seamless sensor-to-software pipelines. Industrial equipment in German manufacturing facilities generates the densest data streams feeding these architectures.
- AI:Pattern recognition engines process vibration, thermal, and acoustic signatures to flag degradation before threshold breaches.
- Machine Learning:Continuous model refinement improves failure prediction accuracy as operational datasets accumulate.
- Big Data:Distributed storage and query infrastructure supports cross-facility benchmarking and historical trend analysis.
IoT installations dominate current deployment volume; AI capabilities are climbing the fastest as automated maintenance recommendations displace human diagnostic workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility infrastructure modernization and smart factory mandates concentrate EAM procurement across the United States, Germany, Japan, and select industrial clusters in China and the United Kingdom. Regulatory disclosure requirements and operational resilience standards reshape deployment priorities in each geography.
United States
Grid modernization programs and renewable asset expansion drive utility sector investment. FERC reliability standards compel systematic inspection logging and predictive maintenance adoption. Texas and California utilities deploy cloud-native platforms to manage distributed generation portfolios.
Germany
Industrial digitization initiatives and chemical processing compliance burdens sustain platform demand. EU CSRD emissions disclosure rules mandate granular asset-level carbon tracking. The Ruhr industrial corridor and Bavarian manufacturing clusters lead predictive analytics deployment.
Japan
Precision manufacturing and smart factory standards accelerate lifecycle management digitization. METI JIS-certified maintenance protocols require systematic documentation infrastructure. The Chubu region around Nagoya anchors automotive and machinery sector adoption.
China
State-owned enterprise reform and industrial IoT integration reshape maintenance management practices. Dual carbon goals impose energy efficiency tracking requirements on heavy industry. Yangtze River Delta manufacturing hubs pilot digital twin convergence with operational asset data.
United Kingdom
Energy network decarbonization and offshore wind expansion create asset management complexity. HSE equipment integrity enforcement drives systematic corrective-action documentation. Scottish renewable clusters and Midlands manufacturing bases concentrate platform deployment.
Enterprise Asset Management (EAM) Market Competitive Landscape
Strategic partnerships and cloud migration services dominate the current landscape as vendors reposition around subscription economics. The vendor base clusters into three tiers: ERP-integrated suites with embedded maintenance modules, standalone EAM specialists with deep industrial protocol expertise, and emerging cloud-native challengers targeting mid-market displacement. Incumbents defend position through vertical solution bundles while challengers exploit API-first architectures to bypass legacy migration friction. Technology licensing and geographic expansion represent the two prevailing competitive vectors.
Within the ERP-integrated tier, SAP EAM and Oracle EAM Cloud occupy positions anchored by procurement and financial workflow connectivity. IBM Maximo exemplifies the industrial specialist archetype with heavy-asset sector concentration. AVEVA EAM sits within the engineering-centric segment where design-origin documentation merges with operational lifecycle data.
| Leading Market Players |
|---|
| Oracle EAM Cloud |
| AVEVA EAM |
| IBM Maximo |
| AssetWorks |
| IFS Ultimo |
| SAP EAM |
| Dynamics 365 Business Central |
| ABB Lumada |
| Infor EAM |
| Others |
Supply & Pricing Matrix
Utility procurement concentration in the United States and Germany anchors subscription-based SaaS pricing as the dominant commercial model, with cloud-native vendors capturing recurring revenue streams from grid modernization programs.
Pricing Analysis
Volume concentrates in mid-tier SaaS subscriptions while margin pools sit with premium predictive analytics bundles. Price differentiation rests on IoT protocol depth and CSRD compliance certification tier. Cost compression in the mid-market intensifies as spreadsheet-dependent manufacturers migrate to cloud platforms. Tier-two industrial operators in Japan exhibit highest price sensitivity; utilities facing FERC reliability mandates show lowest.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gates restrict vendor qualification, concentrating platform development talent in the United States, Germany, and India. Cloud infrastructure draws from hyperscaler networks in Virginia, Frankfurt, and Singapore. Single-source vulnerability in OPC UA protocol licensing elevates supply risk. Distribution runs through systems integrators and vertical channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud platform development talent scarcity props pricing power for established vendors, constraining rapid market entry by undercapitalized challengers.
For Market Incumbents: Acquire predictive analytics engineering teams to deepen AI maintenance capabilities. SAP and IBM must secure OPC UA protocol expertise before IoT-native challengers erode industrial connectivity advantages. Backward integration into sensor hardware partnerships tightens platform control. For New Entrants and Emerging Players: API-first architectures targeting mid-market German manufacturers offer the most penetrable white-space. JIS-certified maintenance protocol gaps in tier-three Japanese automotive suppliers present conversion opportunities. Freemium field-technician mobile apps accelerate land-and-expand cycles. For Investors and Strategic Acquirers: The window for entry favors cloud-native specialists with proven CSRD compliance modules. Long-term viability hinges on recurring revenue concentration above seventy percent. Watch for EU AI Act algorithmic certification requirements as inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP connectivity with SAP and Oracle procurement workflows locks in enterprise buyers. |
| Acquisition of Specialist Firm | Predictive maintenance startups with OPC UA expertise fill industrial protocol gaps. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure accelerate multi-tenant deployment velocity. |
| Geographic Expansion | Chubu region presence captures METI smart factory standard compliance requirements. |
| Product Launch | CSRD-ready emissions tracking modules satisfy EU audit documentation mandates. |
Research Methodology
Document review covered vendor SEC filings, EU regulatory guidance, and IoT protocol standards documentation, complemented by interviews with maintenance directors at US utilities, plant engineers in German manufacturing clusters, and channel partners in Japan. Primary fieldwork included discussions with EAM implementation specialists and cloud platform procurement officers. Secondary validation drew from FERC reliability reports, METI smart factory guidelines, and EIA grid modernization data. Bottom-up deployment estimates triangulated against top-down market sizing.
Cross-referencing historical adoption curves with expert panel input shaped the projection framework. Segmentation dimensions modeled include deployment architecture, solution functional depth, end-user vertical, and technology layer sophistication. CAGRs derived from trend extrapolation anchored in utility infrastructure investment cycles and manufacturing digitization program timelines. Forecast inputs incorporated renewable asset portfolio growth rates and predictive maintenance algorithm maturity curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged OT-IT integration delays. Model assumptions reflect documented regulatory trajectories and vendor disclosed implementation timelines. A model refresh is warranted upon material change in CSRD audit requirement granularity or hyperscaler data residency policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Kenya ICT Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Location As a Service Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Container Management Software Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Global Digital Art Software Market