
 Incidence Management Software Market | 2026-2036
Incidence Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Incidence Management Software Market Foresight
North American SaaS infrastructure investment is shifting toward integrated incident response stacks. ServiceNow leverages its enterprise workflow dominance to anchor multi-tenant deployments across Fortune 500 accounts. PagerDuty competes through specialized on-call orchestration tools that sustain developer-centric market penetration. BigPanda differentiates via AI-driven event correlation that reduces mean time to resolution for complex cloud architectures.
Incidence Management Software constitutes a digital operations platform that automates detection, triage, communication, and post-incident analysis of service disruptions, typically integrating with monitoring telemetry APIs and IT service management databases to maintain system reliability. Cloud-based deployment leads product type adoption due to elastic scalability and reduced infrastructure overhead, while on-premises solutions retain share in government agencies with data sovereignty constraints. Incident Reporting dominates application-level demand as regulated industries mandate documented accountability chains, whereas Workflow Automation captures expanding margin pools through subscription-based orchestration layers.
FDA 21 CFR Part 11 requirements shape healthcare provider software validation protocols, while HIPAA security rules mandate encrypted audit trails for incident data handling in the United States. The EU AI Act imposes risk classification obligations on automated incident triage systems deployed across European member states. Stakeholders must monitor evolving cross-border data localization mandates that threaten multi-tenant architecture viability in selective jurisdictions.
Market Dynamics
Cloud-native incident response architectures are compressing deployment timelines and forcing legacy on-premise vendors to restructure pricing models around consumption-based metering. HIPAA and EU AI Act compliance mandates now function as gatekeepers for market entry rather than post-hoc checklists.
Growth Catalysts
- EU AI Act risk classification:Automated triage systems deployed across European member states must meet strict algorithmic accountability standards, creating certified vendor preference effects.
- Healthcare patient safety mandates:FDA 21 CFR Part 11 validation protocols compel hospital systems to replace paper-based incident logs with encrypted digital audit trails.
- Germany cloud infrastructure expansion:Elastic scalability requirements in Frankfurt and Munich data corridors accelerate multi-tenant SaaS adoption over fixed-capacity on-premise licensing.
Market Restraints
- Cross-border data localization:Selective jurisdictions threaten multi-tenant architecture viability through residency requirements that fragment operational scale.
- Specialized DevOps talent scarcity:Event correlation engineering and SRE automation skills command premium compensation that inflates implementation costs.
- Legacy ITSM integration friction:ServiceNow and BMC Remedy incumbent positions create switching costs that delay competitive displacement cycles.
Strategic Opportunities
- Japan METI digital resilience guidelines:Manufacturing and critical infrastructure sectors face new operational continuity mandates that expand addressable market for predictive incident platforms.
- Workflow Automation convergence:Orchestration layers that bridge incident detection with automated remediation capture expanding subscription margin pools.
- United Kingdom NHS digital transformation:National patient safety reporting standardization creates centralized procurement pathways for compliant SaaS vendors.
Industry Challenges
- ISO 27001 certification timelines:Healthcare and financial services buyers demand current attestations that extend sales cycles by 6-12 months for emerging vendors.
- API standardization gaps:Monitoring telemetry integration requires custom development work for each observability stack, compressing gross margins on professional services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incidence Management Software Market |
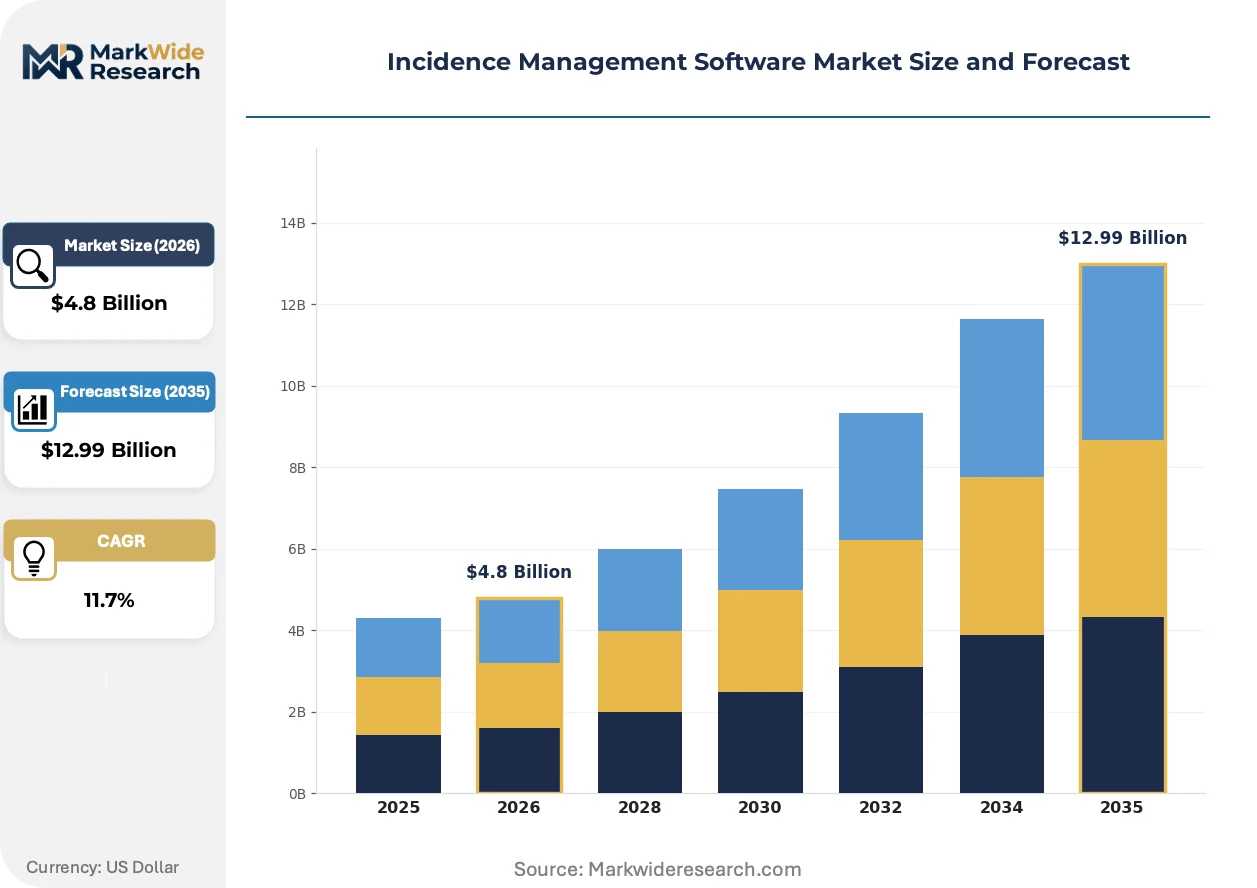
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile End User: Healthcare Providers, Educational Institutions, Government Agencies, Corporations Deployment: Single-Tenant, Multi-Tenant, Enterprise, Small Business Application: Incident Reporting, Risk Management, Workflow Automation, Compliance Tracking |
| Companies Covered | Splunk Oncall, BigPanda, PagerDuty, Datadog Oncall, xMatters, ServiceNow, incident.io, New Relic, Atlassian Opsgenie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incidence Management Software Market Shifts & Advancements
Artificial intelligence is compressing mean-time-to-resolution through real-time event correlation that replaces manual triage queues. Regulatory pressure on algorithmic accountability is reshaping vendor development priorities. Buyer procurement patterns are shifting toward integrated response stacks that consolidate fragmented point solutions.
AI-driven event correlation engines are unifying telemetry streams from cloud monitoring, security operations, and business application layers into single-pane incident contexts. Large enterprises with complex microservice architectures are adopting these platforms at accelerated procurement cycles. This unification is compressing the addressable market for standalone alerting tools by folding their functionality into broader operational intelligence suites.
REACH chemical safety reporting extensions in the European Union now mandate digital incident documentation for supply chain disruptions involving hazardous materials. Industrial manufacturers must integrate these requirements into existing EHS software or face enforcement penalties. German chemical producers and their downstream customers are responding by consolidating incident management with environmental compliance systems under unified vendor contracts.
Hospital procurement committees now require demonstration of HIPAA Business Associate Agreement execution before pilot authorization, replacing previous post-contract compliance verification. This behavioral shift elongates vendor qualification timelines but reduces downstream legal exposure for covered entities. United States health systems in Texas, California, and New York exhibit the strictest pre-engagement documentation requirements.
Incidence Management Software Market Segmentation
Incidence Management Software segments reflect divergent integration architectures. Some categories operate as embedded modules within enterprise suites; others demand standalone procurement with custom API development.
Product Type:
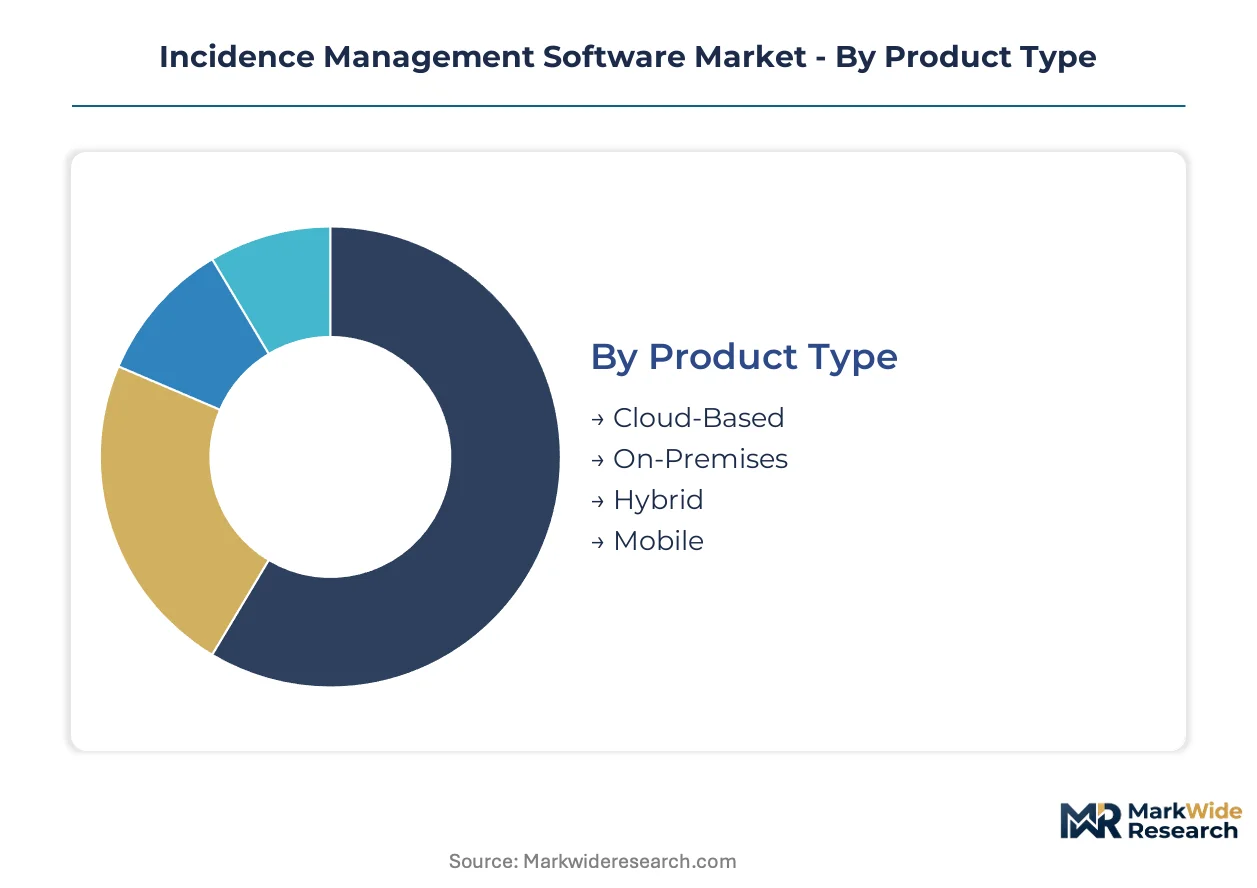
Integration depth varies sharply: Cloud-Based and Hybrid solutions embed natively into existing SaaS stacks, while On-Premises and Mobile often require standalone deployment with middleware layers.
- Cloud-Based:Elastic infrastructure provisions compute on demand through browser-accessible dashboards. Hospital systems in Texas and California concentrate procurement here, driven by HIPAA Business Associate Agreement pre-verification requirements that favor established SaaS vendors with current attestations.
- On-Premises:Fixed-capacity licensing deploys within client data centers with full hardware control. German government agencies and defense contractors mandate this architecture to satisfy data sovereignty constraints under national cybersecurity frameworks.
- Hybrid:Split architectures synchronize sensitive operations on-premise with analytics workloads in cloud environments.
- Mobile:Native iOS and Android applications extend incident capture to field personnel without continuous connectivity.
Cloud-Based leads volumes today; Hybrid is gaining share fastest.
End User:
Customer procurement maturity creates tiered margin structures. Healthcare and Government segments demand extended certification cycles; Corporate and Educational buyers compress vendor selection timelines.
- Healthcare Providers:Hospital networks and outpatient clinics deploy incident reporting modules to satisfy FDA 21 CFR Part 11 validation protocols. The United Kingdom NHS digital transformation creates centralized procurement pathways for compliant SaaS vendors serving acute care facilities.
- Government Agencies:Federal, state, and municipal entities require FedRAMP or equivalent security attestations. Japanese METI digital resilience guidelines are expanding addressable market for predictive incident platforms across manufacturing and critical infrastructure sectors.
- Corporations:Fortune 500 enterprises integrate incident response with IT service management databases through pre-built connectors.
- Educational Institutions:Universities and K-12 districts prioritize cost-efficient multi-tenant deployments with limited customization.
Healthcare Providers anchor revenue concentration; Government Agencies show steepest expansion trajectory.
Deployment:
Architecture tenancy determines operational scale economics. Multi-Tenant configurations maximize margin through shared infrastructure; Single-Tenant and Enterprise deployments sacrifice efficiency for isolation guarantees.
- Multi-Tenant:Shared infrastructure partitions logical instances across customer organizations without physical separation. Frankfurt and Munich data corridors accelerate adoption here, as German cloud infrastructure expansion favors elastic scalability over fixed-capacity licensing.
- Enterprise:Dedicated resource allocation with custom service level agreements supports complex microservice architectures. Large manufacturers with REACH chemical safety reporting obligations in the European Union select this tier to unify incident management with environmental compliance systems.
- Single-Tenant:Physically isolated environments serve clients with regulatory prohibitions on data commingling.
- Small Business:Standardized configurations with minimal professional services reduce total cost of ownership.
Multi-Tenant dominates current installations; Enterprise climbs the fastest among new deployments.
Application:
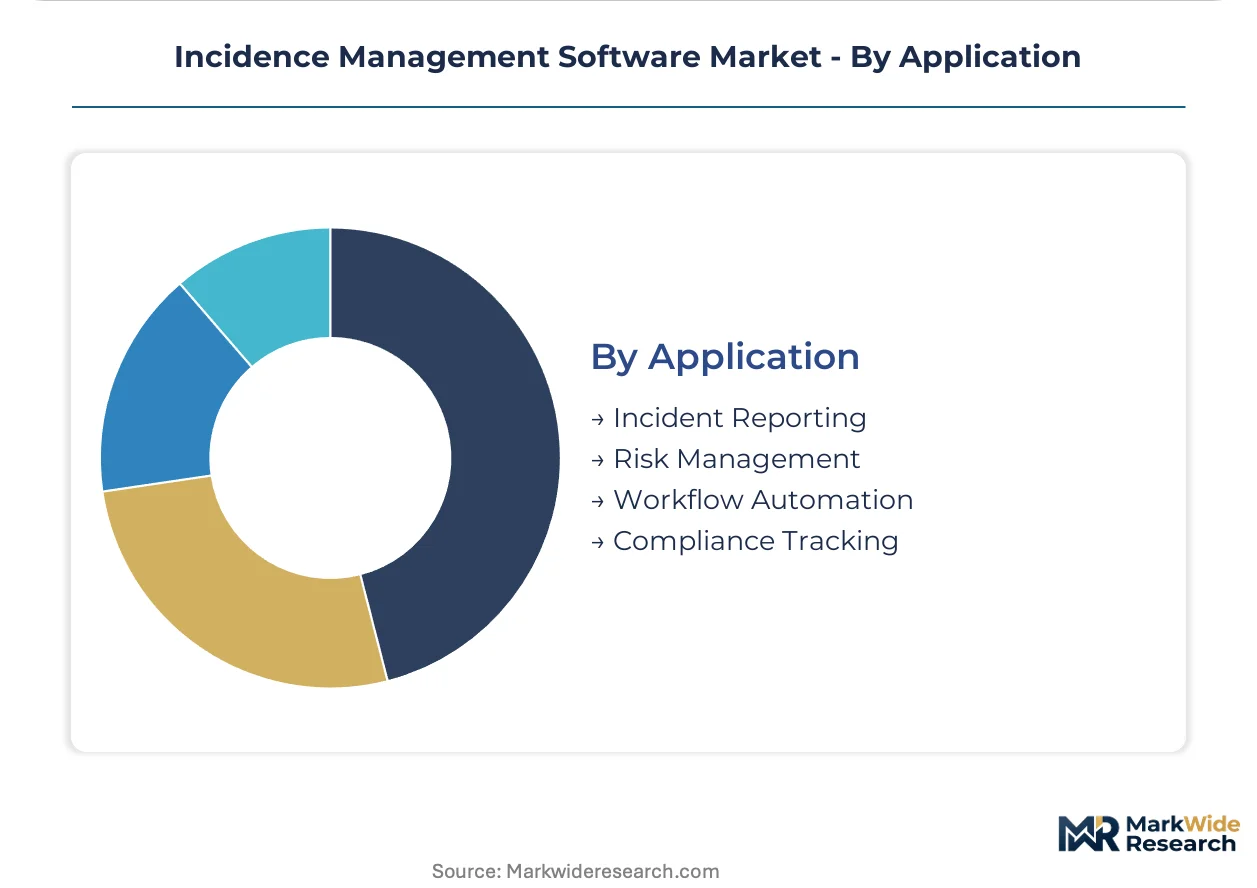
Functional modules map to distinct buyer workflows. Incident Reporting and Compliance Tracking serve audit-driven procurement; Workflow Automation and Risk Management compete for operational efficiency budgets.
- Incident Reporting:Structured capture, classification, and documentation of service disruptions with encrypted audit trails. United States health systems in New York exhibit strictest pre-engagement documentation requirements here, replacing post-contract compliance verification with pre-pilot HIPAA Business Associate Agreement execution.
- Workflow Automation:Orchestration layers bridge incident detection with automated remediation actions. Subscription-based pricing captures expanding margin pools as DevOps teams demand event correlation engineering and SRE automation capabilities.
- Risk Management:Predictive scoring and mitigation planning for operational and regulatory exposures.
- Compliance Tracking:Continuous monitoring against EU AI Act risk classification standards and industry-specific mandates.
Incident Reporting leads current procurement volumes; Workflow Automation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor certification priorities as compliance cost differentials drive SaaS infrastructure investment toward jurisdictions with harmonized standards. Cloud-based deployments concentrate where data localization mandates remain permissive.
United States
Hospital networks in Texas and California are expanding encrypted digital audit trails to satisfy HIPAA security rules and FDA 21 CFR Part 11 validation protocols. Federal procurement committees now require FedRAMP attestations before pilot authorization. The New York metropolitan corridor exhibits the strictest pre-engagement documentation requirements for Business Associate Agreement execution.
Germany
Frankfurt and Munich data corridors are accelerating multi-tenant SaaS adoption as chemical manufacturers integrate REACH reporting obligations with incident management systems. National cybersecurity frameworks mandate data sovereignty constraints that preserve on-premises licensing in defense contracting. Bavaria-based government agencies anchor demand for fixed-capacity deployment architectures.
United Kingdom
The NHS digital transformation is creating centralized procurement pathways for compliant SaaS vendors serving acute care facilities. London-based health systems are replacing paper-based incident logs with structured digital capture modules. National patient safety reporting standardization is compressing vendor selection timelines for workflow automation layers.
Japan
Manufacturing clusters in the Nagoya-Chubu corridor are adopting predictive incident platforms to satisfy METI digital resilience guidelines for operational continuity. Osaka-based critical infrastructure operators are expanding automated triage system deployments. Tokyo health systems are integrating incident response with IT service management databases through pre-built connectors.
India
Bangalore and Hyderabad technology corridors are driving demand for event correlation engineering capabilities as offshore development centers adopt SRE automation. Mumbai-based financial services buyers are demanding ISO 27001 certifications that extend sales cycles for emerging vendors. National cloud infrastructure expansion is favoring elastic scalability over legacy fixed-capacity licensing models.
Incidence Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized orchestration niches and AI-driven correlation layers. The vendor base clusters around three maturity tiers: enterprise workflow incumbents with pre-built ITSM connectors, developer-centric alerting specialists, and cloud-native intelligence platforms. Dominant competitive moves include M&A activity targeting event correlation capabilities and strategic partnerships with observability stack providers to compress integration timelines.
Within the enterprise workflow tier, ServiceNow anchors multi-tenant deployments across Fortune 500 accounts through IT service management database integration. PagerDuty and BigPanda exemplify contrasting specialization strategies—on-call orchestration tooling versus AI-driven event correlation for complex microservice architectures. These three entities represent the dominant archetypes competing for subscription margin pools in automated remediation and mean-time-to-resolution compression.
| Leading Market Players |
|---|
| Splunk Oncall |
| BigPanda |
| PagerDuty |
| Datadog Oncall |
| xMatters |
| ServiceNow |
| incident.io |
| New Relic |
| Atlassian Opsgenie |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FedRAMP-authorized enterprise tiers and uncertified mid-market offerings manifests in both subscription pricing and cloud infrastructure sourcing strategies. HIPAA-eligible deployments command premium SaaS rates through dedicated compliance engineering, while uncertified alternatives compete on raw compute economics anchored to spot-priced hyperscaler capacity.
Pricing Analysis
Direct-to-enterprise discounts dominate channel economics, with Fortune 500 procurement committees extracting volume-based concessions from multi-tenant SaaS vendors. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by compliance certification depth and event correlation sophistication. Cost compression in the mid-market tier intensifies because hyperscaler reserved-instance arbitrage erodes vendor margin buffers. Educational institutions exhibit highest price sensitivity, while United States hospital networks prioritize HIPAA Business Associate Agreement execution over per-seat economics.
Supply Chain Analysis
Freight costs for on-premises hardware deployments into German government data centers inflate total ownership economics against cloud-native alternatives. Software supply concentrates in the United States, Ireland, and Germany, with hyperscaler regions in Frankfurt, Virginia, and Dublin anchoring elastic capacity. Raw material dependencies span silicon for AI inference chips, lithium for uninterruptible power systems, and rare earth elements for server-grade magnetics. Single-source vulnerability in NVIDIA GPU supply for event correlation engines threatens deployment timelines. Distribution runs through hyperscaler marketplaces and direct vendor sales organizations with professional services bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between United States compliance premiums and European operational continuity mandates, with EU AI Act certification costs running substantially below parallel FDA validation pathways for equivalent risk classifications.
For Market Incumbents: Acquire event correlation engineering teams to neutralize cloud-native intelligence platform encroachment. Fortify multi-tenant architecture isolation guarantees against single-tenant competitive displacement in German defense contracting. Deepen backward integration into observability stack API development to compress professional services margin erosion from telemetry integration friction. For New Entrants and Emerging Players: Cloud marketplace distribution routes offer lowest-friction customer acquisition for workflow automation modules targeting mid-market manufacturing clusters. Japan METI digital resilience guidelines create the most penetrable regulatory entry point, with predictive incident platforms for Nagoya-Chubu manufacturing corridors facing limited incumbent saturation. Position through SRE automation capability demonstrations rather than comprehensive platform replacement pitches. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 27001 certification timelines extend sales cycles beyond 12 months, favoring acquirers with existing attestation portfolios. Long-term viability hinges on AI-driven mean-time-to-resolution compression as standalone alerting functionality commoditizes. Target acquisition archetype: cloud-native intelligence platforms with pre-built ServiceNow connectors. Signal to watch: hospital procurement committee standardization on pre-pilot HIPAA Business Associate Agreement execution as inflection toward certified-vendor preference.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies incident detection with ServiceNow ITSM databases for Fortune 500 workflow consolidation. |
| Acquisition of Specialist Firm | Captures event correlation engineering talent scarce in Bangalore and Hyderabad technology corridors. |
| Geographic Expansion | Establishes Frankfurt data corridor presence to satisfy German chemical manufacturer REACH integration requirements. |
| Strategic Partnership | Compresses API standardization gaps through pre-built observability stack connectors with Datadog and New Relic. |
| Product Launch | Introduces predictive incident platforms aligned with Japan METI digital resilience guidelines for manufacturing continuity. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with CTOs, IT procurement officers, platform engineers, and hospital purchasing committees alongside secondary validation. Primary fieldwork drew from SEC filings, hyperscaler capex disclosures, App Annie mobility data, and NHS procurement databases. Bottom-up deployment modeling triangulated against top-down regulatory mandate analysis across FDA, EU AI Act, and METI frameworks.
Granularity-level framing applied organization size, deployment model, vertical industry, and integration complexity dimensions at the segment level across the analysis window. CAGRs derived from elasticity-adjusted adoption curves reflecting HIPAA compliance deadline clustering and EU AI Act enforcement phase transitions. Forecast inputs incorporated cloud infrastructure expansion rates in Frankfurt and Munich data corridors alongside SRE automation talent supply constraints in Indian technology corridors.
The model assumes a particular technology adoption path; alternative pathways for AI-driven event correlation would alter the outlook if algorithmic accountability standards tighten beyond current EU AI Act risk classification thresholds. Forecasts reflect documented assumptions about certification timeline compression and hyperscaler pricing stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Social Networking App Market
Digital Solutions
Online Home Service Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
Marketing Automation Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Construction Design App Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Digital Library Software Market
Digital Solutions
North America API Management Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Global Space Planning Software Market