
 Cloud Monetization Market | 2026-2036
Cloud Monetization Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Monetization Market Outlook
Telecommunications is broadening its share of cloud monetization deployments as carriers replace legacy billing with real-time usage engines. Microsoft Corporation leverages its Azure-native integration to anchor enterprise accounts across hybrid environments. Amazon Web Services sustains dominance in metered infrastructure billing through deep API control over compute and storage consumption. Zuora Inc. specializes in subscription orchestration for B2B SaaS vendors seeking to unify recurring and consumption models.
Cloud monetization encompasses the platforms, pricing engines, and billing infrastructure that translate resource consumption into revenue events across distributed computing environments. These systems process telemetry streams from virtualized infrastructure, apply contractual rate cards, and generate invoicing data with sub-hour latency for enterprise finance operations. The deployment model dimension shows hybrid cloud configurations capturing the strongest margin pools as customers demand on-premise data sovereignty paired with elastic burst capacity. Public cloud billing systems lead in transaction volume but face compression from commodity API management layers. SME customer types represent the fastest expansion vector as vertical SaaS vendors embed pre-configured monetization modules.
The US Federal Trade Commission scrutinizes auto-renewal transparency in subscription software, compelling vendors to build granular consent workflows into billing interfaces. The EU AI Act and GDPR jointly shape data residency requirements for monetization analytics, restricting cross-border processing of usage telemetry without explicit legal basis. Stakeholders must monitor how fragmented national digital services taxation regimes alter pricing architecture and compliance cost allocation across customer geographies.
Market Dynamics
Real-time usage metering is compressing billing cycles from monthly to sub-hour intervals, forcing vendors to rebuild revenue recognition engines around event-stream architectures rather than batch processing systems.
Growth Catalysts
- GDPR Article 30:European data processing records mandate granular audit trails, driving demand for monetization platforms with embedded compliance telemetry.
- Telecommunications carriers:5G network slicing requires dynamic rate application per slice, accelerating replacement of legacy postpaid billing with real-time engines.
- Hybrid cloud configurations:Enterprise demand for data sovereignty paired with elastic burst capacity creates margin-rich deployment scenarios for metering infrastructure.
Market Restraints
- API commoditization:Public cloud billing systems face margin compression as standardized metering interfaces become undifferentiated infrastructure.
- Fragmented taxation regimes:National digital services taxes in France, Italy, and Spain force vendors to maintain parallel pricing architectures per jurisdiction.
- Cross-border data friction:GDPR Chapter V restrictions on usage telemetry transfer without adequacy decisions limit analytics centralization for multinational deployments.
Strategic Opportunities
- India's PLI scheme:Domestic cloud infrastructure incentives position the country as a captive monetization stack market for SaaS vendors targeting regulated sectors.
- Edge computing convergence:Distributed metering nodes combined with 5G MEC create new pricing models for latency-sensitive industrial applications.
- SME vertical SaaS:Pre-configured monetization modules embedded in industry-specific software open underpenetrated customer tiers.
Industry Challenges
- Revenue recognition automation:ASC 606 and IFRS 15 compliance for usage-based contracts demands specialized accounting-engineering talent scarce in most vendor organizations.
- Legacy ERP integration:SAP and Oracle financial systems require custom middleware development, extending implementation timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Monetization Market |
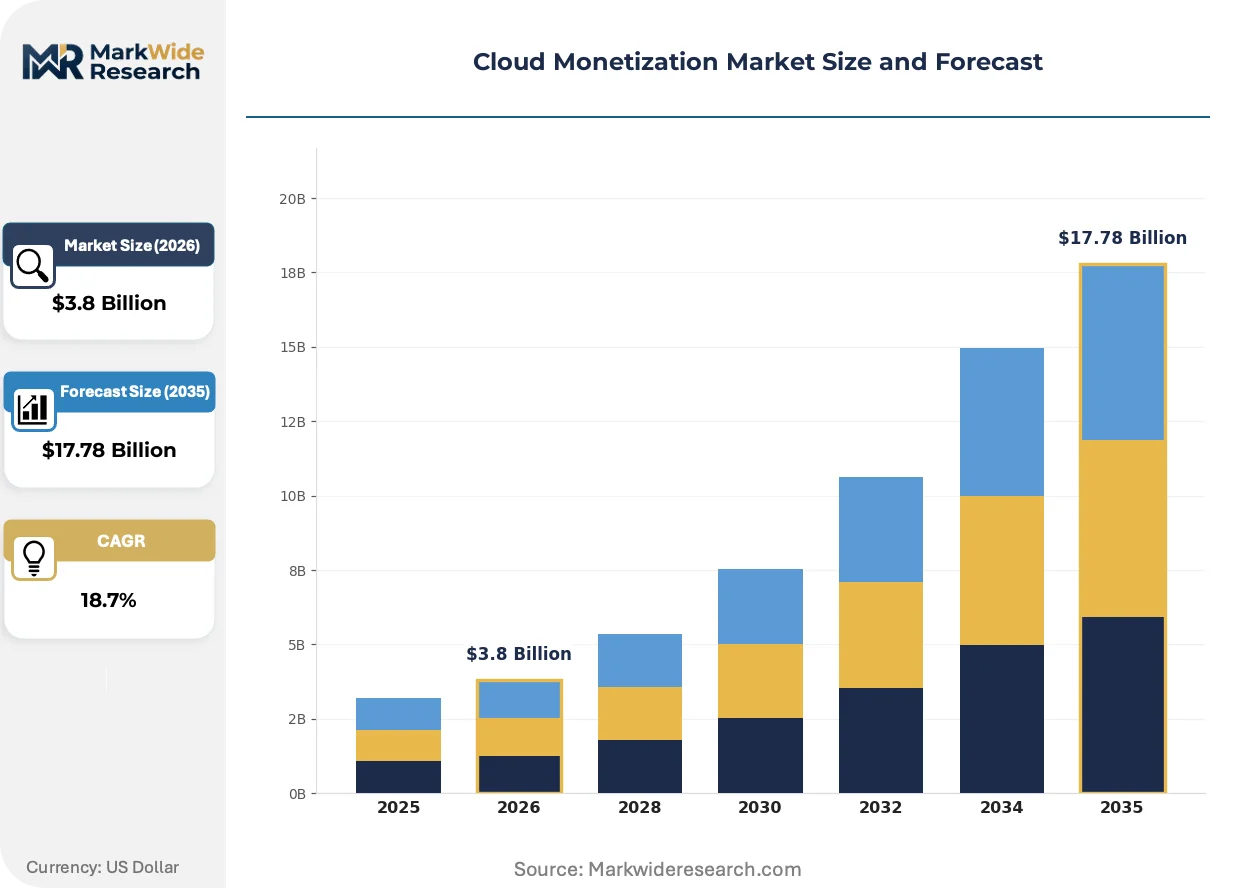
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Pay-As-You-Go, Tiered Pricing, Freemium Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Customer Type: SMEs, Large Enterprises, Government Agencies, Startups Solution: Billing Systems, Analytics Tools, Compliance Frameworks, API Management |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Oracle Corporation, SAP SE, Salesforce Inc., IBM Corporation, Zuora Inc., Aria Systems, Chargebee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Monetization Market Strategic Shifts
Event-driven architectures are displacing batch billing systems across enterprise software stacks, enabling continuous revenue recognition and dynamic pricing adjustments tied to actual consumption patterns rather than contractual estimates.
Container-native metering is modularizing how usage telemetry is captured, processed, and rated. Kubernetes operators now embed sidecar proxies that stream resource consumption to billing engines with millisecond latency. SaaS vendors serving enterprise DevOps teams are adopting these patterns fastest, compressing time-to-bill from days to minutes and enabling granular cost allocation across internal service lines.
The EU AI Act risk classification framework is reshaping data processing requirements for monetization analytics. High-risk AI systems used for pricing optimization must maintain audit trails of training data provenance and model versioning. German automotive software vendors and French fintech platforms are restructuring their telemetry pipelines to isolate EU-resident data before cross-border model training, adding infrastructure cost but preserving market access.
Enterprise procurement functions are consolidating vendor relationships and demanding unified billing across hybrid infrastructure estates. Chief financial officers at US healthcare systems and German manufacturers now require single invoices spanning on-premise data centers and burst capacity from public clouds. This pattern forces monetization vendors to build multi-cloud reconciliation engines or risk displacement by platforms offering consolidated financial operations dashboards.
Cloud Monetization Market Segmentation
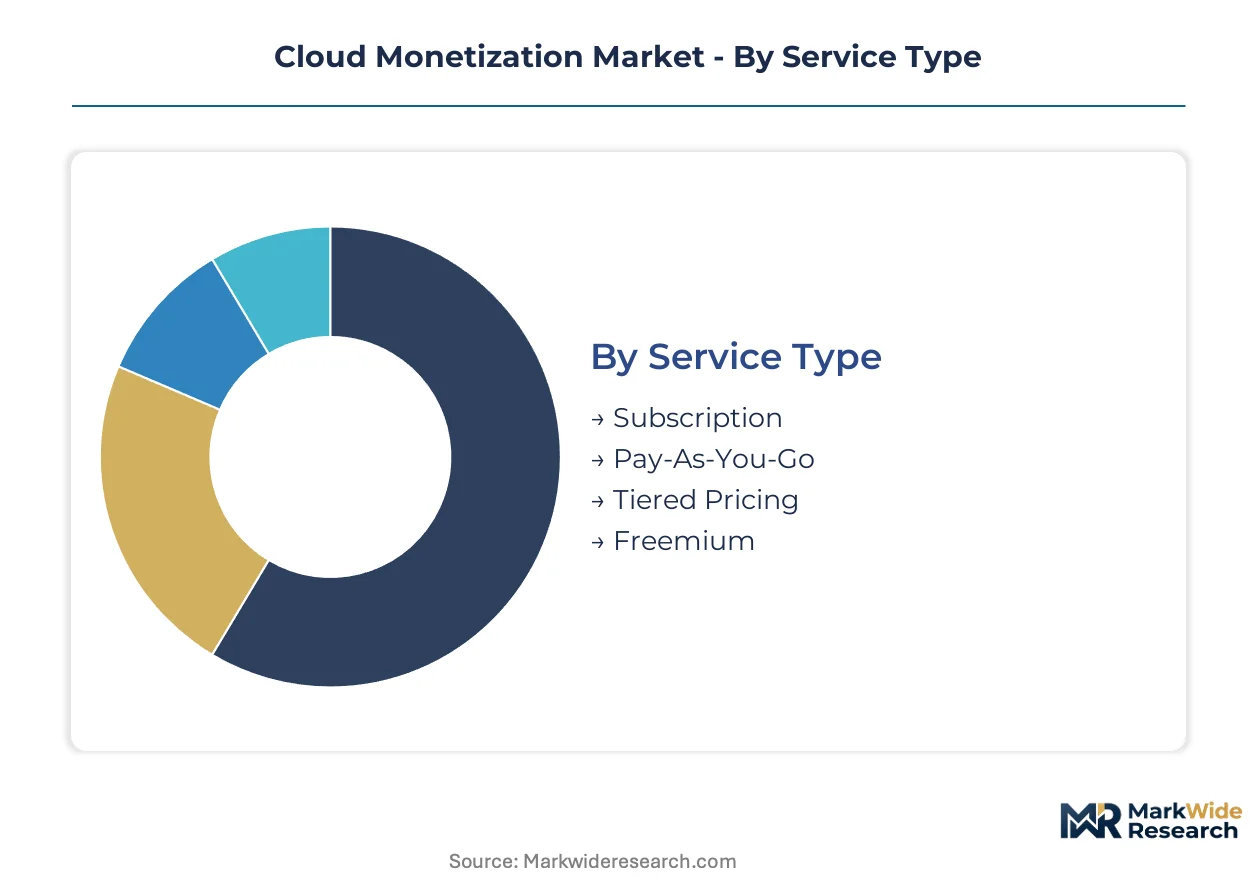
Cloud monetization platforms serve heterogeneous buyer needs across billing models, infrastructure estates, and regulatory environments. Segmentation reveals where margin pools concentrate and which configuration combinations unlock pricing power.
Service Type:
Supply concentration in metering infrastructure favors providers with real-time rating engines over batch-oriented legacy systems.
- Subscription:Recurring revenue contracts with fixed periodic charges anchor enterprise SaaS relationships. German automotive software vendors and US healthcare systems demand these models for predictable budget forecasting, though CFOs now insist on usage-adjustment clauses.
- Pay-As-You-Go:Consumption-based metering with sub-hour latency enables granular cost allocation. Indian cloud infrastructure providers under the PLI scheme deploy these engines to attract price-sensitive regulated sector buyers.
- Tiered Pricing:Three-level structures separate premium, standard, and economy service levels based on performance SLAs and support depth.
- Freemium:Zero-entry pricing with feature-gated conversion funnels dominates vertical SaaS acquisition strategies.
Today's leader: Subscription. Tomorrow's challenger: Pay-As-You-Go.
Deployment Model:
Margin structure varies sharply by where metering infrastructure resides relative to customer data estates.
- Hybrid Cloud:Sovereignty-compliant on-premise cores paired with elastic public burst capacity command premium pricing. German manufacturers and US healthcare systems drive this configuration to satisfy GDPR and HIPAA data residency mandates while retaining scalability.
- Multi-Cloud:Orchestration across AWS, Azure, and GCP estates requires reconciliation engines that normalize disparate metering formats. Enterprise procurement functions at Fortune 500 manufacturers now mandate unified billing across these environments.
- Public Cloud:Native metering APIs face commodity compression as standardized interfaces proliferate.
- Private Cloud:Dedicated infrastructure appeals to defense contractors and financial institutions with air-gapped security requirements.
Hybrid Cloud captures the steepest expansion trajectory as compliance complexity intensifies.
Customer Type:
Implementation cost recovery determines viable entry points across organizational scale.
- SMEs:Pre-configured vertical SaaS modules with embedded monetization reduce deployment friction. Indian fintech platforms and US specialty healthcare IT vendors target this tier with industry-specific rate card templates.
- Large Enterprises:Custom middleware requirements for SAP and Oracle ERP integration extend sales cycles but yield multi-year professional services revenue.
- Government Agencies:FedRAMP and state-level certification requirements filter vendor eligibility.
- Startups:API-first billing with minimal configuration overhead supports rapid product-market-fit iteration.
SMEs expand most quickly through vertical software embedding.
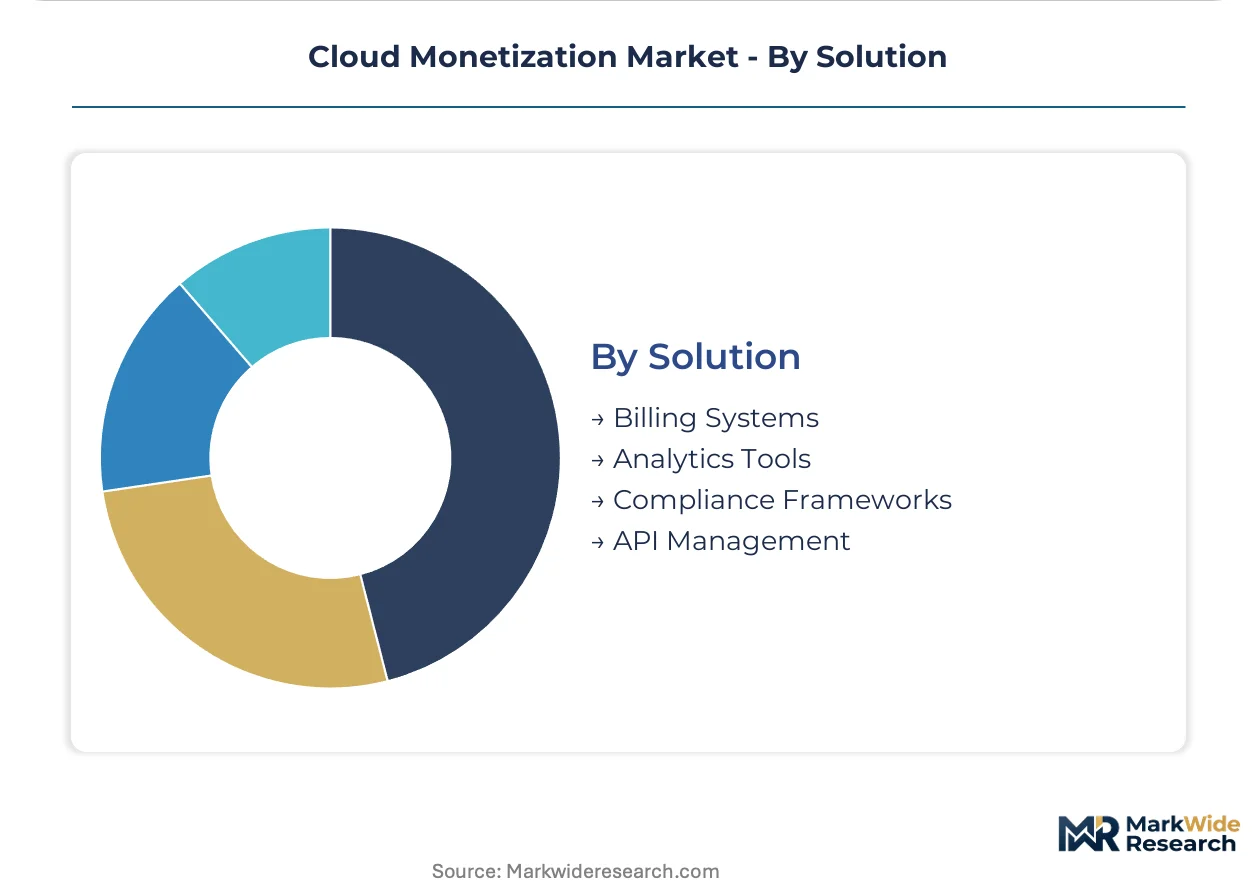
Solution:
Functional depth in compliance telemetry separates premium platforms from commodity API layers.
- Compliance Frameworks:Embedded GDPR Article 30 audit trails and EU AI Act risk classification tooling differentiate enterprise-grade offerings. French fintech platforms and German automotive software vendors require these capabilities to preserve EU market access.
- Billing Systems:Revenue recognition engines processing ASC 606 and IFRS 15 rules for usage-based contracts remain scarce technical capabilities.
- Analytics Tools:Consumption forecasting and churn prediction models leverage telemetry pipelines.
- API Management:Standardized metering interfaces face undifferentiation pressure from open-source alternatives.
Compliance Frameworks command the strongest pricing power as regulatory fragmentation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where cloud monetization infrastructure gets deployed, as vendors seek jurisdictions with clearer compliance frameworks and lower data residency friction. Cost-of-compliance gaps between the United States, Germany, and India are driving differential investment patterns across the analysis window.
United States
Hyperscale cloud regions in Northern Virginia and Oregon anchor enterprise software demand, with healthcare systems and financial institutions driving hybrid deployment configurations. FTC scrutiny of auto-renewal transparency in subscription software forces vendors to embed granular consent workflows into billing interfaces. Seattle-based Microsoft Corporation and Amazon Web Services in Seattle leverage Azure-native integration and deep API control over compute consumption to anchor enterprise accounts across hybrid environments.
Germany
Automotive software vendors and industrial manufacturers in Bavaria and Baden-Württemberg demand sovereignty-compliant metering infrastructure paired with elastic burst capacity. GDPR Article 30 mandates granular audit trails, compelling monetization platforms to embed compliance telemetry directly into rating engines. Frankfurt and Munich host dense concentrations of enterprise buyers restructuring telemetry pipelines to isolate EU-resident data before cross-border model training under the EU AI Act risk classification framework.
India
Domestic cloud infrastructure providers under the PLI scheme deploy real-time usage engines to attract price-sensitive buyers in regulated sectors including banking and telecommunications. Mumbai and Bangalore fintech platforms target SME tiers with pre-configured vertical SaaS modules featuring embedded monetization and industry-specific rate card templates. TRAI regulations on data localization reinforce demand for domestic metering infrastructure as multinational vendors establish captive development centers.
United Kingdom
London's financial services sector drives demand for revenue recognition engines processing ASC 606 and IFRS 15 rules for usage-based contracts. The Information Commissioner's Office enforces GDPR-aligned data processing requirements, restricting cross-border telemetry transfer without adequacy decisions. Cambridge and Manchester technology clusters host vertical SaaS vendors embedding container-native metering with Kubernetes operators that stream resource consumption to billing engines with millisecond latency.
Japan
Enterprise DevOps teams in Tokyo and Osaka adopt event-driven architectures displacing batch billing systems, enabling continuous revenue recognition tied to actual consumption patterns. METI guidelines on data sovereignty shape procurement requirements for hybrid cloud configurations among automotive and electronics manufacturers. Nagoya's industrial software vendors demand unified billing across on-premise data centers and burst capacity from public clouds, forcing monetization vendors to build multi-cloud reconciliation engines.
Cloud Monetization Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors seek to bridge capability gaps in compliance telemetry and legacy ERP integration. The vendor base concentrates around three tiers: hyperscale cloud providers with native metering APIs, specialized subscription orchestration platforms, and vertical SaaS vendors embedding pre-configured monetization modules. Two strategic archetypes have emerged: infrastructure-anchored players leveraging deep API control over compute and storage consumption, and compliance-first specialists differentiating through embedded GDPR and EU AI Act tooling. Geographic expansion and technology licensing represent the dominant competitive moves, with vendors seeking access to India's PLI-subsidized infrastructure and European data residency-compliant hosting.
Within the infrastructure-anchored tier, Microsoft Corporation and Amazon Web Services exemplify players leveraging hybrid cloud integration and metered infrastructure billing to capture enterprise accounts. Zuora Inc. occupies a position among subscription orchestration specialists, representing the archetype of vendors unifying recurring and consumption models for B2B SaaS vendors. These three companies anchor the competitive structure, with each sitting within distinct capability domains that reflect broader market segmentation between native cloud metering, subscription management, and embedded vertical solutions.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Oracle Corporation |
| SAP SE |
| Salesforce Inc. |
| IBM Corporation |
| Zuora Inc. |
| Aria Systems |
| Chargebee |
| Others |
Value Chain & Pricing Dynamics
EU AI Act risk classification mandates gate both qualified supply and premium-tier pricing access, as vendors must isolate EU-resident data before cross-border model training to preserve market access. German automotive software vendors and French fintech platforms now pay substantial premiums for compliance-embedded metering infrastructure that satisfies these telemetry isolation requirements.
Pricing Analysis
Direct-to-OEM discounts compress channel margins for standardized API management layers while subscription-SaaS tiering dominates enterprise relationships. Price differentiation hinges on GDPR Article 30 audit trail depth and EU AI Act certification grade, with sovereign-compliant hybrid configurations commanding substantial premiums over public cloud metering. Cost compression in commodity API tiers intensifies as open-source alternatives proliferate, while Indian PLI-subsidized providers exhibit highest price sensitivity and US healthcare systems demonstrate lowest sensitivity due to HIPAA-mandated data residency requirements.
Supply Chain Analysis
Dual-sourcing requirements from German manufacturers and US healthcare systems mandate multi-supplier qualification across metering infrastructure vendors. Supply concentrates in the United States, Germany, and India as these host densest hyperscale cloud regions and enterprise software buyer clusters. Raw material dependencies center on specialized compliance telemetry modules, container-native metering sidecars, and real-time rating engine software. Single-source vulnerability persists in legacy ERP integration middleware for SAP and Oracle systems. Distribution runs through direct enterprise sales with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud monetization functions as a regulatory compounder where GDPR Article 30 and EU AI Act mandates continuously deepen demand for compliance-embedded infrastructure.
For Market Incumbents: Anchor enterprise accounts through captive hybrid cloud integration that satisfies data sovereignty mandates while extending professional services revenue from SAP and Oracle middleware development. Threat substitution from container-native open-source metering alternatives demands accelerated certification investment in EU AI Act risk classification tooling. Capacity addition in India's PLI-subsidized infrastructure zones preserves margin position against price-sensitive domestic competitors. For New Entrants and Emerging Players: The mid-market price-point gap between premium compliance-embedded platforms and economy-tier API commoditization offers viable entry terrain. SME vertical SaaS modules with pre-configured rate card templates represent the most penetrable segment, particularly among Indian fintech platforms and US specialty healthcare IT vendors. Go-to-market execution should emphasize Kubernetes-native sidecar deployment with millisecond-latency telemetry streaming as a technical wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among compliance-first specialists with embedded GDPR and EU AI Act tooling but limited geographic footprint. Long-term viability across the projection horizon favors vendors with multi-cloud reconciliation engines that normalize disparate metering formats across AWS, Azure, and GCP estates. The signal to watch is enterprise procurement consolidation mandating unified billing across hybrid infrastructure estates.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Framework Embedding | EU AI Act risk classification tooling preserves German and French market access for automotive and fintech vendors. |
| Hybrid Cloud Capacity Expansion | Sovereignty-compliant on-premise cores with elastic burst capacity satisfy GDPR and HIPAA mandates for healthcare systems. |
| Vertical SaaS Partnership | Pre-configured monetization modules reduce deployment friction for Indian fintech platforms targeting SME banking segments. |
| Legacy ERP Integration Development | Custom SAP and Oracle middleware extends sales cycles but yields multi-year professional services revenue from large enterprises. |
| Geographic Licensing Agreement | Technology licensing to India's PLI-subsidized infrastructure providers accesses price-sensitive regulated sector buyers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation through SEC filings, hyperscaler capex disclosures, and regulatory submission databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators anchored the value estimates.
Segment-weighting approaches distributed value across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derived from fitted growth curves applied to each segment's baseline and projected endpoint across the analysis window. Forecast inputs incorporated telecommunications carrier 5G network slicing requirements and SME vertical SaaS penetration rates.
The model assumes a particular technology adoption path; alternative pathways for event-driven billing architectures displacing batch systems would alter the outlook. Deviation in regulatory enforcement intensity for GDPR Article 30 or EU AI Act risk classification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
IPTV Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Product Data Management Market
Digital Solutions
Global Automatic Content Recognition (ACR) Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Mock Interview Platforms Market