
 Packaging Straps and Buckles Market | 2026-2036
Packaging Straps and Buckles Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Straps and Buckles Market Analytics
The EU Green Deal is recalibrating material preferences across European packaging supply chains, pushing converters toward recyclable polymer alternatives. Signode Industrial Group leverages its vertical integration in steel strapping to sustain dominance in heavy-load applications. Polychem Corporation anchors North American demand through specialized polyester formulations. Teufelberger Holding AG differentiates via high-tenacity fiber technology for cord-based securing systems.
Packaging straps and buckles comprise tensioning devices and fastening hardware engineered to unitize palletized goods, secure freight containers, and reinforce corrugated shipments during transit. Polyester straps typically achieve break strengths of 300-2,000 pounds with elongation recovery below 14%, enabling repeated stress cycles without permanent deformation. Steel straps retain primacy in metalworking and construction end users where extreme load rigidity prevents package settlement. Automatic strapping technology captures expanding margin pools as fulfillment centers replace manual bundling with inline systems operating at 60+ cycles per minute.
REACH compliance in Europe and FDA indirect food contact regulations in the United States constrain plasticizer and additive selection for strapping materials. OSHA ergonomic standards influence manual strapping tool design, reducing repetitive strain liability for warehouse operators. Stakeholders must monitor how extended producer responsibility frameworks reshape material recovery economics and buckle reusability requirements.
Market Dynamics
Automatic strapping systems operating at 60+ cycles per minute are compressing manual bundling margins across fulfillment networks, while EU Green Deal packaging waste directives force material substitutions from steel to recyclable polymers.
Growth Catalysts
- EU Green Deal packaging directives:Mandates for recyclable materials accelerate polyester and polypropylene strap adoption across European automotive and logistics supply chains.
- E-commerce fulfillment automation:Third-party logistics operators in Germany and the Netherlands deploy inline strapping systems to meet same-day delivery load-securing requirements.
- High-tensile fiber advances:Cord-based securing systems achieve break strengths rivaling steel at one-fifth the weight, penetrating aerospace component shipping.
Market Restraints
- Petrochemical feedstock volatility:Polyester strap producers face margin compression when PTA and MEG prices spike, limiting pricing flexibility against steel alternatives.
- REACH compliance costs:European manufacturers absorb testing and documentation expenses for plasticizer content in polymer formulations, disadvantaging smaller converters.
- Steel strap rigidity premium:Metalworking and construction end users reject polymer substitutes where load settlement prevention outweighs weight savings.
Strategic Opportunities
- India's warehousing expansion:Cold chain infrastructure investments create demand for moisture-resistant polypropylene strapping in agricultural export corridors.
- Extended producer responsibility frameworks:EU member states implementing buckle reusability mandates favor modular fastening systems designed for disassembly.
- RFID-embedded smart straps:Convergence of polymer extrusion and printed electronics enables real-time tension monitoring for high-value pharmaceutical shipments.
Industry Challenges
- Ergonomic tool design certification:OSHA standards for repetitive strain reduction extend product development timelines for manual strapping equipment by 8-14 months.
- Legacy system integration:Automated strapping line retrofits in established distribution centers require custom PLC programming and mechanical interfacing with existing conveyor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Straps and Buckles Market |
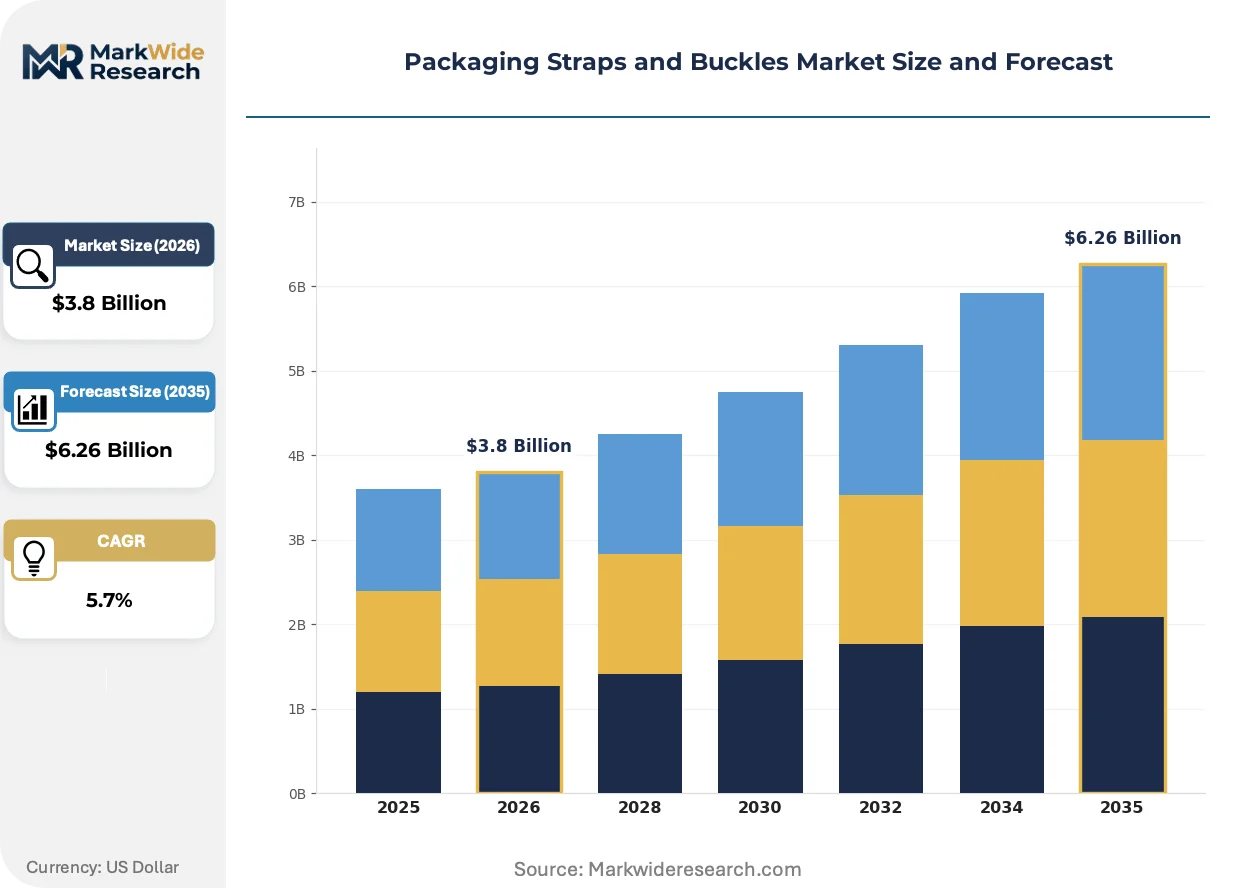
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Straps, Polypropylene Straps, Steel Straps, Buckles End User: Retail, Manufacturing, Logistics, Construction Technology: Machine Strapping, Manual Strapping, Automatic Strapping, Semi-Automatic Strapping Distribution Channel: Online Retail, Direct Sales, Distributors, Suppliers |
| Companies Covered | Signode Industrial Group, Polychem Corporation, Teufelberger Holding AG, Fromm Packaging Systems, Cyklop International, Samuel Strapping Systems, M.J. MAILLIS GROUP, Mosca Direct, Cordstrap BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Straps and Buckles Market Evolving Landscape
Material science breakthroughs and regulatory pressure are converging to reshape strapping specifications across freight-intensive industries, with sustainability metrics now embedded in procurement scoring.
Bio-based polyester formulations derived from recycled PET feedstocks are electrifying sustainable packaging roadmaps for consumer electronics exporters. Dell and HP procurement teams now specify minimum 30% post-consumer recycled content in inbound packaging straps. This specification is compressing virgin polymer premiums and forcing resin suppliers to secure certified waste stream partnerships.
REACH restrictions on phthalate plasticizers are tightening additive portfolios for European polymer strap manufacturers. ECHA substance evaluations now target specific flexibilizers common in low-temperature performance grades. German automotive suppliers respond by accelerating validation of bio-plasticizer alternatives, extending qualification cycles but securing long-term market access.
Direct procurement relationships between e-commerce platforms and strap converters are disintermediating traditional distribution channels. Amazon and Zalando negotiate annual volume commitments with Polychem and Teufelberger for standardized polyester specifications, bypassing regional packaging distributors. This concentration is most visible in the Netherlands and Belgium, where Rotterdam-Antwerp logistics clusters consolidate demand for automated line integration.
Packaging Straps and Buckles Market Segmentation
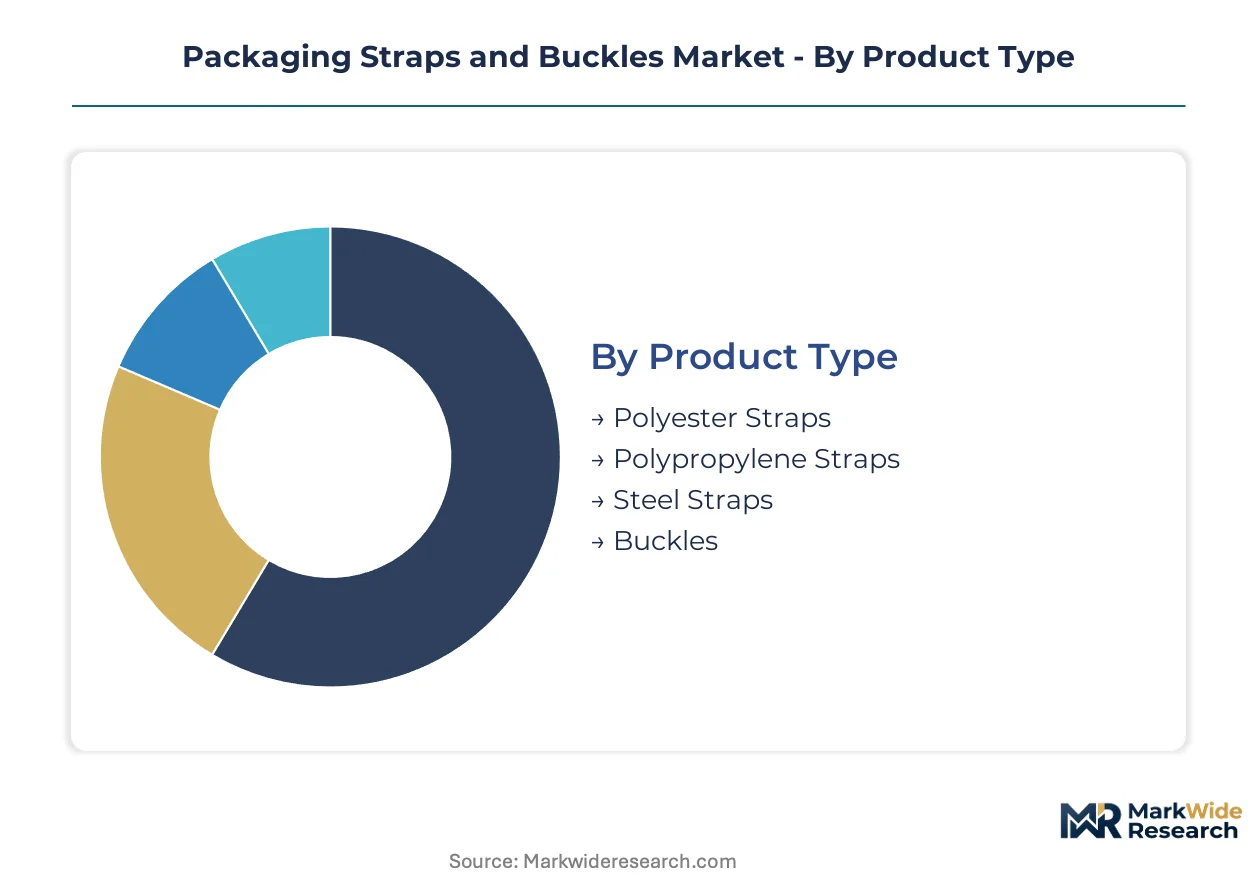
Strapping procurement patterns diverge sharply between high-volume commodity flows and precision-engineered securing requirements. Material selection, automation level, and channel configuration each reshape margin structures and supplier relationships across freight-intensive industries.
Product Type:
Volume dominance belongs to polyester and polypropylene formulations, while steel retains premium positioning for extreme load rigidity.
- Polyester Straps:Extruded polyethylene terephthalate delivers 300-2,000 pound break strength with sub-14% elongation recovery. E-commerce fulfillment centers in Germany and the Netherlands specify these for repeated stress cycles in automated lines.
- Steel Straps:Cold-rolled carbon steel maintains primacy where load settlement prevention outweighs weight savings. Metalworking and construction end users in Germany's industrial corridor reject polymer substitutes for cross-border heavy freight.
- Polypropylene Straps:Lower-cost polymer suited to lightweight corrugated bundling and single-use export packaging.
- Buckles:Galvanized steel and polymer fastening hardware engineered for tension retention and reusability under EU Green Deal mandates.
Mature deployment sits with steel strapping in heavy industrial applications. Newer deployment is concentrated in recyclable polymer alternatives across European automotive supply chains.
End User:
Procurement sophistication escalates from retail commodity buying to logistics-driven technical specifications.
- Logistics:Third-party operators deploy inline automatic systems operating at 60+ cycles per minute. Amazon and Zalando negotiate direct annual volume commitments with converters, bypassing traditional distribution in Rotterdam-Antwerp clusters.
- Manufacturing:Automotive component exporters require high-tensile bundling solutions with REACH-compliant formulations. German suppliers validate bio-plasticizer alternatives to secure long-term market access.
- Retail:Standardized polyester specifications for inbound packaging, with Dell and HP procurement teams mandating minimum 30% post-consumer recycled content.
- Construction:Steel strap rigidity premium persists where structural load integrity prevents package settlement during transit.
Margin compression concentrates in retail procurement through direct platform-converter relationships. Technical differentiation survives in manufacturing specifications requiring REACH documentation and recycled content certification.
Technology:
Automation intensity separates fulfillment network economics from field construction applications.
- Automatic Strapping:Inline systems integrate with conveyor architectures at 60+ cycles per minute. Legacy distribution center retrofits demand custom PLC programming and mechanical interfacing.
- Machine Strapping:Standalone powered units for mid-volume operations without full line integration requirements.
- Semi-Automatic Strapping:Operator-fed systems bridging manual and fully automated workflows in regional distribution facilities.
- Manual Strapping:Hand tools and portable tensioners for construction sites and low-volume applications. OSHA ergonomic standards extend product development timelines by 8-14 months for repetitive strain reduction certification.
Capital deployment concentrates in automatic systems for e-commerce fulfillment density. Manual equipment retains necessity where power infrastructure and line integration prove uneconomical.
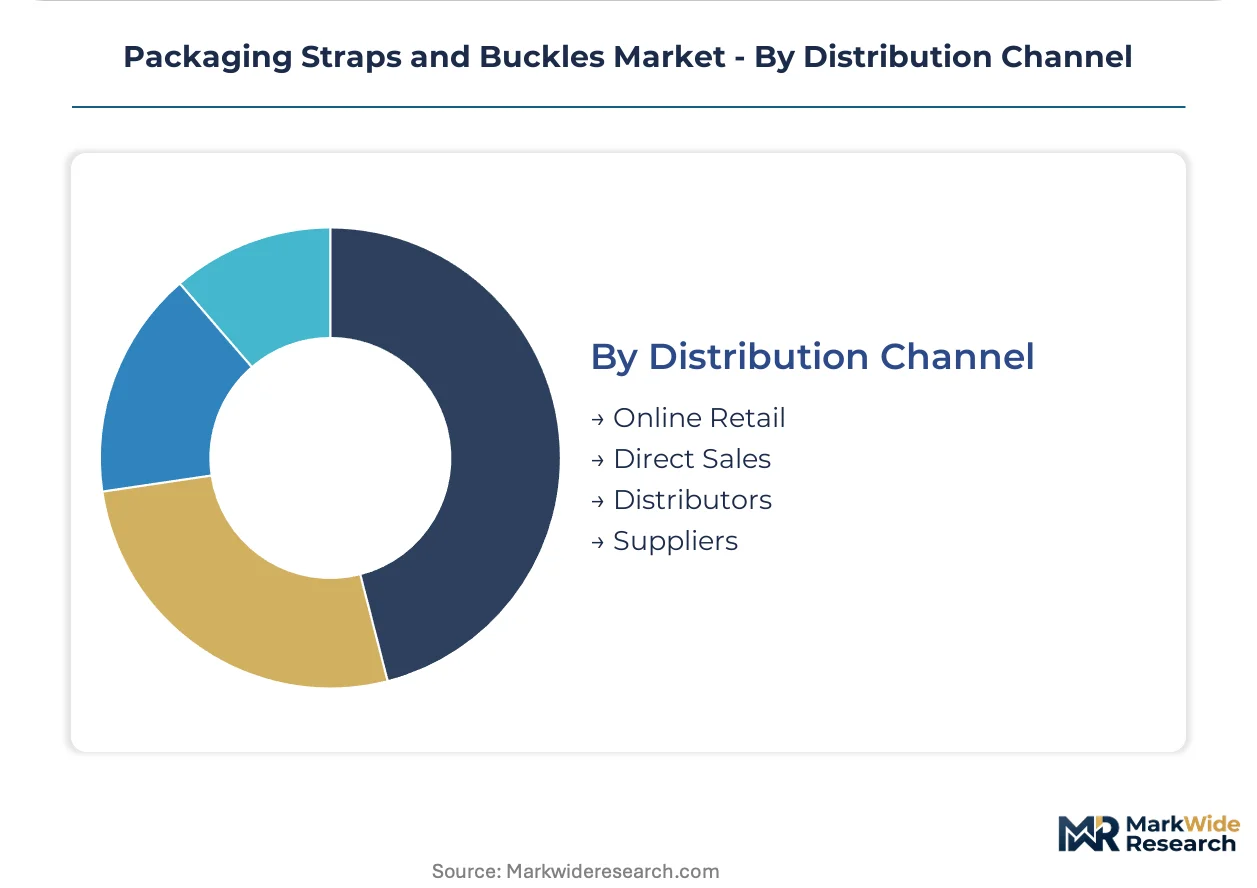
Distribution Channel:
Channel concentration reflects procurement scale and technical specification complexity.
- Direct Sales:Annual volume commitments between e-commerce platforms and specialized converters. Disintermediation is most visible in Netherlands and Belgium logistics clusters.
- Distributors:Regional packaging suppliers serving mid-market manufacturers without dedicated procurement teams.
- Suppliers:Integrated resin-to-strap producers capturing margin through backward integration into polymer feedstocks.
- Online Retail:Spot purchasing for replacement buckles and manual tool accessories by small-scale end users.
Relationship-based contracting dominates high-volume logistics procurement. Transactional purchasing persists in maintenance, repair, and operations segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp logistics corridor concentrates European demand for automated strapping systems, while regulatory divergence across major economies is fragmenting material specifications and procurement standards.
Germany
Automotive component exporters in Stuttgart and Munich drive high-tensile polyester procurement for cross-border freight securing. REACH compliance through ECHA mandates documentation of plasticizer content in polymer formulations. The Baden-Württemberg industrial corridor validates bio-plasticizer alternatives to maintain long-term market access for bundling solutions.
United States
E-commerce fulfillment centers in Chicago and Dallas deploy inline automatic strapping at 60+ cycles per minute. FDA indirect food contact regulations constrain additive selection for straps entering pharmaceutical supply chains. The Pacific Northwest tech corridor sees Dell and HP procurement teams mandate minimum 30% post-consumer recycled content in inbound packaging straps.
Netherlands
Third-party logistics operators in Rotterdam's port zone negotiate direct annual volume commitments with specialized converters. EU Green Deal packaging waste directives accelerate shifts from steel to recyclable polymer strapping across Dutch supply chains. The Randstad logistics cluster consolidates demand for automated line integration and standardized polyester specifications.
China
Manufacturing exporters in the Yangtze River Delta scale polyester strap production to meet load-securing requirements for containerized freight. Dual carbon goals under MEE oversight push converters toward recycled PET feedstock integration. The Pearl River Delta electronics assembly belt specifies moisture-resistant polypropylene for agricultural export corridor applications.
India
Cold chain infrastructure investments in Maharashtra and Gujarat create demand for moisture-resistant polypropylene strapping. BIS standards govern tensile strength certification for domestic and export-bound securing products. The Delhi-Mumbai Industrial Corridor warehouses adopt semi-automatic systems bridging manual and fully automated workflows in regional distribution facilities.
Packaging Straps and Buckles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specialization and automation integration depth. The vendor base stratifies between steel-focused heavy-load specialists, polymer formulation experts, and system integrators capturing recurring service revenue. Three archetypes dominate: vertically integrated resin-to-strap producers, technology licensors for automated line integration, and regional converters serving spot-demand maintenance segments. Capacity expansion and direct procurement disintermediation represent the dominant competitive vectors reshaping channel economics.
Within the steel-strapping tier, Signode Industrial Group and Samuel Strapping Systems exemplify heavy-load application dominance through captive metallurgical processing. Polychem Corporation anchors North American polymer demand through specialized polyester formulations, representing the formulation-specialist archetype against regional competitors. Teufelberger Holding AG occupies a differentiated position in high-tenacity fiber systems for cord-based securing applications.
| Leading Market Players |
|---|
| Signode Industrial Group |
| Polychem Corporation |
| Teufelberger Holding AG |
| Fromm Packaging Systems |
| Cyklop International |
| Samuel Strapping Systems |
| M.J. MAILLIS GROUP |
| Mosca Direct |
| Cordstrap BV |
| Others |
Value Network & Pricing Analysis
Automatic strapping systems operating at 60+ cycles per minute are compressing manual bundling margins while simultaneously concentrating procurement power among e-commerce platforms with direct converter relationships. This technology shift feeds back into resin sourcing economics, as high-volume polyester specifications from Amazon and Zalando override regional distributor pricing in Rotterdam-Antwerp logistics clusters.
Pricing Analysis
Throughput-based pricing anchors value capture for inline automatic systems, with fulfillment centers paying premium rates for guaranteed cycle-time performance and uptime commitments. Price differentiation separates REACH-compliant formulations with ECHA documentation from commodity polymer grades lacking certification. Pricing pressure stems from PTA and MEG feedstock volatility squeezing converter margins against fixed steel strap benchmarks. Retail procurement teams exhibit highest price sensitivity, while automotive exporters prioritize qualification documentation over unit cost.
Supply Chain Analysis
Refurbishment flows for reusable buckles under EU Green Deal mandates are creating reverse logistics infrastructure that polymer converters must integrate to maintain European market access. Raw material concentration centers on Germany, the Netherlands, and China for extruded polyester and cold-rolled steel feedstocks. Supply chains draw from petrochemical complexes in the Rhine-Ruhr region and Yangtze River Delta, with secondary sourcing from US Gulf Coast PTA producers. Single-source vulnerability sits with specialized bio-plasticizer suppliers qualifying REACH-compliant alternatives. Distribution runs through direct annual volume commitments between e-commerce platforms and specialized converters, bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Packaging Straps and Buckles Market functions as a cost-of-compliance arena where REACH documentation and ECHA substance evaluations erect barrier-to-entry moats favoring incumbents with established testing protocols.
For Market Incumbents: To counter direct procurement disintermediation by Amazon and Zalando, deepen captive control over polymer feedstock supply through backward integration into recycled PET waste stream partnerships. Prioritize certification investment in bio-plasticizer alternatives to secure long-term automotive supplier relationships under tightening ECHA restrictions. For New Entrants and Emerging Players: RFID-embedded smart strap technology offers a technology-first wedge into pharmaceutical cold chain monitoring where real-time tension data commands premium pricing. Target India's agricultural export corridor for moisture-resistant polypropylene specifications, leveraging BIS certification requirements that favor specialized formulations over commodity imports. Pursue joint development agreements with cold chain infrastructure investors in Maharashtra and Gujarat. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated packaging conglomerates seeking automated line integration capabilities. Long-term viability favors converters with demonstrated REACH compliance infrastructure and direct e-commerce platform relationships. Monitor ECHA substance evaluation timelines for phthalate restrictions as inflection indicators for bio-plasticizer adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Feedstocks | Dell and HP procurement mandates for 30% post-consumer content secure premium positioning. |
| REACH-Compliant Bio-Plasticizer Validation | German automotive suppliers accelerate qualification cycles to maintain ECHA market access. |
| Direct E-Commerce Platform Relationships | Amazon and Zalando volume commitments in Rotterdam-Antwerp clusters disintermediate distributors. |
| RFID-Embedded Smart Strap Development | Convergence of polymer extrusion and printed electronics enables pharmaceutical shipment monitoring. |
| Modular Buckle Reusability Design | EU Green Deal extended producer responsibility mandates favor disassembly-ready fastening systems. |
Research Methodology
Document review covered customs and trade flow databases, SEC filings from packaging equipment manufacturers, and EU regulatory filings through ECHA, complemented by interviews with plant managers at polyester extrusion facilities, procurement leads at third-party logistics operators, technical R&D directors at polymer formulation houses, and aftermarket service heads at automated strapping system integrators. Secondary validation drew from ACC and Cefic chemical industry reports, FEFCO corrugated packaging statistics, and OECD trade policy databases. Bottom-up volume estimates from converter capacity utilization triangulated against top-down demand projections from end-use industry shipment data.
Cross-referencing historical pricing spreads between steel and polymer straps against panel input from procurement executives at German automotive suppliers and Dutch logistics operators anchored the analytical framework. Segmentation dimensions modeled include material type, automation technology tier, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment density indices and REACH compliance cost pass-through assumptions. Industry-specific forecast inputs captured cold chain infrastructure investment pipelines in India and dual carbon goal implementation timelines under MEE oversight in China.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock price spikes and accelerated ECHA substance restriction timelines. Practitioners should monitor PTA and MEG futures curves, ECHA evaluation publication schedules, and e-commerce platform procurement RFP releases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
France Packaging Market
Packaging Materials
Urn Liners Market
Packaging Materials
Global Food Processing Seals Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Cavitated Films Market
Packaging Materials
China Packaging Market