
 Animal Feed Additives Market | 2026-2036
Animal Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Additives Market Insights
Brazil is reconfiguring South American supply dynamics through expanded fermentation capacity for amino acid and enzyme production. Cargill leverages backward integration into raw material sourcing across Midwestern U.S. grain belts. Evonik Industries anchors European production of methionine with dedicated biotechnology platforms. dsm-firmenich specializes in vitamin premixes, competing on precision nutrition formulations for industrial feed manufacturers.
Animal feed additives comprise biologically active substances—vitamins, enzymes, amino acids, probiotics, acidifiers, and antibiotics—incorporated at 0.01% to 1% inclusion rates to enhance feed conversion ratios, gut health, and growth performance in production animals. Amino acids and enzymes command the deepest margin pools due to fermentation complexity and patent-protected microbial strains. Poultry applications absorb the highest additive volumes globally, while aquaculture represents the fastest-expanding application segment as marine protein producers replace fishmeal with precision-formulated alternatives.
EFSA and the EU Green Deal shape European additive demand through restrictions on antibiotic growth promoters and mandates for sustainable protein sourcing. The FDA and USDA jointly regulate U.S. feed additive safety under the Food Safety Modernization Act and Federal Food, Drug, and Cosmetic Act, creating compliance thresholds that favor large premix suppliers. Brazil's national agricultural regulator enforces residue limits aligned with Codex Alimentarius to maintain China-bound export access. Stakeholders must track evolving enzyme approval pathways and carbon-accounting requirements that will determine which formulation technologies retain market access.
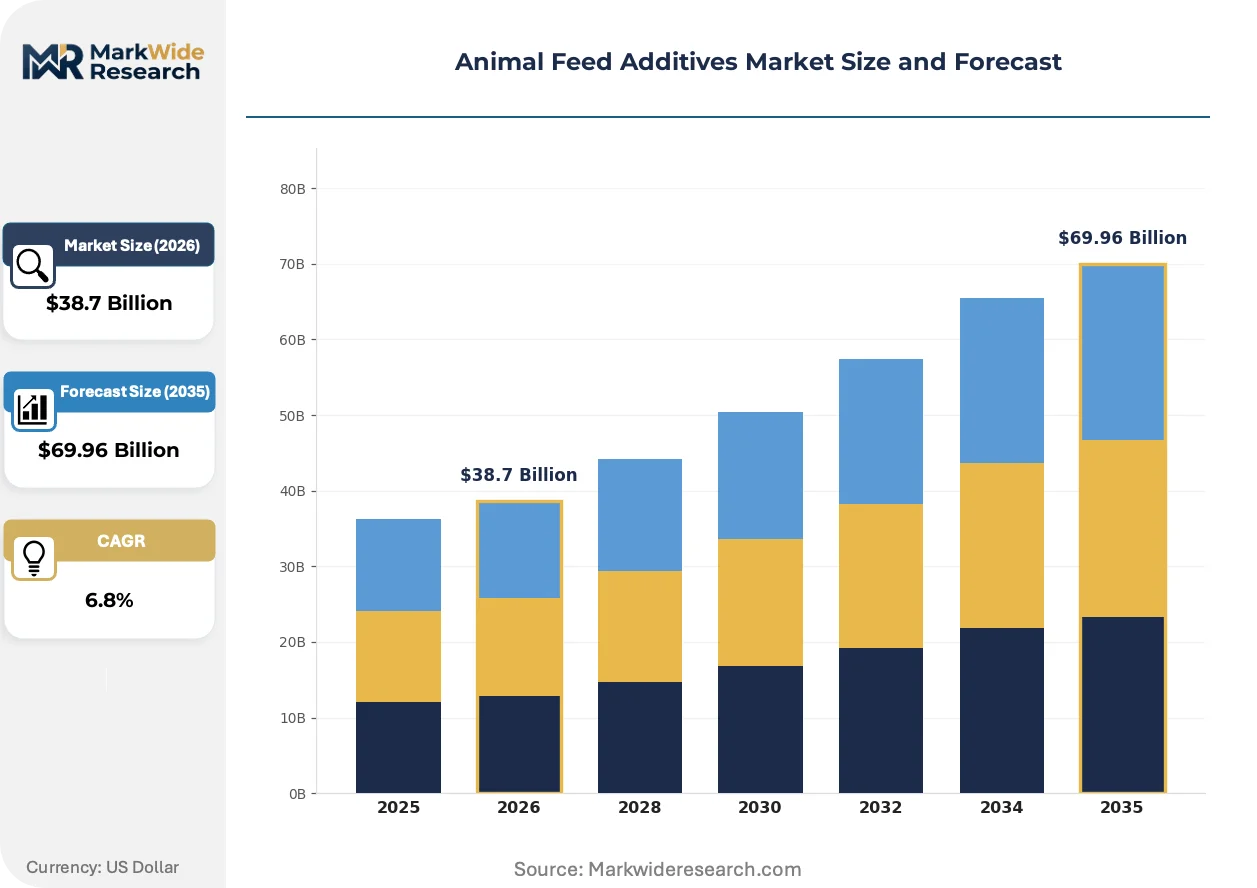
Market Dynamics
Fermentation capacity concentration in Brazil and the U.S. Midwest is restructuring amino acid and enzyme supply economics, forcing premix manufacturers to secure captive biotech platforms or face margin compression from input volatility.
Growth Catalysts
- EU Green Deal antibiotic restrictions:The phased ban on growth-promoting antimicrobials across European livestock operations accelerates probiotic and acidifier incorporation rates in compound feeds.
- Poultry sector consolidation in Vietnam and Indonesia:Industrial broiler operations across Southeast Asia mandate precision amino acid fortification to achieve export-grade feed conversion ratios.
- Fishmeal displacement in aquaculture:Marine protein producers deploy enzyme-enhanced plant protein concentrates to reduce dependency on Peruvian anchovy harvest volatility.
Market Restraints
- Corn and soybean meal price volatility:Fermentation feedstock costs swing with Midwestern U.S. grain futures, compressing methionine and lysine producer margins unpredictably.
- Single-source enzyme strain dependencies:Patent-protected microbial platforms from concentrated European biotechnology suppliers create supply vulnerability for Asian premix formulators.
- Residue testing harmonization gaps:Brazil's ANVISA enforcement of Codex Alimentarius limits lags EU detection thresholds, blocking some additive categories from China-bound meat exports.
Strategic Opportunities
- Sub-Saharan African poultry expansion:Greenfield feed mill construction in Nigeria and Kenya creates first-mover positioning for vitamin premix suppliers establishing local blending facilities.
- Carbon-accounting integration:The EU CSRD mandates scope 3 emissions disclosure from livestock producers, creating premium pricing for additives with verified methane-reduction credentials.
- Precision nutrition software convergence:Real-time formulation algorithms linked to NIR spectroscopy enable dynamic additive dosing that responds to raw material quality variation.
Industry Challenges
- Fermentation scale-up engineering talent scarcity:Industrial microbiology and bioprocess engineering expertise concentrates at established European and Brazilian production hubs, constraining new facility commissioning timelines.
- Multi-jurisdiction approval synchronization:Enzyme products require separate EFSA, FDA, and Chinese Ministry of Agriculture safety dossiers, extending commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Additives Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vitamins, Enzymes, Amino Acids, Probiotics, Acidifiers Application: Poultry, Swine, Aquaculture, Ruminants, Pet Nutrition, Equine Form: Powder, Liquid, Granules, Pellets, Concentrate, Premix End User: Feed Manufacturers, Integrators, Livestock Farms, Pet Food Companies, Research Institutes |
| Companies Covered | Cargill, Archer Daniels Midland Company, Alltech, Evonik Industries, dsm-firmenich, Adisseo, Kemin Industries, Nutreco, Novonesis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Additives Market Trends and Innovations
Digital integration across formulation, fermentation monitoring, and farm-level dosing is compressing the feedback loop between additive design and animal performance outcomes, rewarding suppliers with real-time data infrastructure.
Near-infrared spectroscopy coupled with cloud-based feed analysis is digitizing quality control workflows at commercial feed mills. Large integrators in Brazil and the U.S. deploy inline sensors to adjust enzyme and amino acid inclusion rates batch-by-batch. This capability is digitizing the traditional static premix model into responsive formulation systems that lock in feed conversion gains.
The EU F-Gas Regulation and REACH chemical safety revisions are tightening excipient and carrier material approvals for vitamin and probiotic products. Formulators must reformulate delivery matrices to maintain stability without restricted solvents or synthetic coatings. Poultry premix manufacturers serving Dutch and Danish operations face the most compressed compliance timelines as these member states enforce ahead of EU minimum schedules.
Integrated livestock operators are consolidating additive procurement under single-source premix contracts that bundle technical services, formulation software, and residue testing support. Independent feed mills lose volume to vertically aligned suppliers offering outcome guarantees on feed conversion ratios. This concentration is most visible across Brazilian broiler operations where four processors control two-thirds of national feed demand.
Animal Feed Additives Market Segmentation
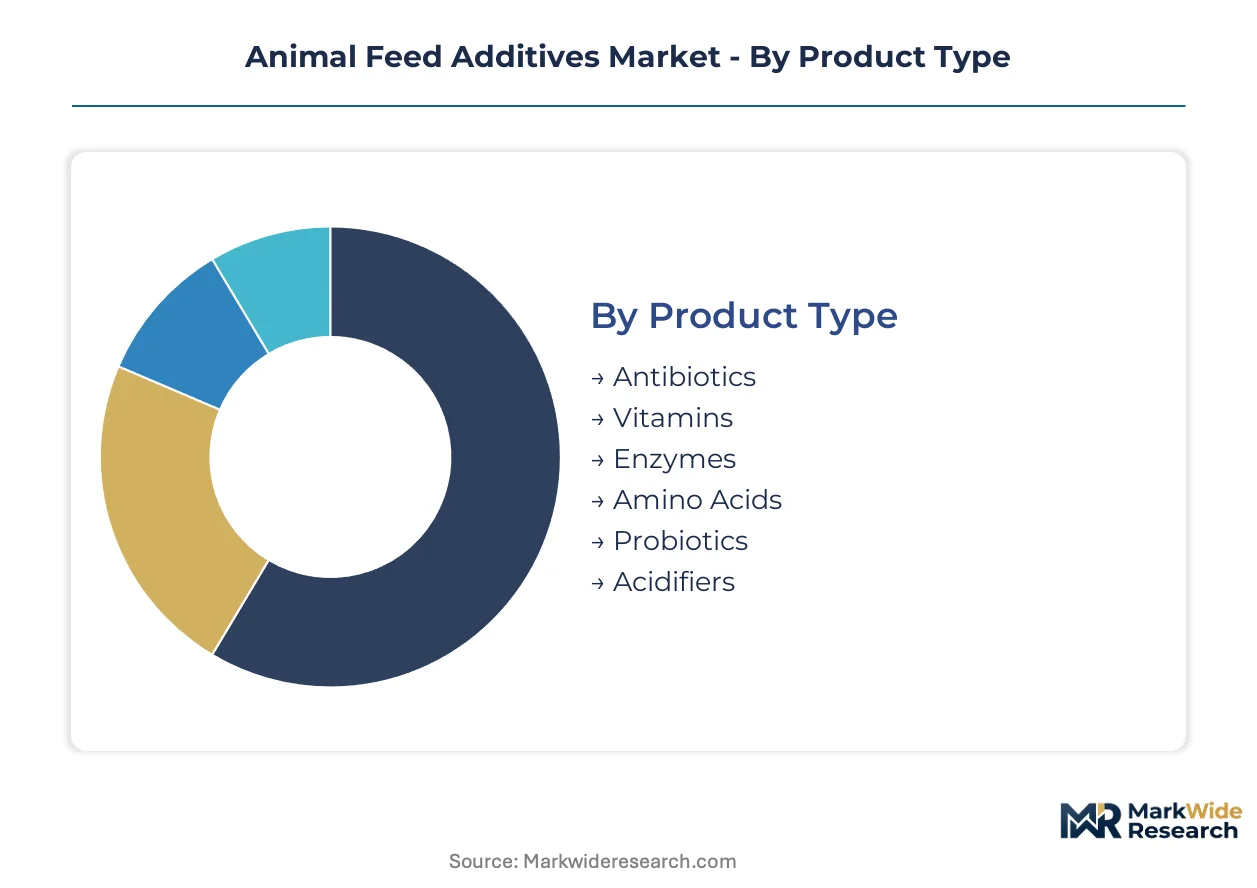
Animal feed additives fragment across four intersecting dimensions that determine formulation economics and procurement patterns. Product chemistry dictates margin structures, while application species and end-user scale shape volume concentration and technical service requirements.
Product Type:
Functional requirements span from growth promotion to gut health modulation, with fermentation-derived categories commanding premium positioning due to bioprocess complexity and strain patent protection.
- Amino Acids:Lysine, methionine, threonine, and tryptophan dominate inclusion economics in poultry and swine compound feeds. Industrial fermentation at Brazilian and U.S. Midwest facilities supplies bulk volumes, while Chinese demand for export-grade livestock protein drives precision fortification specifications.
- Enzymes:Phytases, carbohydrases, and proteases unlock phosphorus and energy from plant-based feedstuffs. Patent-protected microbial strains from European biotechnology suppliers create supply concentration for Asian premix formulators seeking fishmeal displacement in aquaculture.
- Vitamins:Fat-soluble and water-soluble micronutrients prevent deficiency disorders in high-density livestock operations.
- Probiotics:Live microbial cultures colonize gut microbiota to enhance nutrient absorption and pathogen exclusion.
- Acidifiers:Organic acids lower gastric pH to improve protein digestion and suppress bacterial proliferation.
- Antibiotics:Therapeutic and sub-therapeutic antimicrobials face phased restrictions under EU Green Deal mandates and FDA guidance documents.
Established volume favors amino acids; emerging adoption favors enzymes.
Application:
Species-specific digestive physiology and production intensity create divergent additive performance requirements and dosing protocols.
- Poultry:Broiler and layer operations consume the highest additive volumes globally, with precision amino acid fortification mandatory for export-grade feed conversion ratios in Vietnamese and Indonesian integrators.
- Aquaculture:Marine and freshwater protein producers deploy enzyme-enhanced plant concentrates to reduce Peruvian anchovy fishmeal dependency. Salmon and shrimp farms in Norway and Ecuador drive formulation innovation for species-specific nutrient matrices.
- Swine:Post-weaning diets incorporate acidifiers and zinc oxide alternatives to manage gut health in high-turnover operations.
- Ruminants:Methane-inhibiting feed additives attract investment as EU CSRD scope 3 disclosure requirements reach livestock producers.
- Pet Nutrition:Premium companion animal diets incorporate specialized vitamin premixes and palatability enhancers.
- Equine:Performance and breeding operations require targeted mineral and vitamin supplementation for metabolic optimization.
Volume concentrates in poultry; steepest expansion trajectory appears in aquaculture.
Form:
Physical delivery systems determine stability, handling characteristics, and precision dosing capabilities across feed manufacturing infrastructure.
- Premix:Concentrated blends of vitamins, minerals, and trace additives distributed to commercial feed mills and on-farm mixers. Brazilian integrators consolidate procurement under single-source contracts bundling technical services and residue testing support.
- Powder:Fine particulate forms suit inclusion in mash feeds and mineral supplements for ruminant operations.
- Liquid:Pumpable acidifiers and enzymes enable post-pelleting application and drinking water supplementation in automated systems.
- Granules:Agglomerated particles reduce dust generation and improve flowability in pneumatic conveying systems.
- Pellets:Compressed forms protect heat-sensitive actives during feed processing and transport.
- Concentrate:High-potency intermediates require dilution before final feed incorporation.
Procurement scale favors premix; precision dosing favors liquid.
End User:
Customer structure spans integrated value chains to fragmented independent operations with divergent technical capabilities and volume requirements.
- Integrators:Vertically aligned livestock operators consolidate additive procurement under outcome-guarantee contracts linking premix supply to feed conversion performance. Four Brazilian broiler processors control two-thirds of national feed demand through captive supply arrangements.
- Feed Manufacturers:Independent compound feed mills face volume pressure from integrator self-supply and require differentiated technical service offerings to defend position.
- Livestock Farms:On-farm mixing operations purchase base mixes and individual additives for custom formulation.
- Pet Food Companies:Specialized manufacturers demand precision vitamin premixes and palatability systems for premium product positioning.
- Research Institutes:Academic and government facilities drive additive efficacy validation and regulatory safety dossier development.
Volume aggregates with integrators; margin protection concentrates with feed manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA and USDA jointly administer feed additive safety protocols across the United States, establishing compliance benchmarks that favor large premix suppliers with dedicated regulatory affairs infrastructure.
United States
Midwestern grain belt fermentation facilities supply bulk amino acid volumes to domestic integrators and export markets. The Food Safety Modernization Act mandates hazard analysis and preventive controls for animal food facilities, elevating compliance costs for smaller premix manufacturers. Iowa and Illinois host concentrated enzyme production clusters serving North American poultry and swine operations.
Brazil
Livestock exporters scale probiotic and enzyme adoption to satisfy China-bound meat certification requirements under Codex Alimentarius alignment. ANVISA enforces residue limits that lag EU detection thresholds, creating formulation gaps for certain additive categories. São Paulo and Paraná states anchor fermentation capacity expansion for methionine and lysine production serving Mercosur harmonization.
China
Domestic livestock producers drive precision amino acid fortification demand as protein self-sufficiency targets intensify. The Ministry of Agriculture maintains separate safety dossier requirements for enzyme approvals, extending commercialization timelines for foreign suppliers. Shandong and Jiangsu provinces concentrate vitamin premix manufacturing for industrial feed mill customers.
Germany
Industrial feed manufacturers reformulate delivery matrices to comply with REACH chemical safety revisions and F-Gas Regulation carrier restrictions. EFSA antibiotic growth promoter bans accelerate probiotic incorporation rates across Bavarian and Lower Saxon livestock operations. Baden-Württemberg hosts biotechnology platforms specializing in patent-protected microbial strains for enzyme production.
Vietnam
Industrial broiler integrators mandate precision additive fortification to achieve export-grade feed conversion ratios for Japanese and South Korean poultry markets. National feed safety standards incorporate ASEAN harmonized MRLs for antibiotic residues in compound feeds. Mekong Delta feed mill clusters drive volume concentration for amino acid and enzyme procurement.
Animal Feed Additives Market Competitive Landscape
Diversified agricultural conglomerates and specialized biotechnology platforms split the market between volume-scale amino acid production and precision-formulation premix services. The vendor base concentrates around fermentation-derived categories where bioprocess complexity and strain patent protection create defensible margin pools. Three archetypes dominate: backward-integrated grain processors, dedicated fermentation biotechnology specialists, and precision nutrition premix formulators. Capacity expansion and captive supply arrangements constitute the dominant competitive moves as input volatility pressures margin structures.
Among diversified agricultural processors, Cargill and Archer Daniels Midland Company occupy positions anchored in Midwestern U.S. grain belt infrastructure. Evonik Industries exemplifies the European biotechnology specialist archetype with dedicated fermentation platforms. The dsm-firmenich combination represents precision nutrition formulation capabilities competing on vitamin premix technical services.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Alltech |
| Evonik Industries |
| dsm-firmenich |
| Adisseo |
| Kemin Industries |
| Nutreco |
| Novonesis |
| Others |
Pricing and Supply Chain Analysis
São Paulo and Paraná states anchor fermentation capacity expansion that transfers upstream cost volatility directly into methionine and lysine contract negotiations, compressing margin buffers for premix manufacturers lacking captive biotech platforms.
Pricing Analysis
Midwestern U.S. grain futures spreads against Brazilian export parity create divergent amino acid landed costs across Atlantic and Pacific trade lanes. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and commodity-grade specifications reflects EFSA residue certification tiers and volume scale commitments. Pricing pressure stems from corn and soybean meal feedstock swings, forcing spot-market exposure on smaller formulators. Independent feed mills exhibit acute price sensitivity; integrators with captive supply arrangements absorb volatility through long-term offtake structures.
Supply Chain Analysis
Corn and soybean meal feedstock sourcing draws from Iowa and Illinois grain belts, Brazilian cerrado production zones, and Argentine pampas cultivation regions. Phytase and carbohydrase enzyme production rests on patent-protected microbial strain licensing from Baden-Württemberg biotechnology platforms. Single-source strain dependencies expose Asian premix formulators to supply interruption. Distribution runs through integrator self-supply networks and independent compound feed mill procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as four Brazilian broiler processors capture two-thirds of national feed demand, fragmenting pricing leverage for additive suppliers without outcome-guarantee contract structures.
For Market Incumbents: Build fermentation capacity moats through backward integration into Midwestern U.S. grain belt sourcing or Brazilian Mercosur-aligned production hubs. Commission dedicated biotech platforms to neutralize input volatility from corn and soybean meal futures swings. Secure EFSA and FDA enzyme approval dossiers ahead of EU Green Deal antibiotic restriction deadlines to lock in probiotic substitution demand. For New Entrants and Emerging Players: Sub-Saharan African poultry expansion in Nigeria and Kenya offers greenfield feed mill construction partnerships with minimal incumbent premix presence. Target vitamin blending facilities for local formulation capability rather than competing on bulk amino acid fermentation scale. Lead with precision nutrition software bundling to differentiate against established suppliers' static premix models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision nutrition formulators with real-time NIR spectroscopy integration over commodity-scale fermentation operators. Five-to-ten year viability hinges on carbon-accounting credential verification for methane-reduction additives under EU CSRD scope 3 disclosure mandates. Monitor enzyme approval pathway synchronization across EFSA, FDA, and Chinese Ministry of Agriculture as inflection indicator for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Brazilian methionine and lysine buildout secures Mercosur export-grade protein compliance under ANVISA-Codex alignment. |
| Backward Integration into Grain Sourcing | Midwestern U.S. corn belt control neutralizes feedstock cost volatility compressing amino acid producer margins. |
| Enzyme Approval Dossier Investment | EFSA and FDA safety submissions accelerate probiotic market access as EU antibiotic growth promoter bans phase in. |
| Precision Nutrition Software Convergence | Real-time NIR spectroscopy dosing locks in feed conversion gains for Vietnamese and Indonesian broiler integrators. |
| Carbon-Accounting Credential Development | Verified methane-reduction additive certification captures premium pricing under EU CSRD livestock disclosure requirements. |
Research Methodology
Desk research of FDA enforcement records, EFSA additive safety opinions, Brazilian ANVISA residue limit publications, and ASEAN feed safety harmonization documents preceded structured interviews with fermentation plant managers, premix procurement leads at Brazilian integrators, enzyme R&D directors, and regulatory affairs specialists at vitamin formulators. Primary fieldwork combined with customs trade data, SEC filings from diversified agricultural processors, and Codex Alimentarius MRL databases enabled bottom-up volume triangulation against top-down protein demand modeling.
Assumptions held fixed include EU Green Deal antibiotic restriction phase-in schedules, Mercosur harmonization timelines, and Chinese protein self-sufficiency targets; variables included corn and soybean meal price volatility bands, enzyme approval pathway durations, and CSRD scope 3 disclosure adoption rates across the analysis window. Segmentation modeling incorporated product chemistry tiers, species-specific application requirements, physical form delivery systems, and end-user scale categories. CAGRs derived from iterative reconciliation of fermentation capacity buildout announcements against feed mill consumption surveys.
Practitioners should monitor EFSA enzyme safety opinion publication cadence, Brazilian ANVISA residue limit enforcement stringency, and EU F-Gas Regulation carrier material restriction expansions for early signals necessitating forecast revision. Cross-checking against FAO protein production statistics and national feed industry association consumption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
North America Animal Feed Additives Market