
 PM2.5 Sensors Market | 2026-2036
PM2.5 Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
PM2.5 Sensors Market Analysis
Direct-to-municipality procurement channels are reshaping how PM2.5 sensor vendors reach end-users. Honeywell leverages its building automation footprint to anchor large-scale indoor air quality contracts across North American commercial real estate. Sensirion specializes in miniaturized optical sensing modules that compete for design wins inside consumer electronics and HVAC integration. Bosch Sensortec sustains R&D intensity in low-power MEMS-based detection, positioning its portfolio for wearable and mobile applications where battery life dominates purchasing criteria.
PM2.5 sensors detect airborne particulate matter with aerodynamic diameters of 2.5 micrometers or less, typically employing light-scattering or beta-attenuation methods to quantify mass concentration in micrograms per cubic meter for regulatory compliance and health protection. Optical technology leads unit shipments due to its balance of cost and real-time output, while LIDAR-based systems command premium positioning in environmental research and regulatory-grade monitoring networks where spatial resolution justifies higher expenditure. Fixed outdoor sensors dominate infrastructure-led deployments, whereas portable units are gaining traction among industrial health and safety teams requiring mobile compliance verification.
The EPA enforces National Ambient Air Quality Standards that mandate PM2.5 monitoring around major emission sources, directly stimulating replacement cycles and densification of monitoring grids. ISO 23210 and equivalent national calibration protocols determine which sensor architectures qualify for regulatory reporting, creating a certification barrier that favors established metrology vendors. Stakeholders must monitor evolving WHO air quality guidelines and their adoption into binding national frameworks, as these transitions historically trigger wholesale sensor upgrades and new procurement windows.
Market Dynamics
Smart city infrastructure mandates in China are compressing procurement cycles for outdoor PM2.5 sensor networks, forcing vendors to reconfigure supply chains for high-volume, low-margin municipal contracts while maintaining regulatory-grade calibration standards.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Tightened ambient monitoring requirements around major industrial sources are triggering replacement cycles and grid densification across the United States.
- Optical sensing miniaturization:Advances in laser diode and photodetector integration are enabling sub-10-gram sensor modules for consumer electronics and HVAC system integration.
- East Asian metropolitan corridors:Regulatory enforcement convergence with urban densification in Shanghai, Seoul, and Tokyo is concentrating demand for continuous outdoor monitoring infrastructure.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korea dominate specialty semiconductor manufacturing for low-power detection elements, creating single-source vulnerability.
- Calibration gas supply volatility:Certified reference materials for PM2.5 sensor validation face price instability due to purified aerosol production bottlenecks.
- ISO 23210 certification timelines:Multi-month approval processes for regulatory-grade architectures delay market entry for new sensor designs.
Strategic Opportunities
- India's Smart Cities Mission:Federal funding for urban air quality infrastructure in 100 designated cities creates a procurement window for outdoor sensor networks.
- Wearable health integration:Convergence of PM2.5 sensing with pulse oximetry and GPS tracking enables personal exposure mapping for outdoor workers and athletes.
- EU Green Deal implementation:National adaptation of WHO air quality guidelines into binding frameworks will trigger wholesale sensor upgrades across member states.
Industry Challenges
- Metrology talent scarcity:Specialized expertise in aerosol physics and optical calibration remains concentrated in national standards laboratories and select academic centers.
- Cross-platform integration complexity:Legacy building management systems require custom protocol adaptation for real-time PM2.5 data ingestion, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PM2.5 Sensors Market |
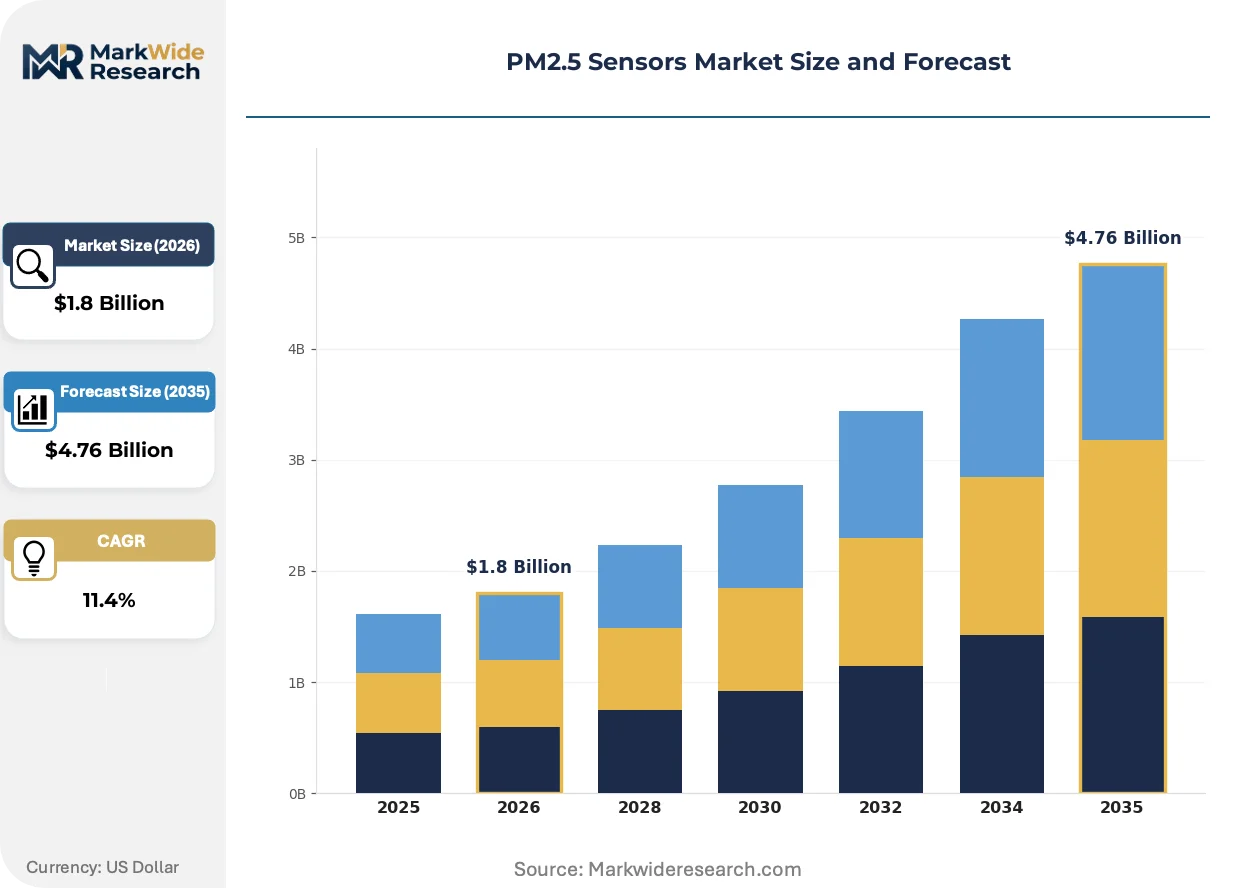
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sensors, Fixed Sensors, Indoor Sensors, Outdoor Sensors Technology: LIDAR, Optical, Electrochemical, Gravimetric End User: Residential, Commercial, Government, Industrial Application: Air Quality Monitoring, Environmental Research, Industrial Emissions, Health & Safety |
| Companies Covered | Siemens, TSI, Honeywell, Rohde & Schwarz, 3M, Bosch Sensortec, Teledyne, Aeroqual, Sensirion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PM2.5 Sensors Market Emerging Trajectories
Light-scattering architectures are undergoing rapid performance recalibration as beta-attenuation methods face cost pressure in regulatory networks. Three converging developments are reshaping competitive positioning across the value chain.
Electrochemical sensing is migrating from industrial safety applications toward residential indoor air quality monitors as cost curves compress below five-dollar module pricing. Chinese white-label manufacturers are absorbing volume from branded consumer electronics suppliers. This migration is collapsing the traditional three-tier price segmentation that separated laboratory, commercial, and consumer-grade detection.
The EU's Corporate Sustainability Reporting Directive now mandates granular air quality disclosure for large industrial installations, compelling facilities to install continuous monitoring rather than periodic manual sampling. Metal processing and cement manufacturing sites in Germany and Poland are accelerating capital expenditure timelines to meet 2025 reporting deadlines. Third-party verification services are capturing value previously retained by sensor vendors.
Municipal procurement teams are consolidating vendor relationships through framework agreements that bundle installation, calibration, and data analytics into multi-year service contracts. Direct sensor sales are losing share to integrated air quality management platforms in Scandinavian and Benelux urban markets. Copenhagen and Amsterdam have piloted subscription-based models where payment ties to uptime guarantees rather than hardware transfer.
PM2.5 Sensors Market Segmentation
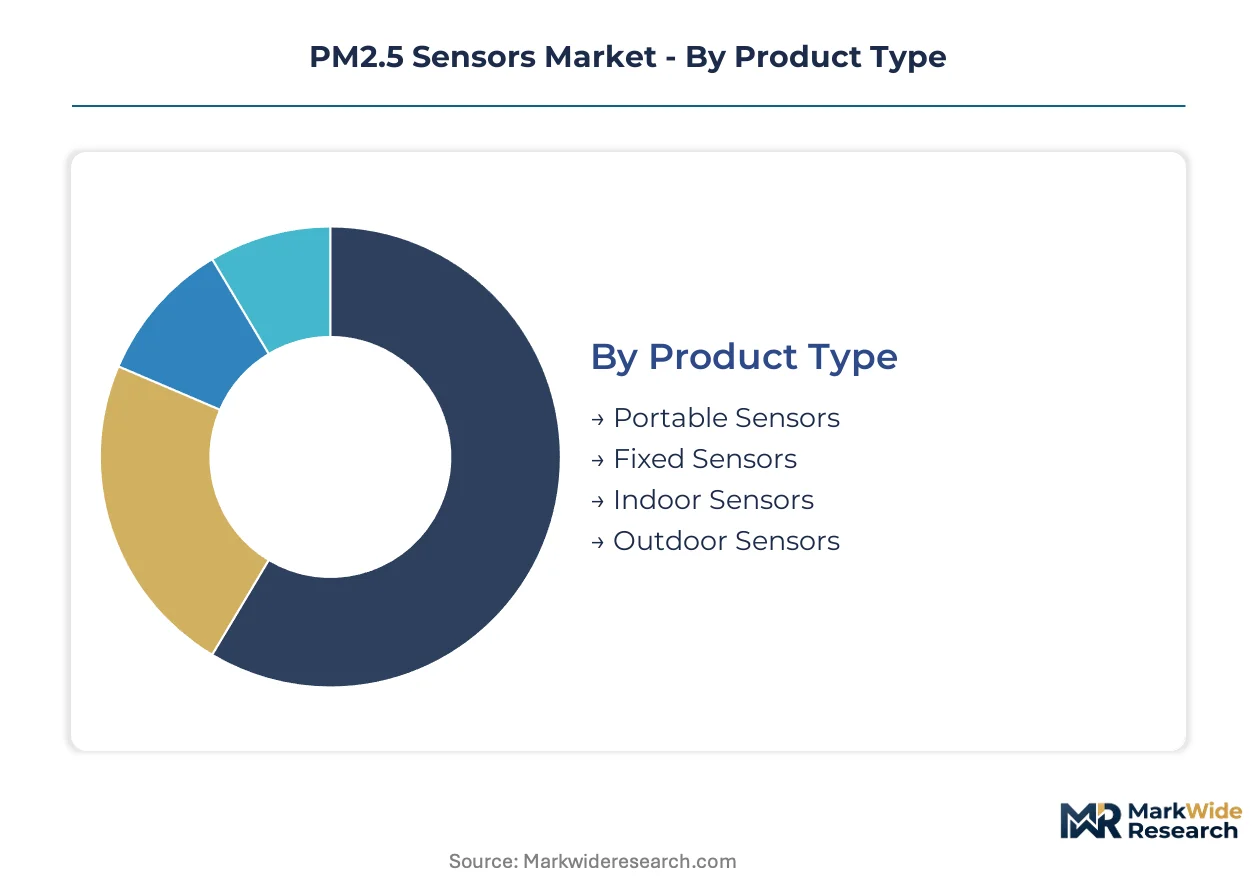
PM2.5 sensor architectures diverge sharply across deployment contexts, with regulatory compliance requirements and power constraints dictating technology selection. Understanding segment boundaries enables vendors to align R&D investment with procurement channels that concentrate volume and margin.
Product Type:
Mature fixed installations dominate municipal infrastructure budgets, while portable formats emerge as the fastest-expanding category for industrial health verification and consumer mobility.
- Fixed Sensors:Permanent installations employ beta-attenuation or optical scattering in weather-hardened enclosures for continuous regulatory reporting. Municipal networks in Shanghai, Seoul, and Tokyo anchor procurement volume through smart city framework agreements.
- Portable Sensors:Battery-powered units integrate MEMS optical modules for spot-check compliance in industrial facilities and personal exposure assessment. Field teams in cement manufacturing and metal processing drive replacement cycles as OSHA inspection protocols tighten.
- Indoor Sensors:Compact optical modules target HVAC integration and commercial building automation with sub-10-gram form factors.
- Outdoor Sensors:Hardened enclosures with heated inlet systems prevent condensation artifacts in extreme humidity environments.
Fixed sensors handle the majority of throughput; portable units are climbing the fastest on share as industrial safety teams adopt mobile verification protocols.
Technology:
Cost tier stratification separates research-grade precision from mass-market accessibility, with optical platforms capturing the middle ground where real-time output meets acceptable accuracy.
- Optical:Light-scattering architectures using laser diodes and photodetectors balance unit economics with continuous measurement capability. Consumer electronics and HVAC integration absorb the highest shipment volumes as Chinese white-label manufacturers compress module pricing below five dollars.
- LIDAR:Pulsed laser systems deliver spatially resolved particulate mapping for environmental research and regulatory-grade networks. Atmospheric scientists in German and Polish research institutes justify premium expenditure for three-dimensional concentration profiles.
- Electrochemical:Solid-state designs migrate from industrial gas detection toward residential indoor monitors as manufacturing scale reduces per-unit cost.
- Gravimetric:Filter-based mass collection remains the reference method for EPA and ISO 23210 certification protocols.
Optical technology commands the dominant share of unit shipments; LIDAR systems show the steepest expansion trajectory in research and regulatory network procurement.
End User:
Customer type determines calibration rigor and contract structure, with government procurement favoring multi-year service bundles over hardware transfer.
- Government:Municipal environmental agencies mandate ISO 23210-certified architectures with third-party verification for National Ambient Air Quality Standards compliance. Copenhagen and Amsterdam have pioneered subscription models tying payment to uptime guarantees rather than capital expenditure.
- Industrial:Cement manufacturing and metal processing facilities accelerate capital expenditure to meet EU Corporate Sustainability Reporting Directive disclosure requirements. German and Polish installations face 2025 deadlines for continuous monitoring installation.
- Commercial:Building automation contracts bundle PM2.5 sensing with energy management platforms across North American commercial real estate portfolios.
- Residential:Consumer electronics integration drives demand for miniaturized modules in air purifiers and smart home devices.
Government end users concentrate the highest contract value; industrial accounts are expanding most quickly as mandatory disclosure rules proliferate.
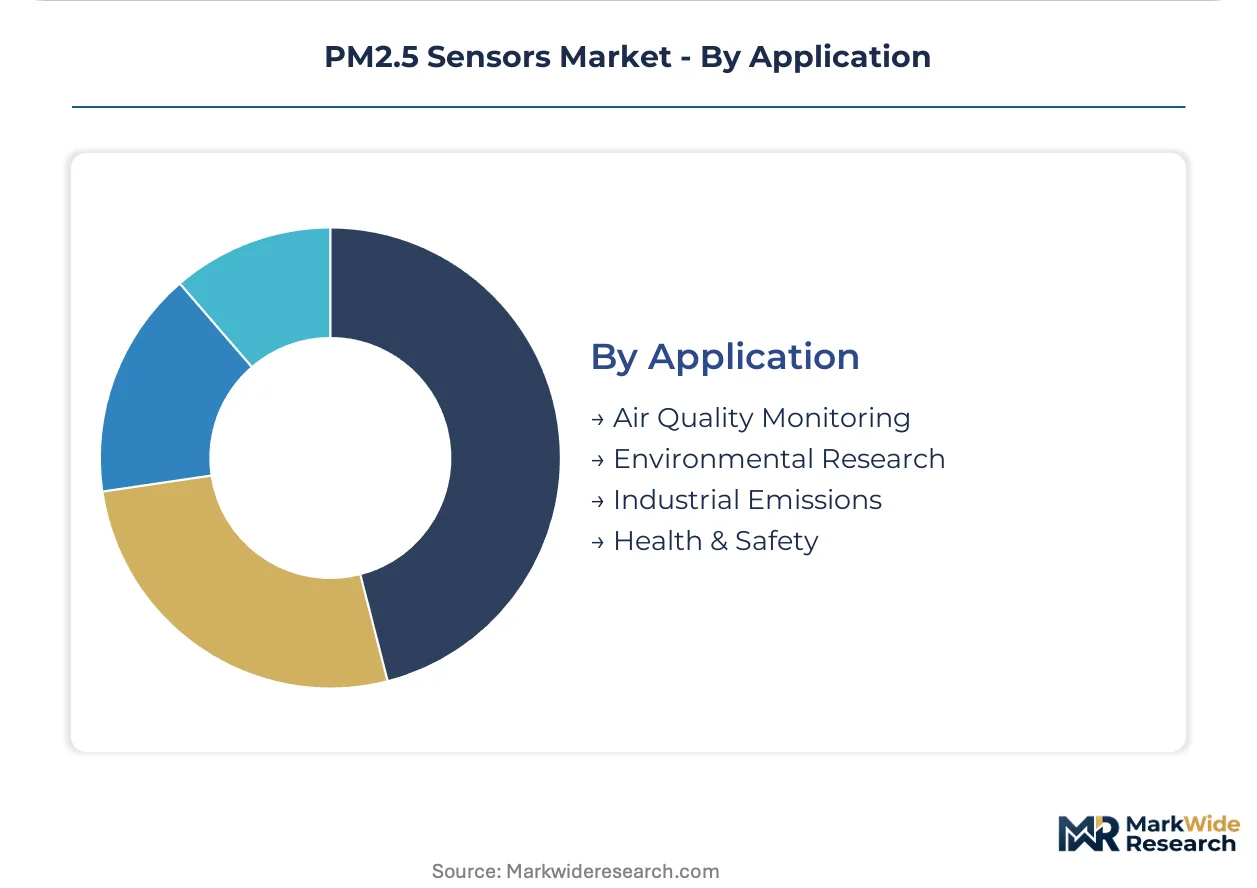
Application:
Application scope maps directly to performance tier requirements, with regulatory reporting demanding stricter metrology than occupational safety or consumer awareness.
- Air Quality Monitoring:Continuous outdoor networks for regulatory compliance and public health alerting. EPA tightened standards trigger replacement cycles and grid densification around major emission sources in the United States.
- Industrial Emissions:Stack monitoring and perimeter surveillance for environmental permit compliance. Metal processing sites in Germany deploy continuous systems to satisfy EU Green Deal implementation timelines.
- Environmental Research:Academic and governmental studies requiring high spatial and temporal resolution for atmospheric modeling.
- Health & Safety:Personal exposure assessment for outdoor workers and athletes through wearable integration with pulse oximetry and GPS tracking.
Air quality monitoring absorbs the dominant share of installed base value; industrial emissions applications are gaining share fastest as mandatory disclosure expands across manufacturing sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai high-speed rail corridor underwrites China's dominance in smart city sensor deployment, while the Rhine-Main-Danube waterway network supports industrial monitoring infrastructure across Central Europe. These backbone assets determine where procurement capital concentrates.
China
Smart city mandates in 100 designated metropolitan areas compress procurement timelines for outdoor sensor networks. MEE enforcement of GB 3095-2012 ambient air quality standards triggers continuous monitoring installation around steel mills and coal-fired plants. Yangtze River Delta municipalities including Shanghai and Hangzhou anchor volume through framework agreements bundling hardware, calibration, and data analytics.
United States
EPA tightened National Ambient Air Quality Standards compel grid densification around petrochemical corridors and power generation facilities. OSHA inspection protocol revisions accelerate portable sensor adoption among industrial health and safety teams. Gulf Coast refining clusters in Texas and Louisiana face replacement cycles for legacy beta-attenuation monitors as real-time optical systems achieve regulatory equivalency.
Germany
EU Corporate Sustainability Reporting Directive deadlines in 2025 force continuous monitoring installation at metal processing and cement manufacturing sites. ECHA coordination of REACH-aligned emissions disclosure creates third-party verification demand previously retained by sensor vendors. Rhine-Ruhr industrial belt facilities in North Rhine-Westphalia accelerate capital expenditure to meet granular air quality reporting requirements.
India
Federal Smart Cities Mission funding for urban air quality infrastructure in designated metropolitan areas opens procurement windows for outdoor sensor networks. CPCB enforcement of National Ambient Air Quality Standards tightens around thermal power plants and construction corridors. Delhi-NCR and Mumbai metropolitan authorities issue tenders for dense monitoring grids covering industrial peripheries and traffic corridors.
Japan
METI promotion of environmental sensor exports supports domestic manufacturers targeting Asian smart city contracts. JIS standards alignment with ISO 23210 calibration protocols maintains certification barriers favoring established metrology vendors. Kanto region municipalities including Tokyo and Yokohama deploy hardened outdoor sensors with heated inlet systems for extreme humidity performance.
PM2.5 Sensors Market Vendor Landscape
On the supply side, the industry is bifurcated between regulatory-grade metrology specialists and high-volume module suppliers serving consumer electronics integration. Tier-one positions concentrate around diversified industrial conglomerates with building automation footprints, while mid-tier specialists compete on miniaturization and power efficiency. Strategic archetypes include integrated platform vendors, component module specialists, and calibration service providers. Competitive moves center on multi-year service contract bundling and backward integration into MEMS foundry partnerships.
Among diversified industrial technology groups, Siemens and Honeywell exemplify platform-integrated positioning through building automation and industrial control system anchoring. Bosch Sensortec occupies a specialist position within the low-power MEMS detection segment. These three entities represent distinct competitive vectors: systems integration at scale, miniaturized component supply, and power-optimized sensing architectures respectively.
| Leading Market Players |
|---|
| Siemens |
| TSI |
| Honeywell |
| Rohde & Schwarz |
| 3M |
| Bosch Sensortec |
| Teledyne |
| Aeroqual |
| Sensirion |
| Others |
Supply Flow & Price Mechanics
Single-source MEMS foundry concentration in Taiwan and South Korea generates simultaneous pricing tier compression and supply vulnerability, forcing buyers into long-term offtake contracts that lock in volume-discount structures while accepting extended lead-time exposure for optical detection modules.
Pricing Analysis
Volume-discount tiering structures dominate municipal procurement, with framework agreements bundling installation, calibration, and data analytics into multi-year service contracts that eclipse per-unit hardware margins. Pricing stratifies across regulatory-grade, commercial, and consumer tiers based on ISO 23210 certification status and after-sales service bundling. Cost compression in consumer-grade optical modules is intensifying because Chinese white-label manufacturers have collapsed module pricing below five dollars. Government end users exhibit the least price sensitivity due to compliance mandates, while residential consumer electronics integrators demand continuous cost reduction.
Supply Chain Analysis
Export-control regime restrictions on advanced laser diode and photodetector technologies limit flows from US and Japanese suppliers to Chinese module assemblers, fragmenting sourcing strategies. Taiwan, South Korea, and China anchor specialty semiconductor manufacturing for low-power detection elements, with purified aerosol calibration gas production concentrated in Germany and the United States. Single-source vulnerability in MEMS foundry capacity creates chokepoint exposure for optical sensor architectures. Distribution runs through direct-to-municipality channels and building automation integrators, with subscription-based service platforms capturing increasing downstream value in Scandinavian and Benelux markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including calibration, data analytics, and uptime guarantees are expanding faster than hardware transfer, transforming vendor economics toward recurring-revenue models that improve customer lifetime value and reduce churn.
For Market Incumbents: Pre-empt white-label commoditization by deepening backward integration into MEMS foundry partnerships that secure captive supply of low-power detection elements. Anchor multi-year framework agreements with municipal procurement teams before India's Smart Cities Mission accelerates competitive tendering. Certification investment in ISO 23210 equivalency for real-time optical systems defends positioning against beta-attenuation incumbents in EPA-regulated networks.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with HVAC integration demand outpacing established vendor coverage. Portable industrial health and safety units for cement manufacturing and metal processing sites offer second-mover advantage as OSHA inspection protocols tighten. A calibration-service-first go-to-market angle bypasses capital-intensive hardware development while building regulatory relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform vendors with building automation footprints over pure-play component suppliers. Long-term viability hinges on recurring-revenue mix and municipal contract tenure rather than hardware shipment volume. Acquisition targets should demonstrate framework agreement scale in 3+ metropolitan markets. The signal to watch is EU member state transposition of WHO air quality guidelines into binding frameworks, which would trigger wholesale sensor upgrade procurement windows.
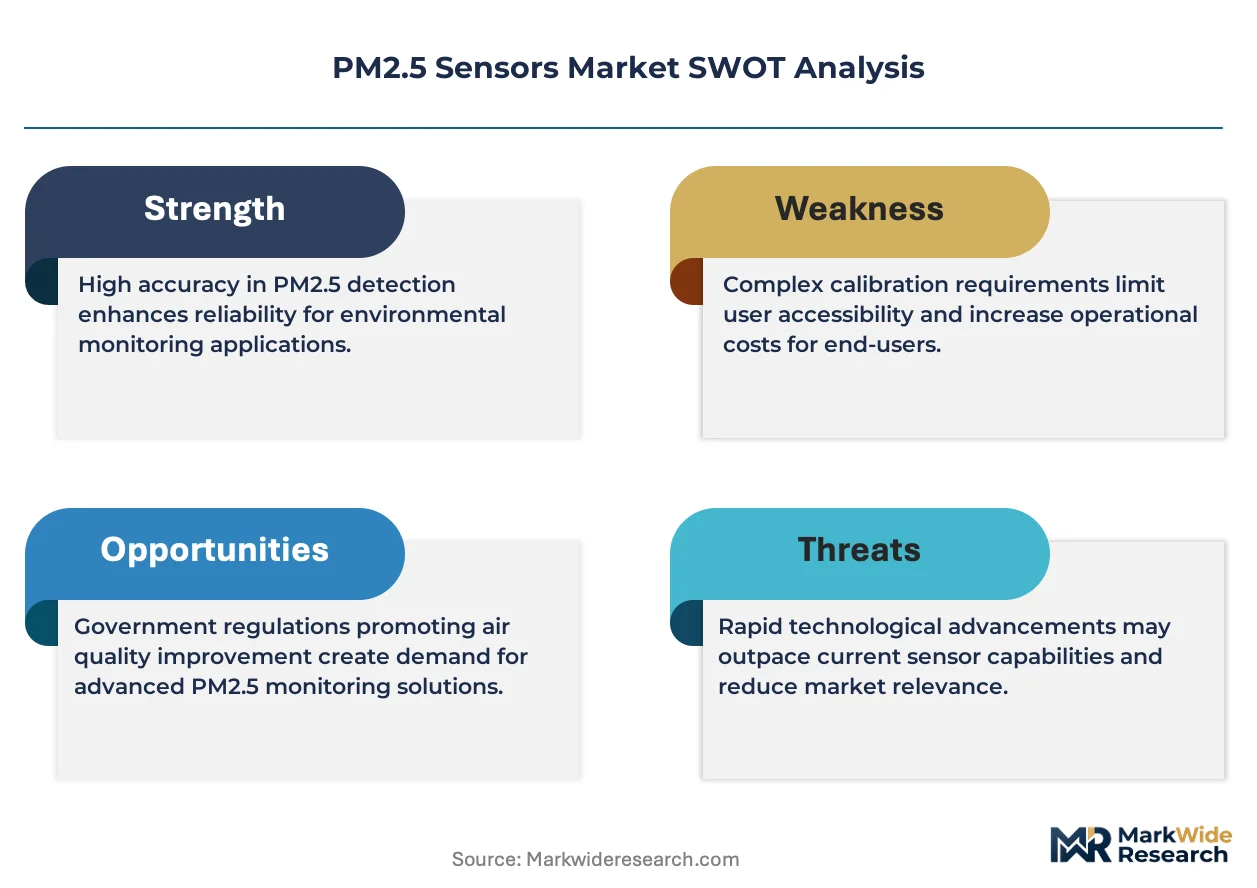
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Partnerships | Captive supply of low-power detection elements reduces single-source vulnerability and stabilizes module cost curves. |
| Framework Agreement Consolidation | Copenhagen and Amsterdam subscription models tie payment to uptime guarantees, improving revenue predictability. |
| Calibration Service Platform Launch | Third-party verification services capture value previously retained by sensor vendors under EU Corporate Sustainability Reporting Directive. |
| Wearable Health Integration Development | Convergence with pulse oximetry and GPS tracking enables personal exposure mapping for outdoor workers and athletes. |
| Regulatory-Grade Optical Certification | ISO 23210 equivalency for real-time systems displaces legacy beta-attenuation monitors in EPA National Ambient Air Quality Standards networks. |
Methodological Framework
The analysis maps fixed outdoor, portable, indoor, and outdoor hardened sensor sub-sectors, each validated through municipal procurement officers, industrial health and safety directors, building automation integrators, and calibration service providers. Primary interviews with environmental monitoring specialists and HVAC system engineers combined with secondary validation from EPA enforcement records, ISO 23210 certification databases, EU Corporate Sustainability Reporting Directive implementation filings, and smart city tender documentation. Bottom-up shipment estimates by technology and application triangulated against top-down infrastructure budget allocations across the analysis window.
Assumption sets held regulatory enforcement timelines and ambient air quality standard stringency fixed while varying smart city procurement acceleration scenarios and MEMS foundry capacity utilization rates. Segmentation dimensions modeled include product format, detection technology, end-user category, and application scope alongside regional regulatory cluster adoption patterns. CAGRs derived from weighted average of historical replacement cycles and projected densification mandates. Industry-specific inputs incorporated EPA grid densification requirements and EU Green Deal implementation timelines for industrial emissions monitoring.
Macroeconomic conditions sit as an overlay; deviation in municipal infrastructure budgets or semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and calibration gas supply stability. Material shifts in EPA National Ambient Air Quality Standards stringency or ISO 23210 protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Smart Haptic Devices Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Tactile Indicators Market