
 Europe Liability Insurance Market | 2026-2036
Europe Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Liability Insurance Market Analytics
Parametric underwriting platforms is reconfiguring how European carriers assess and price casualty exposure. Allianz leverages proprietary IoT sensor networks to refine real-time risk scoring for industrial clients. Munich Re anchors its competitive stance through reinsurance capacity that absorbs peak liability layers across multiple European jurisdictions. Zurich Insurance Group specializes in multinational program structures that harmonize coverage across EU member states with divergent tort regimes.
Europe liability insurance constitutes a contractual risk-transfer mechanism where insurers assume legal defense costs and indemnity obligations arising from third-party bodily injury, property damage, or financial loss attributable to an insured's operations, products, or professional services. Policies incorporate claims-made or occurrence triggers, retroactive dates, and aggregate limits calibrated to exposure severity. Professional indemnity coverage leads premium generation as financial services and technology advisory exposures expand across the region. Product liability lines exhibit concentrated growth in pharmaceutical and medical device verticals where strict liability doctrines under the EU Product Liability Directive amplify claimant recovery. General liability remains mature in construction and manufacturing, though margin pools shift toward environmental impairment and cyber-physical damage endorsements.
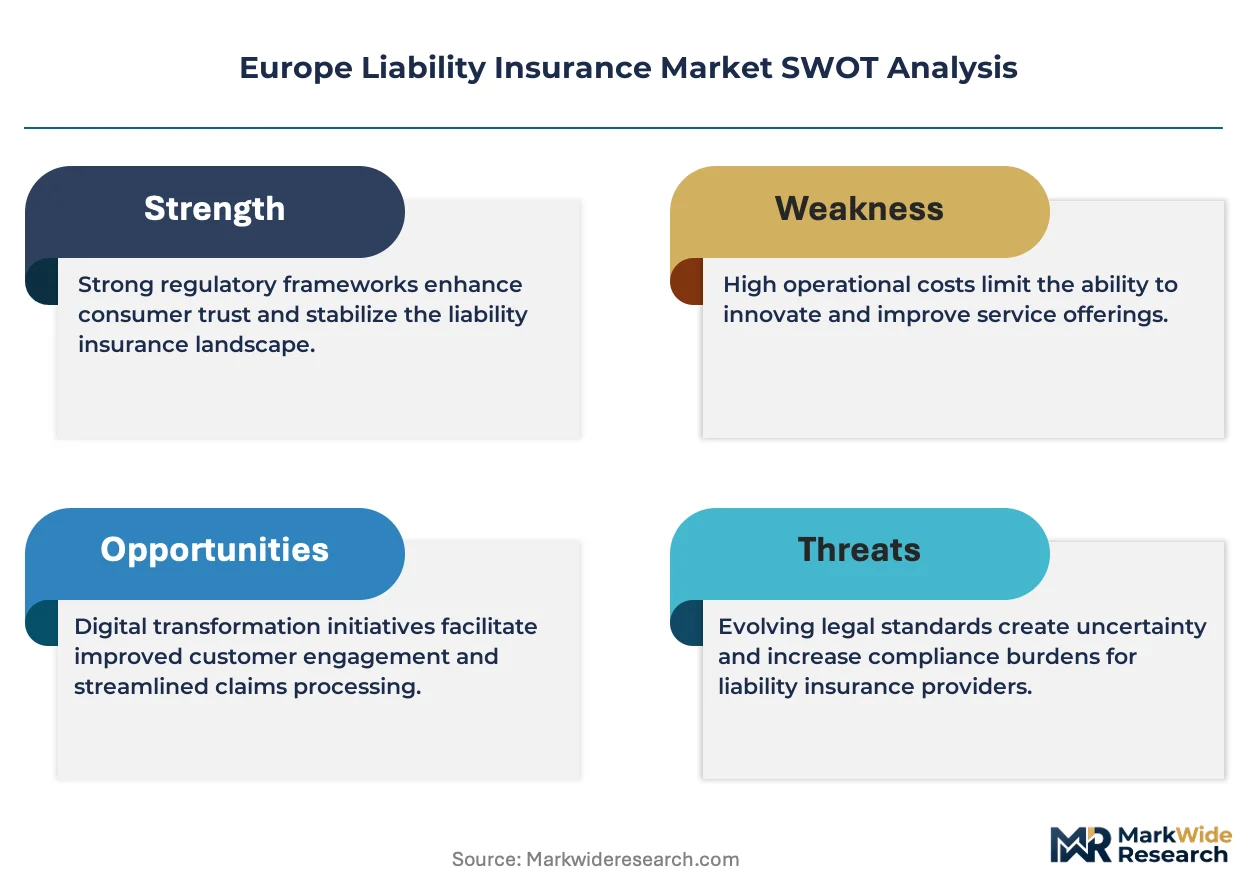
The EU AI Act, Solvency II framework, and national conduct regulators including BaFin and the UK's Prudential Regulation Authority collectively reshape carrier capital requirements and policy form standards. EIOPA's stress-testing protocols force insurers to hold additional reserves against long-tail casualty reserves, compressing underwriting capacity for complex risks. Stakeholders must monitor how the EU Green Deal's expanding environmental liability directives alter coverage triggers for pollution and biodiversity loss before renewing industrial program structures.
Market Dynamics
The EU AI Act's algorithmic accountability mandates are forcing corporate legal departments across Germany, France, and the Netherlands to expand professional indemnity coverage before deploying automated decision systems.
Growth Catalysts
- EU AI Act compliance mandates:Financial services and technology advisory firms in Frankfurt and London face mandatory algorithmic risk coverage requirements, expanding professional indemnity demand.
- IoT sensor deployment:Industrial manufacturing clusters across the Ruhr Valley and northern Italy are adopting connected monitoring systems that generate real-time exposure data for parametric underwriting.
- Strict liability expansion:The EU Product Liability Directive's pharmaceutical and medical device interpretations are amplifying claimant recovery pathways, concentrating growth in product liability lines.
Market Restraints
- EIOPA stress-testing reserves:Solvency II capital requirements force carriers to hold additional reserves against long-tail casualty exposures, compressing underwriting capacity for complex risks.
- Retroactive date limitations:Claims-made policy structures create coverage gaps for legacy environmental and asbestos exposures that predate 2000 policy periods.
- Jurisdictional fragmentation:Divergent tort regimes between German civil law traditions and English common law principles complicate multinational program harmonization.
Strategic Opportunities
- Cyber-physical damage endorsements:Industrial IoT integration creates unmet demand for policies covering property damage triggered by network security failures in manufacturing automation.
- Environmental liability directives:The EU Green Deal's expanding biodiversity loss and pollution coverage triggers open new product development pathways for industrial program renewals.
- Parametric distribution platforms:Digital broker networks connecting SME buyers with algorithmic pricing engines represent underpenetrated channel expansion in Spain and Poland.
Industry Challenges
- Actuarial talent scarcity:Specialized expertise in AI-driven risk modeling and climate scenario analysis remains concentrated among a limited pool of quantitative professionals in London and Zurich.
- Legacy system integration:Established carriers face friction embedding real-time sensor data streams into decades-old policy administration platforms.
- Cross-border claims coordination:Multi-jurisdictional litigation involving EU member states requires harmonized defense cost allocation mechanisms that current treaty structures inadequately address.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Liability Insurance Market |
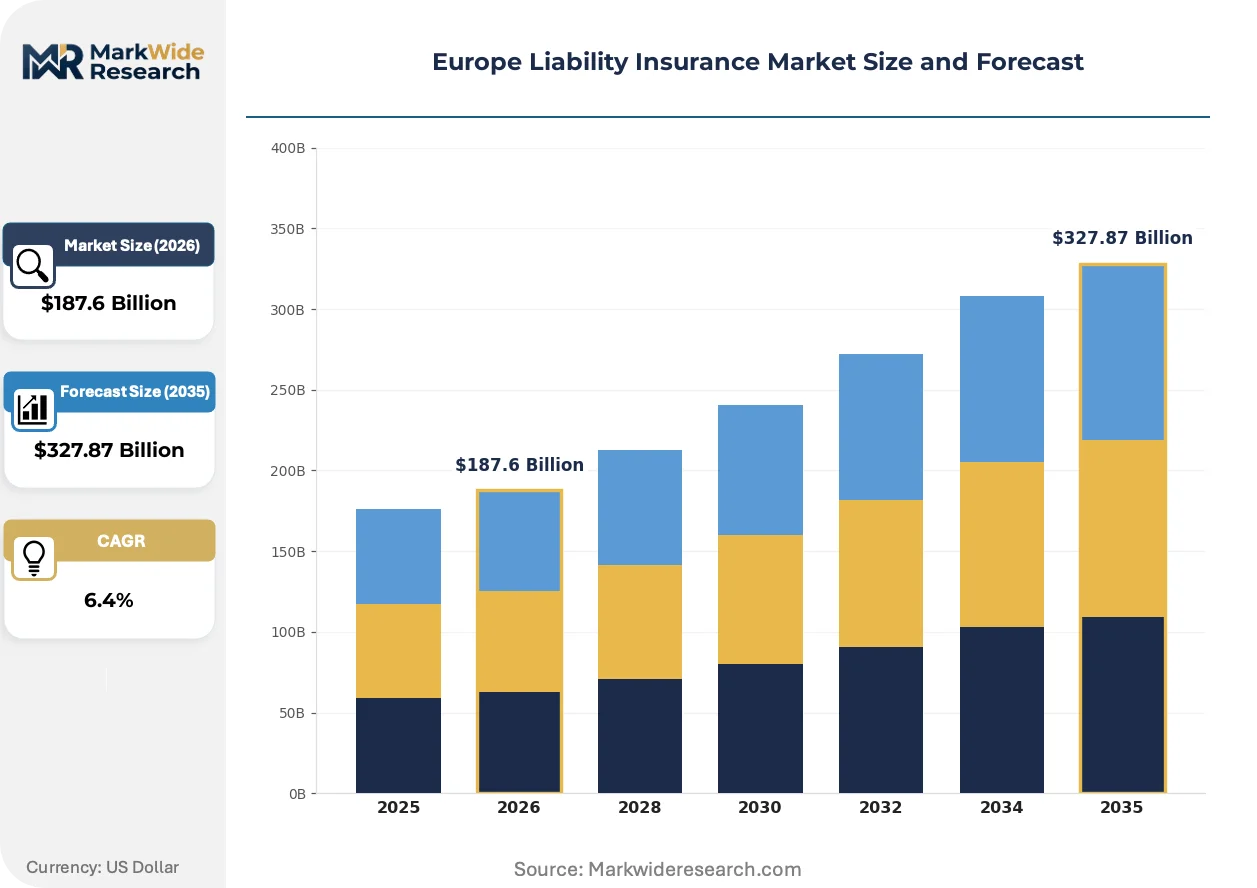
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $327.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: General Liability, Professional Indemnity, Product Liability, Employers' Liability Industry Vertical: Construction, Manufacturing, Healthcare, Retail Policyholder Type: Corporations, SMEs, Individuals, Non-profits Premium Structure: Fixed, Variable, Pay-as-you-go, Bundled |
| Companies Covered | AXA, Allianz, Assicurazioni Generali, Munich Re, Zurich Insurance Group, Lloyd's, HDI Group, Chubb, Swiss Re, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Liability Insurance Market Evolving Landscape
Parametric underwriting architectures are compressing traditional risk assessment cycles while regulatory technology mandates reshape coverage form standards across European jurisdictions.
Blockchain-enabled smart contracts are digitizing claims settlement workflows for low-complexity liability exposures. Mid-market industrial buyers in Belgium and the Netherlands are piloting automated indemnity triggers tied to verified IoT incident logs. This infrastructure is digitizing the traditional loss-adjustment function, reducing dispute resolution timelines from quarters to weeks.
The EU AI Act's risk-classification framework is mandating tiered insurance requirements for high-risk algorithmic applications. Deployers of automated credit-scoring and biometric identification systems must demonstrate financial responsibility mechanisms before market entry. Financial services clusters in London and Frankfurt are restructuring professional indemnity programs to satisfy these pre-deployment conditions.
Corporate risk managers are consolidating vendor relationships around carriers offering unified EU-wide program structures. Mid-cap manufacturing enterprises previously purchasing country-specific policies are migrating toward multinational towers with centralized claims handling. This concentration is most visible in cross-border logistics and pharmaceutical distribution verticals operating between Germany, the Netherlands, and Switzerland.
Europe Liability Insurance Market Segmentation
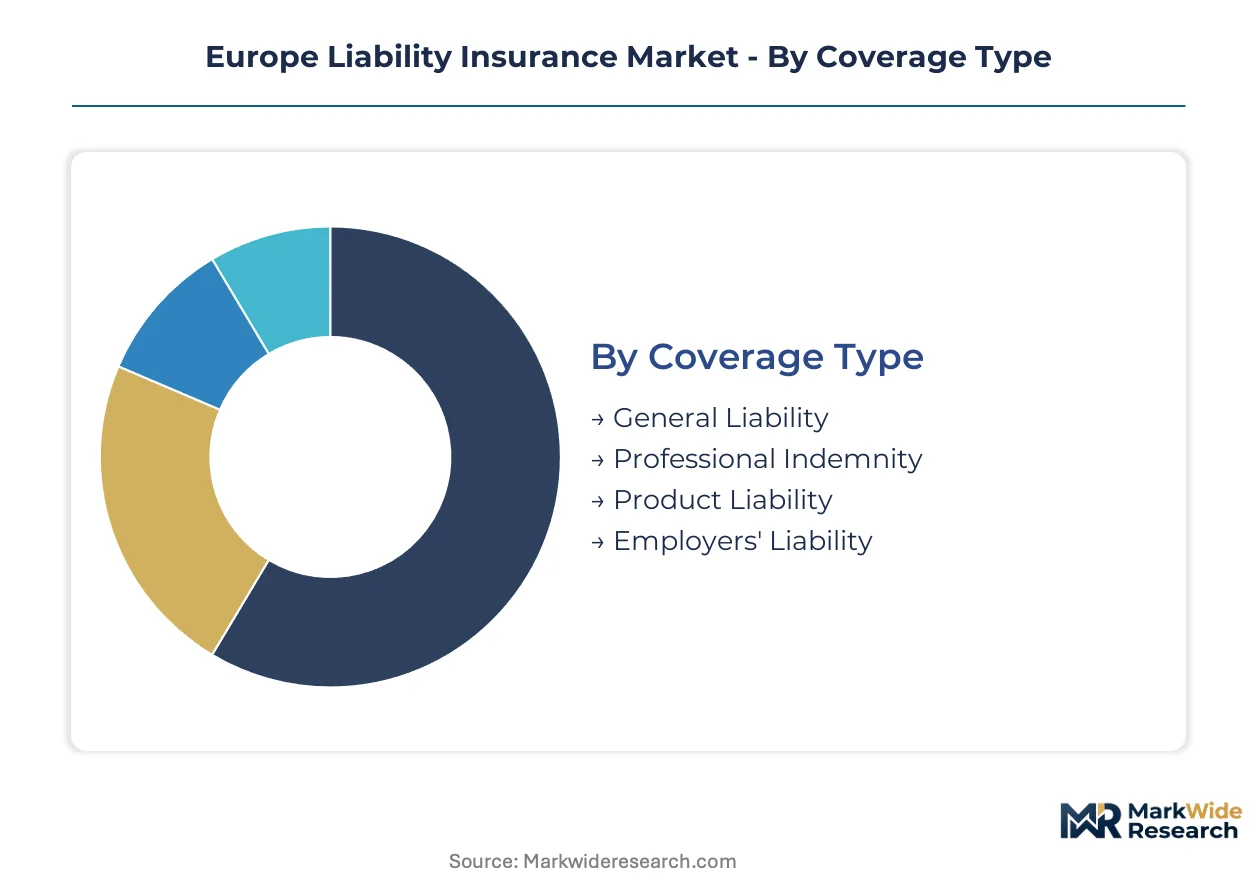
European liability insurance markets fragment across coverage mechanisms, industry exposures, and buyer scale. Each segmentation dimension reveals distinct pricing power dynamics and distribution channel requirements that carriers must navigate.
Coverage Type:
Cost tier differentiation separates baseline protection from specialized indemnity structures with escalating defense cost provisions.
- General Liability:Bodily injury and property damage coverage triggered by premises or operations exposures. Construction contractors in Germany and Spain concentrate purchases here as building activity accelerates across EU cohesion fund projects. Strict liability interpretations under national civil codes amplify settlement severity.
- Professional Indemnity:Financial loss protection arising from negligent advice, design, or professional service delivery. Frankfurt and London financial advisory clusters drive demand concentration as EU AI Act mandates expand algorithmic accountability coverage requirements. Claims-made triggers with retroactive date limitations dominate policy architecture.
- Product Liability:Coverage for bodily injury or property damage caused by defective products. Pharmaceutical and medical device manufacturers face amplified exposure under EU Product Liability Directive strict liability doctrines.
- Employers' Liability:Statutory coverage for workplace injury claims. Mature penetration across northern European markets with state-backed compensation schemes limiting pure private market growth.
Professional Indemnity holds installed capacity. Product Liability is rotating up the share rankings.
Industry Vertical:
Application-specific risk profiles determine loss frequency patterns and reinsurance attachment point requirements.
- Construction:Contractual liability exposures from defect claims and subcontractor negligence. Italian and Polish infrastructure investment cycles concentrate premium generation. Delay-in-start-up endorsements increasingly bundled with core liability towers.
- Manufacturing:Product defect and environmental impairment exposures from industrial processes. German automotive and chemical clusters anchor volume. Supply chain disruption coverage extensions gain traction as just-in-time production amplifies contingent business interruption.
- Healthcare:Medical malpractice and clinical trial liability. French hospital networks and Dutch long-term care facilities represent concentrated buyer pools.
- Retail:Premises liability and product recall exposures. E-commerce logistics networks across Benelux markets expand distribution-related coverage demand.
Manufacturing maintains the deepest premium pool. Construction exhibits the steepest expansion trajectory.
Policyholder Type:
Customer scale determines purchasing sophistication, broker involvement intensity, and program structure complexity.
- Corporations:Multinational program structures with centralized claims handling and EU-wide tower coordination. Cross-border logistics and pharmaceutical distribution verticals operating between Germany, Netherlands, and Switzerland concentrate here.
- SMEs:Standardized coverage through digital distribution platforms and regional broker networks. Underpenetrated pools in Spain and Poland attract parametric pricing innovation.
- Individuals:Personal liability and professional practice coverage for sole practitioners. Limited pure premium contribution relative to commercial segments.
- Non-profits:Directors and officers liability with volunteer protection extensions. Social service providers and cultural institutions in France and Belgium anchor demand.
Corporations command program design resources. SMEs are gaining share fastest through digital channel expansion.
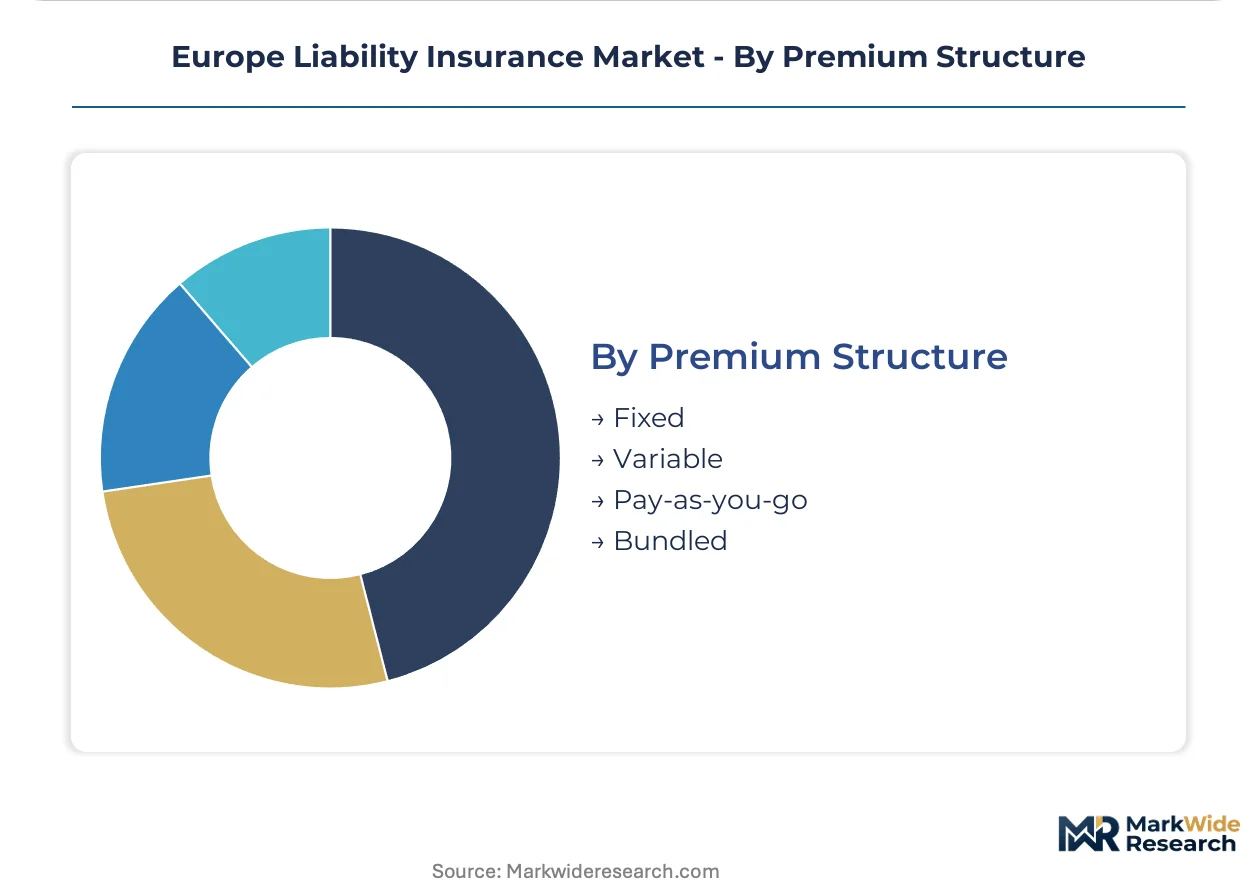
Premium Structure:
Payment mechanism flexibility aligns carrier cash flow with buyer working capital constraints and exposure volatility.
- Fixed:Annual premium determined by audited exposure bases. Traditional manufacturing and construction buyers favor this predictability for budget certainty.
- Variable:Premium adjustments tied to claims experience or exposure metric changes. Mid-cap enterprises with seasonal revenue patterns utilize this structure.
- Pay-as-you-go:Real-time premium calculation from IoT sensor data and actual activity metrics. Industrial IoT deployments across Ruhr Valley manufacturing clusters pilot this approach.
- Bundled:Multi-line packaging with property and casualty coverage. Corporate risk managers consolidating vendor relationships drive adoption.
Fixed structures retain the largest premium base. Pay-as-you-go is climbing the fastest as sensor infrastructure penetrates industrial risks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German liability insurers export capacity to industrial buyers across the Netherlands and Switzerland through integrated cross-border program structures. French carriers serve Mediterranean markets from Paris and Lyon underwriting hubs. London's Lloyd's market anchors specialty lines distribution for European risk buyers.
Germany
Frankfurt's financial advisory clusters and Ruhr Valley manufacturing drive professional indemnity and general liability demand. BaFin's Solvency II implementation forces carriers to hold elevated reserves against long-tail casualty exposures. Munich anchors reinsurance capacity that absorbs peak liability layers across multiple EU jurisdictions.
United Kingdom
London's Lloyd's market and specialty brokers concentrate algorithmic risk coverage for EU AI Act compliance. The Prudential Regulation Authority's stress-testing protocols compress underwriting capacity for complex multinational risks. Birmingham and Manchester industrial zones generate construction liability premium through infrastructure investment cycles.
France
Paris-based financial services and Lyon pharmaceutical manufacturing expand product liability and professional indemnity purchases. ANSM's medical device oversight and CNIL's data protection enforcement amplify coverage requirements for healthcare technology deployers. Île-de-France hospital networks concentrate medical malpractice buyer pools.
Netherlands
Rotterdam logistics hubs and Amsterdam fintech clusters drive distribution-related liability and cyber-physical damage coverage demand. The country's strict liability interpretations under civil code traditions amplify settlement severity for industrial risks. Eindhoven's high-tech manufacturing pilots parametric pay-as-you-go premium structures.
Switzerland
Zurich and Geneva headquarters anchor multinational program structures serving EU-wide corporate buyers. Swissmedic's pharmaceutical oversight and the country's reinsurance expertise concentrate product liability capacity for medical device manufacturers. Basel's chemical and pharmaceutical clusters generate specialized environmental impairment coverage demand.
Europe Liability Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Consolidated capacity concentrates among pan-European carriers with integrated reinsurance arms, while regional mutuals retain local SME relationships. Three archetypes dominate: diversified multinationals with IoT-enabled underwriting platforms, reinsurance-anchored specialists absorbing peak layers, and digital-first distributors targeting underpenetrated mid-market segments. Competitive moves center on parametric pricing engine deployment and cross-border program harmonization capabilities.
Among diversified multinational carriers, Allianz, AXA, and Zurich Insurance Group occupy positions exemplifying integrated IoT and multinational program strengths. Allianz represents the sensor-network-enabled underwriting archetype. AXA sits within the tier emphasizing digital distribution platform scale. Zurich Insurance Group anchors the multinational program harmonization specialist position serving cross-border logistics and pharmaceutical distribution verticals.
| Leading Market Players |
|---|
| AXA |
| Allianz |
| Assicurazioni Generali |
| Munich Re |
| Zurich Insurance Group |
| Lloyd's |
| HDI Group |
| Chubb |
| Swiss Re |
| Others |
Value Network & Pricing Analysis
Overcapacity in London's specialty reinsurance market compresses risk-transfer pricing while Solvency II reserve requirements elevate capital costs for German and French carriers. This utilization asymmetry forces mid-tier insurers toward parametric pricing partnerships and drives ceding commissions higher for peak liability layers.
Pricing Analysis
Legacy actuarial pricing separates from algorithmic-generation underwriting as IoT-enabled pay-as-you-go structures penetrate industrial risks. Three-tier pricing structure across premium multinational programs, standard SME coverage, and economy digital-distributed policies reflects claims-handling sophistication and defense cost provisions. Pricing pressure stems from EIOPA stress-testing protocols that force additional long-tail casualty reserves. SME buyers exhibit highest price sensitivity due to standardized coverage commoditization, while multinational corporations prioritize program harmonization over premium minimization.
Supply Chain Analysis
Extended payment terms from continental European industrial buyers strain carrier cash conversion cycles, prompting supply-chain finance facilities through Lloyd's syndicate structures. Capacity concentrates in Germany, the United Kingdom, and Switzerland as Munich Re and Swiss Re anchor reinsurance supply. Primary carriers draw from London brokerage networks, proprietary IoT sensor data streams, and national regulatory filings as core inputs. Single-source vulnerability runs through algorithmic underwriting talent pools concentrated in London and Zurich. Distribution runs through three-tier structures: global brokers for multinationals, regional networks for mid-market, and digital platforms for SME risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs this market as parametric underwriting APIs and blockchain-enabled smart contracts restructure how risk capital connects with buyer demand. Interoperability between IoT sensor networks and carrier pricing engines represents the decisive ecosystem shift.
For Market Incumbents: Harden algorithmic underwriting capabilities through captive data infrastructure investments that reduce reliance on third-party sensor providers. Consolidate defense cost allocation mechanisms across multi-jurisdictional treaty structures to neutralize cross-border litigation friction. The priority lever centers on embedding real-time exposure data into legacy policy administration platforms before insurtech competitors achieve scale.
For New Entrants and Emerging Players: Build out parametric distribution platforms targeting underpenetrated SME pools in Spain and Poland where traditional broker networks retain coverage gaps. White-space opportunities concentrate in cyber-physical damage endorsements for industrial IoT risks and environmental liability extensions under EU Green Deal directives. A direct digital channel with algorithmic instant-quote engines offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carriers with embedded IoT sensor networks and long-term industrial monitoring contracts. Long-term viability favors diversified multinationals with integrated reinsurance arms over pure-play distributors. Target acquisition profiles should emphasize parametric pricing engine capabilities and cross-border program harmonization expertise. The signal to watch is regulatory technology mandate acceleration under EU AI Act implementation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Network Deployment | Allianz's proprietary infrastructure enables real-time risk scoring that compresses underwriting cycles for industrial clients. |
| Parametric Pricing Engine Development | Algorithmic platforms connecting SME buyers with instant quotes penetrate underpenetrated Spanish and Polish markets. |
| Cross-Border Program Harmonization | Zurich Insurance Group's EU-wide structures neutralize jurisdictional fragmentation between German civil law and English common law. |
| Blockchain Smart Contract Integration | Automated indemnity triggers tied to verified IoT logs reduce Belgian and Dutch dispute resolution timelines from quarters to weeks. |
| Reinsurance Capacity Anchoring | Munich Re's peak layer absorption across multiple EU jurisdictions enables primary carriers to underwrite complex multinational risks. |
Research Methodology
Initial hypotheses were tested against primary input from chief underwriting officers, corporate risk managers, Lloyd's syndicate leads, and regulatory affairs directors at EIOPA and BaFin, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including Solvency II disclosure filings, EIOPA stress-testing reports, Lloyd's market data, and national insurance regulator statistics. Bottom-up premium pool estimates triangulated against top-down macroeconomic exposure projections.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation modeled by coverage type, industry vertical, policyholder scale, and premium structure flexibility. CAGRs derived from historical premium trajectory analysis adjusted for regulatory capital requirement shifts and technology adoption curves. Forecast inputs incorporated IoT sensor penetration rates and EU AI Act compliance timeline assumptions.
Stress conditions across Solvency II capital charge volatility, long-tail casualty reserve adequacy, and algorithmic underwriting model accuracy were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pace and technology diffusion rates. Macroeconomic contraction, accelerated EU Green Deal liability expansion, or breakthrough quantum computing risk modeling would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Takaful Insurance Market
Insurance
Agricultural Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Crime Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
GCC Bancassurance Market
Insurance
General Insurance Market
Insurance
Africa Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Aviation Insurance Market
Insurance
Cyber Insurance Market
Insurance
Factory and Warehouse Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Canada House Insurance Market
Insurance
Europe Travel Insurance Market