
 Asia-Pacific EV Insurance Market | 2026-2036
Asia-Pacific EV Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific EV Insurance Market Analytics
Telematics integration is narrowing the data gap between risk assessment and premium pricing across Asia-Pacific EV insurance portfolios. Ping An Insurance leverages its proprietary IoT infrastructure to anchor real-time driving behavior analytics in mainland China. PICC Property and Casualty Company Limited sustains dominance through state-backed distribution networks and mandatory third-party liability scale. QBE Insurance Group competes across Australia and Southeast Asia with specialized commercial fleet products.
Asia-Pacific EV insurance encompasses risk-transfer instruments designed for battery-electric, plug-in hybrid, and fuel-cell vehicles, incorporating battery degradation clauses, charging infrastructure liability riders, and thermal runaway coverage into standard policy architecture. Its primary purpose is to align actuarial models with electrochemical propulsion risks distinct from internal-combustion powertrains. Comprehensive policy types command premium pricing due to battery replacement cost exposure, while pay-as-you-drive products are expanding fastest among ride-share services seeking variable cost structures. AI underwriting within technology integration segments is concentrating margin pools through automated claims triage and fraud detection.
China's MIIT and SAMR shape product standards through GB-compliant vehicle certification and mandatory data localization for telematics platforms, while India's IRDAI and BIS framework governs policy wording and motor tariff structures. Japan's METI coordinates cross-border data protocols affecting insurer interoperability across regional fleets. Stakeholders must monitor divergent battery certification requirements and telematics data sovereignty rules as these determine market access and product design latitude.
Market Dynamics
Telematics-enabled usage-based pricing is restructuring actuarial risk pools across Asia-Pacific EV portfolios, compressing the lag between real-time driving data and premium recalculation from annual cycles to continuous adjustment.
Growth Catalysts
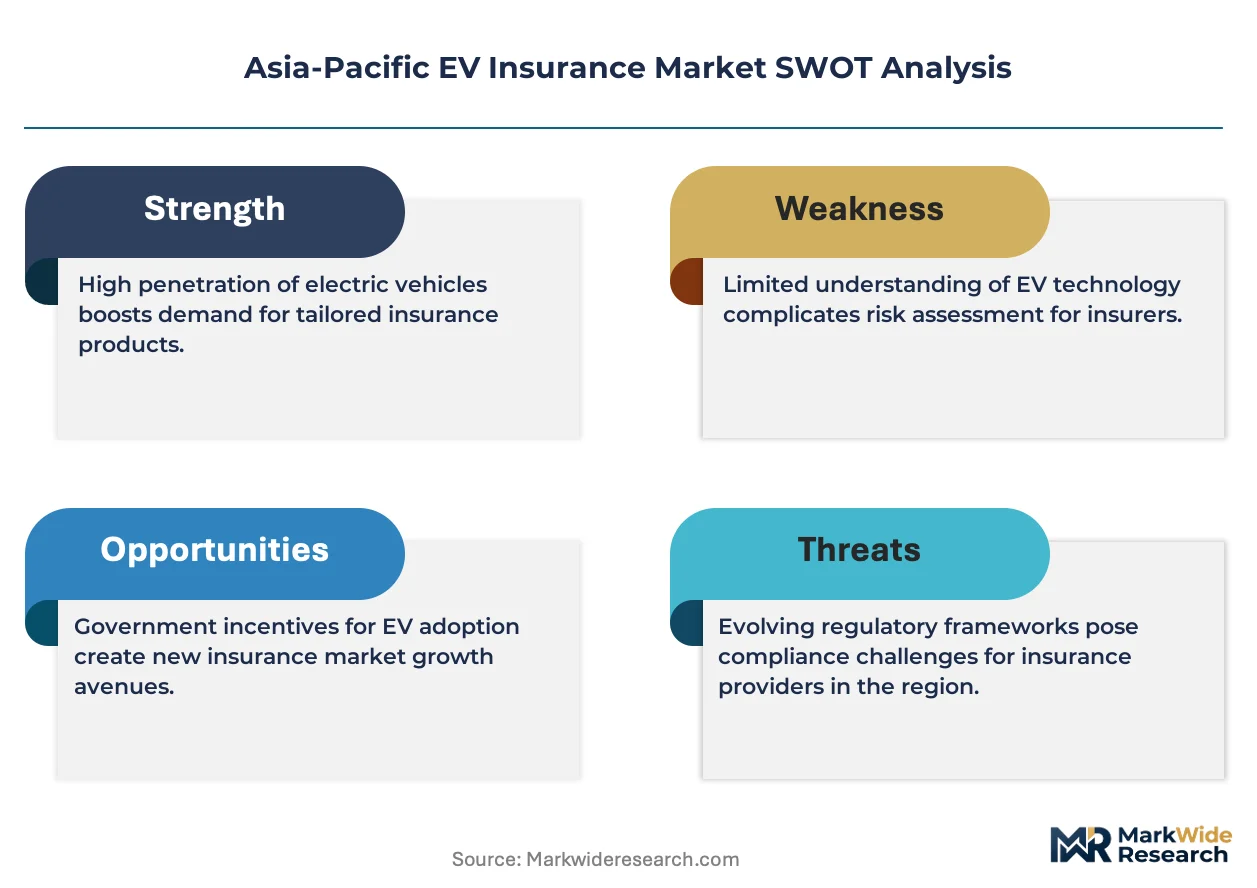
- MIIT Data Localization Mandates:China's requirement for domestic telematics data storage creates compliant infrastructure that insurers leverage for granular risk segmentation in tier-one cities.
- Commercial Fleet Electrification:Ride-hail and logistics operators across India and Southeast Asia are scaling pay-per-kilometer coverage to align variable insurance costs with per-trip revenue models.
- Battery Degradation Modeling:Advanced electrochemical simulation tools now enable insurers to price cell capacity fade into comprehensive policies with actuarial precision previously unavailable.
Market Restraints
- Lithium-Ion Cell Cost Volatility:Cathode material price swings directly inflate comprehensive policy premiums, as battery replacement constitutes the dominant loss severity driver.
- Single-Source Telematics Hardware:Concentrated supply of GB-compliant onboard monitoring units from domestic Chinese manufacturers creates procurement bottlenecks for regional insurers.
- Thermal Runaway Assessment Gaps:Insufficient standardized testing protocols for cell-level thermal propagation leave underwriters exposed to catastrophic loss uncertainty in high-density battery packs.
Strategic Opportunities
- Vietnam and Indonesia Fleet Markets:Motorcycle-to-EV transition corridors in Hanoi and Jakarta present first-mover advantages for micro-mobility insurance products with embedded telematics.
- Vehicle-to-Grid Liability Coverage:Bidirectional charging infrastructure creates unaddressed risk pools around grid-interconnection faults and energy export indemnification.
- India's FAME-II Subsidy Extensions:Continued central government EV purchase incentives expand the addressable insured vehicle base in Mumbai, Delhi, and Bangalore metropolitan clusters.
Industry Challenges
- Cross-Border Data Sovereignty Fragmentation:Divergent telematics storage requirements between China's GB standards, India's draft data protection framework, and Japan's METI cross-border protocols complicate regional fleet policy administration.
- Actuarial Talent Scarcity:Shortage of professionals combining electrochemical engineering expertise with traditional motor underwriting experience constrains product development velocity across domestic insurers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific EV Insurance Market |
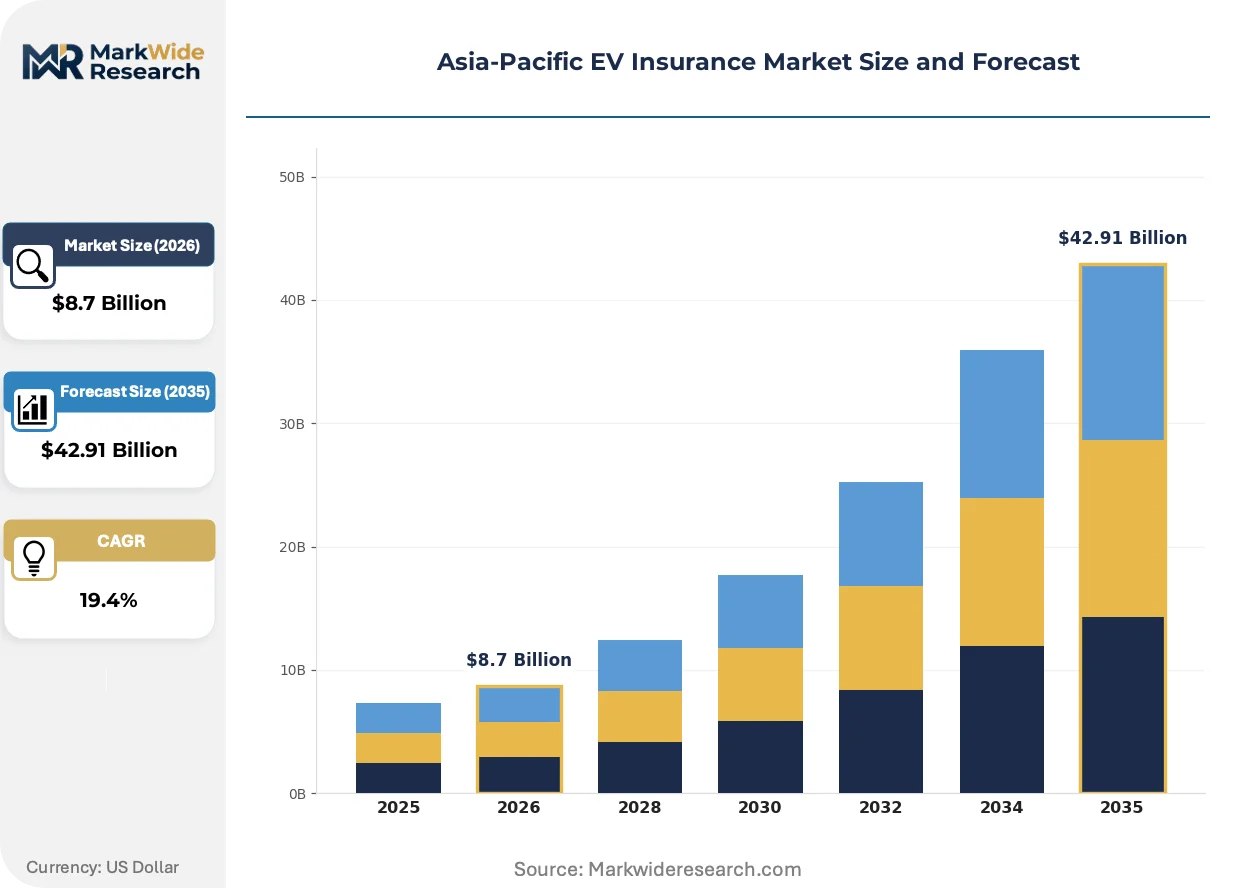
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third-Party Liability, Fire and Theft, Pay-As-You-Drive Coverage Level: Full Coverage, Limited Coverage, Basic Coverage, Supplemental Coverage Customer Type: Individual Owners, Fleet Operators, Corporate Clients, Ride-Share Services Technology Integration: Telematics, Mobile Apps, AI Underwriting, Smart Contracts |
| Companies Covered | AXA, Aviva, Ping An Insurance (Group) Company of China, Ltd., Cheche Group, QBE Insurance Group, PICC Property and Casualty Company Limited, Zurich Insurance Group, Direct Line Insurance Group plc, Allianz, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific EV Insurance Market Evolving Landscape
Artificial intelligence is compressing claims resolution timelines while embedded insurance models are dissolving the boundary between vehicle purchase and policy activation across Asia-Pacific distribution channels.
Parametric battery health warranties are collapsing the traditional claims investigation process for capacity degradation events. Commercial fleet operators in Australia's mining logistics sector are adopting these instruments to bypass lengthy adjuster assessments. The compression of settlement cycles from weeks to hours is reallocating capital reserves from loss adjustment expenses to pure risk coverage.
China's SAMR has finalized mandatory telemetry disclosure standards for NEVs, requiring real-time transmission of state-of-charge and thermal management data to certified insurance platforms. This regulatory architecture enables dynamic premium adjustment based on actual charging behavior rather than declared usage patterns. Domestic insurers are restructuring product filings to incorporate these continuous data streams into rating algorithms.
Fleet procurement teams are unbundling insurance from vehicle lease agreements to source coverage through specialized EV underwriters with superior telematics integration. This disintermediation of captive finance-and-insurance products is most pronounced among Singapore-based logistics operators managing cross-border ASEAN routes. Third-party brokers with dedicated EV actuarial capabilities are capturing margin previously retained by manufacturer-affiliated insurers.
Asia-Pacific EV Insurance Market Segmentation
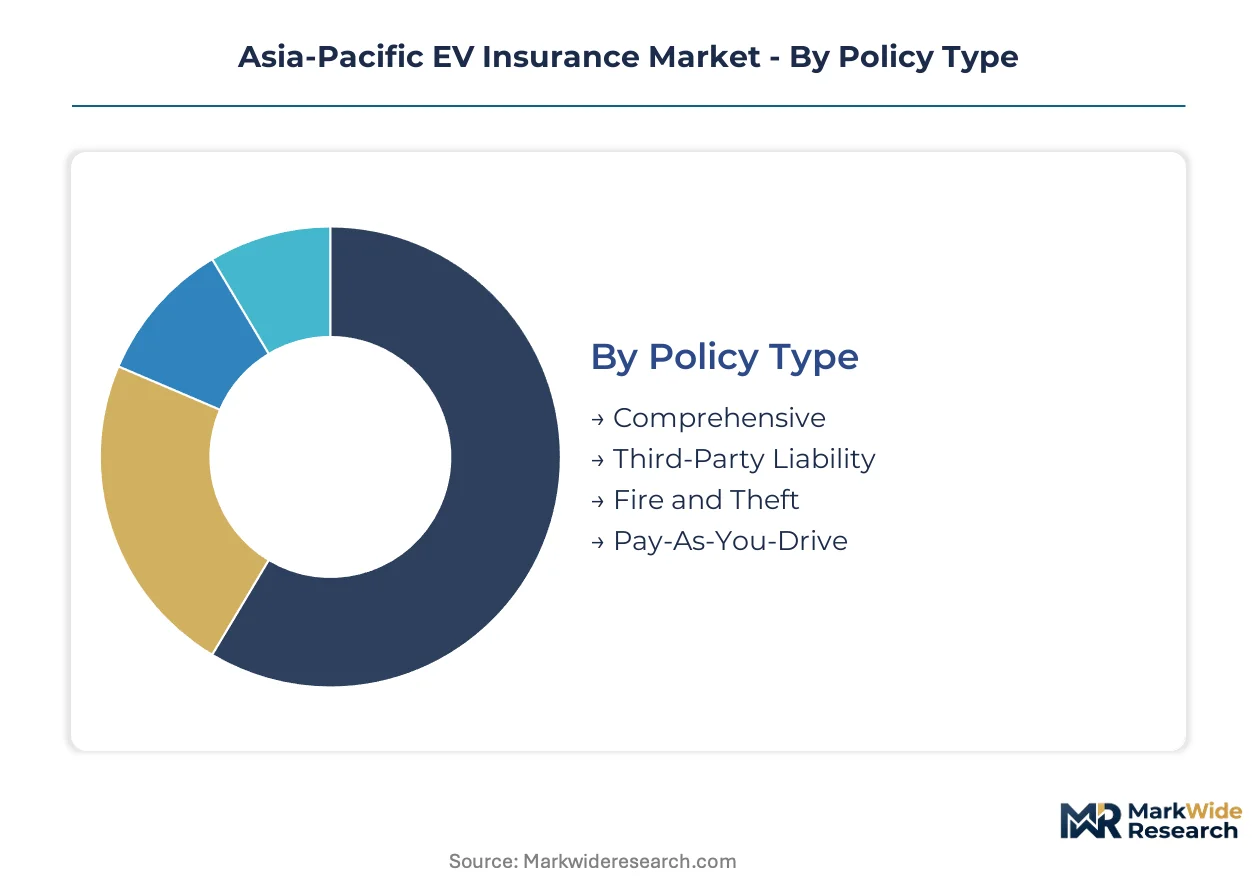
Segmentation in Asia-Pacific EV insurance reflects divergent risk appetites across battery-electric and plug-in hybrid vehicle classes. Actuarial models must differentiate between electrochemical propulsion systems, charging infrastructure exposure, and telematics-enabled usage patterns unique to this region.
Policy Type:
Mature comprehensive products coexist with emerging usage-based structures across regional portfolios.
- Comprehensive:Wraps battery replacement, thermal runaway damage, and charging infrastructure liability into unified coverage architecture. Demand concentrates among corporate fleet operators in Shanghai and Shenzhen seeking protection against cell degradation costs that dominate loss severity.
- Third-Party Liability:Mandatory coverage anchored to state-mandated minimums with premium modulation through MIIT-compliant telematics verification. India's IRDAI motor tariff structures govern pricing in Mumbai and Delhi metropolitan corridors where enforcement density is highest.
- Fire and Theft:Standalone peril coverage addressing lithium-ion thermal propagation risks excluded from standard motor policies.
- Pay-As-You-Drive:Variable premium structures tied to real-time state-of-charge and mileage telemetry. Ride-hail operators in Bangalore and Jakarta deploy these products to align insurance costs with per-trip revenue.
Comprehensive handles the majority of throughput; Pay-As-You-Drive is the fastest mover on share.
Coverage Level:
Cost tier differentiation separates premium protection from constrained indemnity products.
- Full Coverage:Maximum indemnity limits with zero depreciation on battery replacement and guaranteed OEM parts sourcing. High-net-worth individual owners in Singapore and Tokyo premium districts drive subscription.
- Limited Coverage:Capped battery replacement benefits with aftermarket parts acceptance and depreciation schedules on electrochemical components. Fleet operators in Vietnam's Hanoi corridor optimize here for cost control.
- Basic Coverage:Statutory minimums with no battery-specific riders. Price-sensitive motorcycle-to-EV transition buyers in Indonesia's secondary cities populate this tier.
- Supplemental Coverage:Add-on modules for vehicle-to-grid liability and public charging station damage. Early adopters in Australia's commercial logistics sector test these instruments.
Full Coverage captures the dominant premium pool; Supplemental Coverage is expanding most rapidly as bidirectional charging proliferates.
Customer Type:
Volume concentration varies sharply between fragmented retail and concentrated commercial accounts.
- Individual Owners:Retail policyholders purchasing through direct channels and agency networks. China's tier-one cities generate the deepest penetration rates as NEV mandates accelerate replacement cycles.
- Fleet Operators:Commercial accounts managing 50+ vehicle portfolios with centralized telematics platforms. Southeast Asian logistics corridors from Bangkok to Ho Chi Minh City anchor regional demand.
- Corporate Clients:Enterprise procurement teams unbundling insurance from vehicle lease agreements. Singapore-based cross-border ASEAN route managers are disintermediating captive finance products.
- Ride-Share Services:Platform-mediated drivers seeking variable cost structures aligned to trip frequency. India's Ola and Uber partner fleets in Bangalore and Delhi represent the steepest expansion trajectory.
Fleet Operators command the largest policy values; Ride-Share Services are scaling fastest on policy count.
Technology Integration:
Margin pools concentrate where automation displaces manual underwriting and claims processing.
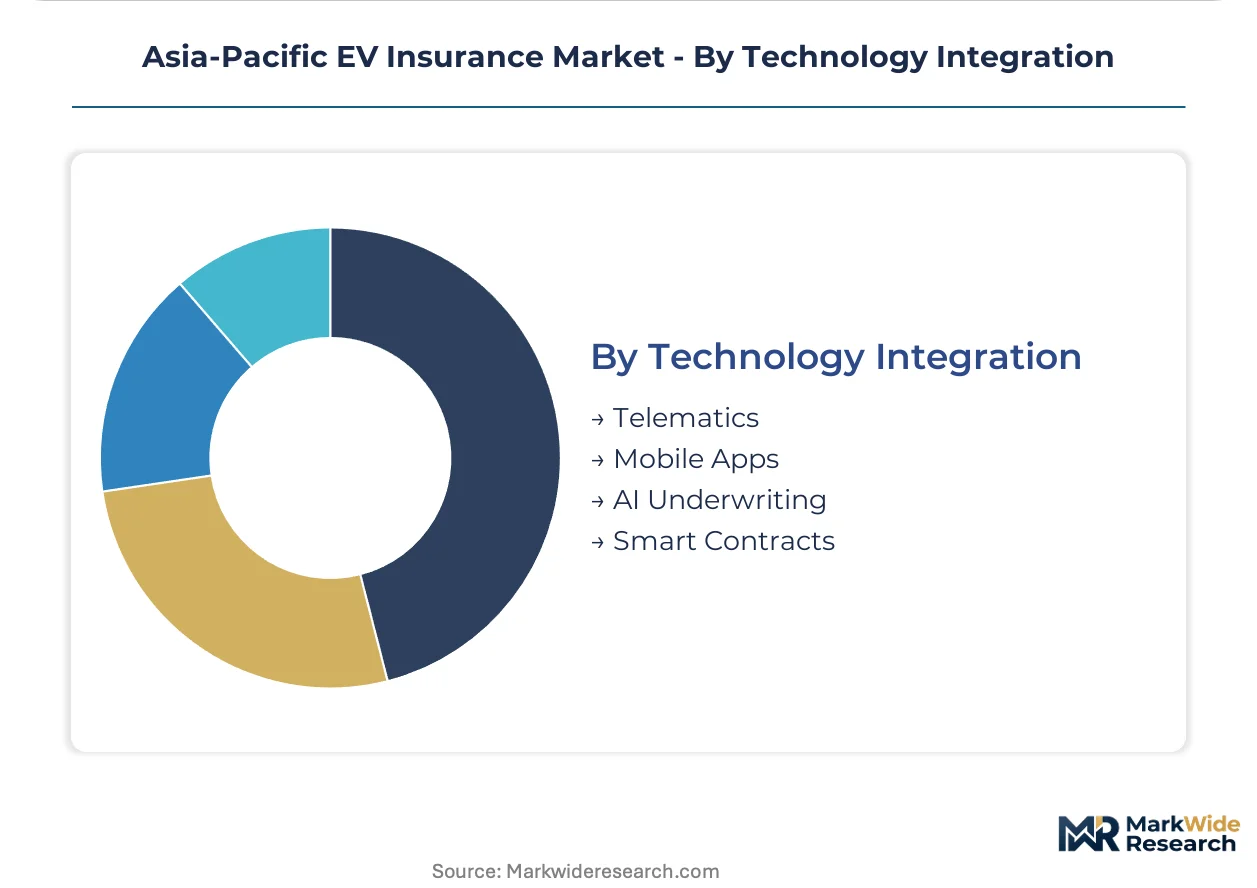
- Telematics:GB-compliant onboard monitoring units transmitting real-time state-of-charge, thermal management, and geolocation data. China's SAMR mandatory disclosure standards enable dynamic premium recalculation.
- Mobile Apps:Policyholder interfaces for claims submission, coverage modification, and charging station locator integration. Urban individual owners in Tokyo and Seoul demonstrate highest engagement rates.
- AI Underwriting:Automated risk scoring combining driving behavior analytics with electrochemical degradation models. Ping An's proprietary IoT infrastructure anchors deployment in mainland China.
- Smart Contracts:Blockchain-enabled parametric triggers for battery health warranty payouts. Australian mining logistics fleets pilot these instruments to compress settlement cycles.
Telematics underpins the broadest installed base; Smart Contracts are gaining adoption fastest among commercial specialty lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's telematics infrastructure exports data processing capabilities to Southeast Asian insurers underwriting cross-border fleet routes. Singapore-based logistics operators leverage this connectivity to administer usage-based policies across ASEAN corridors.
China
NEV mandates in Beijing and Shanghai accelerate replacement cycles among corporate fleets. MIIT data localization requirements force domestic storage of telematics streams, enabling Ping An and PICC to refine granular risk segmentation. Shenzhen and Guangzhou anchor the deepest penetration of comprehensive battery coverage products.
India
Ola and Uber partner fleets in Bangalore and Delhi drive pay-as-you-drive subscription volumes. IRDAI motor tariff structures govern mandatory third-party liability pricing in Mumbai's enforcement-dense corridors. FAME-II subsidy extensions expand the addressable insured vehicle base across Maharashtra and Karnataka metropolitan clusters.
Japan
Tokyo premium districts generate concentrated demand for full-coverage products with zero depreciation clauses. METI coordinates cross-border data protocols affecting insurer interoperability for regional fleet administration. Kansai logistics operators test vehicle-to-grid liability riders for bidirectional charging infrastructure.
Australia
Mining logistics fleets in Western Australia pilot parametric battery health warranties to compress claims settlement cycles. QBE Insurance Group competes with specialized commercial products across the continent. Sydney and Melbourne telematics engagement rates exceed regional benchmarks among urban individual owners.
Vietnam
Motorcycle-to-EV transition corridors in Hanoi present first-mover positioning for micro-mobility insurance with embedded telematics. Cheche Group targets this emerging segment through digital distribution platforms. Ho Chi Minh City fleet operators optimize limited coverage tiers for cost control across expanding logistics networks.
Asia-Pacific EV Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. State-backed insurers leverage mandatory distribution networks to capture third-party liability scale, while telematics-native entrants compress pricing cycles through real-time data integration. Three archetypes dominate: incumbent state insurers with captive regulatory access, technology-integrated private carriers with proprietary IoT infrastructure, and digital intermediaries unbundling coverage from vehicle finance. Competitive moves concentrate on telematics platform licensing and cross-border data protocol alignment.
Among state-backed incumbents, PICC Property and Casualty Company Limited and Ping An Insurance (Group) Company of China, Ltd. occupy positions defined by regulatory compliance scale and proprietary data infrastructure respectively. QBE Insurance Group represents the specialist tier with focused commercial fleet capabilities across Australia and Southeast Asia. These three anchors illustrate divergent pathways to margin capture: state-mandated distribution dominance, technology-enabled dynamic pricing, and regional specialty line concentration.
| Leading Market Players |
|---|
| AXA |
| Aviva |
| Ping An Insurance (Group) Company of China, Ltd. |
| Cheche Group |
| QBE Insurance Group |
| PICC Property and Casualty Company Limited |
| Zurich Insurance Group |
| Direct Line Insurance Group plc |
| Allianz |
| Others |
Value Network & Pricing Analysis
The Shanghai-Singapore maritime corridor's freight cost dynamics compress margins for GB-compliant telematics hardware shipments while amplifying price differentiation between insurers with captive data infrastructure and those sourcing through third-party platforms.
Pricing Analysis
Current-generation AI underwriting platforms command premium positioning against prior-generation actuarial models and emerging next-generation parametric smart contract instruments. Three-tier pricing structure across premium, standard, and economy levels separates Ping An's proprietary IoT-integrated policies from PICC's state-mandated third-party liability products and Cheche Group's digital micro-mobility offerings. Pricing pressure stems from lithium-ion cell cost volatility feeding comprehensive policy inflation. Fleet operators in Vietnam and Indonesia exhibit highest price sensitivity; Tokyo premium district individual owners demonstrate lowest.
Supply Chain Analysis
Extended payment terms from domestic Chinese manufacturers of GB-compliant onboard monitoring units strain regional insurer working capital. Supply concentrates in China for telematics hardware, South Korea for battery management system semiconductors, and Japan for thermal sensor components. Raw material dependencies span lithium carbonate, cobalt sulfate, and rare-earth magnets. Single-source vulnerability around GB-certified telemetry units creates procurement chokepoints. Distribution runs through state-backed agency networks in China, broker-led unbundling in Singapore, and direct digital platforms in Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent insurers face substitution pressure from embedded finance products dissolving the vehicle purchase-policy boundary, requiring defensive capability building around real-time data infrastructure.
For Market Incumbents: Build proprietary telematics data moats through MIIT-compliant platform licensing to anchor dynamic pricing capabilities against digital intermediary disintermediation. Deepen backward integration into GB-certified hardware procurement to secure supply continuity. Channel control through state-mandated distribution networks retains third-party liability scale against fintech entrants.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's motorcycle-to-EV transition corridors where micro-mobility insurance remains underpenetrated and regulatory frameworks are still forming. Target Jakarta's fleet operator segment with pay-per-kilometer products unbundled from manufacturer finance packages. Go-to-market through embedded partnerships with ride-hail platforms captures trip-frequency data streams.
For Investors and Strategic Acquirers: Telematics-native insurers with proprietary IoT infrastructure and regional regulatory licenses represent the most defensible acquisition archetype for long-horizon portfolio construction. Monitor FAME-II subsidy extension announcements from India's Ministry of Heavy Industries as the critical demand inflection signal. Cross-border data protocol alignment between China's MIIT and ASEAN regulators determines scalable platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Licensing | Ping An's proprietary IoT infrastructure enables real-time premium recalculation based on SAMR-mandated telemetry disclosure. |
| GB-Compliant Hardware Procurement | Domestic Chinese manufacturers of certified onboard monitoring units control regional insurer supply continuity. |
| Parametric Smart Contract Deployment | Australian mining logistics fleets pilot blockchain-enabled battery health warranties to compress settlement cycles. |
| Cross-Border Data Protocol Alignment | Singapore-based ASEAN route managers require METI-coordinated interoperability for fleet policy administration. |
| Embedded Insurance Partnership | Cheche Group's digital distribution platforms target Vietnam's motorcycle-to-EV transition corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with fleet procurement managers, insurance product actuaries, telematics platform engineers, and IRDAI regulatory affairs specialists. Secondary validation drew from MIIT NEV certification databases, SAMR mandatory disclosure filings, IRDAI motor tariff circulars, and ASEAN customs telematics import records. Bottom-up policy count aggregation and top-down premium pool estimation were triangulated against cross-referenced sources.
Calibration against historical penetration rates and announced fleet electrification timelines anchored projections across the analysis window. Segmentation dimensions modeled include policy type, coverage level, customer archetype, and technology integration depth. CAGRs were derived from compounding annual premium growth assumptions. Forecast inputs incorporated FAME-II subsidy extension probabilities and MIIT data localization compliance trajectories.
Sensitivities concentrate around lithium carbonate price volatility, GB hardware supply disruptions, and cross-border data sovereignty rulings. Forecasts reflect documented assumptions regarding fleet electrification cadence and regulatory mandate enforcement density. Macroeconomic contraction, regulatory mandate delays, or thermal runaway protocol standardization failures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Travel Insurance Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
US Travel Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Europe Car Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
Europe Liability Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Agriculture Insurance Market
Insurance
Bancassurance in ASEAN Market