
 Finland Cyber (Liability) Insurance Market | 2026-2036
Finland Cyber (Liability) Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Finland Cyber (Liability) Insurance Market Foresight
Cloud-native infrastructure migration is reshaping how Finnish enterprises architect their digital operations and corresponding insurance requirements. AXA leverages its pan-Nordic platform to deliver standardized cyber policies across the Baltic Sea region. LocalTapiola anchors its competitive stance through deep integration with domestic SME banking relationships. If Insurance specializes in sector-specific underwriting for technology and healthcare verticals.
Finland Cyber (Liability) Insurance constitutes risk-transfer instruments designed to indemnify policyholders against financial losses stemming from data breaches, network intrusions, and operational technology failures, with coverage structures typically specifying indemnity limits, waiting periods, and forensic cost sub-limits. First-party coverage dominates premium volumes as ransomware recovery and business interruption claims accelerate among Finnish policyholders. Third-party coverage exhibits the fastest expansion trajectory, driven by litigation exposure under GDPR and the EU AI Act's emerging liability frameworks. Medium enterprises represent the most contested segment, with carriers competing on risk-engineering services rather than price alone.
Finanssivalvonna (FIN-FSA) supervises insurer solvency and policyholder protection standards, while the Finnish Transport and Communications Agency (Traficom) enforces NIS2 implementation timelines for critical infrastructure operators. The EU AI Act introduces new liability allocation mechanisms that will reshape coverage exclusions and sub-limit structures. Stakeholders must monitor how Traficom designates sector-specific critical entities, as these classifications will trigger mandatory coverage thresholds and reshape addressable market boundaries.
Market Dynamics
Cloud-native infrastructure migration is compressing traditional policy renewal cycles as Finnish enterprises demand coverage structures aligned with containerized workloads and API-driven architectures rather than static perimeter defenses.
Growth Catalysts
- NIS2 Directive:Traficom's enforcement timelines for critical infrastructure operators are mandating minimum coverage thresholds that expand addressable premium pools.
- Healthcare digitization:Finnish hospital districts deploying patient data lakes are purchasing standalone cyber policies with forensic cost riders.
- Ransomware frequency:Incident response retainers bundled with first-party coverage are displacing traditional IT security spending among medium enterprises.
Market Restraints
- Actuarial data scarcity:Limited historical loss experience in Nordic OT environments compresses carrier confidence in pricing industrial control system exposures.
- Reinsurance capacity:Baltic Sea region retrocession markets are tightening aggregate limits following pan-European systemic risk repricing.
- Claim attribution complexity:State-sponsored intrusion vectors challenge standard war exclusion interpretations and delay settlement timelines.
Strategic Opportunities
- Tampere-Turku corridor:Manufacturing clusters outside Helsinki exhibit sub-15% penetration rates for standalone cyber coverage.
- EU AI Act liability:Algorithmic decision-making exclusions create white space for specialized AI risk endorsements.
- Embedded distribution:Neobank partnership channels are capturing SME policyholders outside traditional broker relationships.
Industry Challenges
- Forensic talent scarcity:Incident response firms serving Finnish policyholders face 6-9 month hiring timelines for Nordic-speaking analysts.
- Legacy system integration:Mainframe-dependent insurers struggle to ingest real-time telemetry from policyholder cloud environments.
- GDPR-NIS2 overlap:Breach notification timing conflicts between frameworks complicate claims documentation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland Cyber (Liability) Insurance Market |
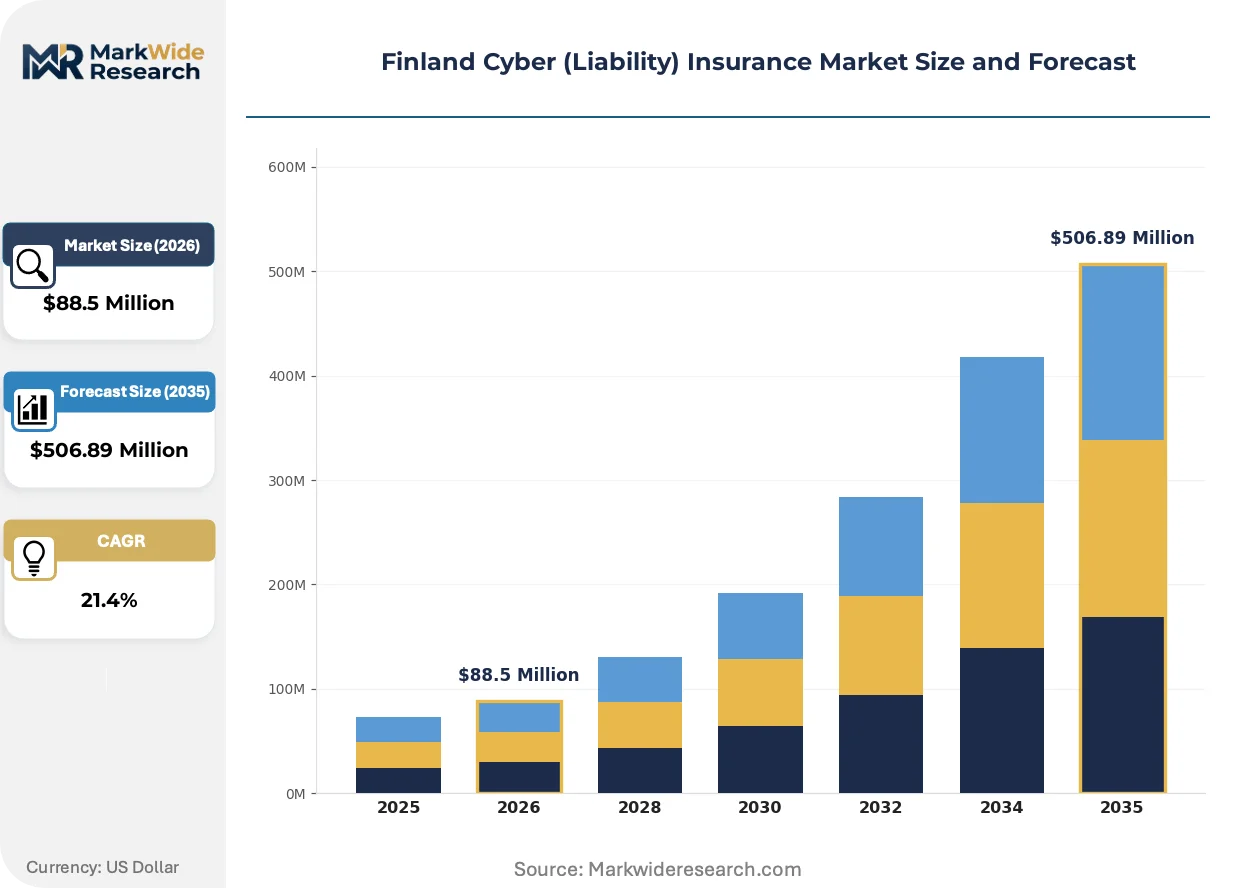
| Market Size in 2026 | $88.5 Million |
| Market Size in 2035 | $506.89 Million |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: First-Party Coverage, Third-Party Coverage, Data Breach Liability, Business Interruption Industry Vertical: Healthcare, Financial Services, Retail, Technology Company Size: Small Enterprises, Medium Enterprises, Large Enterprises, Startups Coverage Limit: Up to €1M, €1M to €5M, €5M to €10M, Above €10M |
| Companies Covered | AXA, Allianz, AIG, OP Insurance, LocalTapiola, If Insurance, Dual Finland, Aon plc, Pohjola Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland Cyber (Liability) Insurance Market Shifts & Advancements
Finnish carriers are restructuring policy architectures around continuous risk telemetry rather than point-in-time underwriting assessments. This shift demands new data pipelines and real-time pricing engines.
Parametric cyber coverage is digitizing claims settlement for Finnish policyholders by triggering payouts based on predefined downtime metrics rather than forensic investigation outcomes. Manufacturing firms in the Helsinki-Uusimaa region are piloting these structures for production line interruption risks. The compression of settlement timelines from months to days is reshaping buyer expectations across the market.
Finanssivalvonna is tightening solvency capital requirements for cyber underwriting reserves following EIOPA stress-testing guidelines. Finnish carriers must hold additional capital against systemic ransomware scenarios. Domestic mutual insurers are responding by ceding more risk to Lloyd's syndicates with specialized cyber expertise.
Enterprise procurement of cyber coverage is consolidating through group captive structures as Finnish mid-market firms pool retentions. This displaces individual standalone policies in the 50-250 employee segment. The cooperative purchasing model is particularly visible among technology subcontractors serving Nokia's supply chain in Oulu and Espoo.
Finland Cyber (Liability) Insurance Market Segmentation
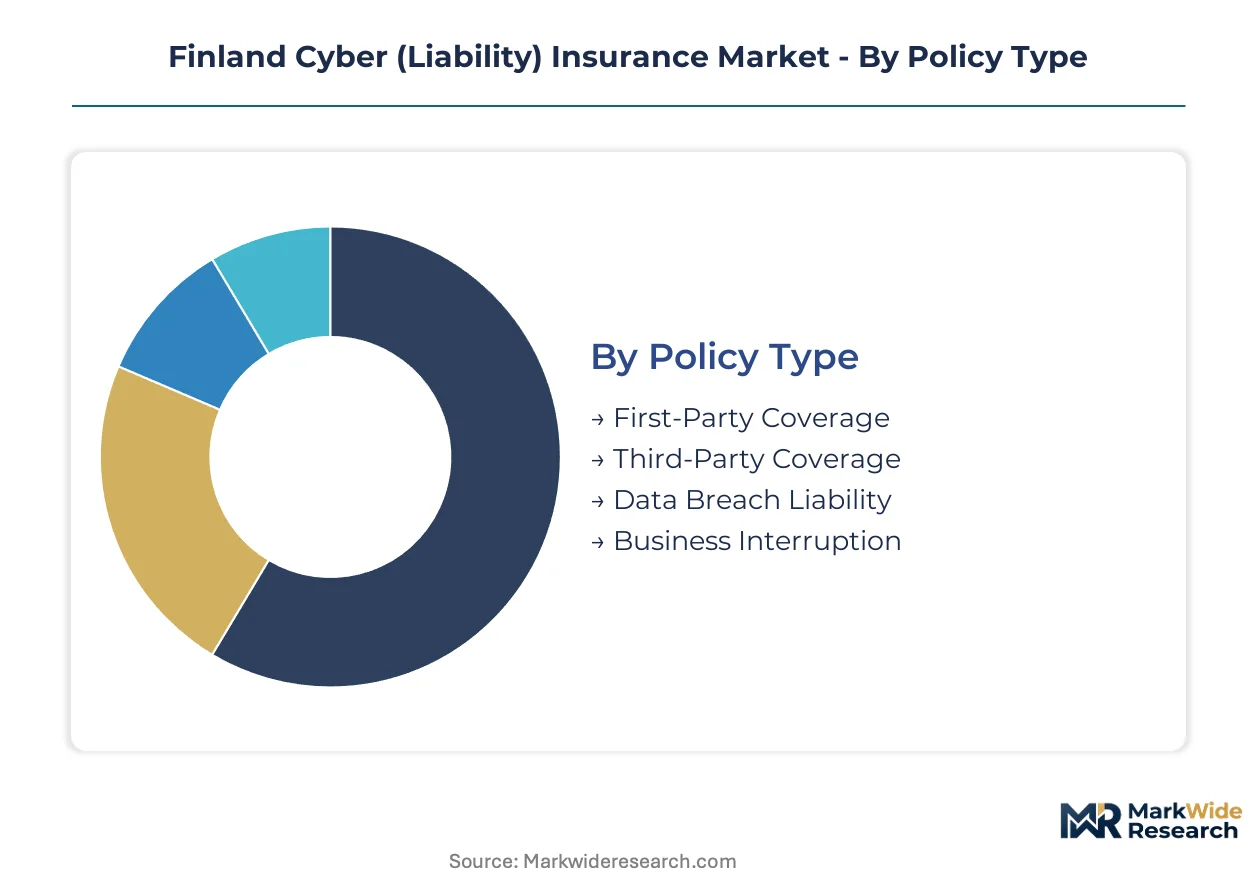
Finnish cyber insurance buyers segment sharply across liability structures and operational scale. Carrier product development and distribution strategies diverge materially across these divides.
Policy Type:
Mature indemnity structures dominate premium flows, while emerging coverage forms reshape contract architecture.
- First-Party Coverage:Indemnifies policyholders for direct losses including forensic investigation, data restoration, and ransomware extortion payments. Helsinki metropolitan healthcare providers and manufacturing clusters purchase these policies with business interruption riders following Traficom's NIS2 implementation timelines.
- Third-Party Coverage:Shields against liability claims from affected customers, partners, or regulatory bodies for data breaches or privacy violations. GDPR litigation exposure and the EU AI Act's emerging liability frameworks are accelerating uptake among Finnish technology exporters serving continental European clients.
- Data Breach Liability:Specialized coverage for notification costs, credit monitoring, and regulatory fines tied to unauthorized data access.
- Business Interruption:Compensates for revenue loss during operational downtime from cyber incidents.
First-Party Coverage handles the majority of throughput; Third-Party Coverage is the fastest mover on share.
Industry Vertical:
End-use concentration varies by regulatory exposure and digital asset intensity.
- Healthcare:Hospital districts deploying patient data lakes purchase standalone policies with forensic cost riders. Finnish healthcare digitization mandates under EU health data regulations are expanding addressable premium pools.
- Financial Services:Banks and payment processors maintain the most mature cyber insurance programs. Finanssivalvonna supervision drives consistent coverage minimums across domestic institutions.
- Retail:E-commerce platforms and point-of-sale operators seek coverage for payment card industry breach scenarios.
- Technology:Software vendors and cloud service providers face algorithmic liability exposure under the EU AI Act.
Financial Services anchors premium volume; Healthcare is expanding most quickly as district-level procurement consolidates.
Company Size:
Customer type determines distribution channel and risk engineering intensity.
- Medium Enterprises:The most contested segment with carriers competing on incident response retainers and risk telemetry services. Finnish mid-market firms in the 50-250 employee range are consolidating procurement through group captive structures.
- Large Enterprises:Maintain sophisticated programs with layered coverage and captive retention vehicles. Nokia's supply chain subcontractors in Oulu and Espoo exhibit cooperative purchasing models.
- Small Enterprises:Often access coverage through embedded distribution channels including neobank partnerships.
- Startups:Emerging technology ventures with venture capital backing seeking initial coverage for investor due diligence requirements.
Large Enterprises command the deepest coverage limits; Medium Enterprises are gaining share fastest as Traficom designates additional critical entities.
Coverage Limit:
Premium tier stratification reflects buyer sophistication and regulatory minimum thresholds.
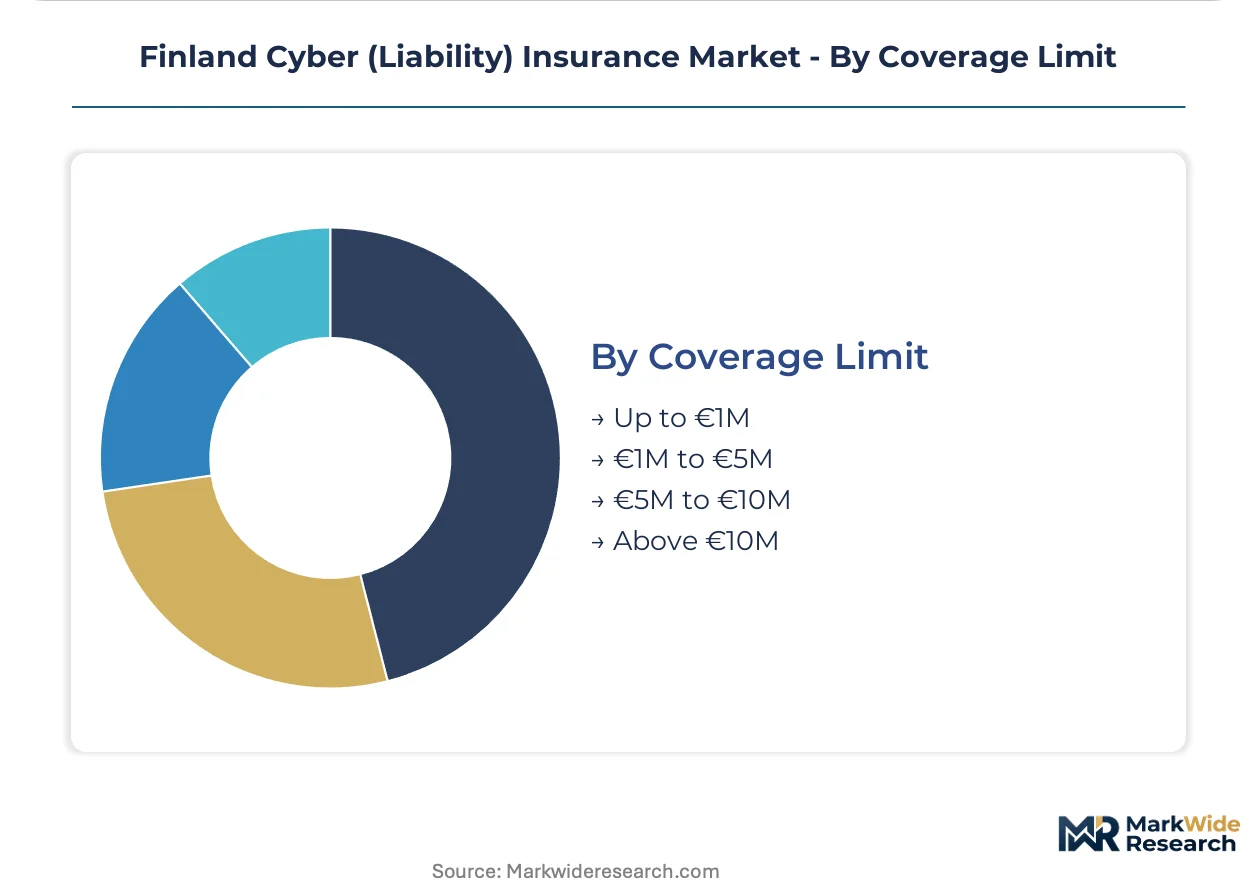
- €1M to €5M:The standard range for Finnish medium enterprises meeting NIS2 mandatory coverage thresholds. Traficom's enforcement timelines for critical infrastructure operators are compressing purchasing cycles in this band.
- Above €10M:Reserved for large enterprises with systemic risk exposure and international operations. Lloyd's syndicates participate heavily here following Finanssivalvonna's tightened solvency capital requirements.
- Up to €1M:Entry-level policies for small enterprises and startups with limited digital footprints.
- €5M to €10M:Mid-tier coverage for established enterprises scaling their risk transfer programs.
€1M to €5M limits handle the majority of policy count; Above €10M is climbing the fastest as reinsurance markets reprice systemic risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish cyber insurance procurement concentrates among medium enterprises in the Helsinki metropolitan region, with district-level healthcare digitization and NIS2 compliance deadlines compressing purchasing cycles across the country.
Helsinki-Uusimaa Region
Hospital districts deploying patient data lakes purchase standalone policies with forensic cost riders. Traficom's NIS2 enforcement timelines mandate minimum coverage thresholds for critical infrastructure operators. The metropolitan technology corridor exhibits the deepest carrier competition on risk-engineering services.
Tampere-Turku Corridor
Manufacturing clusters exhibit sub-15% penetration rates for standalone cyber coverage. The Finnish Transport and Communications Agency designates sector-specific critical entities that trigger mandatory coverage. Industrial firms in Pirkanmaa and Southwest Finland are consolidating procurement through group captive structures.
Oulu Region
Nokia's supply chain subcontractors exhibit cooperative purchasing models for cyber coverage. Finanssivalvonna supervision drives consistent coverage minimums across technology subcontractors. The northern technology hub is displacing individual standalone policies in the 50-250 employee segment.
Espoo Cluster
Cloud-native infrastructure migration compresses traditional policy renewal cycles among technology vendors. The EU AI Act introduces new liability allocation mechanisms that reshape coverage exclusions. Software exporters serving continental European clients accelerate third-party coverage uptake.
Finland Cyber (Liability) Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Finland's cyber insurance market. The carrier base concentrates around pan-Nordic platforms with standardized policy architectures and domestic mutual insurers with deep banking relationships. Three archetypes dominate: pan-regional carriers leveraging scale, domestic mutuals with embedded distribution, and Lloyd's-backed specialists serving high-limit segments. Competitive moves center on risk-engineering service differentiation and neobank partnership channels for SME acquisition.
Among pan-Nordic platforms, AXA leverages standardized cyber policy delivery across the Baltic Sea region. LocalTapiola anchors its competitive stance through domestic SME banking integration. If Insurance occupies the sector-specialist tier with technology and healthcare vertical focus. These three represent the dominant competitive archetypes shaping carrier positioning in the Finnish market.
| Leading Market Players |
|---|
| AXA |
| Allianz |
| AIG |
| OP Insurance |
| LocalTapiola |
| If Insurance |
| Dual Finland |
| Aon plc |
| Pohjola Insurance |
| Others |
Supply & Pricing Matrix
Reinsurance capacity constraints in the Baltic Sea region are compressing primary carrier pricing power and forcing Finnish underwriters to restructure risk retention layers. Tightening retrocession markets elevate ceding costs and push domestic mutuals toward Lloyd's syndicate partnerships.
Pricing Analysis
Cost-plus treaty arrangements with Lloyd's syndicates carry London Market Indexation clauses that pass through systemic risk repricing to Finnish policyholders. Premium-mid-economy pricing differentiation separates large enterprise layered programs from SME packaged coverage. Pricing pressure stems from Finanssivalvonna's tightened solvency capital requirements for cyber reserves. Small enterprises through neobank channels exhibit highest price sensitivity; large enterprises with captive retention vehicles demonstrate lowest sensitivity.
Supply Chain Analysis
Extended payment terms from Nordic reinsurers to Lloyd's syndicates stretch working capital cycles for Finnish primary carriers. Risk capital concentrates in the United Kingdom, Bermuda, and Switzerland. Actuarial modeling talent and forensic incident response capacity constitute critical input dependencies. Single-source vulnerability runs through London's specialty cyber underwriting expertise. Distribution runs through broker-led placement for large enterprises and embedded bancassurance channels for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finnish cyber insurance underwriting rests on scarce Nordic-speaking forensic talent and specialized OT risk modeling capabilities that constrain carrier expansion velocity.
For Market Incumbents: Entrench dominance through exclusive incident response retainer partnerships with Nordic forensic firms, blocking competitor access to critical claims capacity. Expand captive fronting capabilities for Nokia supply chain clusters to deepen vertical integration into technology subcontractor risk pools. Neutralize Lloyd's syndicate encroachment by embedding risk telemetry services that external carriers cannot replicate. For New Entrants and Emerging Players: Build out parametric coverage products for manufacturing business interruption in the Tampere-Turku corridor where penetration sits below fifteen percent. Target healthcare district procurement consolidations with forensic cost riders that incumbent mutuals underprice. Pursue neobank distribution partnerships to capture SME policyholders outside traditional broker relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cyber underwriting reserves following Finanssivalvonna's EIOPA-aligned stress-testing mandates. Prioritize acquisition of Nordic forensic incident response firms with six-to-nine-month analyst hiring backlogs. Monitor Traficom critical entity designations as inflection signals for mandatory coverage threshold expansions.| Strategic Initiative | Industry Significance |
|---|---|
| Risk Telemetry Platform Integration | Real-time policyholder monitoring satisfies Finanssivalvonna's continuous risk assessment expectations. |
| Nordic Forensic Firm Acquisition | Captive incident response capacity eliminates six-to-nine-month analyst hiring delays. |
| Parametric Product Launch | Predefined downtime triggers compress settlement timelines from months to days for manufacturing clients. |
| Neobank Distribution Partnership | Embedded channels capture SME policyholders outside traditional broker networks. |
| Group Captive Structure Expansion | Cooperative purchasing pools displace individual policies in the fifty-to-two-hundred-fifty employee segment. |
Research Methodology
The analysis maps first-party coverage structures, third-party liability frameworks, and parametric product architectures, each validated through underwriter interviews, broker placement specialists, and forensic incident response firms. Primary fieldwork combined with secondary validation from Finanssivalvonna solvency disclosures, Traficom NIS2 implementation guidance, and Lloyd's market returns. Bottom-up policy count modeling triangulates against top-down premium pool estimates from regulatory filings.
Assumptions held Traficom critical entity designations and EU AI Act liability phase-ins as fixed boundary conditions while varying ransomware frequency scenarios and reinsurance capacity availability across the projection horizon. Segmentation dimensions modeled include policy type, industry vertical, company size, coverage limit tier, and regional procurement cluster. CAGRs derive from premium pool expansion tied to mandatory coverage thresholds and healthcare digitization mandates. Forecast inputs incorporate NIS2 compliance deadlines and EIOPA stress-testing capital requirements.
Stress conditions across reinsurance capacity, ransomware claim severity, and forensic talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction, accelerated EU AI Act enforcement, or state-sponsored attack attribution disputes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Title Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Fire Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Peru Insurance Market
Insurance
Europe Parametric Insurance Market
Insurance
Auto Extended Warranty Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Crop Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Financial Guarantee Market