
 Asia-Pacific Group Health Insurance Market | 2026-2036
Asia-Pacific Group Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Group Health Insurance Market Analytics
Project finance partnerships between insurers and third-party administrators is tilting competitive dynamics toward asset-light operators with lower capital requirements. Ping An Insurance Group leverages its integrated healthcare ecosystem to control end-to-end policy servicing costs. AIA Group anchors its regional position through proprietary digital distribution platforms spanning Southeast Asian markets. Nippon Life sustains dominance in Japan's mature employer-sponsored segment through conservative reserve management and long-duration liability matching.
Asia-Pacific group health insurance constitutes employer-funded medical coverage pools administered through risk-pooling arrangements, with policy structures typically specifying annual benefit limits, network hospital tiers, and co-payment ratios calibrated to workforce demographics. The primary commercial purpose centers on workforce risk transfer, where employers substitute predictable premium outlays for volatile direct medical expenditure exposure. Managed care products lead premium generation across the region, while consumer-directed plans represent the fastest-growing structural category as cost-conscious employers shift partial spending responsibility to employees. Distribution through online platforms is displacing traditional broker intermediation in price-transparent segments, though large corporations retain broker relationships for complex multinational coverage coordination.
China's SAMR and NMPA jointly supervise product filing and network provider qualification standards, while India's IRDAI mandates minimum benefit floors and solvency margins for group underwriters. Japan's METI guidelines influence corporate wellness program integration with insurance offerings, creating compliance-driven demand for preventive care riders. Stakeholders must monitor regulatory divergence across Association of Southeast Asian Nations member states, where harmonized solvency standards remain under negotiation and fragmented compliance obligations multiply operational complexity for regional portfolio managers.
Market Dynamics
Employer-sponsored coverage expansion across India and China's technology corridors is compressing traditional broker intermediation as digital distribution platforms capture mid-market accounts with transparent premium benchmarking tools.
Growth Catalysts
- IRDAI benefit floor mandates:India's regulatory minimums for group health coverage are standardizing employer-sponsored benefits across formal sector enterprises, expanding addressable enrollment pools in Bangalore and Mumbai corporate clusters.
- Telemedicine infrastructure:Post-pandemic virtual care networks are embedding into policy designs, reducing per-claim servicing costs while extending coverage reach to distributed workforces across Southeast Asian markets.
- Dual carbon wellness integration:China's NMPA-aligned corporate wellness programs are creating compliance-linked demand for preventive care riders that bundle biometric screening with core medical coverage.
Market Restraints
- Medical inflation volatility:Input cost pressure from specialized pharmaceuticals and advanced diagnostic procedures is compressing underwriting margins across fee-for-service policy structures.
- Hospital network concentration:Tier-1 metropolitan provider oligopolies in Shanghai, Tokyo, and Singapore limit insurer negotiating leverage on reimbursement rate setting.
- Legacy system integration friction:Employer HRIS incompatibility with insurer policy administration platforms extends implementation timelines and elevates operational abandonment risk.
Strategic Opportunities
- Vietnam and Philippines underpenetration:Formal sector expansion in these ASEAN economies offers first-mover positioning as employer-sponsored coverage transitions from executive-only to workforce-wide enrollment.
- API-enabled embedded distribution:Payroll platform partnerships allow insurers to originate coverage at point of employment onboarding, capturing lifetime value through automated renewal workflows.
- PLI scheme alignment:India's production-linked incentive structures for manufacturing investment are creating captive workforce pools with standardized benefit requirements and predictable risk profiles.
Industry Challenges
- Actuarial talent scarcity:Shortage of professionals skilled in Asian mortality and morbidity modeling limits product innovation velocity for emerging market entrants.
- Cross-border claims adjudication complexity:Multinational employer programs require harmonized provider credentialing across Japan's METI guidelines, China's SAMR standards, and India's IRDAI frameworks, multiplying compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Group Health Insurance Market |
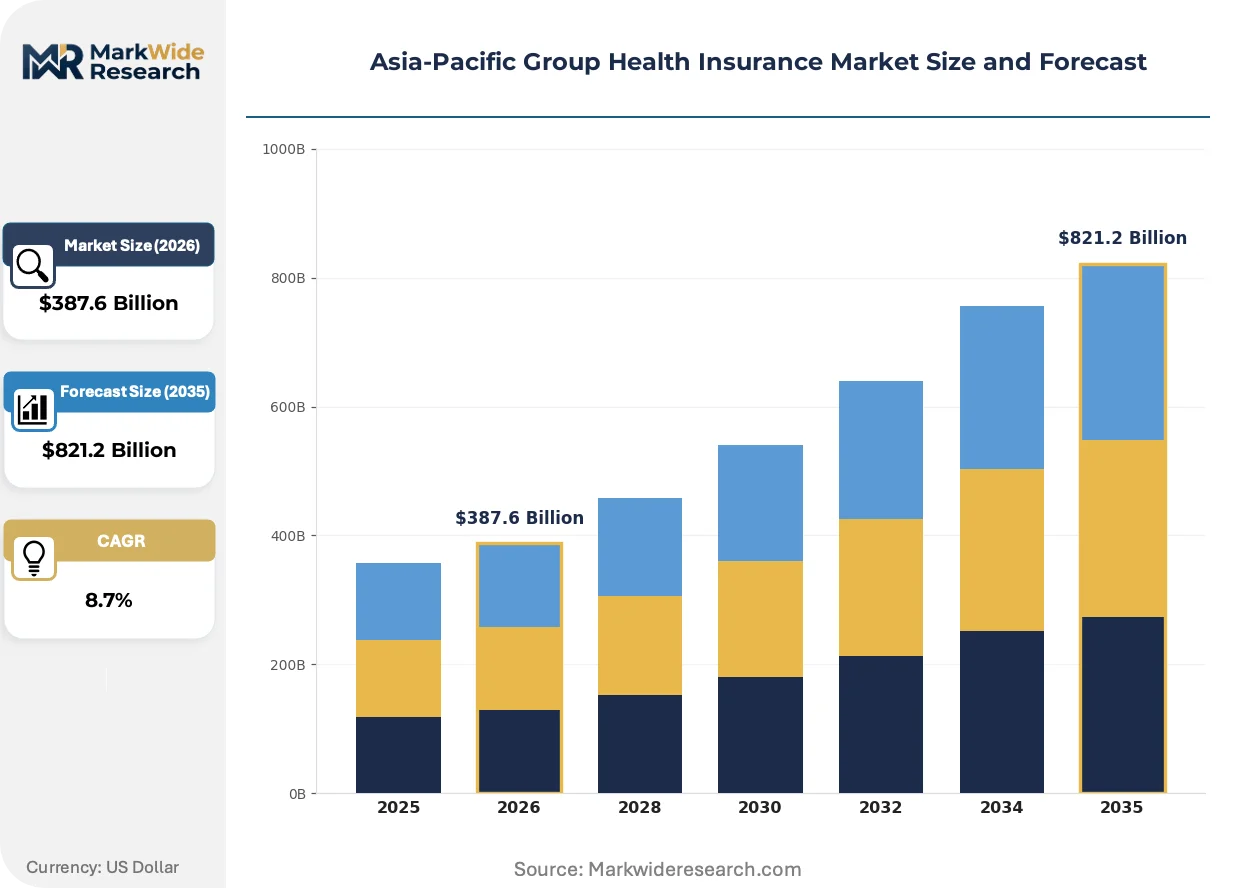
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Managed Care, Indemnity Plans, Consumer-Directed Plans, Direct Pay Plans Customer Type: Small Businesses, Large Corporations, Non-Profit Organizations, Government Agencies Distribution Channel: Brokers, Online Platforms, Direct Sales, Agents Coverage Type: Employer-Sponsored, Individual Health, Family Health, Supplementary Coverage |
| Companies Covered | Allianz, Nippon Life, AIA Group, QBE Insurance Group, LIC of India, Ping An Insurance Group, AXA, SBI Life Insurance, China Life Insurance Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Group Health Insurance Market Evolving Landscape
Digital infrastructure investment is compressing policy servicing costs while regulatory pressure on preventive care integration is reshaping product architecture across the region's employer-sponsored segment.
Blockchain-verified claims processing is digitizing reimbursement workflows through immutable provider billing records. Mid-market technology employers in India and Singapore are piloting these platforms to compress claims settlement cycles from weeks to days. The structural consequence is digitizing trust intermediation, reducing fraud audit expenditure while enabling real-time premium adjustment based on utilization patterns.
China's NMPA wellness-linked policy standards are mandating biometric screening minimums for group coverage eligibility. This regulatory architecture is forcing product redesign toward preventive care bundles that subsidize gym memberships and smoking cessation programs. Manufacturing employers in Guangdong and Jiangsu provinces are most affected, with HR departments restructuring benefit menus to meet filing requirements.
Employer procurement committees are consolidating vendor relationships from multi-carrier broker panels to single-platform direct contracts. Large technology and financial services buyers in Australia and South Korea are leading this consolidation, replacing commission-driven broker advice with transparent fee-for-service consulting. This pattern is most visible in Sydney and Seoul, where Fortune 500 regional headquarters have completed RFP processes favoring integrated health ecosystem providers over traditional indemnity specialists.
Asia-Pacific Group Health Insurance Market Segmentation
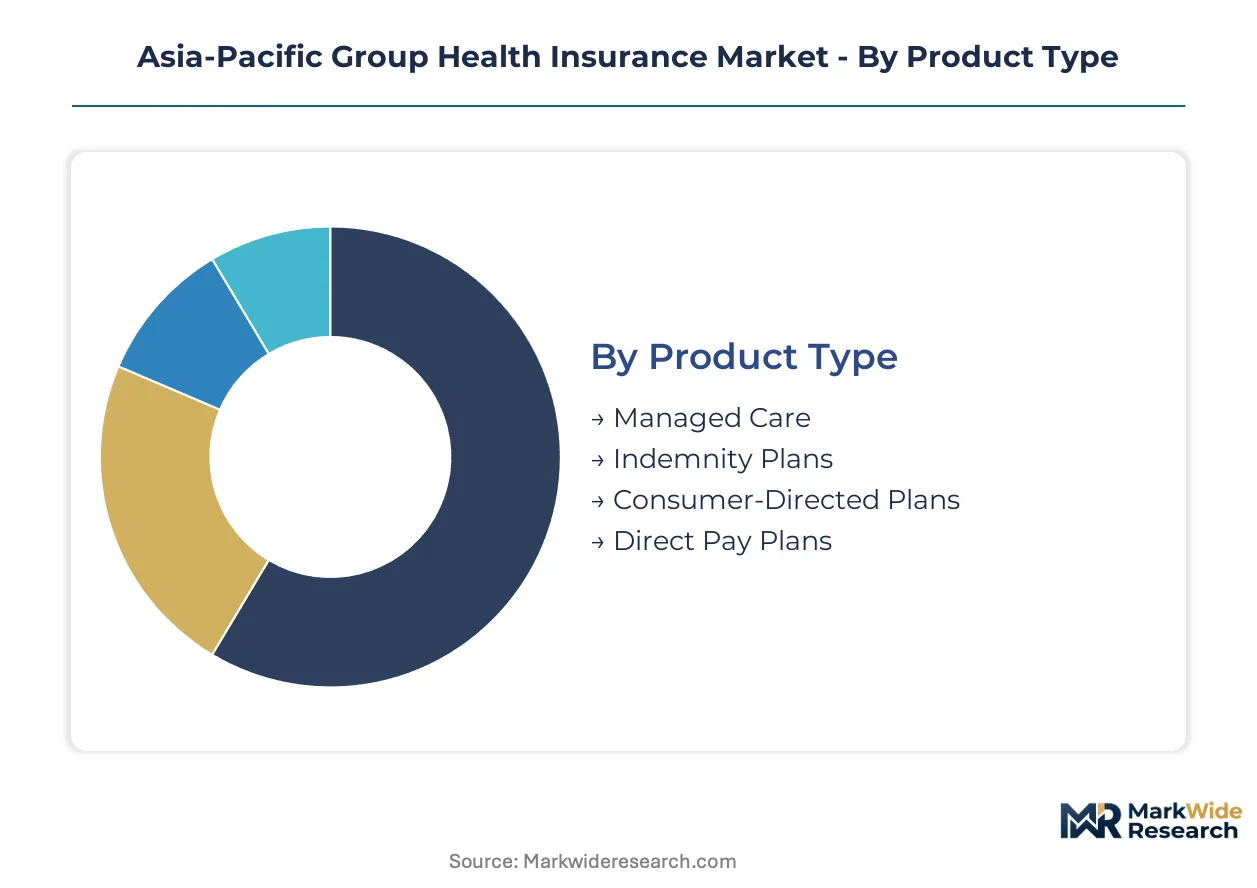
Asia-Pacific group health insurance exhibits structural fragmentation across four dimensions that determine pricing architecture, distribution economics, and regulatory compliance burdens. Product type stratification separates cost-control mechanisms from indemnity structures, while customer size dictates underwriting sophistication and servicing cost profiles.
Product Type:
Employer use-case spectrum spans from comprehensive risk transfer to cost-sharing arrangements calibrated to workforce demographics and budget constraints.
- Managed Care:Network-restricted coverage pools utilizing gatekeeper primary care and pre-authorization protocols to contain utilization. Demand concentrates among large manufacturing employers in China's Guangdong province seeking predictable per-employee costs under NMPA filing requirements.
- Indemnity Plans:Fee-for-service reimbursement without network restrictions, preserving employee provider choice. Technology employers in Bangalore and Mumbai deploy these for executive tiers where retention competition demands premium benefit positioning.
- Consumer-Directed Plans:High-deductible structures paired with health savings mechanisms, shifting first-dollar spending responsibility to employees. Mid-market professional services firms in Singapore and Australia pilot these for cost-conscious renewal cycles.
- Direct Pay Plans:Cashless settlement arrangements with designated hospital networks, eliminating reimbursement friction. Preferred by Japanese employers under METI wellness integration guidelines requiring streamlined claims experience.
Established volume favors Managed Care; emerging adoption favors Consumer-Directed Plans.
Customer Type:
Account size tiering determines distribution channel economics and actuarial sophistication requirements across the regional portfolio.
- Small Businesses:Employers with under 100 lives purchasing standardized products through intermediated channels. Regulatory minimums from India's IRDAI are expanding addressable enrollment among formalizing enterprises in secondary cities.
- Large Corporations:Multinational and domestic enterprises with 500+ employees commanding bespoke policy design and captive servicing teams. These accounts anchor premium generation across Shanghai, Tokyo, and Sydney corporate headquarters.
- Non-Profit Organizations:Mission-driven employers prioritizing benefit equity over cost minimization, often accepting community-rated pricing. Concentrated in India's social enterprise sector and ASEAN development organization networks.
- Government Agencies:Public sector employers with statutory coverage mandates and budget-cycle procurement constraints. China's state-owned enterprise reforms are expanding competitive bidding for these historically captive accounts.
Margin concentration sits with Large Corporations; policy count expansion centers on Small Businesses.
Distribution Channel:
Channel selection reflects price transparency tolerance and implementation complexity across buyer segments.
- Brokers:Commission-based intermediaries providing multi-carrier comparison and placement services. Retain dominance in multinational program coordination requiring cross-border harmonization.
- Online Platforms:Digital aggregators delivering instant premium benchmarking and policy issuance. Capturing mid-market share in price-transparent segments across India and Southeast Asia.
- Direct Sales:Insurer-employed representatives targeting large accounts with customized proposal development. Preferred by Japanese and South Korean employers for relationship-based renewal negotiations.
- Agents:Tied distribution representing single carriers with localized market knowledge. Sustains penetration in tier-2 Indian cities and Philippines provincial corporate clusters.
Digital displacement is accelerating fastest through Online Platforms; relationship complexity preserves Broker relevance.
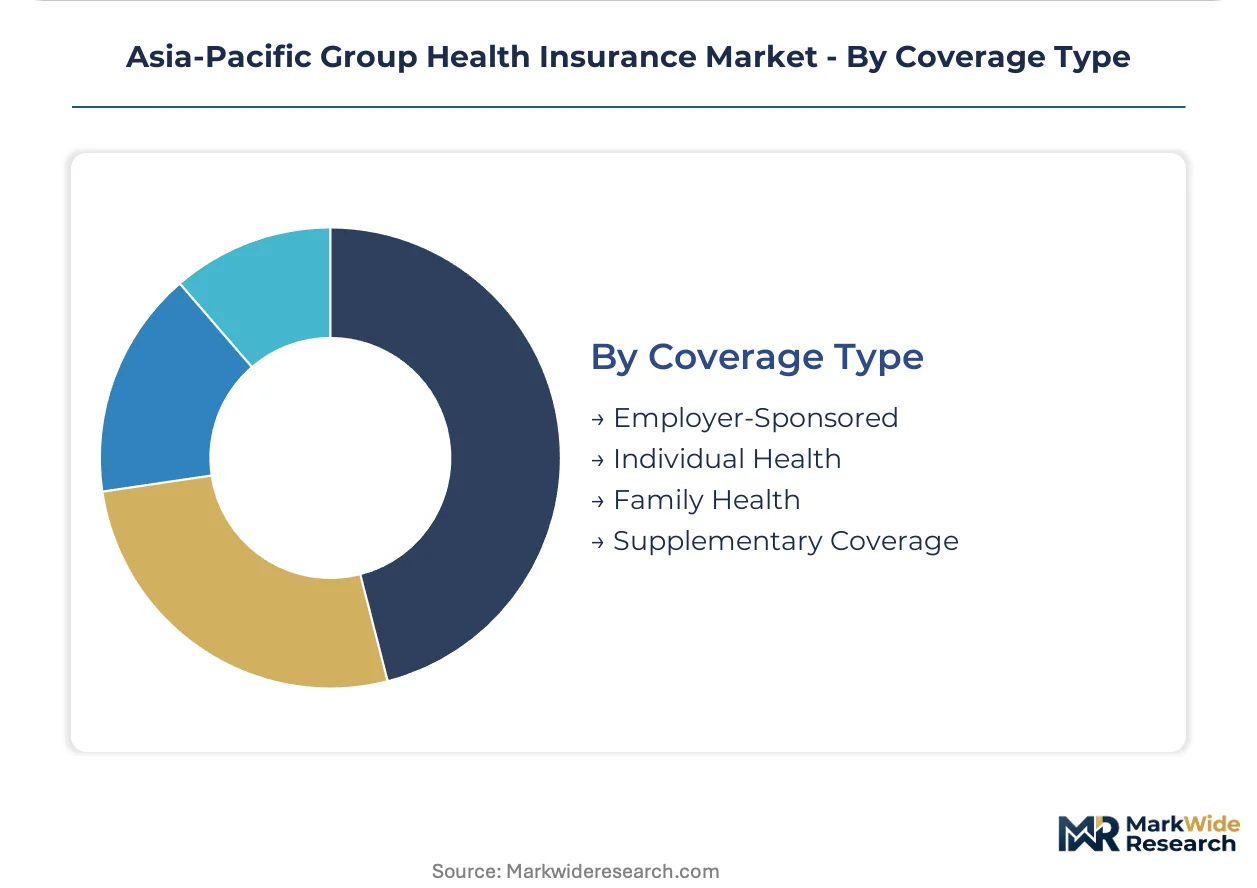
Coverage Type:
Benefit architecture separates employer-funded pools from individual voluntary arrangements with distinct risk selection dynamics.
- Employer-Sponsored:Group risk pools funded entirely or substantially by corporate sponsors, constituting the core market definition. China's dual carbon wellness mandates are restructuring these offerings toward preventive care integration.
- Individual Health:Voluntary coverage purchased outside employer arrangements, typically through conversion or portability provisions. Limited penetration in markets with strong formal sector employment.
- Family Health:Dependent coverage extensions beyond employee-only benefits, commanding premium multiples calibrated to household size. Standard inclusion in Australian and South Korean group contracts.
- Supplementary Coverage:Gap-filling products for deductibles, co-payments, and non-covered services. Expanding in Japan as employers shift to cost-sharing designs under METI guideline evolution.
Premium concentration remains with Employer-Sponsored structures; Supplementary Coverage is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific group health insurance market exhibits pronounced sub-regional specialization, with premium generation concentrating in economies where formal sector employment expansion intersects with regulatory benefit mandates. Cross-border policy servicing complexity varies significantly across national insurance frameworks.
China
Technology employers in Shenzhen and Hangzhou are expanding group enrollment as talent competition intensifies. NMPA wellness-linked filing requirements are restructuring product designs toward preventive care bundles. Manufacturing clusters in Guangdong province are standardizing biometric screening minimums for coverage eligibility.
India
IRDAI benefit floor mandates are formalizing employer-sponsored coverage across Bangalore and Mumbai corporate corridors. Production-linked incentive schemes for semiconductor and pharmaceutical manufacturing are creating captive workforce pools with standardized risk profiles. Digital distribution platforms are displacing traditional broker intermediation in mid-market accounts.
Japan
METI wellness integration guidelines are embedding preventive care riders into corporate benefit menus. Nippon Life and domestic carriers sustain dominance through conservative reserve management matched to long-duration liabilities. Tokyo and Osaka headquarters anchor premium concentration among multinational employer programs.
Australia
Fortune 500 regional headquarters in Sydney are consolidating vendor relationships toward single-platform direct contracts. Fee-for-service consulting is replacing commission-driven broker advice in large account procurement. Integrated health ecosystem providers are capturing share from traditional indemnity specialists.
South Korea
Seoul-based technology and financial services employers are piloting blockchain-verified claims processing to compress settlement cycles. Digital infrastructure investment is reducing per-claim servicing costs while extending coverage to distributed workforces. Relationship-based renewal negotiations preserve direct sales channel relevance.
Asia-Pacific Group Health Insurance Market Competitive Landscape
On the supply side, the industry is consolidating around integrated health ecosystem providers with end-to-end cost control capabilities. Regional champions with proprietary distribution platforms command pricing power in fragmented Southeast Asian markets. Three strategic archetypes dominate: asset-light operators leveraging third-party administrator partnerships, vertically integrated players controlling captive provider networks, and digital-native platforms capturing mid-market share through transparent benchmarking. Competitive dynamics center on M&A activity targeting TPAs with established hospital relationships, and API-enabled payroll platform partnerships that embed coverage at employment onboarding.
Among Asia-Pacific-based insurers, Ping An Insurance Group exemplifies the integrated ecosystem archetype through its healthcare service verticals. AIA Group anchors Southeast Asian digital distribution with proprietary platforms spanning multiple national markets. Nippon Life occupies the conservative liability-matching position within Japan's mature employer-sponsored segment. European multinationals Allianz and AXA represent the cross-border program coordination tier, serving multinational employers requiring harmonized coverage across regulatory jurisdictions.
| Leading Market Players |
|---|
| Allianz |
| Nippon Life |
| AIA Group |
| QBE Insurance Group |
| LIC of India |
| Ping An Insurance Group |
| AXA |
| SBI Life Insurance |
| China Life Insurance Company |
| Others |
Value Network & Pricing Analysis
Shanghai's tier-1 hospital network concentration shapes insurer negotiating leverage and downstream premium calibration across employer-sponsored coverage pools. Guangdong province manufacturing clusters feed capacity into wellness-linked policy designs, compressing implementation timelines for biometric screening mandates while elevating operational cost structures.
Pricing Analysis
Large corporation procurement committees anchor premium negotiations through consolidated single-platform contracts that displace commission-driven broker intermediation. Pricing stratifies across premium indemnity tiers for executive retention, standard managed care pools for workforce-wide enrollment, and economy digital-only products for cost-conscious mid-market buyers. Premium pressure intensifies as telemedicine infrastructure commoditizes basic coverage components, though relationship-based direct sales channels preserve pricing power in Japanese and South Korean accounts. Small businesses exhibit highest price sensitivity through online platform comparison tools, while multinational headquarters demonstrate lowest sensitivity when coordinating cross-border harmonization.
Supply Chain Analysis
Third-party administrator partnerships in India and Southeast Asia concentrate policy servicing capacity, with TPAs in Bangalore and Mumbai managing enrollment administration and claims adjudication workflows. Raw material dependencies center on hospital network credentialing databases, biometric screening infrastructure, and digital platform development talent. Single-source vulnerability runs through concentrated tier-1 metropolitan provider oligopolies in Tokyo, Singapore, and Sydney that limit reimbursement rate negotiating leverage. Distribution runs through API-enabled payroll platform integrations that embed coverage origination at employment onboarding, compressing traditional broker channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-insured employer alternatives and health savings account structures threaten traditional risk-transfer policy economics, forcing incumbents to defend embedded distribution relationships against disintermediation.
For Market Incumbents: Harden proprietary digital distribution platforms against payroll aggregator encroachment by securing exclusive API partnerships with dominant HRIS providers in India and Southeast Asia. Deepen captive hospital network relationships in Shanghai and Tokyo to defend reimbursement negotiating position against tier-1 provider consolidation. Prioritize TPA acquisition targets with established biometric screening infrastructure to meet China's NMPA wellness-linked filing requirements. For New Entrants and Emerging Players: Pursue white-space positioning in Vietnam and Philippines formal sector expansion, where employer-sponsored coverage transitions from executive-only to workforce-wide enrollment with limited incumbent digital presence. Target mid-market technology employers in Bangalore and Singapore with transparent premium benchmarking tools that displace traditional broker relationships. Lead with telemedicine-embedded product designs that reduce per-claim servicing costs below legacy operator structures. For Investors and Strategic Acquirers: Long-term, this sits as a regional consolidation play because fragmented ASEAN compliance obligations multiply operational complexity and favor scaled operators with harmonized policy administration platforms. Acquisition targets should emphasize TPAs with established hospital network credentialing across multiple regulatory jurisdictions. Monitor India's IRDAI benefit floor mandate expansion into secondary cities as enrollment volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API-Enabled Payroll Integration | Captures lifetime value through automated renewal workflows embedded at employment onboarding across Indian technology corridors. |
| TPA Acquisition with Hospital Networks | Secures negotiating leverage against tier-1 provider oligopolies in Shanghai, Tokyo, and Singapore reimbursement rate setting. |
| Biometric Screening Infrastructure Buildout | Meets China's NMPA wellness-linked filing requirements for manufacturing employers in Guangdong and Jiangsu provinces. |
| Blockchain Claims Processing Pilot | Compresses settlement cycles from weeks to days for Seoul-based technology and financial services employer accounts. |
| Preventive Care Rider Development | Aligns product architecture with Japan's METI wellness integration guidelines embedding smoking cessation and gym membership subsidies. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with group insurance underwriters, third-party administrator executives, and HR benefits directors at technology and manufacturing employers; and secondary validation through IRDAI regulatory filings, NMPA product registration databases, and METI wellness program disclosure documents. Bottom-up enrollment data from Bangalore, Mumbai, and Shenzhen corporate clusters triangulated against top-down premium estimates from regional carrier financial disclosures.
Forecast inputs incorporated product type segmentation across managed care, indemnity, consumer-directed, and direct pay structures; customer size tiering from small business through large corporation accounts; and distribution channel evolution from broker intermediation toward online platform displacement. CAGRs derived from regression analysis of historical enrollment expansion correlated with formal sector employment growth and regulatory benefit mandate implementation across the projection horizon.
Sensitivities concentrate around medical inflation volatility in specialized pharmaceuticals, hospital network consolidation in tier-1 metropolitan markets, and legacy HRIS integration friction extending implementation timelines. Quarterly review of IRDAI mandate expansion announcements, NMPA wellness-linked filing updates, and METI guideline evolution is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Horse Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Title Insurance Market
Insurance
Financial Guarantee Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Europe Online Insurance Market
Insurance
Global SME Insurance Market
Insurance
Europe Health Insurance Market
Insurance
Art Insurance Market
Insurance
Aircraft Insurance Market
Insurance
Bancassurance Market
Insurance
Jewelry Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Green Insurance Market
Insurance
AI in Insurance Market