
 Sensor Landscape in Robotics and ADAS Vehicle Market | 2026-2036
Sensor Landscape in Robotics and ADAS Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Landscape in Robotics and ADAS Vehicle Market Insights
Fleet operators are unwinding legacy reliance on aftermarket retrofit kits as OEMs integrate sensor suites at the factory gate. Robert Bosch GmbH leverages in-house MEMS fabrication to control cost curves across ultrasonic and radar portfolios. Continental AG anchors European supply through its lidar joint ventures and ADAS software stack integration. NVIDIA differentiates by supplying the DRIVE platform as the compute layer where camera, radar, and lidar data streams converge for real-time perception.
The sensor landscape in robotics and ADAS vehicles encompasses optoelectronic, electromagnetic, and acoustic transducers engineered to detect objects, measure distance, and map environments with sub-centimeter precision at operational speeds up to 250 meters. These devices function through time-of-flight laser pulses, frequency-modulated continuous-wave radar, CMOS image arrays, and piezoelectric echo ranging, serving the primary purpose of enabling machine perception for safe autonomous motion. Lidar modules command premium positioning in highway autonomy stacks where 360-degree coverage and high-definition point clouds resolve edge-case scenarios, while camera systems dominate volume deployment in driver assistance due to mature supply chains and declining unit costs. Sensor fusion architectures are gaining structural importance as the integration layer that arbitrates conflicting inputs across radar, lidar, and visual channels, creating margin pools for software-defined perception platforms.
The UNECE R157 regulation mandates specific sensor performance thresholds for automated lane-keeping systems sold in European markets, directly influencing lidar range and camera resolution specifications. The EU AI Act imposes conformity assessment requirements on safety-critical AI components embedded in sensor processing pipelines, extending compliance burdens to Tier-1 suppliers and OEMs. In the United States, NHTSA FMVSS updates and state-level autonomous vehicle statutes create a fragmented but tightening compliance map for sensor validation and failure-mode documentation. Stakeholders must monitor how regulatory divergence between European type-approval frameworks and American self-certification protocols reshapes R&D allocation and platform architecture decisions across the decade ahead.
Market Dynamics
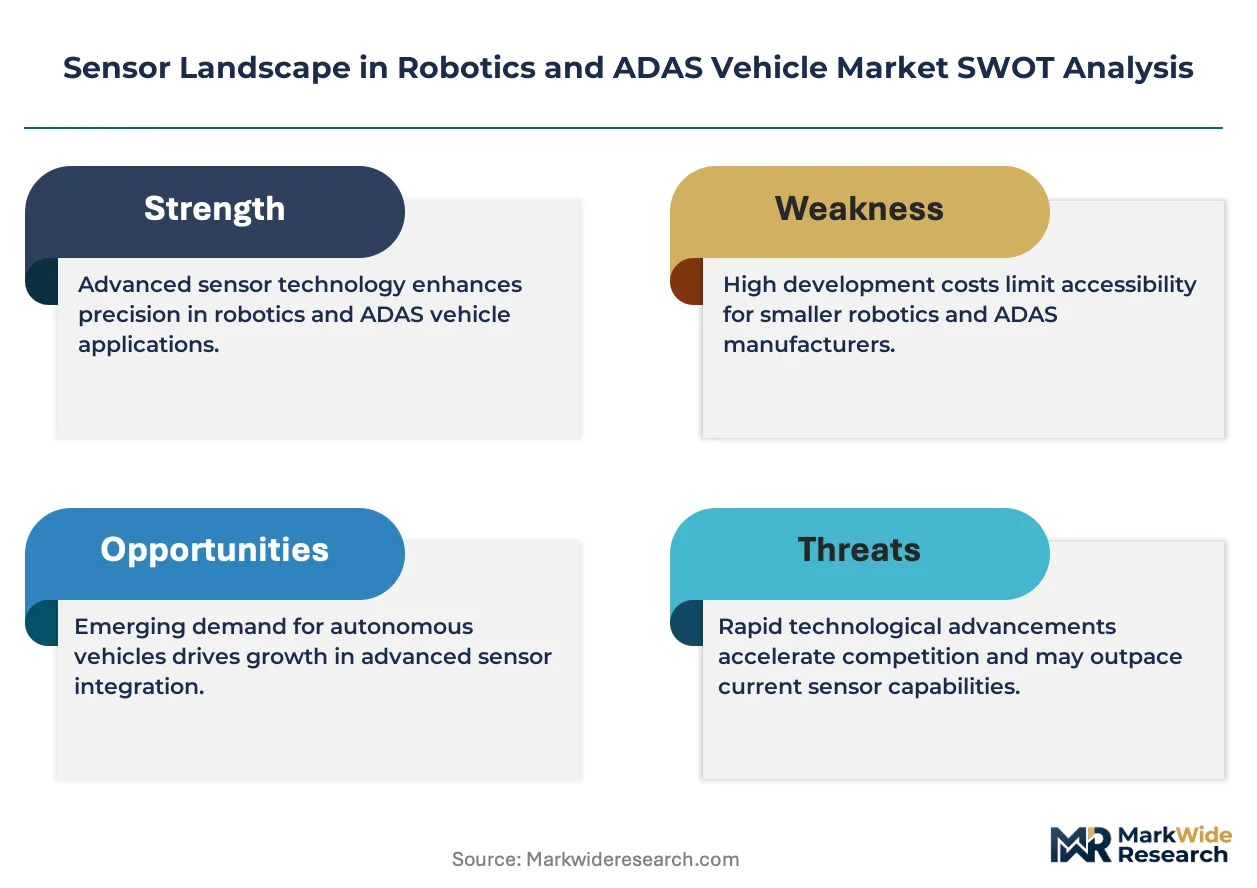
Sensor fusion architectures are compressing the value chain as software-defined perception platforms absorb discrete hardware margins across robotics and ADAS deployments.
Growth Catalysts
- EU AI Act conformity pathways:The regulation mandates third-party assessment for safety-critical AI components, creating certified supplier tiers that lock in long-term procurement relationships for compliant sensor modules.
- Level-3 highway automation programs:OEM validation cycles for hands-off driving are expanding factory-integrated lidar volumes as fleet operators abandon aftermarket retrofit strategies.
- MEMS fabrication scale:In-house semiconductor production at major Tier-1 suppliers is flattening unit cost curves for ultrasonic and radar portfolios across German and Japanese supply bases.
Market Restraints
- Indium phosphide supply concentration:Laser emitter substrates for 1550nm lidar systems source predominantly from Chinese refiners, exposing European and North American module assemblers to export control volatility.
- UNECE R157 validation timelines:The regulation's specific sensor performance thresholds for automated lane-keeping extend type-approval cycles by 8-14 months, compressing launch windows for new vehicle platforms.
- Camera-to-radar substitution in parking assistance:Ultrasonic echo-ranging systems retain cost advantage below 5-meter detection ranges, limiting lidar penetration in low-speed maneuvering applications.
Strategic Opportunities
- Indian PLI scheme for automotive electronics:The production-linked incentive framework is attracting sensor packaging investments to serve domestic OEMs and re-export to Middle Eastern markets.
- Silicon photonics convergence:CMOS-compatible optical phased arrays are enabling chip-scale lidar integration that collapses mechanical complexity in robotics navigation stacks.
- Direct OEM-channel bypass:Fleet operators with centralized procurement functions are negotiating sensor-suite specifications upstream of Tier-1 assembly contracts, capturing specification influence.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise concentrates in Stuttgart, Tokyo, and Detroit metro areas, constraining validation bandwidth at emerging robotics startups.
- Multi-sensor calibration complexity:Temporal synchronization across camera, radar, and lidar streams demands specialized test rigs that extend manufacturing cycle times at low-volume assembly plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Landscape in Robotics and ADAS Vehicle Market |
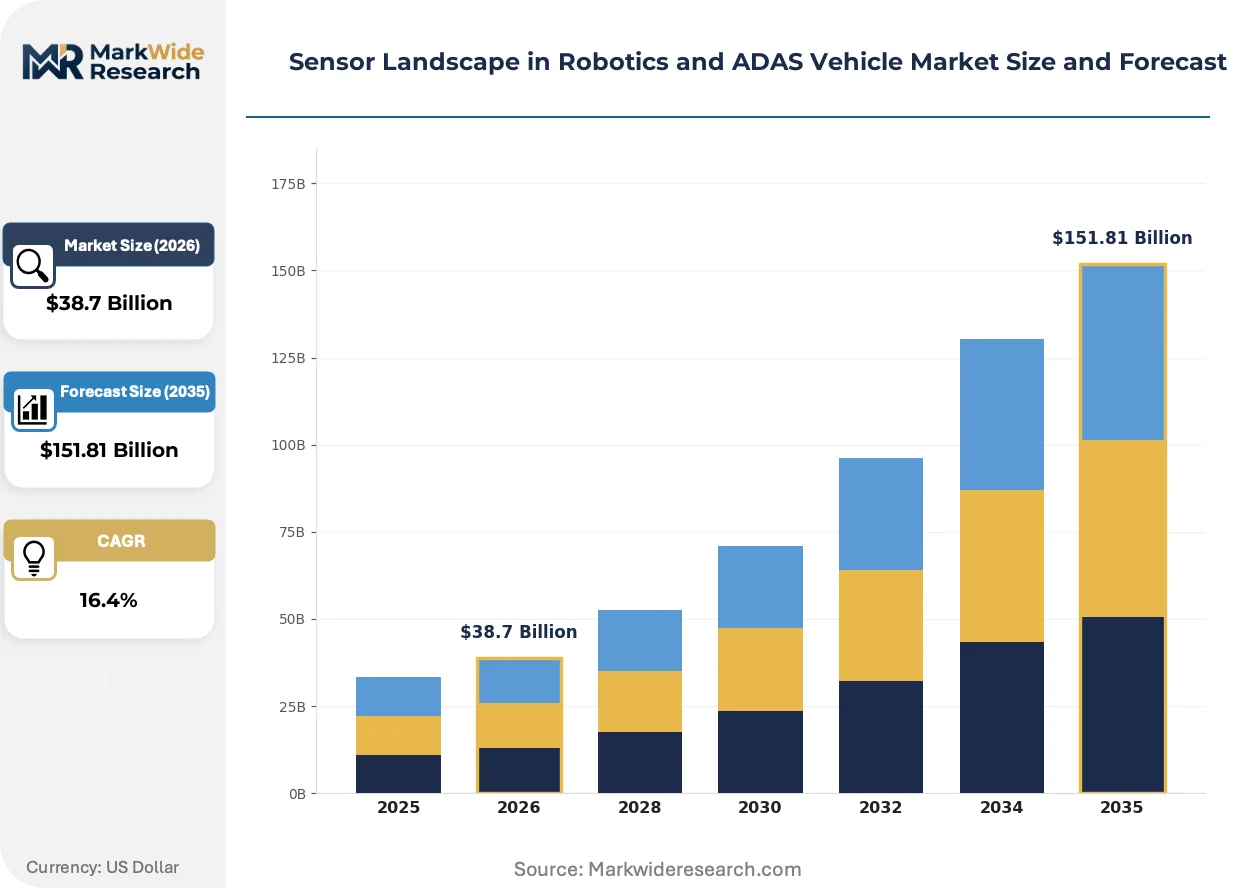
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Lidar, Radar, Camera, Ultrasonic Application Area: Autonomous Navigation, Collision Avoidance, Environmental Mapping, Driver Assistance End User Segment: OEMs, Tier-1 Suppliers, Fleet Operators, Aftermarket Installers Technology Feature: Real-Time Processing, High Definition Imaging, 360-Degree Coverage, Sensor Fusion |
| Companies Covered | Robert Bosch GmbH, Continental AG, Infineon Technologies AG, NXP Semiconductor N.V., ST Microelectronics NV, Denso Corporation, Texas Instruments Incorporated, Valeo SA, NVIDIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Landscape in Robotics and ADAS Vehicle Market Trends and Innovations
Hardware commoditization pressures are forcing differentiation migration toward perception software stacks and real-time fusion algorithms that arbitrate conflicting sensor inputs.
Solid-state lidar is decomposing the mechanical scanning architectures that dominated early autonomous vehicle prototypes. Automotive OEMs are specifying optical phased arrays for 2026 production platforms, collapsing moving-part counts from hundreds to zero. This technology compression is eroding the service-revenue streams that aftermarket lidar maintainers built around mechanical wear-component replacement cycles.
UNECE R157 is tightening sensor performance thresholds for automated lane-keeping systems sold across European markets. The regulation mandates specific minimum detection ranges and angular resolution standards that disqualify legacy camera-only architectures. German and Swedish OEMs are responding by pre-integrating short-range lidar modules into headlamp clusters to guarantee compliance without visible sensor protrusions.
Fleet procurement functions are consolidating specification authority previously dispersed across engineering and maintenance departments. Large logistics operators in the United States are issuing unified sensor-suite requirements that Tier-1 suppliers must meet to qualify for multi-year frame contracts. This buyer concentration is visible most acutely in long-haul trucking, where ten carriers now control procurement decisions affecting sixty percent of highway automation sensor volumes.
Sensor Landscape in Robotics and ADAS Vehicle Market Segmentation
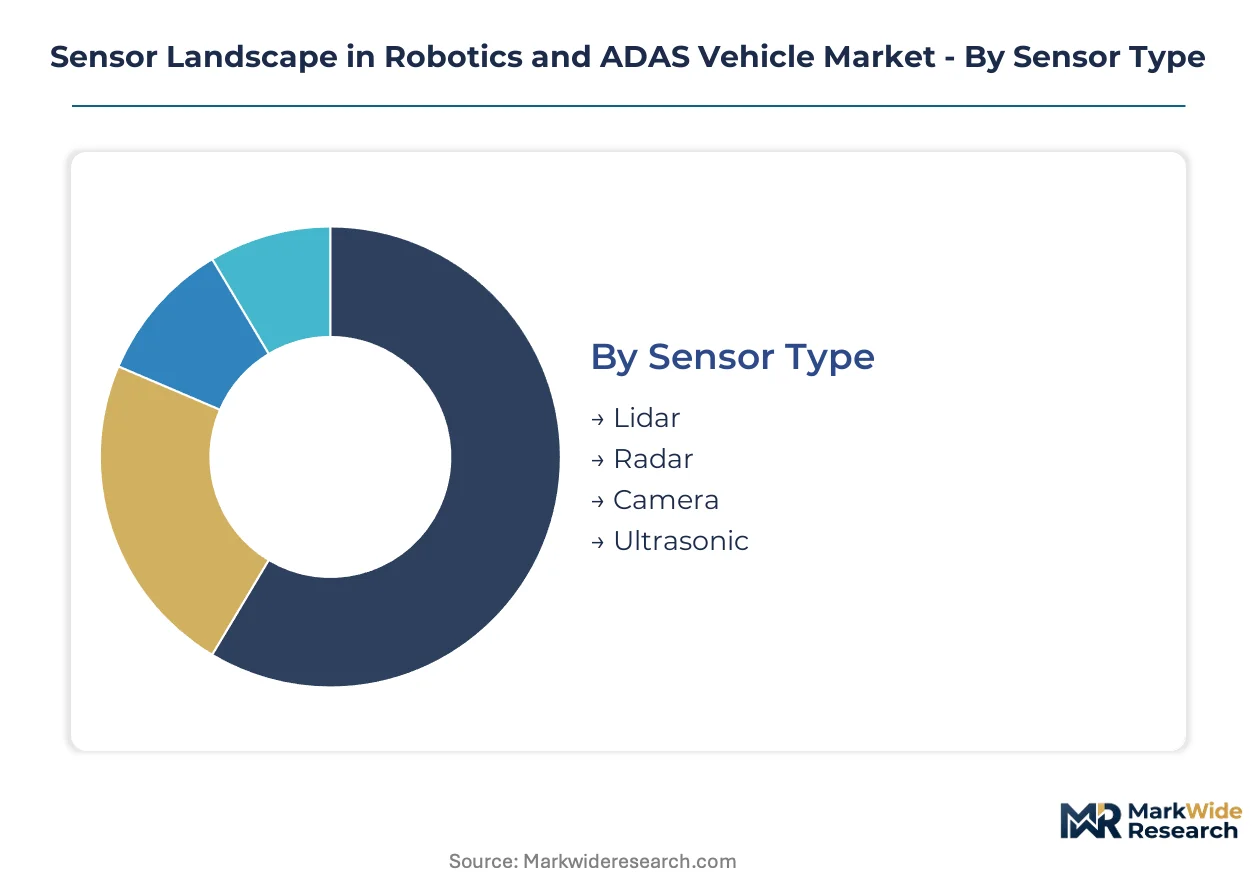
Sensor procurement patterns diverge sharply across deployment contexts, with highway autonomy commanding premium lidar specifications while parking assistance tolerates lower-cost ultrasonic arrays. Margin capture concentrates in software-defined perception platforms that arbitrate multi-sensor inputs rather than discrete hardware modules.
Sensor Type:
Margin pools concentrate in solid-state lidar modules where optical phased arrays displace mechanical scanning architectures and collapse service-revenue opportunities for aftermarket maintainers.
- Lidar:Time-of-flight laser pulse systems generate high-definition point clouds with sub-centimeter precision at operational ranges exceeding 200 meters. German and Swedish OEMs are pre-integrating short-range solid-state variants into headlamp clusters to satisfy UNECE R157 detection-range mandates without visible sensor protrusions.
- Radar:Frequency-modulated continuous-wave systems penetrate atmospheric obscurants and measure relative velocity through Doppler shift calculations. Robert Bosch GmbH leverages captive MEMS fabrication in Germany to flatten unit cost curves across 77GHz and 79GHz automotive portfolios.
- Camera:CMOS image arrays dominate volume deployment in driver assistance due to mature supply chains and declining unit costs from consumer electronics scale.
- Ultrasonic:Piezoelectric echo-ranging retains cost advantage below 5-meter detection ranges, constraining lidar penetration in low-speed parking maneuver applications.
Lidar holds installed capacity. Radar is rotating up the share rankings as highway automation programs validate all-weather reliability requirements.
Application Area:
Cost tiers separate safety-critical highway functions from convenience-oriented parking assistance, with regulatory mandates dictating minimum sensor performance thresholds rather than OEM discretion.
- Autonomous Navigation:Machine perception stacks process fused sensor streams to enable unmanned vehicle motion across unstructured environments. Fleet operators in the United States are consolidating procurement specifications upstream of Tier-1 contracts, demanding 360-degree coverage as a baseline qualification for long-haul trucking frame agreements.
- Collision Avoidance:Real-time object detection and trajectory prediction systems execute emergency braking and steering interventions. The EU AI Act conformity assessment requirements extend compliance burdens to safety-critical AI components embedded in these processing pipelines.
- Environmental Mapping:Simultaneous localization and mapping algorithms construct persistent geometric representations of operational areas.
- Driver Assistance:Lane-keeping and adaptive cruise control functions operate with reduced sensor redundancy compared to full autonomy stacks.
Autonomous Navigation commands premium pricing. Collision Avoidance is expanding fastest as regulatory minimums tighten across European and North American type-approval frameworks.
End User Segment:
Customer type determines specification authority, with centralized fleet procurement functions displacing fragmented engineering and maintenance department influence.
- OEMs:Vehicle manufacturers integrate sensor suites at the factory gate, unwinding legacy aftermarket retrofit strategies. Ten long-haul trucking carriers now control procurement decisions affecting sixty percent of highway automation sensor volumes in the United States.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG anchor European supply through lidar joint ventures and ADAS software stack integration, capturing margin in sensor fusion arbitration layers.
- Fleet Operators:Logistics companies with centralized procurement functions negotiate sensor-suite specifications directly, bypassing traditional Tier-1 channel structures.
- Aftermarket Installers:Retrofit kit providers face structural decline as OEMs pre-integrate compliance-mandated hardware.
OEMs hold installed capacity. Fleet Operators are rotating up the share rankings through direct specification influence.
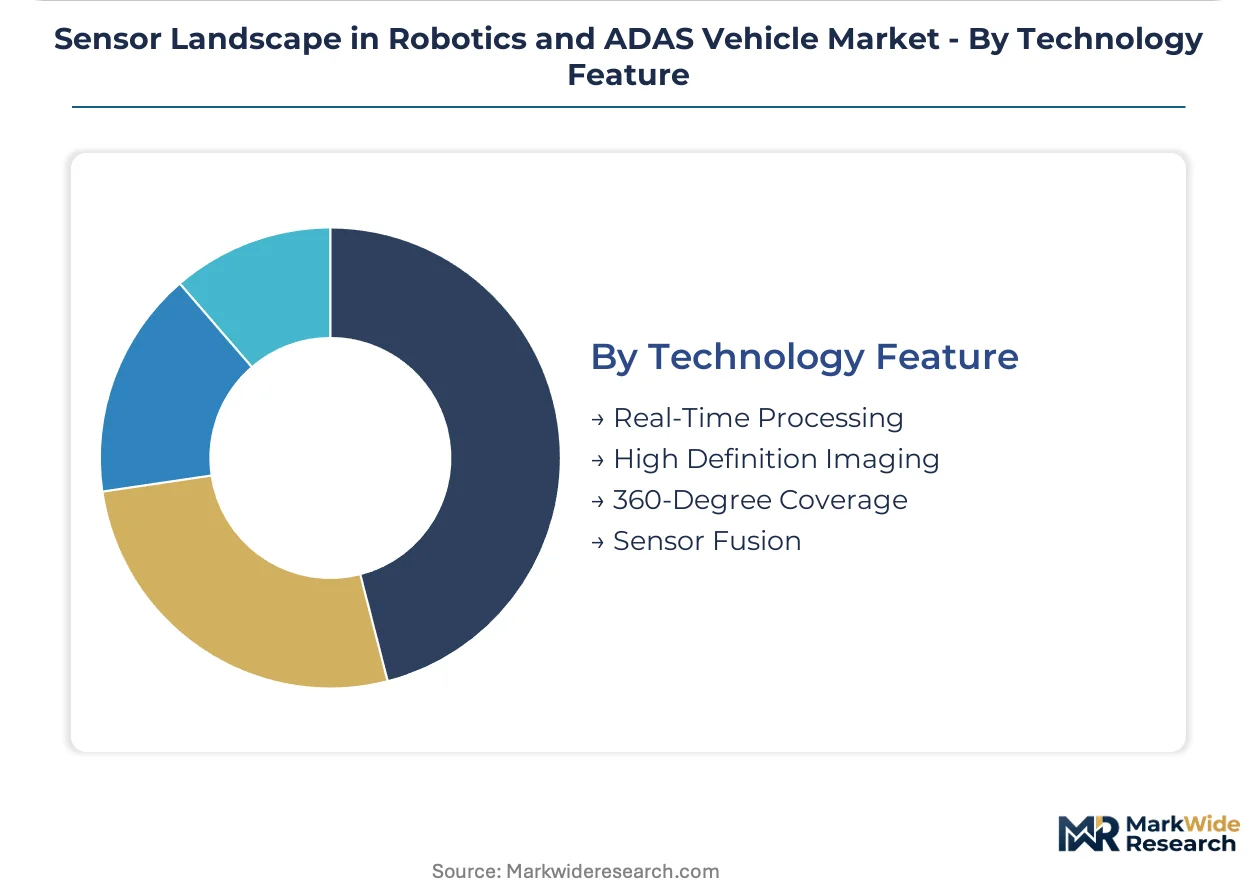
Technology Feature:
Supply concentration in functional safety engineering expertise constrains validation bandwidth for advanced technology integrations.
- Real-Time Processing:Edge computing architectures execute perception algorithms within deterministic latency budgets. NVIDIA supplies the DRIVE platform as the compute layer where camera, radar, and lidar data streams converge for autonomous decision-making.
- High Definition Imaging:Dense point cloud and pixel array resolutions enable classification of small or partially occluded objects. ISO 26262 certification expertise concentrates in Stuttgart, Tokyo, and Detroit metro areas, limiting validation capacity at emerging robotics startups.
- 360-Degree Coverage:Multi-sensor ring configurations eliminate blind spots for unstructured environment navigation.
- Sensor Fusion:Software-defined perception platforms arbitrate conflicting inputs across heterogeneous sensor modalities.
Real-Time Processing holds installed capacity. Sensor Fusion is rotating up the share rankings as the primary margin capture mechanism in perception stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's sensor export capacity for European OEM supply chains, while the Trans-Siberian rail corridor links Chinese component hubs to assembly plants across Eurasia.
United States
Long-haul trucking fleets in the Great Lakes corridor specify 360-degree sensor coverage as a baseline for procurement contracts. NHTSA FMVSS updates create fragmented compliance requirements across state jurisdictions. Detroit's functional safety engineering clusters concentrate ISO 26262 certification expertise for sensor validation pipelines.
Germany
Stuttgart-based OEMs pre-integrate solid-state lidar into headlamp clusters to satisfy detection-range mandates without visible protrusions. UNECE R157 regulation tightens sensor performance thresholds for automated lane-keeping systems. Bavaria's MEMS fabrication facilities supply captive semiconductor production for radar and ultrasonic portfolios.
Japan
Tokyo metro area suppliers leverage in-house semiconductor fabrication to control cost curves across sensor modules. METI industrial policy directs investment toward autonomous navigation hardware for export markets. Nagoya's automotive engineering clusters validate multi-sensor fusion architectures for highway automation programs.
China
Domestic OEMs localize supply chains for advanced driver-assistance platforms across the Yangtze River Delta. MIIT standards harmonize sensor validation protocols for passenger vehicle type approval. Shenzhen's optoelectronics manufacturing bases produce CMOS image arrays at consumer electronics scale.
India
The PLI scheme for automotive electronics attracts sensor packaging investments to serve domestic OEMs and re-export to Middle Eastern markets. BIS certification requirements extend compliance timelines for imported module assemblies. Tamil Nadu's automotive component clusters integrate ultrasonic and radar arrays for parking assistance systems.
Sensor Landscape in Robotics and ADAS Vehicle Market Competitive Landscape
Concentration sits with diversified Tier-1 automotive suppliers that combine captive semiconductor fabrication with ADAS software integration. The vendor base spans three distinct tiers: integrated systems houses with in-house MEMS production, fabless perception platform providers, and specialized component fabricators. Two strategic moves dominate competitive positioning: backward integration into laser emitter substrate supply and forward integration into fleet-direct specification channels.
Among European-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the systems-house archetype that captures margin in sensor fusion arbitration layers. NVIDIA occupies a position as the compute-layer anchor where heterogeneous sensor streams converge for real-time perception. These three entities represent the dominant competitive anchors across hardware fabrication, software-defined platforms, and fleet procurement influence.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Infineon Technologies AG |
| NXP Semiconductor N.V. |
| ST Microelectronics NV |
| Denso Corporation |
| Texas Instruments Incorporated |
| Valeo SA |
| NVIDIA |
| Others |
Pricing and Supply Chain Analysis
Optical phased arrays displacing mechanical lidar scanning architectures simultaneously shift production geography toward CMOS-compatible semiconductor fabs and collapse aftermarket service revenue that previously subsidized hardware margins. This substitution dynamic concentrates pricing power with captive MEMS fabricators while eroding the three-tier service-contract structures that mechanical lidar maintainers built around component replacement cycles.
Pricing Analysis
Volume-discount tiering structures separate highway automation programs commanding 360-degree coverage specifications from parking assistance tolerating ultrasonic arrays below five-meter ranges. Price differentiation hinges on ISO 26262 ASIL certification grades and fleet-scale procurement consolidation, with long-haul trucking operators extracting steeper discounts than fragmented aftermarket installers. Pricing pressure stems from Tier-1 suppliers flattening unit cost curves through in-house semiconductor fabrication. Fleet operators exhibit highest price sensitivity due to centralized specification authority, while robotics startups navigating unstructured environments accept premium positioning for sensor fusion arbitration layers.
Supply Chain Analysis
China and Germany anchor indium phosphide refining and MEMS fabrication respectively, creating bifurcated dependency chains for 1550nm laser emitters and radar transceiver modules. Raw material inputs draw from Chinese rare earth processors for optical substrates and Bavarian semiconductor foundries for piezoelectric arrays. Single-source vulnerability concentrates in indium phosphide supply exposed to export control volatility. Distribution runs through Tier-1 assembly contracts with direct OEM channel bypass emerging among consolidated fleet procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sensor landscape sits at an early-cycle expansion phase where Level-3 highway automation validation cycles are accelerating factory-integrated lidar penetration beyond legacy aftermarket retrofit strategies.
For Market Incumbents: Consolidate backward integration into laser emitter substrate supply and captive MEMS fabrication capacity to defend margin pools against fabless perception platform entrants. Lock in long-term procurement relationships through EU AI Act conformity certification pathways that emerging competitors cannot replicate within validation timelines. Prioritize sensor fusion software stack development as the primary margin capture mechanism displacing discrete hardware premiums. For New Entrants and Emerging Players: Fleet-direct specification channels where centralized procurement functions bypass traditional Tier-1 assembly contracts represent the most penetrable white-space target for robotics navigation stacks. Target Indian PLI scheme beneficiaries seeking automotive electronics packaging partnerships for Middle Eastern re-export markets. Deploy silicon photonics convergence roadmaps as the go-to-market angle collapsing mechanical complexity against incumbent solid-state lidar architectures. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors fabless perception platform providers with sensor fusion arbitration expertise over pure-play hardware fabricators. Long-term viability centers on software-defined margin capture rather than commoditized transducer production. Watch for inflection signals in fleet procurement consolidation ratios as ten carriers now control sixty percent of highway automation sensor volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Emitter Supply | Captive indium phosphide sourcing insulates European module assemblers from Chinese export control volatility. |
| Sensor Fusion Platform Development | Software-defined perception arbitration captures margin pools as hardware commoditization pressures intensify. |
| Fleet-Direct Specification Channel | Centralized procurement functions at long-haul trucking operators displace Tier-1 channel intermediaries. |
| Silicon Photonics Convergence Roadmap | CMOS-compatible optical phased arrays collapse mechanical complexity in robotics navigation stacks. |
| EU AI Act Conformity Certification | Third-party assessment lock-in creates certified supplier tiers securing multi-year procurement relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of UNECE regulatory filings, MIIT standards documentation, and vehicle production databases. Primary interviews engaged OEM platform engineers, Tier-1 supplier procurement leads, fleet operations directors, and functional safety certification specialists. Secondary validation drew from NHTSA FMVSS updates, EU AI Act conformity assessment protocols, and customs records tracking sensor module trade flows. Bottom-up unit economics triangulate against top-down market sizing across sensor type and application area segmentation.
Segmentation dimensions modeled include sensor modality, automation function tier, end-user procurement authority, and regional regulatory cluster. Analytical frameworks project volume and value outputs across the analysis window through elasticity-adjusted adoption curves. CAGRs derive from regression analysis against historical penetration rates and policy mandate timelines. Industry-specific forecast inputs incorporate UNECE R157 validation cycle extensions and MEMS fabrication capacity expansion schedules.
Underlying assumptions cover regulatory harmonization trajectories, with deviation risk concentrated in export control actions affecting indium phosphide supply chains and fleet procurement consolidation velocity. Forecasts reflect documented conditions subject to revision upon material shifts in type-approval frameworks or semiconductor fabrication geography. Recalibration cycles align with regulatory implementation phases and Tier-1 supplier capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
IO Link Market
Sensors
Personal Navigation Devices Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Yield Monitoring Systems Market
Sensors
Transport Monitoring System Market
Sensors
Lidar Market
Sensors
Safety Motion Control System Market
Sensors
Heat Stress Meter Market
Sensors
Refrigeration Monitoring Market
Sensors
Smart Barcode Readers Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
APAC Wireless Sensors Market
Sensors
Digital Direction Finder Market
Sensors
Industrial Barcode Scanners Market
Sensors
Barcode Scanner Market