
 Europe REIT Market | 2026-2036
Europe REIT Market Size, Share, and Industry Trends Forecast 2026-2036
Europe REIT Market Insights
The premium-commodity split in European REITs is consolidating around energy performance certificates and green building certifications. Vonovia SE anchors the German residential segment through scale advantages in regulated rent markets. Segro dominates UK and Continental logistics with specialized exposure to last-mile fulfillment infrastructure. Unibail-Rodamco-Westfield navigates the retail recovery with differentiated flagship asset positioning in Paris, London, and Madrid.
A real estate investment trust pools capital from multiple investors to own, operate, or finance income-producing properties across commercial, residential, industrial, and hospitality categories, with European REITs typically structured as listed vehicles subject to minimum distribution requirements and leverage limits set by national regulators. Residential REITs sustain defensive cash flow profiles supported by housing shortages in major German and Dutch urban centers. Industrial REITs lead growth trajectories as e-commerce fulfillment demand reshapes warehouse specifications toward higher clear heights and automation readiness. Core strategies occupy the deepest institutional capital pools while opportunistic approaches concentrate residual value creation in transitional assets requiring active repositioning.
EU Green Deal carbon targets, CSRD sustainability disclosure rules, and national building energy codes collectively force portfolio decarbonization timelines and capital expenditure commitments across European REITs. EMA guidelines on stress testing and ECB interest rate policy transmission through mortgage and corporate debt markets directly shape refinancing risk and acquisition capacity. Stakeholders must monitor regulatory tightening on embodied carbon in new construction and the divergence between green-certified premium rents and stranded asset discounts in secondary locations.
Market Dynamics
Institutional capital rotation into energy-efficient logistics and residential portfolios is compressing yield spreads and forcing portfolio repositioning across European REITs. The EU Green Deal's carbon reduction timelines and CSRD disclosure mandates are accelerating capital deployment into certified assets while stranding secondary locations.
Growth Catalysts
- CSRD Mandates:The EU's Corporate Sustainability Reporting Directive forces granular energy performance disclosure, redirecting institutional flows toward green-certified portfolios and penalizing opaque holdings.
- E-commerce Fulfillment Density:Last-mile warehouse demand in Dutch and German urban corridors is absorbing speculative development and tightening vacancy rates below structural equilibrium.
- Regulated Rent Markets:German Mietendeckel reforms and successor frameworks preserve occupancy stability in residential REITs, insulating cash flows from cyclical volatility.
Market Restraints
- ECB Rate Transmission:European Central Bank policy tightening has reset debt pricing across Eurozone REITs, compressing acquisition capacity and extending hold periods for maturing loans.
- Construction Input Volatility:Steel and concrete cost fluctuations in Central European supply chains are eroding development margins and delaying ground-breaking on speculative logistics projects.
- Secondary Location Stranding:Energy Performance Certificate thresholds in France and Germany are devaluing Class C and D office assets, trapping capital in depreciating positions.
Strategic Opportunities
- Polish Logistics Corridor:Underpenetrated warehouse stock between Warsaw and Łódź offers yield premiums as manufacturing reshoring accelerates and cross-border fulfillment networks expand.
- Building-to-Grid Integration:Smart meter and battery storage convergence in Nordic residential portfolios enables ancillary revenue streams from demand-response participation.
- EU Taxonomy Alignment:Green bond eligibility for renovation and new construction creates preferential financing access for REITs with certified development pipelines.
Industry Challenges
- Retrofit Execution Gap:Deep energy renovation of 1970s office stock requires specialized contractor capacity that remains scarce in Belgian and Dutch construction markets, extending project timelines.
- Data Architecture Fragmentation:Portfolio-level ESG reporting demands integration across incompatible building management systems, elevating IT capital intensity and vendor management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe REIT Market |
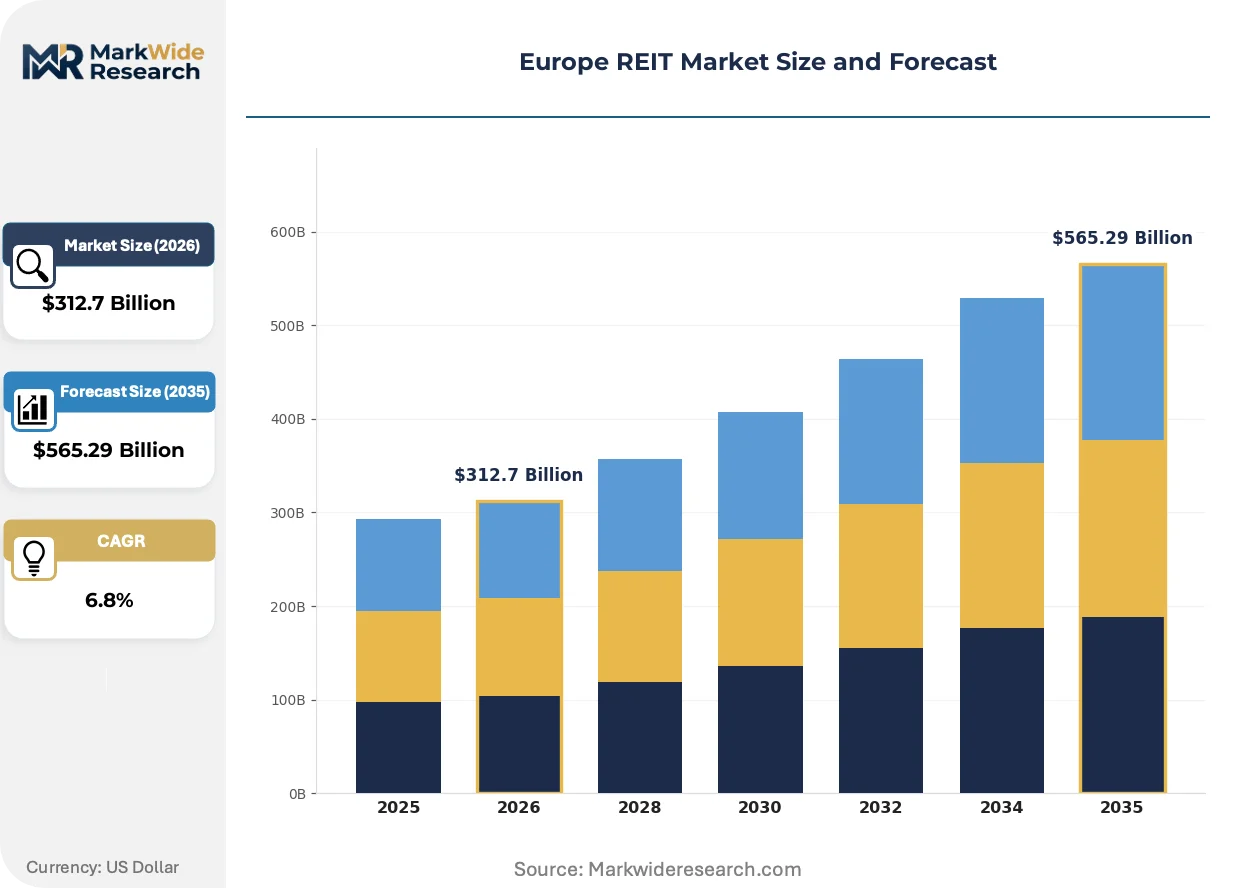
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Hospitality Investment Strategy: Core, Value-Add, Opportunistic, Distressed Distribution Channel: Public Market, Private Market, Direct Investment, Fund Investor Type: Institutional Investors, Retail Investors, Sovereign Wealth Funds, Family Offices |
| Companies Covered | Unibail-Rodamco-Westfield, Vonovia SE, Segro, Land Securities Group, Klepierre SA, Merlin Properties, Gecina SA, Covivio SA, LEG Immobilien, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe REIT Market Trends and Innovations
Property technology integration and sustainability certification are converging to redefine asset valuations and tenant retention mechanics across European REITs. This transformation is compressing legacy operating models while rewarding data-enabled portfolio management.
Distributed energy resource management systems are decentralizing power generation and consumption tracking across multi-tenant logistics parks. Warehouse operators in the Netherlands and Germany are deploying rooftop solar with battery arbitrage to shave peak demand charges. This architecture is decentralizing landlord-tenant energy relationships and enabling net-zero lease structures that command rent premiums.
The EU Green Deal's Renovation Wave strategy is mandating staged efficiency upgrades for commercial buildings above threshold sizes. French and German regulators are enforcing compliance through transaction disclosure requirements and mortgage risk weighting. Office REITs with concentrated Paris and Frankfurt exposure are accelerating capex programs to preempt obsolescence discounts.
Tenant sustainability reporting obligations are compressing lease renewal cycles and elevating service-level expectations. Corporate occupiers in Madrid and Milan are unbundling traditional gross leases to secure verified carbon data for Scope 3 disclosures. This behavioral shift is forcing property managers to invest in sub-metering infrastructure and third-party certification maintenance.
Europe REIT Market Segmentation
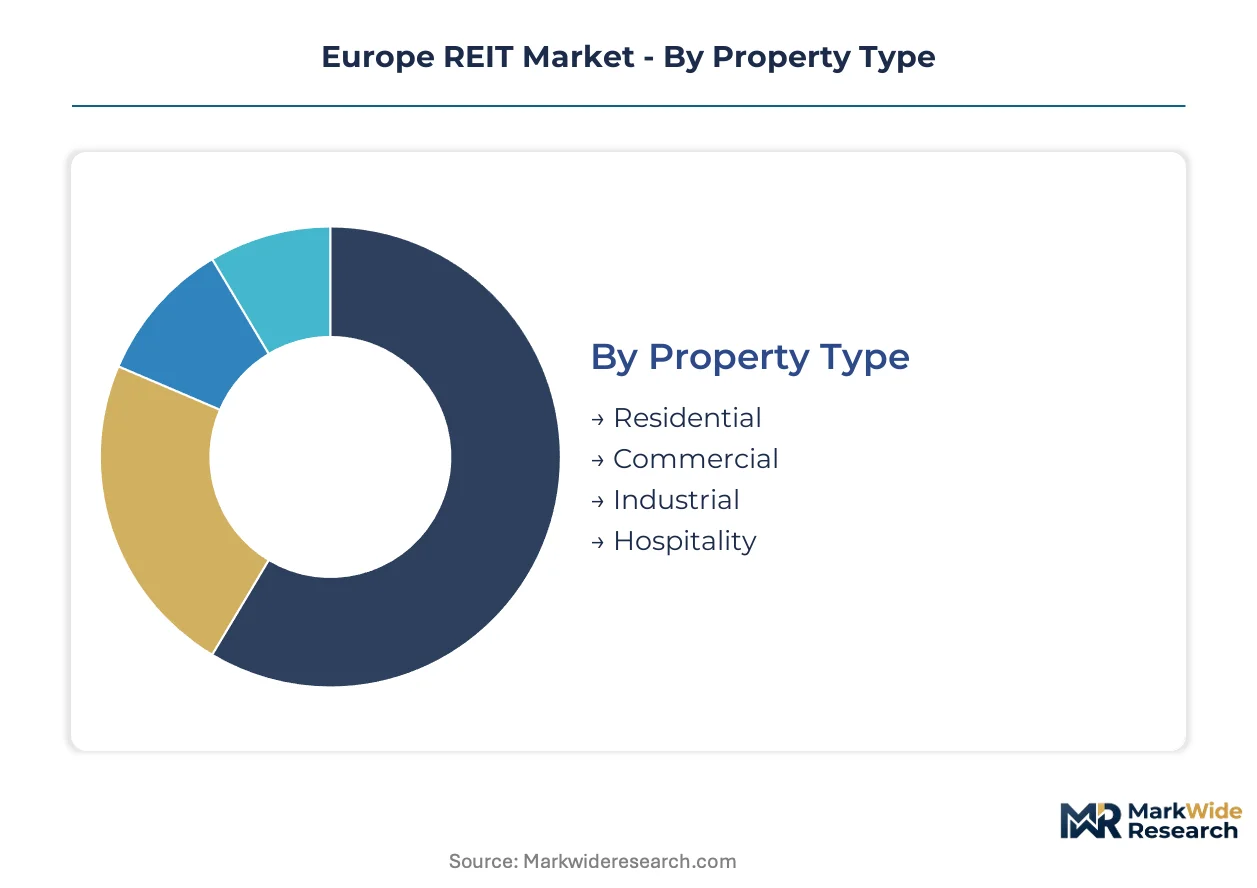
European REIT segmentation reveals how capital allocation priorities diverge across risk-return profiles and regulatory constraints. Property type classifications determine exposure to EU Green Deal compliance costs, while investment strategy tiers reflect varying tolerance for active repositioning versus stabilized yield capture.
Property Type:
Physical asset specifications define energy performance obligations and tenant covenant quality across European jurisdictions.
- Residential:Multi-family rental portfolios concentrate in German and Dutch urban centers with regulated rent frameworks. Housing supply deficits in Berlin, Munich, and Amsterdam sustain occupancy above structural equilibrium despite ECB rate transmission into mortgage markets.
- Industrial:Logistics warehouses with clear heights exceeding 12 meters and automation-ready floor loading specifications dominate development pipelines. Last-mile fulfillment demand in the Randstad and Rhine-Ruhr corridor absorbs speculative supply and compresses vacancy rates below historical averages.
- Commercial:Office assets face bifurcated valuations based on Energy Performance Certificate ratings. Paris and Frankfurt Class A stock commands rent premiums while secondary locations face obsolescence discounts under CSRD disclosure mandates.
- Hospitality:Serviced apartments and select-service hotels in Madrid and Lisbon recover occupancy through leisure travel normalization. Business travel dependency in London and Frankfurt submarkets lags revenue per available room restoration.
Residential leads on scale; Industrial leads on momentum.
Investment Strategy:
Risk-adjusted return targets segment capital deployment timelines and operational intensity requirements.
- Core:Stabilized assets with predictable cash flows attract pension fund and insurance capital seeking duration-matched yields. German residential and Dutch logistics dominate deployment given transparent lease structures and low vacancy volatility.
- Value-Add:Assets requiring active repositioning through renovation or lease-up capture IRR premiums. French office retrofit programs and Belgian logistics extension projects concentrate this capital tier.
- Opportunistic:Development exposure and transitional assets with 3-5 year hold periods target residual value creation. Polish logistics corridors and Spanish residential ground-up construction absorb this risk capital.
- Distressed:Non-performing loan acquisitions and receiver sales exploit dislocation from ECB rate reset and maturity wall stress. Italian and Portuguese commercial assets exhibit elevated distress velocity relative to Northern European markets.
Core dominates capital volume; Value-Add captures expansion velocity.
Distribution Channel:
Access mechanics determine liquidity terms, disclosure burdens, and minimum commitment thresholds for capital deployment.
- Public Market:Listed REITs on Euronext, Deutsche Börse, and LSE provide daily liquidity and CSRD-aligned transparency. Institutional allocations concentrate on large-cap vehicles with index inclusion and research coverage.
- Private Market:Unlisted vehicles and joint ventures offer structural flexibility for complex asset repositioning. Family offices and sovereign wealth funds favor this channel for direct governance rights and bespoke exit timing.
- Direct Investment:Single-asset or portfolio acquisitions bypass fund fee structures and enable operational control. German residential and French logistics attract this capital for scale deployment without manager selection risk.
- Fund:Commingled vehicles aggregate institutional capital for diversified sector or geographic exposure. Open-ended core funds and closed-ended value-add structures segment liquidity preferences and return horizons.
Public Market leads on accessibility; Private Market leads on structural flexibility.
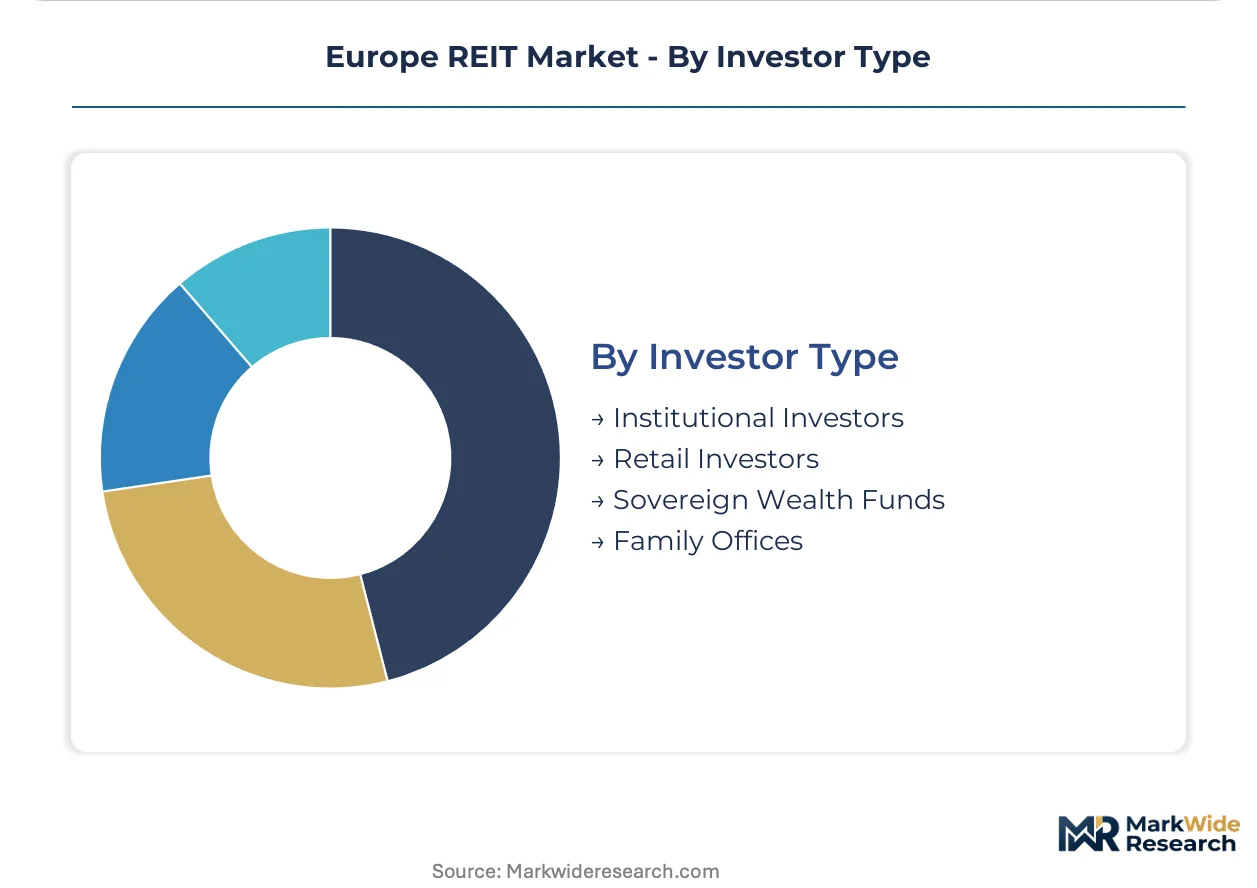
Investor Type:
Capital source characteristics dictate mandate constraints, ESG integration depth, and holding period preferences.
- Institutional Investors:Pension funds and insurance companies prioritize yield stability and inflation linkage. German and Dutch pension capital dominates residential and logistics allocations given liability-matching requirements.
- Retail Investors:Individual allocations through listed REITs and real estate crowdfunding platforms seek dividend income and sector diversification. French and Italian tax-advantaged savings vehicles channel retail flows into regulated REIT structures.
- Sovereign Wealth Funds:Long-dated capital with strategic real estate mandates targets trophy assets and platform acquisitions. Norwegian and Gulf-based funds concentrate Paris and London commercial exposure for currency and geopolitical diversification.
- Family Offices:Flexible capital with multi-generational horizons exploits illiquidity premiums and direct operational involvement. German and Swiss family offices concentrate value-add residential and logistics development in Central European growth corridors.
Institutional Investors anchor capital depth; Family Offices drive opportunistic velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional asset managers and development specialists concentrate in German and Dutch urban corridors, with cross-border capital flows reshaping portfolio composition from Paris logistics hubs to Polish manufacturing zones.
Germany
Regulated residential markets in Berlin and Munich sustain occupancy premiums above Eurozone averages. The Mietendeckel successor framework and federal building energy codes force accelerated capex into efficiency retrofits. Vonovia SE and LEG Immobilien anchor scale positions in Rhine-Ruhr and southern metropolitan clusters.
France
Parisian office demand bifurcates around Energy Performance Certificate ratings, with Class A stock commanding rent spreads over secondary locations. The EU Green Deal's Renovation Wave mandates disclosure through CSRD-aligned transaction protocols. Unibail-Rodamco-Westfield and Gecina SA concentrate flagship exposure in Île-de-France and Lyon corridors.
United Kingdom
Logistics absorption in the Midlands and Southeast outpaces speculative development timelines. Land Securities Group and Segro dominate last-mile fulfillment positioning around London orbital routes. The UK's divergence from EU building regulations creates compliance complexity for cross-border portfolio managers.
Netherlands
Randstad warehouse vacancy rates compress below structural equilibrium as e-commerce fulfillment density intensifies. National building codes ahead of EU minimums accelerate obsolescence risk in 1990s industrial stock. Institutional capital from Dutch pension funds concentrates in logistics joint ventures with German operators.
Poland
Manufacturing reshoring drives warehouse absorption between Warsaw and Łódź at yield premiums to Western European markets. EU cohesion fund infrastructure investment improves cross-border fulfillment connectivity. Local development partnerships with German and Austrian capital sources scale speculative pipeline delivery.
Europe REIT Market Competitive Landscape
Top-tier vendors anchor the large-cap listed tier, while mid-cap specialists and national champions occupy differentiated positions. The European REIT structure concentrates around three strategic archetypes: pan-European diversified platforms with flagship asset concentration, national residential specialists exploiting regulated rent frameworks, and logistics pure-plays capturing e-commerce fulfillment demand. Competitive moves center on portfolio decarbonization capex programs and selective disposals of stranded secondary assets.
Within the diversified platform tier, Unibail-Rodamco-Westfield and Klepierre SA represent archetypal retail-recovery positioning with concentrated Paris, London, and Madrid exposure. Vonovia SE occupies a scale-driven position in the regulated residential segment. These entities exemplify how national regulatory frameworks and EU Green Deal compliance timelines reshape capital allocation priorities across the competitive set.
| Leading Market Players |
|---|
| Unibail-Rodamco-Westfield |
| Vonovia SE |
| Segro |
| Land Securities Group |
| Klepierre SA |
| Merlin Properties |
| Gecina SA |
| Covivio SA |
| LEG Immobilien |
| Others |
Pricing and Supply Chain Analysis
Smart meter and battery storage convergence across Nordic residential portfolios is compressing landlord-tenant energy relationships while simultaneously concentrating procurement leverage among specialized technology integrators. This operational shift forces REITs to unbundle traditional gross lease structures and absorb upfront IoT infrastructure costs that reshape both operating margins and supplier dependency patterns.
Pricing Analysis
The bundled-vs-unbundled service split in European REITs stratifies around energy performance disclosure obligations and ancillary revenue capture. Pricing separates premium-certified assets with verified carbon data from standard-regulated residential and economy-secondary locations facing obsolescence discounts. Cost compression in Class C and D office tiers is intensifying because CSRD-aligned transaction protocols trap capital in depreciating positions. Institutional pension capital shows least price sensitivity for core German residential, while retail investors through crowdfunding platforms exhibit highest sensitivity to fee load and dividend yield.
Supply Chain Analysis
Specialized contractor capacity for deep energy renovation remains scarce in Belgian and Dutch construction markets, forcing REITs to extend project timelines and absorb wage inflation. Supply concentrates in Germany for building automation systems, Poland for steel and concrete inputs, and the Netherlands for smart grid infrastructure. Raw material dependencies center on steel rebar, low-carbon concrete formulations, and semiconductor components for IoT metering. Single-source vulnerability runs through specialized façade contractors certified for heritage building retrofits. Distribution runs through national construction consortiums with embedded maintenance service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European REITs constitute a late-cycle quality story as institutional capital rotation favors energy-efficient logistics and residential portfolios with defensive cash flow profiles. Demand is shifting toward premium-certified assets that command rent spreads and avoid stranded asset discounts under EU Green Deal compliance timelines.
For Market Incumbents: Cement scale advantages in regulated rent markets through accelerated capex into efficiency retrofits ahead of building energy code enforcement. Defend against margin compression from ECB rate transmission by locking long-dated fixed-rate debt and disposing secondary locations before EPC threshold devaluations deepen. Vertical integration into in-house energy management systems reduces ongoing service costs.
For New Entrants and Emerging Players: Dutch pension fund joint venture partners offer preferred access to logistics development pipelines in the Randstad corridor. White-space targets concentrate in Polish warehouse construction between Warsaw and Łódź and Spanish residential ground-up development in Madrid peripheral zones. Go-to-market positioning should emphasize EU Taxonomy-aligned green bond eligibility for certified construction pipelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among secondary-location office REITs with concentrated Paris and Frankfurt exposure facing near-term retrofit capex cliffs. Long-term viability favors platforms with demonstrated building-to-grid integration capabilities and established contractor relationships for deep renovation execution. The signal to watch is acceleration in mortgage risk weighting for non-compliant assets by national regulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Decarbonization Program | CSRD disclosure mandates force granular energy performance tracking across multi-tenant assets to preempt obsolescence discounts. |
| Green Bond Issuance | EU Taxonomy alignment creates preferential financing access for renovation and certified new construction pipelines. |
| Last-Mile Logistics Development | E-commerce fulfillment density in Dutch and German urban corridors absorbs speculative supply below structural equilibrium. |
| Building-to-Grid Integration | Smart meter and battery storage convergence enables ancillary revenue from demand-response participation in Nordic markets. |
| Stranded Asset Disposal | Energy Performance Certificate thresholds in France and Germany trap capital in depreciating secondary locations requiring active repositioning. |
Research Methodology
Direct dialogue with REIT portfolio managers, ESG reporting officers, institutional asset allocators, and construction procurement leads grounded qualitative assessment of capex prioritization and regulatory response patterns. Secondary validation drew from ECB financial stability reports, EU Green Deal implementation documents, national building energy code filings, and Euronext REIT disclosure filings. Bottom-up asset-level cash flow modeling and top-down institutional flow analysis were triangulated against disclosed fund allocation trends.
Segmentation outputs across property type, investment strategy, distribution channel, and investor type were calibrated against disclosed AUM flows and transaction velocity data across the analysis window. CAGRs were derived from historical absorption rates, development pipeline timelines, and regulatory compliance cost curves. Forecast inputs incorporated ECB interest rate transmission lags, EU cohesion fund infrastructure deployment schedules, and national rent regulation reform trajectories.
Revisions become necessary when ECB policy pivot timing, EU Green Deal carbon target acceleration, or contractor capacity constraints in Central European markets materialize differently than modeled. Material deviation in these triggers warrants pause and re-evaluation of acquisition capacity and hold period assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
United States Manufactured Homes Market
Real Estate
India Manufactured Homes Market
Real Estate
Philippines Facility Management Market
Real Estate
Japan Facility Management Market
Real Estate
India Residential Construction Market
Real Estate
Kuwait Facility Management Market
Real Estate
Saudi Arabia Office Real Estate Market
Real Estate
Residential Property Management Market
Real Estate
Malaysia Retail Market
Real Estate
Canada E-House Market
Real Estate
Global Home Services Market
Real Estate
Asia Pacific REIT Market
Real Estate
Property Management Software Market
Real Estate
US Home Service Market
Real Estate
Canada Commercial Real Estate Market
Real Estate
Latin America Facility Management Market