
 Malaysia Retail Market | 2026-2036
Malaysia Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Retail Market Insights
Grocery purchasing among urban professionals is decoupling from traditional hypermarket routines as same-day delivery apps and convenience networks capture weekly basket trips. 99 Speedmart leverages its dense neighborhood store footprint to dominate daily essentials replenishment across Peninsular Malaysia. AEON Co. (M) Bhd sustains its position through integrated mall-retail ecosystems that anchor suburban family spending. MR DIY competes aggressively on household goods price positioning, extending its store count into secondary towns.
Malaysia Retail encompasses the sale of finished consumer goods through physical and digital channels to end users, spanning perishable groceries, durable electronics, fashion apparel, and home maintenance products with inventory turnover cycles ranging from days to seasons. Its commercial purpose centers on matching manufacturer output with fragmented household demand across income levels and geographic densities. The online distribution channel is accelerating fastest among customer segments as logistics networks mature and smartphone penetration deepens. Budget price tiers occupy substantial volume share among families and young adults, while premium positioning captures disproportionate margin pools in electronics and apparel categories.
BIS standards govern product safety labeling for electronics and textiles sold through Malaysian retail channels, while the country's national pharmaceutical regulator oversees health and beauty product shelf compliance. MEE energy efficiency mandates are forcing retrofit investments in cooling and lighting systems across supermarket and hypermarket estates. Stakeholders must monitor how Bank Negara Malaysia's consumer credit regulations affect installment financing uptake for durable goods purchases.
Market Dynamics
Malaysia's dual carbon commitments under MEE are forcing rapid infrastructure reinvestment across retail estates, while smartphone penetration and logistics maturation are compressing purchase cycles from weekly hypermarket trips to same-day app-based replenishment.
Growth Catalysts
- MEE Energy Efficiency Mandates:Cooling and lighting retrofit requirements across supermarket estates are accelerating capital deployment into modernized retail infrastructure, lifting operational standards for compliant operators.
- Smartphone Penetration Deepening:Young adult consumers in Greater Kuala Lumpur are migrating weekly basket trips to convenience-driven digital channels, expanding addressable market for on-demand grocery platforms.
- Logistics Network Maturation:Same-day delivery capabilities now reach secondary towns beyond Peninsular Malaysia's urban corridor, unlocking geographic expansion for digital-first retailers.
Market Restraints
- Input Cost Volatility:Cooling system retrofits mandated by MEE energy standards impose capital intensity on hypermarket operators with thin margin structures, squeezing discretionary reinvestment capacity.
- Supply Concentration Risk:Electronics and textiles sourcing clusters concentrate in specific East Asian manufacturing geographies, exposing Malaysian retailers to freight rate fluctuations and customs processing delays.
- Regulatory Friction:BIS product safety labeling requirements for electronics and textiles create compliance timeline compression for imported inventory, extending stock-to-shelf cycles.
Strategic Opportunities
- Secondary Town Penetration:Household goods price-positioned formats are underpenetrated in East Malaysia and northern Peninsular states, offering first-mover expansion corridors for standardized store models.
- Channel Convergence:Integrated mall-retail ecosystems that anchor suburban family spending represent underexploited digital-physical fusion opportunities, blending experiential destination with fulfillment node functions.
- Bank Negara Consumer Credit Tailwinds:Evolving installment financing regulations for durable goods purchases could expand addressable demand for electronics and appliance categories among credit-constrained households.
Industry Challenges
- Certification Timeline Compression:BIS standards and national pharmaceutical regulator shelf compliance requirements for health and beauty products demand parallel documentation streams, straining quality assurance bandwidth.
- Legacy System Integration Friction:Cooling and lighting retrofits mandated under MEE efficiency frameworks must interface with decades-old building management infrastructure across aging hypermarket estates.
- Talent Scarcity in Energy Systems:Specialized technicians capable of executing MEE-compliant retrofit work are concentrated in Greater Kuala Lumpur, creating deployment bottlenecks for nationwide estate upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Retail Market |
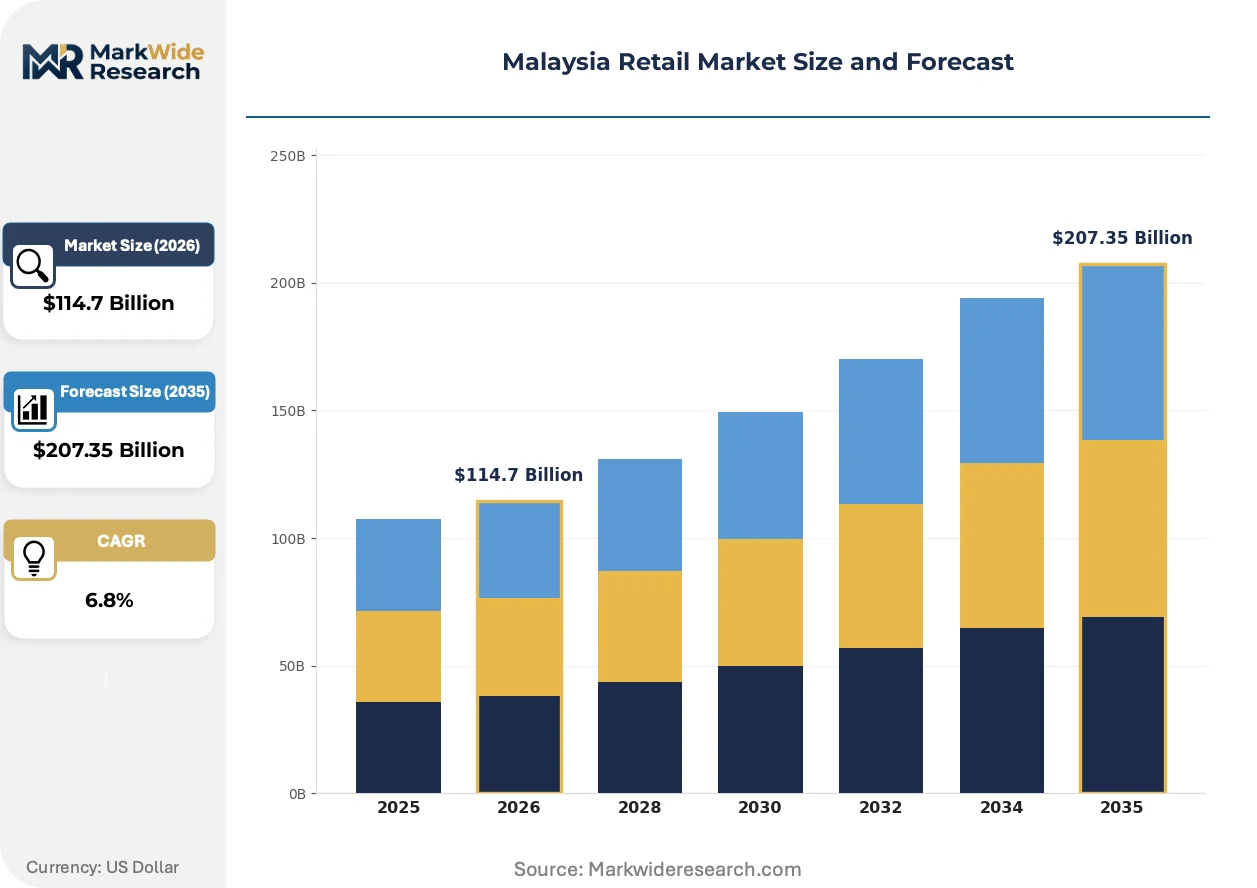
| Market Size in 2026 | $114.7 Billion |
| Market Size in 2035 | $207.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Groceries, Household Goods Price Tier: Premium, Mid-Range, Budget, Discount Distribution Channel: Online, Supermarkets, Convenience Stores, Hypermarkets Customer Type: Families, Young Adults, Seniors, Professionals |
| Companies Covered | 99 Speedmart, AEON Co. (M) Bhd, Lotus's Malaysia, GCH Retail (Giant), Mydin Mohamed Holdings, MR DIY, Padini Holdings Bhd, Senheng New Retail Berhad, Parkson Holdings Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Retail Market Trends and Innovations
Retail technology convergence and regulatory pressure on energy infrastructure are compressing operational timelines while reshaping how Malaysian households access daily essentials across physical and digital touchpoints.
Unified commerce platforms are unifying inventory visibility across neighborhood store networks and central warehouses, enabling real-time stock positioning. AEON Co. and 99 Speedmart are deploying these systems to compress replenishment cycles from days to hours. The technology is unifying previously siloed demand signals, allowing dynamic allocation that reduces stockouts in high-frequency grocery categories.
MEE dual carbon goals are mandating phased efficiency upgrades for retail cooling and lighting estates, with compliance deadlines cascading through supermarket and hypermarket portfolios. Operators face simultaneous pressure to maintain service levels during infrastructure retrofit windows. Electronics and appliance retailers are responding by bundling energy-efficient product lines with financing instruments that align with Bank Negara consumer credit frameworks.
Weekly basket fragmentation is displacing consolidated hypermarket trips as young professionals distribute purchases across convenience networks and same-day delivery apps. This behavioral shift compresses order values while increasing purchase frequency, altering inventory velocity calculations for perishable categories. The pattern concentrates visibly in Greater Kuala Lumpur's dense urban corridor where delivery radius economics favor rapid fulfillment models.
Malaysia Retail Market Segmentation
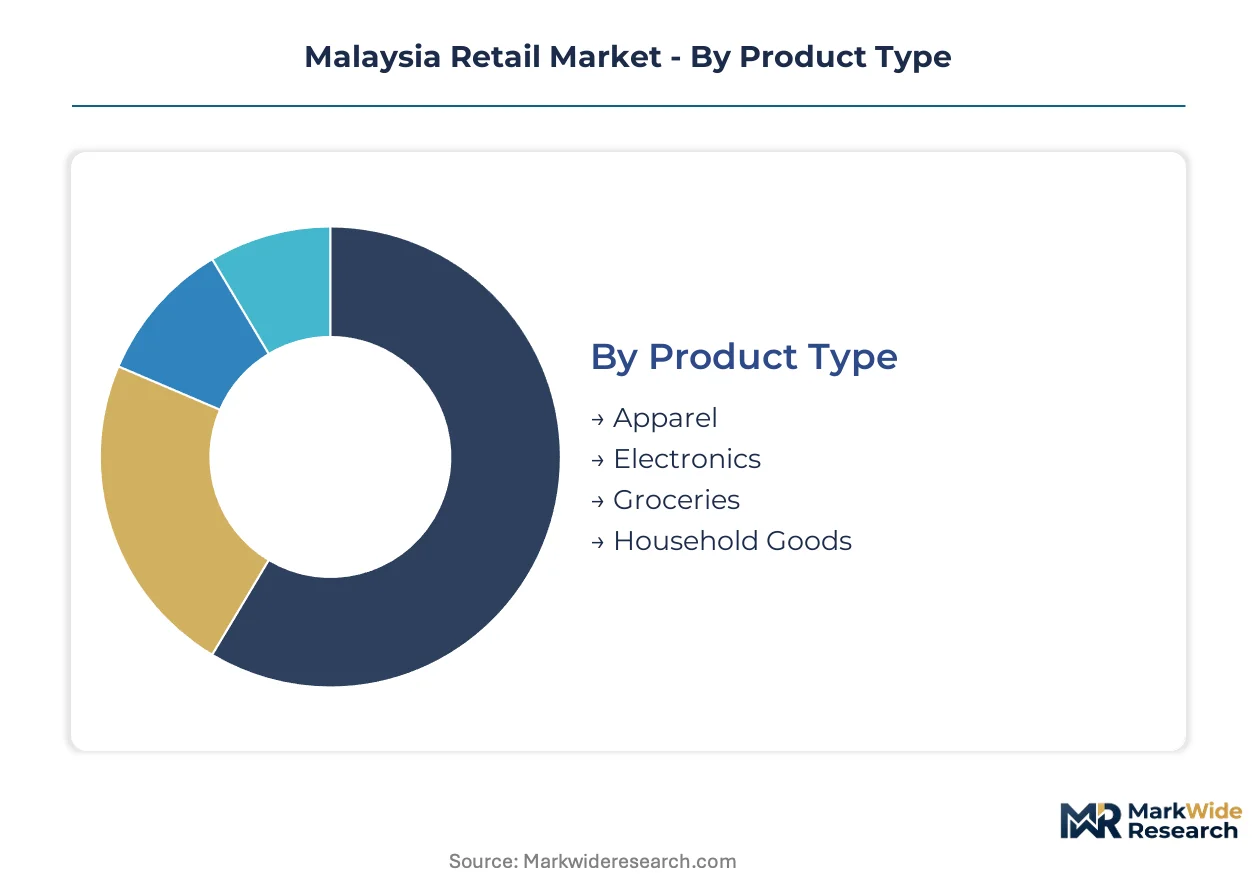
Malaysia's retail segmentation reflects divergent compliance burdens across product categories and channel formats. BIS labeling requirements, MEE energy mandates, and pharmaceutical shelf regulations create tiered certification complexity that shapes operational economics for each segment cluster.
Product Type:
Electronics and textiles face BIS safety certification timelines, while groceries navigate MEE cooling retrofit mandates and perishable handling protocols.
- Electronics:Smartphones, laptops, and home appliances require BIS product safety labeling and electromagnetic compatibility verification before retail placement. Demand concentrates in Greater Kuala Lumpur's urban corridor where young professionals prioritize same-day delivery for device upgrades, though customs processing delays at Port Klang create inventory cycle compression risks.
- Groceries:Fresh produce, packaged foods, and beverages dominate transaction frequency with inventory turnover measured in days. Families in suburban Selangor and Johor Bahru sustain hypermarket volumes, while MEE-mandated cooling retrofits strain estate infrastructure across aging supermarket portfolios.
- Apparel:Fashion and textile retail spans fast fashion through premium positioning, with BIS fiber content and safety labeling requirements governing import documentation. Peninsular Malaysia's mall networks anchor family spending on seasonal collections.
- Household Goods:Cleaning supplies, kitchenware, and home maintenance products compete on price positioning with lower regulatory entry barriers. Secondary towns in northern Peninsular states and East Malaysia show underpenetrated expansion corridors for standardized formats.
Groceries sits at the top of the volume ranking, with Electronics climbing the fastest.
Price Tier:
Margin structures and financing uptake vary sharply across price positioning, with Bank Negara consumer credit frameworks differentially enabling durable goods purchases.
- Premium:Luxury positioning in electronics and apparel captures disproportionate margin pools through brand equity and exclusive distribution. Professionals in Greater Kuala Lumpur drive demand for high-end smartphones and designer fashion, with installment financing penetration highest in this tier.
- Mid-Range:Balanced quality-price positioning targets suburban families seeking reliability without luxury markup. This tier absorbs volume compression as young adults migrate toward convenience-driven channels for routine replenishment.
- Budget:Price-focused household goods and basic apparel dominate family shopping baskets across secondary towns. MR DIY and comparable operators compete aggressively on standardized product lines with minimal service overhead.
- Discount:Aggressive promotional pricing and private-label concentration capture price-sensitive segments, particularly in grocery categories where hypermarket operators defend foot traffic against convenience network fragmentation.
Budget commands the widest household penetration, with Premium expanding most quickly through financing-enabled electronics uptake.
Distribution Channel:
Channel economics diverge based on fulfillment infrastructure requirements and last-mile density thresholds.
- Online:Digital-first retail leverages smartphone penetration and logistics maturation to compress delivery windows. Same-day capabilities now reach secondary towns beyond Peninsular Malaysia's urban corridor, unlocking geographic expansion for grocery and electronics platforms.
- Supermarkets:Full-format grocery retail with fresh produce and packaged goods anchors weekly family shopping routines. MEE cooling retrofit mandates impose capital intensity on estate infrastructure, squeezing reinvestment capacity for thin-margin operators.
- Convenience Stores:Neighborhood-focused formats with limited SKUs and extended hours capture daily replenishment trips. 99 Speedmart's dense footprint across Peninsular Malaysia demonstrates the volume potential of proximity-driven convenience.
- Hypermarkets:Large-format destinations combining groceries, general merchandise, and experiential elements face structural pressure as basket fragmentation displaces consolidated weekly trips. AEON Co.'s integrated mall-retail ecosystems defend suburban family spending through destination anchoring.
Supermarkets maintains volume leadership, with Online gaining share fastest through logistics network extension.
Customer Type:
Demographic segments exhibit divergent channel preferences and category concentration patterns across Malaysia's income distribution.
- Families:Multi-person households drive bulk purchasing in groceries and household goods, sustaining hypermarket and supermarket volumes. Suburban Selangor and Johor anchor this segment's spending concentration.
- Young Adults:Smartphone-native consumers prioritize convenience-driven digital channels for routine replenishment and discretionary purchases. Greater Kuala Lumpur's dense urban corridor concentrates this segment's demand for same-day delivery.
- Seniors:Established shoppers favor familiar physical formats with service assistance, particularly in grocery and health categories. Mall-retail ecosystems with accessibility features capture disproportionate loyalty.
- Professionals:Time-constrained households with dual incomes exhibit highest propensity for premium positioning and financing-enabled durable goods purchases. Electronics and appliance categories show strongest professional segment concentration.
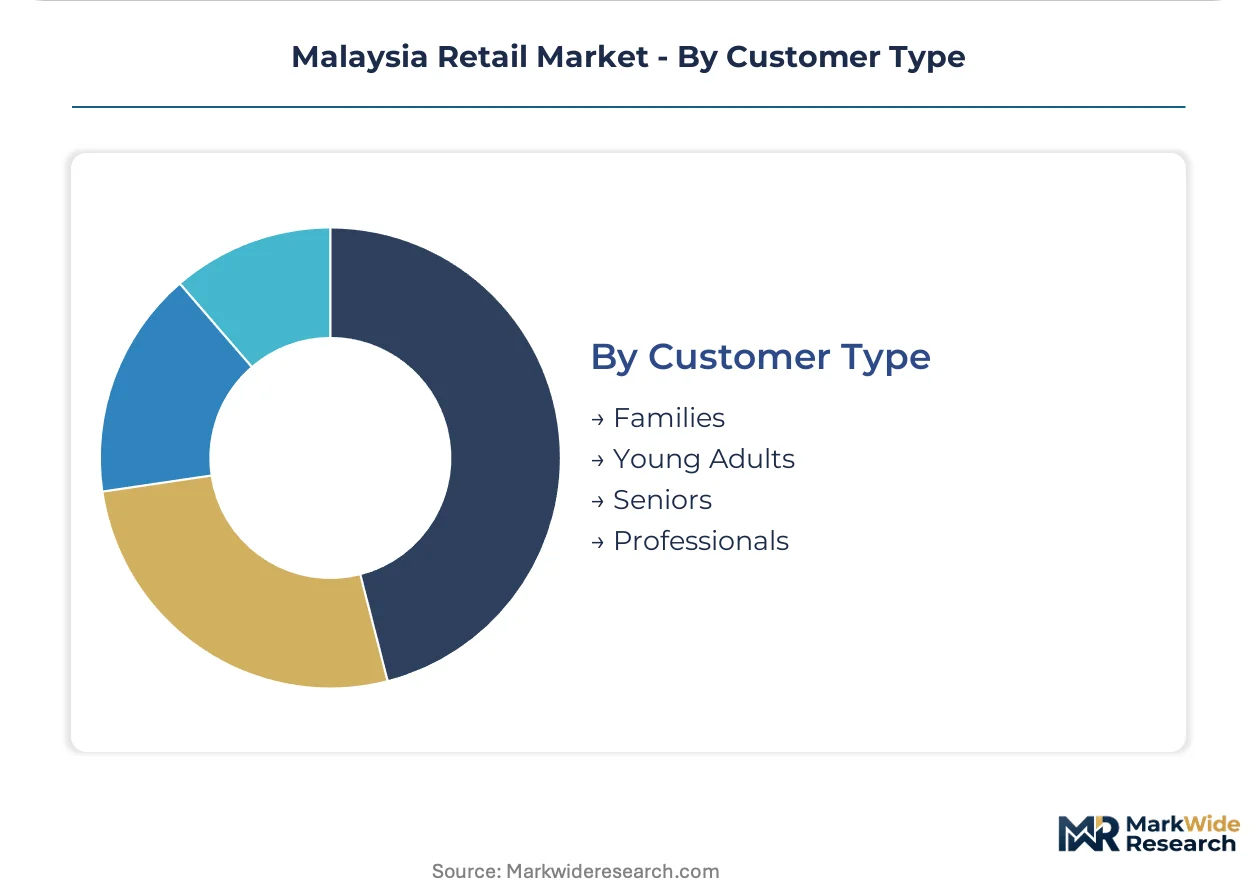
Families represents the largest transaction base, with Young Adults showing the steepest channel shift toward digital fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail capital deployment gravitates toward jurisdictions with streamlined compliance pathways and concentrated consumer density. Malaysia's sub-regional markets exhibit divergent infrastructure maturity and regulatory enforcement intensity that shapes operator economics across Peninsular and East Malaysian territories.
Greater Kuala Lumpur
Young professionals drive same-day delivery adoption for grocery and electronics categories. MEE energy efficiency mandates impose cooling retrofit deadlines on aging supermarket estates. The Klang Valley corridor anchors premium-tier consumption and logistics network densification for digital-first retailers.
Selangor
Suburban family households sustain hypermarket volumes through bulk purchasing routines. BIS product safety labeling requirements compress import documentation timelines for electronics retailers. Shah Alam and Petaling Jaya clusters concentrate mall-retail ecosystems defending against convenience network fragmentation.
Johor Bahru
Cross-border purchasing patterns from Singapore amplify demand for household goods and apparel categories. The national pharmaceutical regulator oversees health and beauty product shelf compliance for pharmacy-anchored retail formats. Iskandar Malaysia's development corridor attracts capital deployment into integrated retail infrastructure.
Penang
Electronics retail demand concentrates around device upgrade cycles among manufacturing sector employees. Bank Negara Malaysia's consumer credit frameworks enable installment financing penetration for durable goods purchases. George Town's heritage retail zones face modernization pressure against convenience network expansion.
East Malaysia
Sarawak and Sabah present underpenetrated expansion corridors for standardized household goods formats. Logistics network maturation extends same-day delivery capabilities to secondary towns previously excluded from digital retail access. Kuching and Kota Kinabalu anchor regional distribution nodes for grocery and general merchandise categories.
Malaysia Retail Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mall-retail ecosystems commanding disproportionate loyalty against fragmented convenience networks. The market structure tiers into three concentration levels: dominant national chains with hundred-plus store footprints, regional specialists with format-specific positioning, and emerging digital-first platforms capturing young adult migration. Strategic archetypes include proximity-driven neighborhood formats, destination-anchored suburban ecosystems, and price-positioned household goods specialists. Competitive moves center on geographic densification into secondary towns and channel convergence investments blending physical presence with fulfillment infrastructure.
Among neighborhood-focused operators, 99 Speedmart exemplifies the proximity-driven archetype through dense Peninsular Malaysia penetration. AEON Co. (M) Bhd occupies the integrated ecosystem position anchoring suburban family spending. MR DIY represents the price-positioned household goods specialist extending standardized formats into underserved territories.
| Leading Market Players |
|---|
| 99 Speedmart |
| AEON Co. (M) Bhd |
| Lotus's Malaysia |
| GCH Retail (Giant) |
| Mydin Mohamed Holdings |
| MR DIY |
| Padini Holdings Bhd |
| Senheng New Retail Berhad |
| Parkson Holdings Bhd |
| Others |
Pricing and Supply Chain Analysis
Young adult professionals in Greater Kuala Lumpur concentrate demand for same-day delivery services, compressing retailer margins through convenience premiums while hypermarket operators absorb MEE-mandated cooling retrofit costs into thin-margin grocery operations.
Pricing Analysis
Retailer markup structures vary sharply by channel format, with neighborhood convenience networks commanding proximity premiums against hypermarket volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates AEON Co.'s mall-anchored positioning from MR DIY's aggressive household goods discounting. Pricing pressure stems from MEE cooling retrofit capital requirements squeezing supermarket operators. Budget-tier families in secondary towns exhibit highest price sensitivity, while professionals financing electronics through Bank Negara frameworks show lowest elasticity.
Supply Chain Analysis
Direct-to-retail channels handle fresh produce and perishable grocery flows, while distributor-mediated networks manage electronics and textiles imports from China, Vietnam, and Bangladesh. BIS labeling requirements for electronics and textiles extend stock-to-shelf cycles through documentation bottlenecks. Supply chain risk concentrates in customs processing delays at Port Klang for East Asian manufacturing clusters. Distribution runs through centralized warehouse hubs in Shah Alam and Johor Bahru before last-mile fragmentation into convenience networks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia Retail offers margin expansion through MEE compliance differentiation, as retrofit-capable operators capture displaced volume from capital-constrained competitors unable to meet energy efficiency deadlines.
For Market Incumbents: Hedge against channel fragmentation by accelerating unified commerce platform deployment across neighborhood store networks. Lock in cooling retrofit contractor capacity before Greater Kuala Lumpur technician scarcity spreads nationwide. Defend suburban family spending against convenience network encroachment through experiential mall-retail ecosystem investments.
For New Entrants and Emerging Players: Secondary town households in East Malaysia represent the most penetrable buyer archetype for standardized household goods formats. Kuching and Kota Kinabalu distribution nodes enable geographic white-space capture with minimal incumbent density. Launch through price-positioned store models with direct sourcing from China and Vietnam manufacturing clusters.
For Investors and Strategic Acquirers: Regional grocery chains with hundred-plus store footprints and MEE-compliant estate infrastructure are the most active acquirer targets in this space. Long-term viability hinges on channel convergence capability blending physical proximity with fulfillment infrastructure. Watch Bank Negara consumer credit regulation evolution as the inflection signal for electronics financing penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| MEE Cooling Retrofit Completion | Compliance-capable operators capture volume from capital-constrained competitors unable to meet energy deadlines. |
| Unified Commerce Platform Deployment | Real-time inventory visibility compresses replenishment cycles from days to hours across neighborhood networks. |
| Secondary Town Geographic Expansion | Standardized store models penetrate underexposed East Malaysia and northern Peninsular corridors before incumbent response. |
| Channel Convergence Investment | Integrated mall-retail ecosystems blend experiential destination with fulfillment node functions against fragmentation. |
| Financing-Enabled Electronics Bundling | Bank Negara-aligned installment instruments expand addressable demand for durable goods among credit-constrained households. |
Research Methodology
Bottom-up household demand modeling reconciled against top-down retail estate tracking forms the analytical core of this study. Primary interviews with supermarket operations directors, convenience network franchise heads, mall-retail ecosystem managers, and MEE compliance officers combined with secondary validation against customs trade records, BIS certification databases, and Bank Negara consumer credit disclosures. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of transaction frequency and basket size patterns informed projection frameworks across product type, price tier, distribution channel, and customer segment dimensions. CAGRs derive from segment-specific growth trajectories modeled against smartphone penetration curves, logistics network extension timelines, and MEE compliance deadline cascades. Electronics financing uptake rates and cooling retrofit capital deployment schedules served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; online channel estimates carry tighter precision than emerging convenience network volumes given data availability disparities. Forecasts reflect documented assumptions around MEE enforcement intensity and logistics maturation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Australia Co-Working Office Spaces Market
Real Estate
Bahrain Co-Working Office Space Market
Real Estate
Turkey Commercial Real Estate Market
Real Estate
Myanmar Residential Real Estate Market
Real Estate
India Residential Construction Market
Real Estate
Saudi Arabia Office Real Estate Market
Real Estate
Romania Facility Management Market
Real Estate
South Korea Luxury Residential Real Estate Market
Real Estate
China Co Working Office Space Market
Real Estate
Singapore Real Estate Market
Real Estate
China Facility Management Market
Real Estate
Saudi Arabia Luxury Market
Real Estate
Saudi Arabia Soft Facility Management Market
Real Estate
Canada Real Estate Services Market
Real Estate
Global Shared Office Spaces Market
Real Estate
Asia-Pacific Self Storage Market