
 Residential Property Management Market | 2026-2036
Residential Property Management Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Property Management Market Insights
Modular service packaging is decoupling property management from traditional bundled offerings, letting landlords purchase tenant screening, maintenance coordination, and financial reporting as standalone modules. Greystar Real Estate Partners leverages its scale to anchor full-service contracts across major metropolitan portfolios. FirstService Residential competes through geographic density in coastal markets. Bozzuto Management Company differentiates via specialization in luxury multi-family lease management.
Residential property management encompasses the operational oversight of leased dwellings, combining tenant lifecycle administration, physical asset maintenance, and financial performance optimization through standardized workflows and digital tracking systems. Cloud-based platforms now dominate technology integration, while AI-powered analytics represents the fastest-growing capability layer as owners seek predictive maintenance and dynamic rent optimization. Single-family homes remain the largest property type segment by unit volume, though multi-family units command superior fee economics per door managed.
FHA underwriting standards, local habitability ordinances, and emerging municipal energy disclosure rules collectively shape compliance costs and platform requirements for managers operating across jurisdictions. The EPA's lead-safe renovation rules and state-level tenant protection statutes further constrain operational flexibility while creating demand for specialized compliance software. Stakeholders must monitor how fragmented regulatory layering affects technology procurement decisions and vendor consolidation timelines.
Market Dynamics
Municipal smart building mandates across Germany, Japan, and the United States are forcing landlords toward integrated technology platforms that unify energy monitoring, tenant access, and predictive maintenance into single operational layers.
Growth Catalysts
- Smart Building Codes:Municipal housing authorities in Germany, Japan, and the United States now require integrated energy and access systems, compelling portfolio upgrades.
- AI-Powered Analytics:Predictive maintenance algorithms and dynamic rent optimization tools are reducing vacancy periods and maintenance cost overruns.
- Sun Belt Migration:Population concentration in United States Sun Belt metropolitan corridors is expanding managed unit volumes faster than national averages.
Market Restraints
- Fragmented Regulatory Layering:EPA lead-safe renovation rules, state-level tenant protection statutes, and local habitability ordinances create compliance cost stacking across jurisdictions.
- Technology Integration Debt:Legacy property management systems require expensive middleware to connect with cloud-native platforms and IoT sensor networks.
- Skilled Technician Scarcity:Certified HVAC, electrical, and smart building system specialists concentrate in coastal metropolitan markets, leaving inland properties underserved.
Strategic Opportunities
- Modular Service Unbundling:Tenant screening, maintenance coordination, and financial reporting now sell as standalone modules, opening entry points for specialized vendors.
- Energy Disclosure Mandates:Emerging municipal energy disclosure rules in United States jurisdictions create demand for automated compliance documentation tools.
- Luxury Multi-Family Specialization:Premium lease management services for high-amenity properties command superior fee economics per door managed.
Industry Challenges
- Interoperability Friction:Cloud-based platforms struggle to integrate with legacy on-premise accounting and tenant tracking systems without custom API development.
- Compliance Timeline Compression:Overlapping FHA underwriting standards, state habitability deadlines, and municipal energy rules create conflicting certification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Property Management Market |
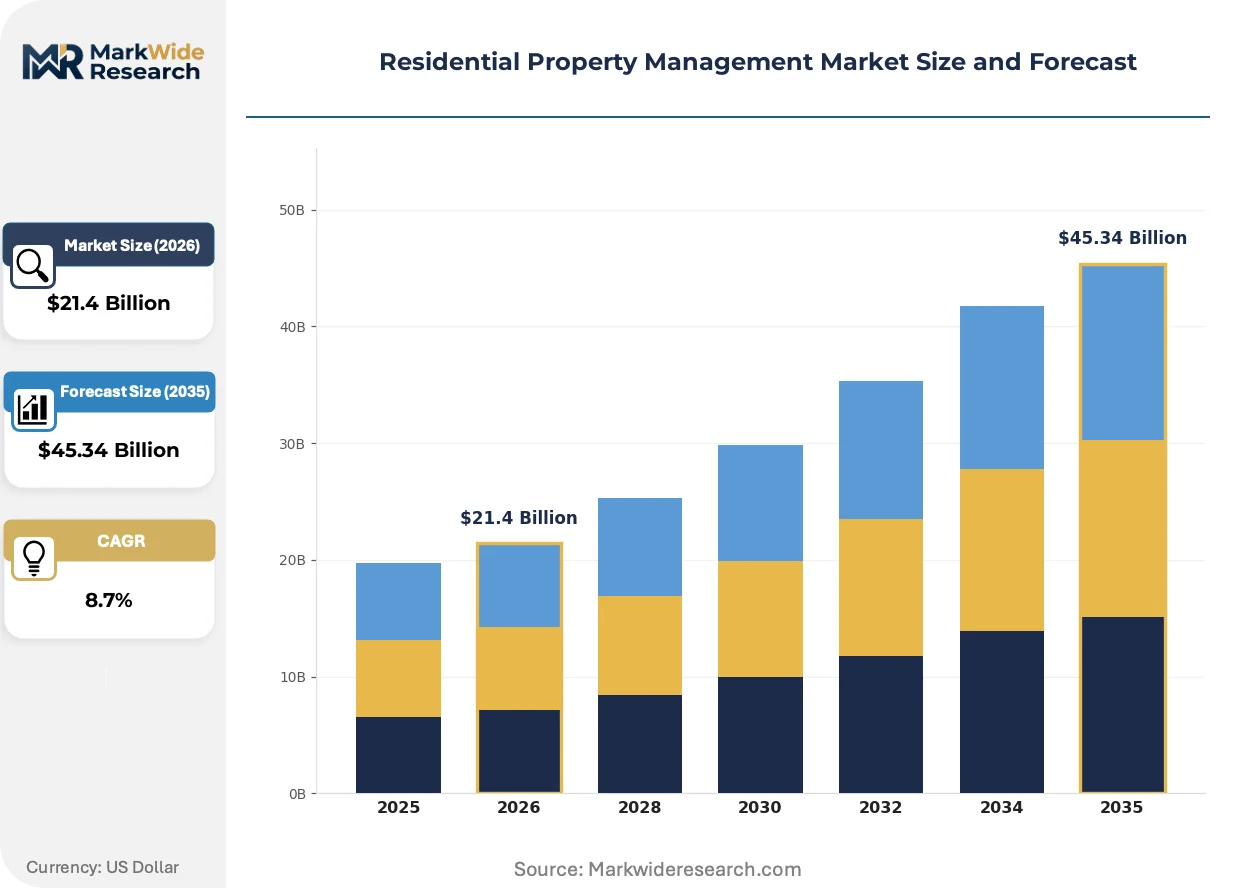
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $45.34 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Tenant Screening, Rent Collection, Maintenance Coordination, Lease Management, Financial Reporting Property Type: Single-Family Homes, Condominiums, Townhouses, Multi-Family Units, Cooperative Apartments Customer Type: Individual Landlords, Real Estate Investors, Housing Associations, Property Developers, Estate Agencies Technology Integration: Cloud-Based Platforms, Mobile Applications, IoT Automation, AI-Powered Analytics, CRM Systems |
| Companies Covered | Willow Bridge Property Company, Lincoln Property Company, Greystar Real Estate Partners, Bozzuto Management Company, BH Management Services, FirstService Residential, RPM Living, WinnResidential, Asset Living, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Property Management Market Trends and Innovations
Technology convergence is compressing the traditional separation between physical building operations and digital tenant experience management. Platform vendors now embed AI analytics directly into core workflows rather than offering them as bolt-on modules.
Machine learning algorithms for predictive maintenance and dynamic pricing are rewriting how multi-family operators allocate capital and price leases. Mid-sized portfolio owners in the United States Sun Belt are adopting these tools faster than institutional landlords, compressing the technology diffusion cycle from seven years to under three. The structural consequence is a shift from reactive maintenance budgeting to condition-based capital planning.
EPA lead-safe renovation rules and emerging municipal energy disclosure mandates are reshaping procurement priorities for property management software. Compliance documentation automation now ranks above tenant portal features in United States RFP evaluations. Multi-state operators are consolidating vendor relationships to reduce audit preparation overhead.
Tenant expectations for self-service digital interactions are displacing traditional phone-based leasing and maintenance request channels. Mobile-first platforms with integrated payment, access control, and community features are capturing preference share among renters under 35 in United States metropolitan markets. This behavioral shift is most visible in Texas and Florida submarkets where new construction competes heavily on technology amenities.
Residential Property Management Market Segmentation
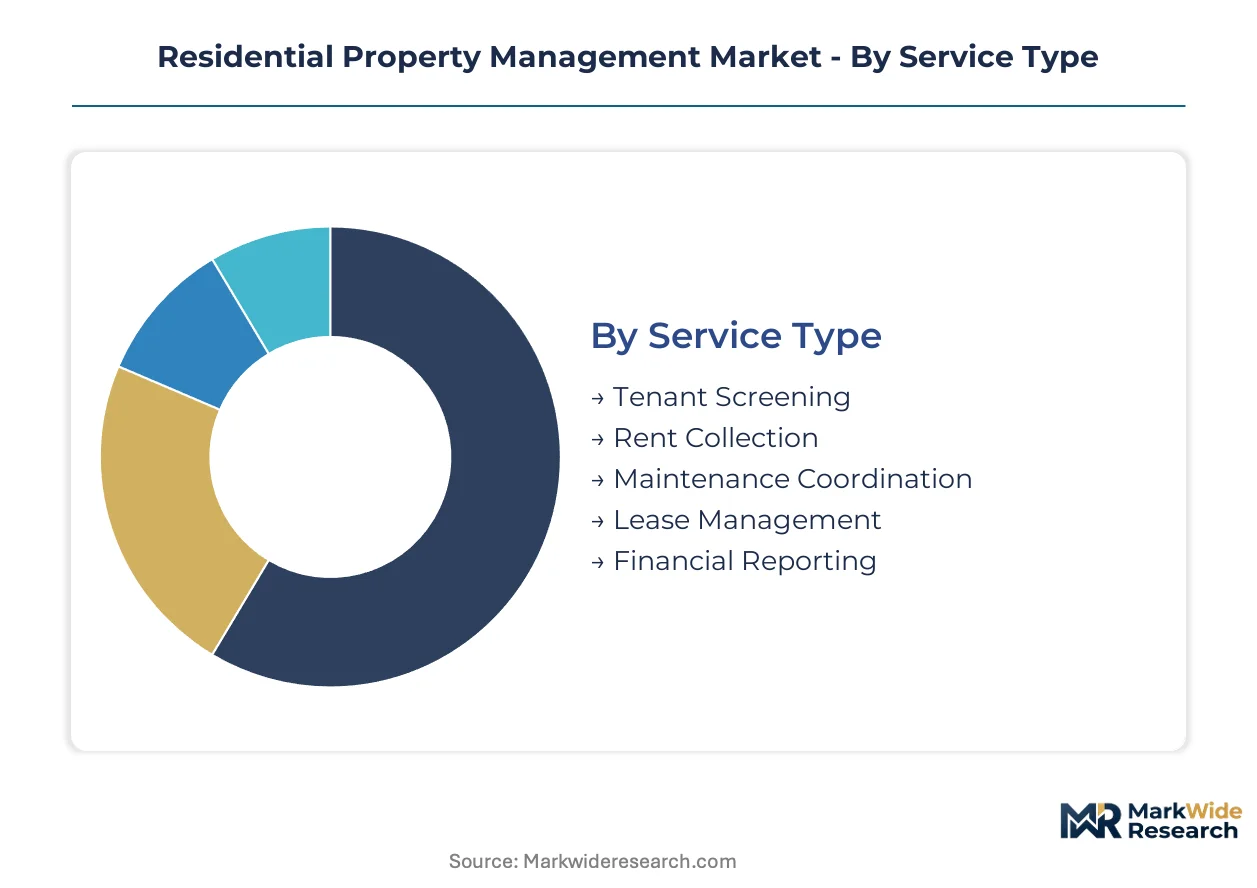
Service unbundling and technology convergence are fragmenting traditional property management bundles into discrete, purchasable components. Landlords now mix modular offerings across categories, forcing vendors to compete on specialized capability rather than comprehensive coverage alone.
Service Type:
Standardized workflows anchor the low-customization end of this spectrum, while bespoke financial reporting and tenant screening sit at the high-customization extreme.
- Tenant Screening:Automated background checks, credit verification, and eviction history analysis now integrate with third-party data providers. Demand concentrates among individual landlords in United States Sun Belt markets where rapid portfolio expansion outpaces in-house verification capacity.
- Maintenance Coordination:Work order dispatch, vendor scheduling, and condition-based capital planning form the operational core. Multi-family operators in Germany and Japan leverage predictive algorithms to compress response times under municipal smart building mandates.
- Rent Collection:Digital payment processing with automated late-fee assessment and ledger reconciliation.
- Lease Management:Document generation, renewal tracking, and compliance deadline monitoring across fragmented regulatory jurisdictions.
- Financial Reporting:Customizable dashboards for NOI tracking, tax preparation, and investor distributions.
Leading the category by volume: Maintenance Coordination. Growing fastest: Tenant Screening.
Property Type:
Fee economics per door vary sharply across this dimension, with density-driven multi-family assets commanding premium margins over dispersed single-family portfolios.
- Multi-Family Units:Apartment buildings and mixed-use developments with centralized management infrastructure. Greystar and Bozzuto anchor full-service contracts here, exploiting scale economies in United States metropolitan corridors where amenity competition drives technology investment.
- Single-Family Homes:Detached residential properties requiring dispersed maintenance networks and localized vendor relationships. Real estate investors in Texas and Florida submarkets are consolidating previously fragmented single-family rentals into institutionally managed portfolios.
- Condominiums:Owner-occupied units with shared common elements governed by association boards.
- Townhouses:Attached single-family structures with hybrid maintenance responsibility splits.
- Cooperative Apartments:Share-based ownership structures with proprietary lease arrangements and board-controlled subletting policies.
Highest fee per door: Multi-Family Units. Steepest expansion trajectory: Single-Family Homes.
Customer Type:
Procurement sophistication separates institutional investors with dedicated asset management teams from individual landlords purchasing ad-hoc services.
- Real Estate Investors:Institutional and private equity-backed entities operating scaled portfolios across multiple jurisdictions. FirstService Residential targets this segment through geographic density in coastal United States markets, embedding compliance automation into core contracts.
- Individual Landlords:Small-scale owners managing fewer than fifty units, often without dedicated staff. Modular service unbundling has opened this segment to specialized vendors offering standalone tenant screening or maintenance coordination.
- Housing Associations:Non-profit or limited-profit entities managing affordable and social housing stock.
- Property Developers:Entities requiring transitional management from construction completion to stabilized occupancy.
- Estate Agencies:Brokerage firms extending into property management as ancillary revenue streams.
Deepest technology penetration: Real Estate Investors. Fastest vendor consolidation: Individual Landlords.
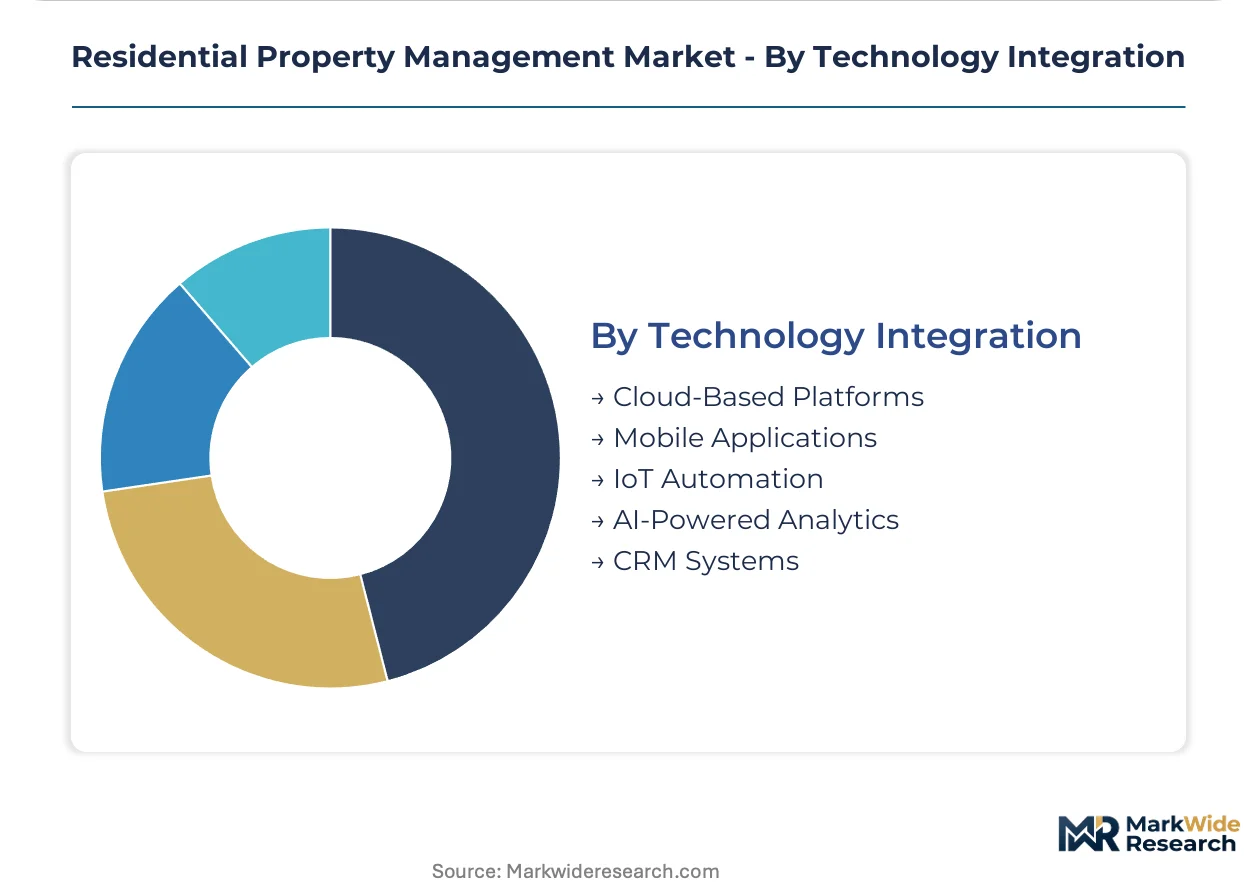
Technology Integration:
Legacy system replacement versus cloud-native adoption defines the migration timeline across customer tiers.
- AI-Powered Analytics:Machine learning algorithms for predictive maintenance, dynamic rent optimization, and vacancy forecasting. Mid-sized portfolio owners in United States Sun Belt markets are compressing adoption cycles from seven years to under three, displacing reactive budgeting with condition-based capital planning.
- Cloud-Based Platforms:Centralized data architecture enabling remote access, multi-user collaboration, and API-based third-party integrations. Municipal smart building codes in Germany, Japan, and the United States are compelling upgrades from on-premise legacy systems.
- Mobile Applications:Tenant-facing interfaces for rent payment, maintenance requests, and community engagement.
- IoT Automation:Sensor networks for energy monitoring, access control, and environmental quality tracking.
- CRM Systems:Prospect nurturing, leasing pipeline management, and resident lifecycle communication tools.
Widest deployment: Cloud-Based Platforms. Gaining share fastest: AI-Powered Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and Qualified Opportunity Funds are concentrating institutional capital in designated low-income census tracts across United States metropolitan corridors, accelerating portfolio aggregation in Sun Belt markets where municipal smart building codes intersect with favorable tax treatment.
United States
Sun Belt metropolitan corridors from Phoenix to Miami are absorbing the fastest portfolio expansion as multi-family operators exploit scale economies in high-migration destinations. EPA lead-safe renovation rules and emerging municipal energy disclosure mandates in California and New York are reshaping software procurement priorities toward compliance automation. Texas and Florida submarkets compete aggressively on technology amenities, with Austin and Miami emerging as testbeds for AI-powered rent optimization.
Germany
Municipal housing authorities in Berlin and Hamburg enforce integrated energy and access system mandates that compel landlords toward unified technology platforms. The country's national building energy regulator enforces stringent efficiency disclosure requirements under the EU Green Deal implementation framework. Frankfurt and Munich concentrate premium multi-family development where predictive maintenance algorithms compress response times under regulatory pressure.
Japan
METI smart building guidelines drive convergence of energy monitoring, tenant access, and IoT sensor networks in Tokyo and Osaka metropolitan portfolios. The Ministry of Land, Infrastructure, Transport and Tourism mandates digital documentation for building maintenance histories, creating demand for cloud-native compliance platforms. Yokohama and Nagoya submarkets lead adoption of condition-based capital planning tools among mid-sized portfolio owners.
United Kingdom
London's concentration of build-to-rent institutional capital anchors demand for full-service management contracts with embedded AI analytics. The UK's national housing regulator enforces escalating energy performance certificate standards that compress upgrade timelines for aging stock. Manchester and Birmingham emerge as secondary hubs where modular service unbundling opens entry points for specialized tenant screening vendors.
Canada
Toronto and Vancouver multi-family markets absorb technology investment from cross-border institutional operators seeking geographic diversification. Health Canada's environmental quality guidelines intersect with provincial tenant protection statutes to create layered compliance requirements. Calgary and Montreal submarkets concentrate single-family rental aggregation as real estate investment trusts consolidate previously fragmented ownership.
Residential Property Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where scale-driven full-service contracts anchor the premium segment and modular unbundling opens entry points at the mid-market. The vendor base organizes around three strategic archetypes: geographic density specialists, luxury multi-family operators, and technology-forward platform vendors. Consolidation proceeds through portfolio acquisitions and strategic vendor partnerships rather than horizontal mergers, while vertical integration into maintenance subcontracting and smart building system installation accelerates among scaled operators.
Within the full-service contract tier, Greystar Real Estate Partners and FirstService Residential occupy positions reflecting divergent geographic strategies—Greystar anchoring scale in major metropolitan corridors, FirstService embedding density in coastal United States markets. Bozzuto Management Company exemplifies the luxury specialization archetype, commanding premium fee economics through high-amenity lease management expertise.
| Leading Market Players |
|---|
| Willow Bridge Property Company |
| Lincoln Property Company |
| Greystar Real Estate Partners |
| Bozzuto Management Company |
| BH Management Services |
| FirstService Residential |
| RPM Living |
| WinnResidential |
| Asset Living |
| Others |
Pricing and Supply Chain Analysis
Cloud-native platform migration simultaneously compresses legacy system maintenance costs and concentrates vendor relationships among scaled operators capable of absorbing upfront integration expenses. This technology shift rewards portfolio aggregators in United States Sun Belt markets with pricing leverage over fragmented individual landlords.
Pricing Analysis
Short lead-time deployments command premium pricing from multi-family operators facing municipal smart building compliance deadlines in Germany and Japan. The dominant structure is a three-tier pricing structure across premium, standard, and economy levels differentiated by AI analytics depth and compliance automation scope. Cost compression in the economy tier is intensifying because mid-sized portfolio owners are bypassing full-service bundles for modular alternatives. Individual landlords in Texas and Florida submarkets exhibit highest price sensitivity, while institutional investors in coastal United States metropolitan corridors prioritize capability over cost.
Supply Chain Analysis
Direct-to-property-manager channels handle hyperscale buyer demand from Greystar and FirstService Residential, while value-added resellers serve fragmented individual landlords. Supply concentrates in the United States, Germany, and Japan where municipal smart building mandates drive platform development. The supply chain draws from cloud infrastructure providers, IoT sensor manufacturers, and compliance documentation specialists. Single-source vulnerability exists around AI analytics engines trained on proprietary maintenance datasets. Distribution runs through SaaS marketplaces, direct enterprise sales teams, and regional property technology integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over maintenance subcontractor networks and smart building system installation capabilities determines margin capture. Players are pursuing backward integration into field service operations to reduce vendor management overhead.
For Market Incumbents: Deepen geographic density in United States coastal corridors to anchor full-service contracts against modular unbundling threats. Invest in captive maintenance technician networks to offset skilled labor scarcity in inland markets. Certification investment in EPA lead-safe renovation compliance automation creates switching costs against emerging platform vendors.
For New Entrants and Emerging Players: Launch via standalone tenant screening modules targeting individual landlords in Texas and Florida submarkets where rapid portfolio expansion outpaces verification capacity. White-space targets include energy disclosure compliance tools for California and New York jurisdictions and predictive maintenance algorithms for aging multi-family stock in United Kingdom secondary cities. Go-to-market through regional property technology integrators bypasses incumbent sales channel saturation.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized platform vendors given AI-powered analytics adoption acceleration among Sun Belt portfolio owners. Long-term viability hinges on compliance automation depth across fragmented regulatory jurisdictions. Acquisition target archetype: specialized vendors with municipal energy disclosure tool deployments. The inflection indicator to monitor is consolidation velocity among individual landlords purchasing modular services versus full-service contracts.
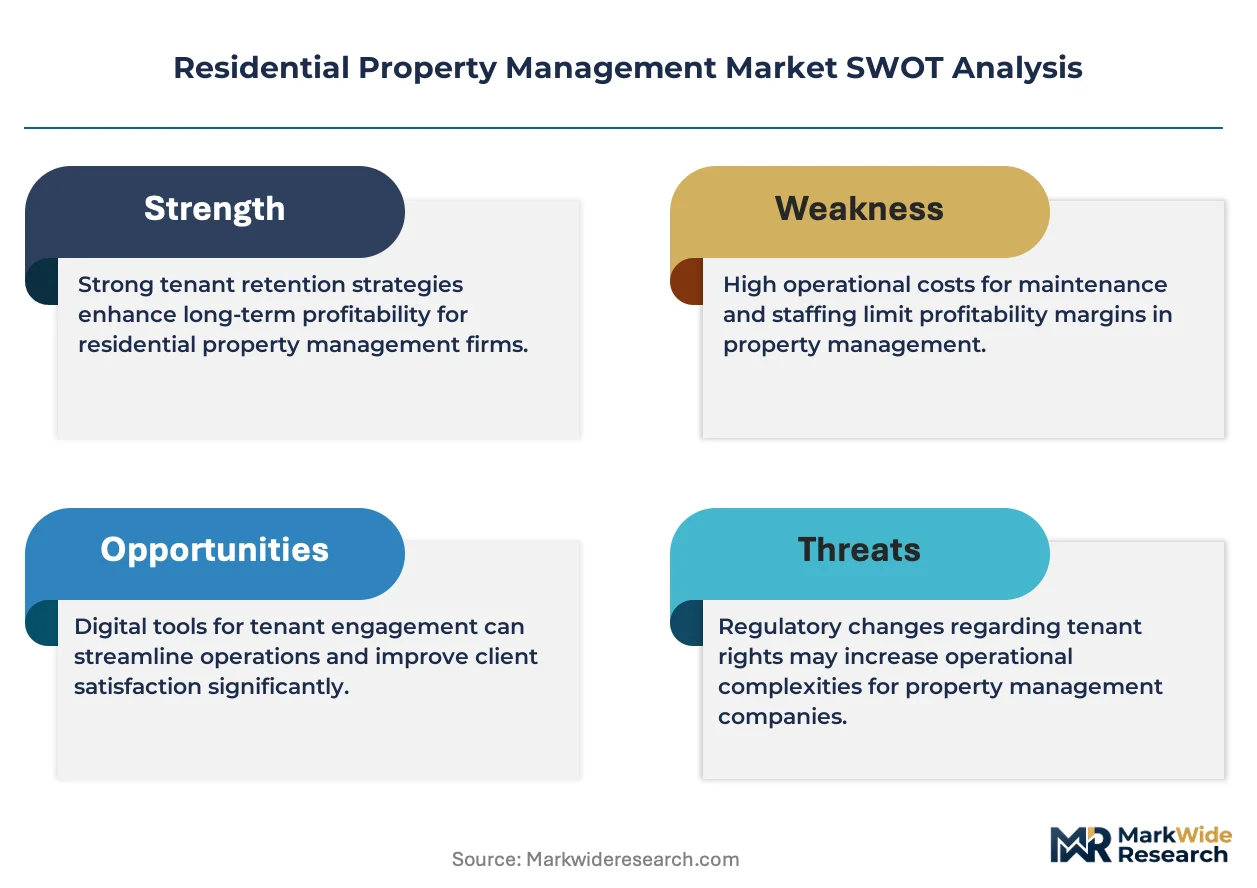
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies tenant screening, maintenance coordination, and financial reporting into single operational layers for multi-family operators. |
| Acquisition of Specialist Firm | Captures predictive maintenance algorithm capabilities trained on proprietary building sensor datasets in Germany and Japan. |
| Strategic Partnership | Secures certified HVAC and electrical technician networks in underserved inland United States markets. |
| Geographic Expansion | Establishes density in United Kingdom build-to-rent corridors where institutional capital concentrates management contract demand. |
| Product Launch | Introduces automated compliance documentation tools addressing EPA lead-safe renovation and municipal energy disclosure mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this residential property management market analysis. Primary interviews with property management executives, municipal housing authority officials, smart building technology vendors, and institutional real estate investors combined with secondary validation from EPA enforcement databases, state-level tenant protection statute registries, and municipal energy disclosure rule filings. Bottom-up unit economics modeling and top-down market sizing triangulation cross-checked segment-level revenue estimates.
Data-stream reconciliation across service type, property type, customer type, and technology integration dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from historical adoption curve analysis and technology diffusion benchmarks specific to AI-powered analytics and cloud-native platform migration. Industry-specific inputs included smart building code implementation timelines in Germany, Japan, and the United States and Sun Belt metropolitan migration patterns affecting managed unit volumes.
The model assumes a particular technology adoption path; alternative pathways for legacy system replacement versus cloud-native greenfield deployment would alter the outlook. Forecasts reflect assumptions about regulatory layering intensity and skilled technician labor market tightness. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
US Property Management Software Market
Property Management
Qatar Flexible Office Space Market
Property Management
Property Management Service Market
Property Management
Real Estate Management Software Market
Property Management
Space Planning and Space Management Solutions Market
Property Management
United States Property Management Market
Property Management
Hungary Warehousing Sector Market
Property Management
Spain Warehousing Market
Property Management
South Korea Self-Storage Market
Property Management
Property Management Software Market
Property Management
Real Estate (Property) Management Market
Property Management
Europe Self Storage Market