
 United Kingdom Food Spreads Market | 2026-2036
United Kingdom Food Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Food Spreads Market Analytics
Single-source to multi-source ingredient procurement is repositioning how British manufacturers manage oilseed and dairy inputs. Unilever Plc leverages its established supply chain infrastructure to secure consistent raw material flows across multiple origins. Premier Foods plc anchors its competitive stance through deep retail relationships and private-label manufacturing capabilities. Stute Foods Ltd specializes in reduced-sugar fruit spread formulations that align with health-conscious consumer segments.
Food spreads encompass semi-solid edible preparations formulated from fats, oils, sugars, fruits, nuts, or dairy derivatives, typically containing 60-80% lipid content in fat-based variants and 30-50% soluble solids in fruit-based products, manufactured through emulsification, homogenization, or vacuum-concentration processes for direct consumption on baked goods or as recipe ingredients. The nut butters category commands premium shelf positioning as protein-enriched alternatives displace conventional breakfast spreads in health-oriented households. Supermarkets dominate volume throughput while online retailers capture the fastest expansion in recurring subscription-based purchasing, though specialty shops retain margin concentration through artisanal and organic price tiers.
The Food Standards Agency enforces compositional standards and allergen labeling that directly constrain formulation flexibility and packaging claims across the category. DEFRA's agricultural policy frameworks and the UK's post-EU retained REACH chemicals regime govern pesticide residues in fruit inputs and additive permissibility. Stakeholders must monitor evolving trade agreement terms with EU member states that determine tariff exposure for imported nut and palm oil feedstocks.
Market Dynamics
DEFRA's sugar reduction mandates and the Food Standards Agency's compositional standards are forcing British manufacturers to reformulate legacy recipes while maintaining sensory profiles that retain retail shelf positioning.
Growth Catalysts
- Plant-based menu expansion:Foodservice operators in London and Manchester are integrating nut butters and dairy alternatives into breakfast and snacking applications, creating pull-through demand for industrial volumes.
- Front-of-pack labeling compliance:The UK's traffic-light labeling scheme rewards reformulated spreads with favorable nutritional scores, unlocking premium retail placement and health-conscious consumer segments.
- Urban corridor concentration:England's metropolitan retail networks generate disproportionate throughput velocity, concentrating marketing investment and distribution efficiency in London, Birmingham, and Manchester catchments.
Market Restraints
- Palm oil input volatility:Post-EU trade friction exposes British processors to tariff uncertainty on Southeast Asian palm oil feedstocks, compressing margin predictability in fat-based spread categories.
- Allergen labeling rigidity:The Food Standards Agency's strict allergen declaration requirements constrain line flexibility and accelerate packaging changeover costs for multi-SKU manufacturers.
- Fruit concentrate supply concentration:Domestic berry and stone fruit processing capacity clusters in Kent and Herefordshire, creating geographic single-point vulnerability for reduced-sugar jam formulations.
Strategic Opportunities
- Subscription channel penetration:Direct-to-consumer recurring delivery models bypass supermarket slotting fees and capture lifetime value from health-oriented households in Greater London and the Home Counties.
- Scottish and Welsh market underdevelopment:Regional retail networks outside England's core corridors exhibit lower private-label penetration, offering first-mover positioning for branded spread portfolios.
- Clean-label additive substitution:Natural emulsifier technologies derived from chickpea and fava bean proteins align with the UK's retained REACH regime on additive permissibility, opening reformulation partnerships with ingredient technology suppliers.
Industry Challenges
- Reformulation R&D timeline compression:The government's 2025 sugar reduction targets force accelerated sensory testing cycles that strain in-house product development teams and external flavor house partnerships.
- Legacy equipment retrofitting costs:Vacuum-concentration and homogenization lines engineered for high-solids formulations require capital-intensive modification to process reduced-sugar fruit matrices without burn-on or texture degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Food Spreads Market |
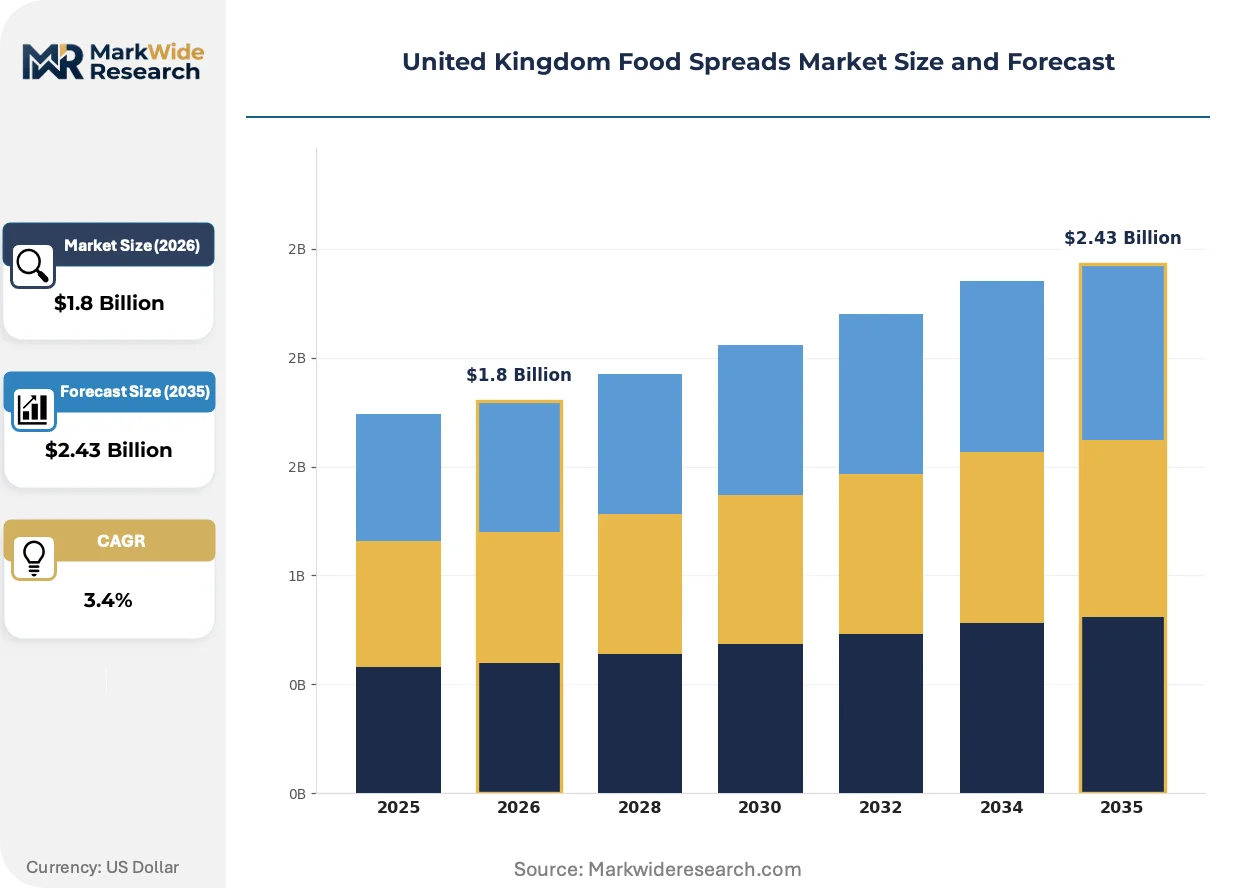
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Nut Butters, Fruit Spreads Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops Customer Type: Households, Foodservice, Retailers, Cafes Price Tier: Premium, Mid-range, Budget, Organic |
| Companies Covered | Unilever Plc, Ferrero International SA, The Hain Celestial Group, The J.M. Smucker Company, Upfield Holdings B.V., Premier Foods plc, Nestlé S.A., The Kraft Heinz Company, Stute Foods Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Food Spreads Market Evolving Landscape
Clean-label ingredient technologies and digital-first distribution models are restructuring how British consumers discover, evaluate, and replenish spread purchases across retail and foodservice channels.
High-pressure processing technology is consolidating shelf-stable nut butter production by eliminating thermal degradation of protein structures while extending ambient shelf life without synthetic preservatives. Artisanal manufacturers in Bristol and Brighton are adopting HPP systems to compete with multinational brands on distribution reach. This consolidation is compressing the traditional trade-off between clean-label positioning and national retail distribution coverage.
The UK's retained REACH chemicals regime and evolving Food Standards Agency guidance on novel ingredients are tightening additive approval pathways for texturizers and preservatives. Manufacturers must now submit expanded safety dossiers for enzyme-modified emulsifiers and natural flavor precursors. Small and mid-cap processors without dedicated regulatory affairs functions are outsourcing compliance to specialized consultancies, fragmenting competitive capability across the supplier base.
Recurring replenishment purchasing through subscription platforms is displacing impulse-driven supermarket selection for premium and specialty spread categories. Health-oriented households in London and Manchester are locking into 4-6 week delivery cycles for organic almond butters and reduced-sugar fruit preserves. This behavioral shift concentrates customer acquisition spend on digital channels and loyalty program infrastructure rather than in-store promotional mechanics.
United Kingdom Food Spreads Market Segmentation
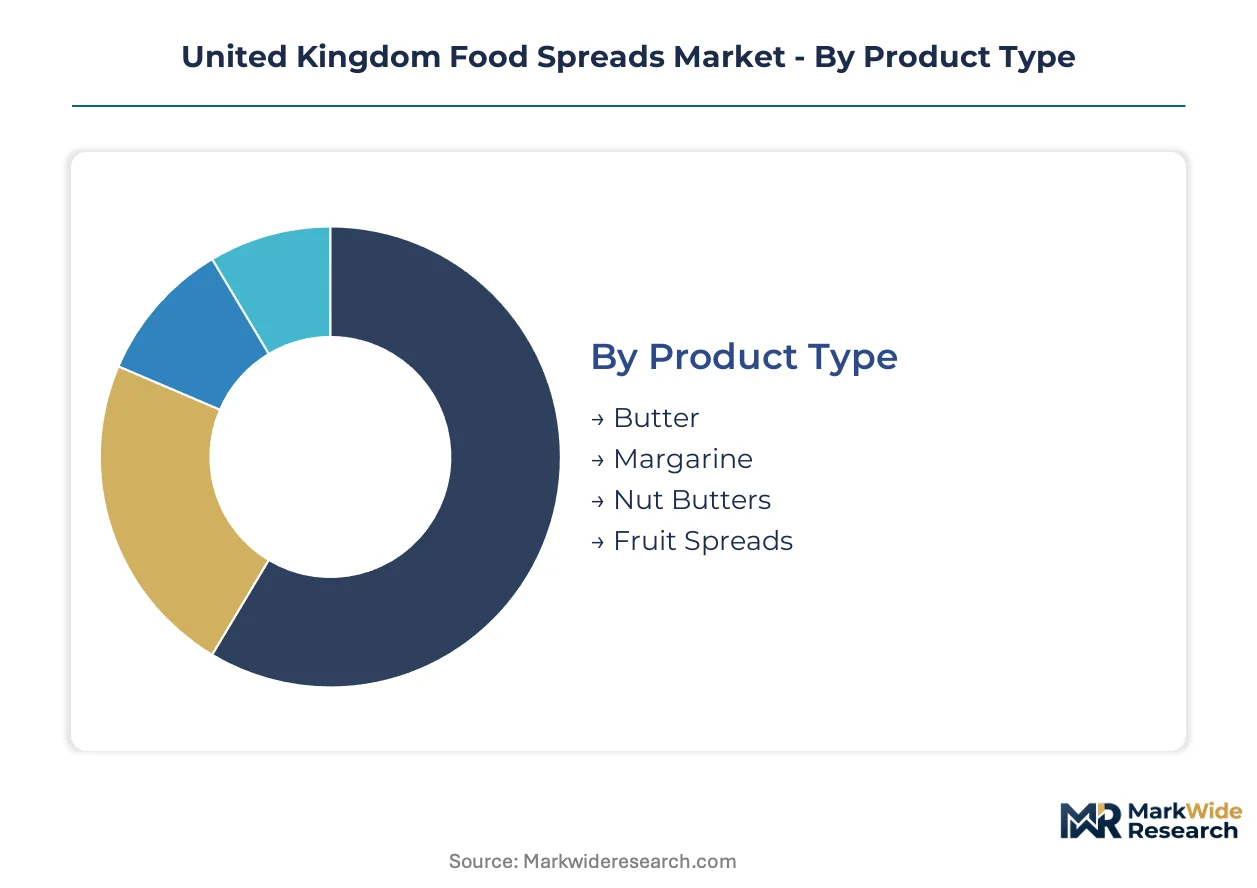
Segmentation reveals how formulation requirements, procurement patterns, and channel economics fragment the United Kingdom food spreads landscape. Manufacturers must align R&D investment and distribution strategy to the distinct technical and purchasing behaviors within each slice.
Product Type:
Upgrade cycles vary sharply across fat-based and fruit-based categories, with protein-enriched variants displacing legacy breakfast staples in health-oriented households.
- Butter:Traditional churned cream formulations with 80-82% milk fat content anchor baking applications and premium table spreads. English dairy processors in the West Country maintain volume leadership through established retail relationships, though plant-based alternatives erode share in London's metropolitan corridors.
- Margarine:Emulsified vegetable oil blends with 70-80% fat content deliver cost-advantaged spreads for price-sensitive segments and industrial baking. Reformulation pressures from DEFRA's reduction targets compress margin structures while demanding accelerated sensory testing cycles.
- Nut Butters:Ground seed and tree nut preparations with 25-30% protein content capture premium positioning in protein-forward diets.
- Fruit Spreads:Vacuum-concentrated fruit preparations with 30-50% soluble solids serve reduced-sugar positioning and clean-label demand.
Butter sits at the top of the volume ranking, with nut butters climbing the fastest.
Distribution Channel:
Channel cost structures and slotting fee regimes determine which spread categories achieve national penetration versus remaining regionally concentrated.
- Supermarkets:Multiples and discounters dominate throughput velocity, concentrating marketing spend on promotional mechanics and front-of-pack labeling compliance. Tesco, Sainsbury's, and Asda control shelf placement decisions that make or break branded spread launches.
- Convenience Stores:Impulse-driven purchasing in urban convenience networks favors single-serve and travel-size formats with higher unit margins.
- Online Retailers:Subscription-based replenishment models bypass traditional slotting fees and capture lifetime value from health-conscious households in Greater London.
- Specialty Shops:Artisanal and organic price tiers concentrate margin in independent retail networks across Bristol, Brighton, and Edinburgh.
Supermarkets command absolute volume leadership, while online retailers gain share fastest through recurring delivery adoption.
Customer Type:
Procurement sophistication and volume scale diverge sharply between institutional buyers and fragmented household purchasing.
- Households:Individual consumers drive flavor innovation and clean-label demand through direct purchasing decisions.
- Foodservice:Contract catering and restaurant chains in London and Manchester integrate plant-based spreads into breakfast and snacking applications, creating industrial volume pull-through.
- Retailers:Private-label manufacturers like Premier Foods plc anchor competitive positioning through deep supermarket relationships and co-manufacturing agreements.
- Cafes:Independent coffee shop networks in metropolitan corridors favor premium nut butters and artisanal fruit spreads for menu differentiation.
Households generate the broadest revenue base, with foodservice expanding most quickly through menu application diversification.
Price Tier:
Margin structures and ingredient input costs stratify across certification requirements and volume scale.
- Premium:High-fat butter and single-origin nut butters command shelf positioning through provenance marketing and sensory differentiation. Waitrose and Marks & Spencer anchor distribution for these tiers in affluent Home Counties catchments.
- Mid-range:Blended spreads and standard fruit preserves balance cost and quality for mainstream household penetration.
- Budget:Price-optimized margarine and high-sugar jams serve value-oriented segments through discounter channels.
- Organic:Certified organic spreads carry Soil Association accreditation and capture health-conscious premiums in specialty retail.
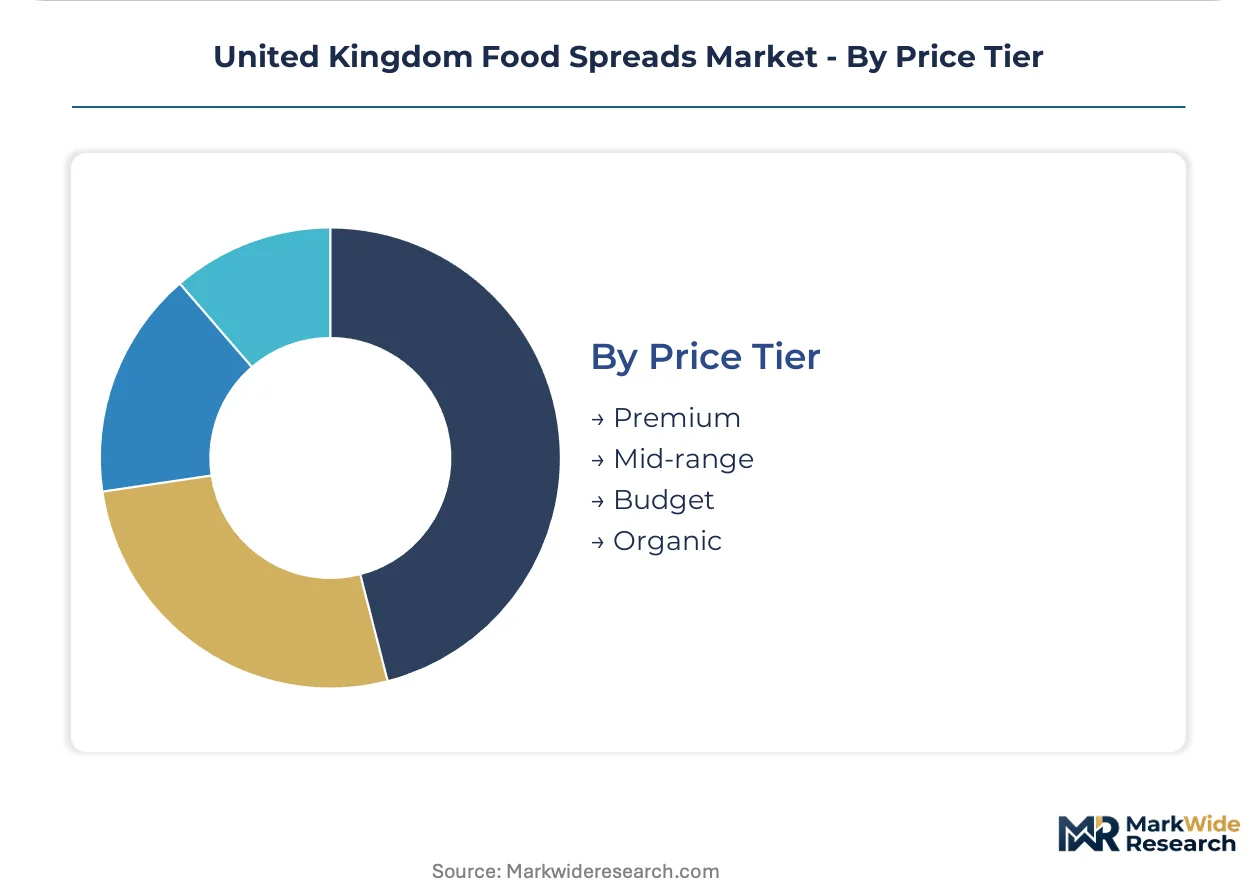
Mid-range spreads dominate absolute volume, with organic tiers showing the steepest expansion trajectory through certification-driven premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal within the United Kingdom given uniform DEFRA and Food Standards Agency oversight, yet sub-regional demand density and supply chain clustering create distinct operational environments across England's metropolitan corridors and the devolved nations.
London and the Southeast
Plant-based spread adoption concentrates in Greater London's foodservice networks, with contract caterers and independent cafes driving nut butter procurement volumes. The Mayor of London's environmental procurement guidelines favor sustainably sourced palm oil alternatives in public sector food contracts. High-pressure processing facilities cluster in Slough and Reading to serve premium organic brands targeting commuter belt households.
Midlands
Industrial baking and private-label manufacturing anchor demand for standard-tier margarine and blended spreads in Birmingham and Leicester catchments. DEFRA's sugar reduction targets apply uniformly but Midlands-based co-manufacturers face compressed reformulation timelines serving multiple supermarket clients simultaneously. Premier Foods plc maintains operational presence in this corridor.
North England
Manchester's foodservice expansion and Liverpool's port logistics create dual demand nodes for imported nut feedstocks and domestically produced fruit spreads. The Northern Powerhouse initiative has directed modest food manufacturing investment toward Hull and Grimsby, though spread-specific capacity remains limited. Discounter channel penetration runs deepest in Yorkshire retail networks.
Scotland
Scottish retail networks exhibit lower private-label spread penetration than England, creating whitespace for branded portfolio expansion. Food Standards Scotland aligns with UK-wide compositional standards but operates distinct enforcement protocols for artisanal producers in Highland and Island regions. Edinburgh's specialty food retail corridor favors premium provenance-positioned butters.
Wales
Welsh dairy processing capacity in Carmarthenshire and Pembrokeshire supplies butter inputs for UK-wide distribution, though value-added spread manufacturing remains underdeveloped. The Welsh Government's food and drink strategy emphasizes provenance marketing that butter producers can leverage. Cardiff and Newport retail networks lag England's metropolitan corridors in subscription-channel adoption.
United Kingdom Food Spreads Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label and direct-to-consumer positioning. The vendor base stratifies across multinational packaged goods conglomerates with diversified pantry portfolios, domestic private-label specialists with deep supermarket relationships, and regional artisanal operators leveraging high-pressure processing for extended distribution reach. Consolidation pressure operates selectively: multinational players defend shelf positioning through reformulation partnerships with flavor houses, while mid-cap specialists acquire regional organic brands to fill portfolio gaps.
Within the multinational tier, Unilever Plc and Nestlé S.A. exemplify scale-driven supply chain integration across oilseed and dairy input streams. Premier Foods plc and Stute Foods Ltd occupy positions bridging private-label manufacturing and branded health-positioned portfolios. These four entities collectively represent the competitive archetypes—multinational conglomerate, diversified food group, private-label anchor, and health-specialist independent—that structure procurement negotiations with Tesco, Sainsbury's, and Asda.
| Leading Market Players |
|---|
| Unilever Plc |
| Ferrero International SA |
| The Hain Celestial Group |
| The J.M. Smucker Company |
| Upfield Holdings B.V. |
| Premier Foods plc |
| Nestlé S.A. |
| The Kraft Heinz Company |
| Stute Foods Ltd |
| Others |
Value Network & Pricing Analysis
High-pressure processing adoption among artisanal manufacturers in Bristol and Brighton simultaneously compresses production cost curves and concentrates supply capability in regional processing clusters. This technology transition enables smaller producers to achieve shelf-stable outputs without synthetic preservatives, reshaping competitive economics across premium and mid-market tiers.
Pricing Analysis
Retailer markup layers dominate final shelf pricing, with Tesco, Sainsbury's, and Asda extracting substantial slotting fees that compress manufacturer margins. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and volume scale differentiation. Pricing pressure stems from DEFRA's sugar reduction mandates forcing accelerated reformulation cycles. Budget-tier margarine purchasers exhibit highest price sensitivity, while organic-certified nut butter buyers demonstrate lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian palm oil feedstocks and Kent-Herefordshire fruit concentrate processing capacity. British manufacturers draw from Indonesian and Malaysian palm oil origins alongside domestic dairy inputs and imported nut feedstocks. Tariff exposure on post-EU trade terms constitutes the primary structural risk. Distribution runs through supermarket-controlled logistics networks with emerging direct-to-consumer subscription channels bypassing traditional retail gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom food spreads market offers margin expansion through clean-label premiumization and subscription-channel capture, with reformulation cost absorption now largely complete among tier-one manufacturers.
For Market Incumbents: Extend high-pressure processing capacity to defend shelf-stable positioning against multinational brands. Deepen backward integration into oilseed sourcing to mitigate palm oil tariff volatility. Accelerate Soil Association certification pipelines to capture organic price premiums in Waitrose and Marks & Spencer networks. For New Entrants and Emerging Players: The gap between premium single-origin nut butters and economy-tier margarine offers white-space positioning for mid-priced clean-label spreads. Target Scottish retail networks where private-label penetration lags England. Pursue direct-to-consumer subscription models in Greater London to bypass supermarket slotting barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional artisanal operators with HPP-enabled distribution reach. Five-to-ten-year viability favors acquisition targets with established DEFRA compliance infrastructure and subscription-channel customer bases. Monitor Food Standards Agency novel ingredient guidance as the key inflection signal for additive-dependent formulation strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | Aligns product portfolios with DEFRA sugar reduction mandates and traffic-light labeling compliance. |
| High-Pressure Processing Capacity Expansion | Enables artisanal producers to achieve national retail distribution without synthetic preservative dependency. |
| Subscription Channel Infrastructure Buildout | Bypasses Tesco and Sainsbury's slotting fees while capturing lifetime value from Home Counties households. |
| Soil Association Certification Investment | Unlocks premium shelf positioning in Waitrose and Marks & Spencer organic tiers. |
| Scottish and Welsh Distribution Expansion | Captures first-mover advantage in retail corridors with lower incumbent private-label density. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged brand managers at Unilever Plc and Premier Foods plc, category buyers at Tesco and Sainsbury's, supply planners at Stute Foods Ltd, and channel sales heads at specialty retailers in Bristol and Edinburgh. Secondary validation drew from Food Standards Agency guidance documents, DEFRA agricultural policy frameworks, Nielsen retail audit data, and UK customs records on oilseed and nut imports. Bottom-up volume modeling triangulated against top-down market sizing across product type, distribution channel, and price tier dimensions.
Historical reference periods anchored the projection horizon through verified base-year consumption patterns and established growth trajectories. Segmentation modeling incorporated formulation technology, channel cost structure, and regional demand density as core dimensions. CAGRs derived from trend extrapolation adjusted for regulatory intervention impacts and technology adoption curves. Forecast inputs included foodservice menu diversification rates, subscription-channel penetration velocity, and front-of-pack labeling compliance thresholds.
Caveats apply where DEFRA sugar reduction timeline acceleration or post-EU trade agreement renegotiation could materially shift the outlook. Forecasts reflect assumptions on consumer acceptance of reformulated sensory profiles and supply chain cost pass-through capability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Instant Soup Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Eco Bowls Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Freekeh Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Iran Breakfast Cereals Market